
 Automotive Driveshaft Couplings Market | 2026-2036
Automotive Driveshaft Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Driveshaft Couplings Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from pure component manufacturing toward lifecycle support contracts. GKN Automotive leverages its integrated driveline platform to capture recurring maintenance streams across European commercial vehicle fleets. Dana Incorporated anchors North American heavy-duty demand through direct OEM supply relationships and authorized service network density. SKF Group differentiates via bearing-coupling integration that reduces total installed cost for vehicle assemblers.
Automotive driveshaft couplings are torque-transmitting mechanical interfaces that connect rotating shafts while accommodating angular misalignment, axial displacement, and vibration isolation; typical units employ forged steel yokes with needle-bearing cross journals rated for torque capacities exceeding 15,000 Nm in heavy-duty configurations. Their primary purpose is maintaining powertrain efficiency and driveline durability across variable load conditions and suspension travel ranges. Universal joint designs dominate OEM installations for passenger and light commercial vehicles due to proven cost-performance ratios and established repair infrastructure. Composite material adoption is expanding fastest in off-road and heavy-duty segments where mass reduction directly improves payload capacity and fuel compliance. Steel retains aftermarket preference among independent repair providers prioritizing part interchangeability and minimal tooling investment.
NHTSA Federal Motor Vehicle Safety Standards govern driveshaft integrity and failure-mode containment for US-sold vehicles, while EU REACH restrictions on hexavalent chromium plating force coating substitutions affecting corrosion-resistant coupling finishes. EPA greenhouse gas Phase 2 rules for medium- and heavy-duty engines cascade into driveline efficiency specifications that OEMs delegate to Tier-1 suppliers. Stakeholders must monitor how emerging battery-electric truck architectures eliminate traditional multi-piece driveshafts, redirecting coupling demand toward e-axle integration modules and specialized high-speed balancing applications.
Market Dynamics
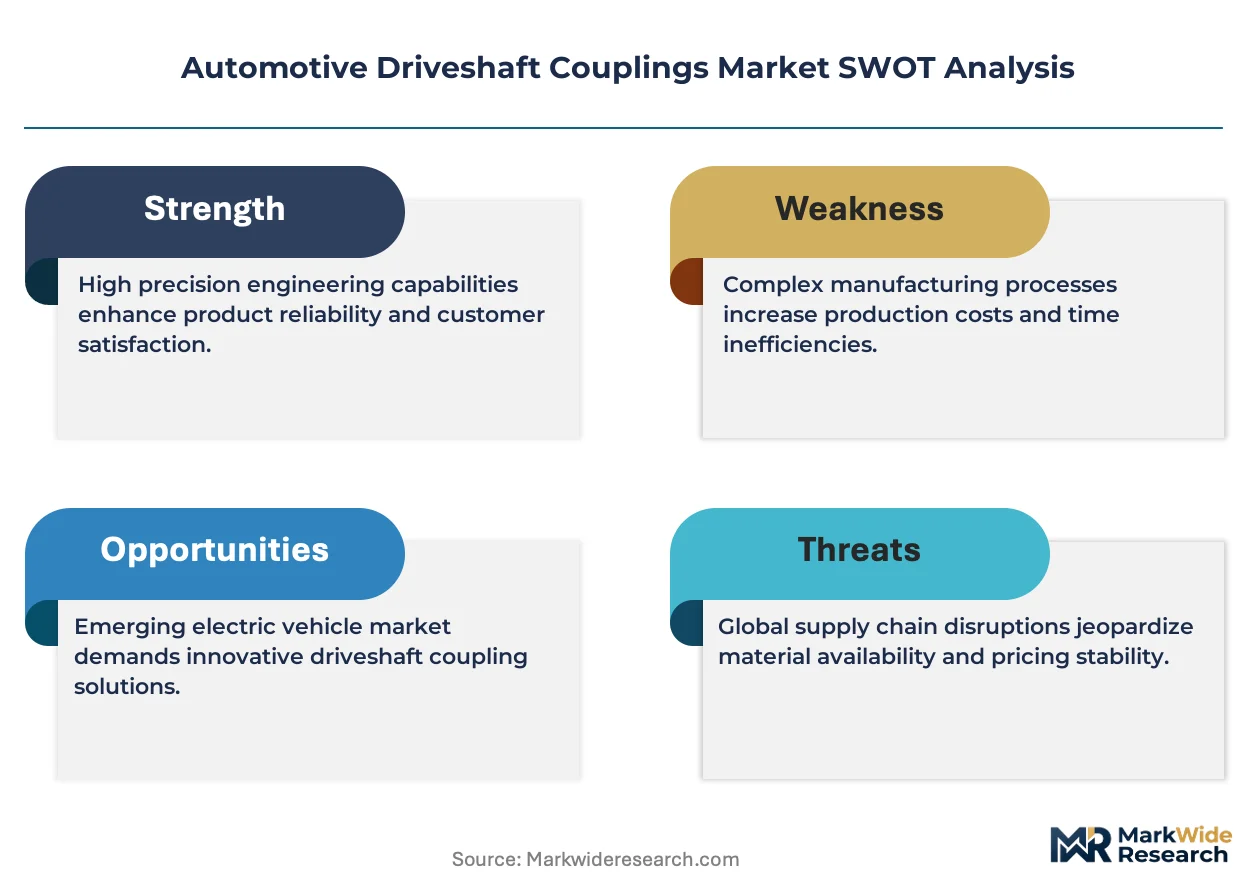
Commercial vehicle electrification is fragmenting traditional driveshaft architectures, forcing coupling suppliers to retool for e-axle integration modules and high-speed balancing applications while maintaining legacy internal combustion revenue streams.
Growth Catalysts
- EPA Phase 2 greenhouse gas rules:Medium- and heavy-duty engine efficiency mandates cascade into driveline specifications that OEMs delegate to Tier-1 suppliers, expanding specification-grade coupling procurement.
- Aluminum and composite material substitution:Fleet operators seeking payload optimization are accelerating lightweight assembly adoption in heavy-duty configurations where mass reduction directly improves fuel compliance.
- German commercial vehicle engineering concentration:Dense OEM headquarters and supplier R&D centers in Stuttgart, Munich, and Wolfsburg concentrate demand for advanced coupling validation and prototype testing.
Market Restraints
- Steel price volatility:Forged alloy input costs fluctuate with scrap metal and energy indices, compressing margin on conventional universal joint production.
- EU REACH hexavalent chromium restrictions:Coating substitution requirements for corrosion-resistant finishes force process requalification and capital retooling.
- Battery-electric truck substitution:Elimination of multi-piece driveshafts in e-axle architectures threatens volume in long-haul segments.
Strategic Opportunities
- Indian commercial vehicle production expansion:Domestic OEM capacity growth under PLI scheme incentives creates untapped demand for localized coupling supply.
- Bearing-coupling integration convergence:SKF and competitors are bundling rotating component assemblies to reduce total installed cost for vehicle assemblers.
- Lifecycle service contract migration:Fleet telematics enable predictive maintenance models that convert component sales into recurring revenue streams.
Industry Challenges
- High-speed balancing technician scarcity:E-axle integration modules require precision balancing capabilities that outstrip current vocational training pipelines.
- Dual certification timeline compression:Simultaneous NHTSA FMVSS and EU type-approval processes delay platform launches for multinational OEM programs.
- Legacy driveline inventory stranding:ICE coupling stockpiles face obsolescence risk as OEMs accelerate electric platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Driveshaft Couplings Market |
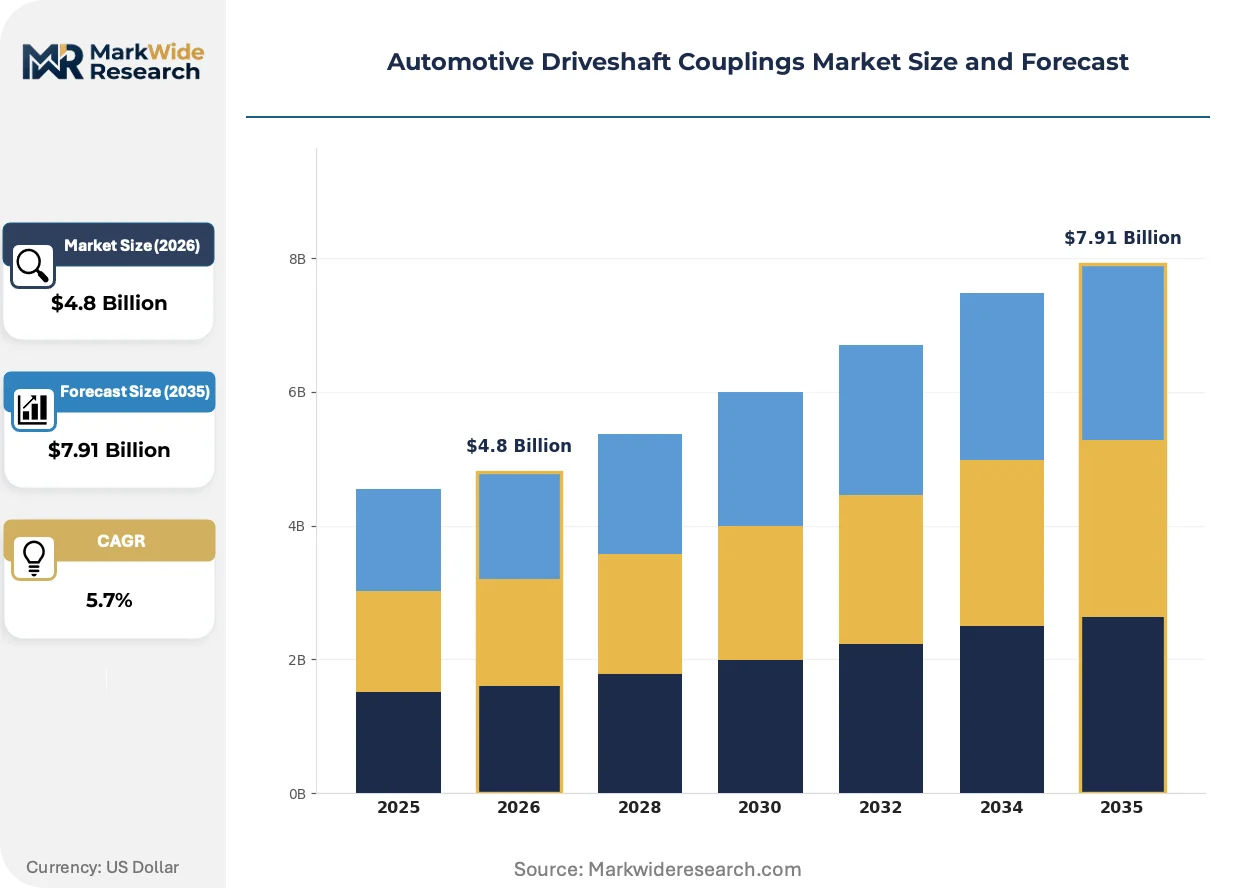
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Joint, Slip Joint, Rigid Coupling, Hooke Joint Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Off-Road Vehicles Material: Steel, Aluminum, Composite, Rubber End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Neapco Holdings LLC, SKF Group, GKN Automotive, American Axle & Manufacturing, ZF Friedrichshafen AG, Dana Incorporated, JTEKT Corporation, Meritor, Inc., NTN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Driveshaft Couplings Market Strategic Shifts
Material science advances and regulatory efficiency mandates are compressing traditional steel-forging dominance while digitization of fleet operations rewires aftermarket revenue models toward predictive service architectures.
Carbon-fiber reinforced polymer (CFRP) composite couplings are migrating from aerospace-derived prototypes to off-road and heavy-duty commercial applications. Mining and construction fleet operators in North America and Australia are piloting CFRP driveshaft assemblies to extend maintenance intervals in high-torque, high-vibration environments. The technology is migrating from niche performance segments toward mainstream heavy-duty procurement specifications as payload-driven fuel economy penalties intensify.
EU REACH restrictions on hexavalent chromium plating entered full enforcement for automotive components, eliminating traditional corrosion protection processes. Coating suppliers have accelerated trivalent chromium and zinc-nickel alloy alternatives through German KBA homologation channels. Heavy-duty coupling manufacturers serving export markets must maintain dual-process capabilities to satisfy divergent US and EU surface treatment standards.
Fleet operators are consolidating maintenance spend under integrated driveline service agreements that unbundle component procurement from installation labor. European commercial vehicle lessors now specify lifecycle cost guarantees rather than unit price in coupling tenders. This behavioral shift concentrates purchasing authority with procurement teams at headquarters locations in Germany, France, and the Netherlands, marginalizing independent repair channel influence.
Automotive Driveshaft Couplings Market Segmentation
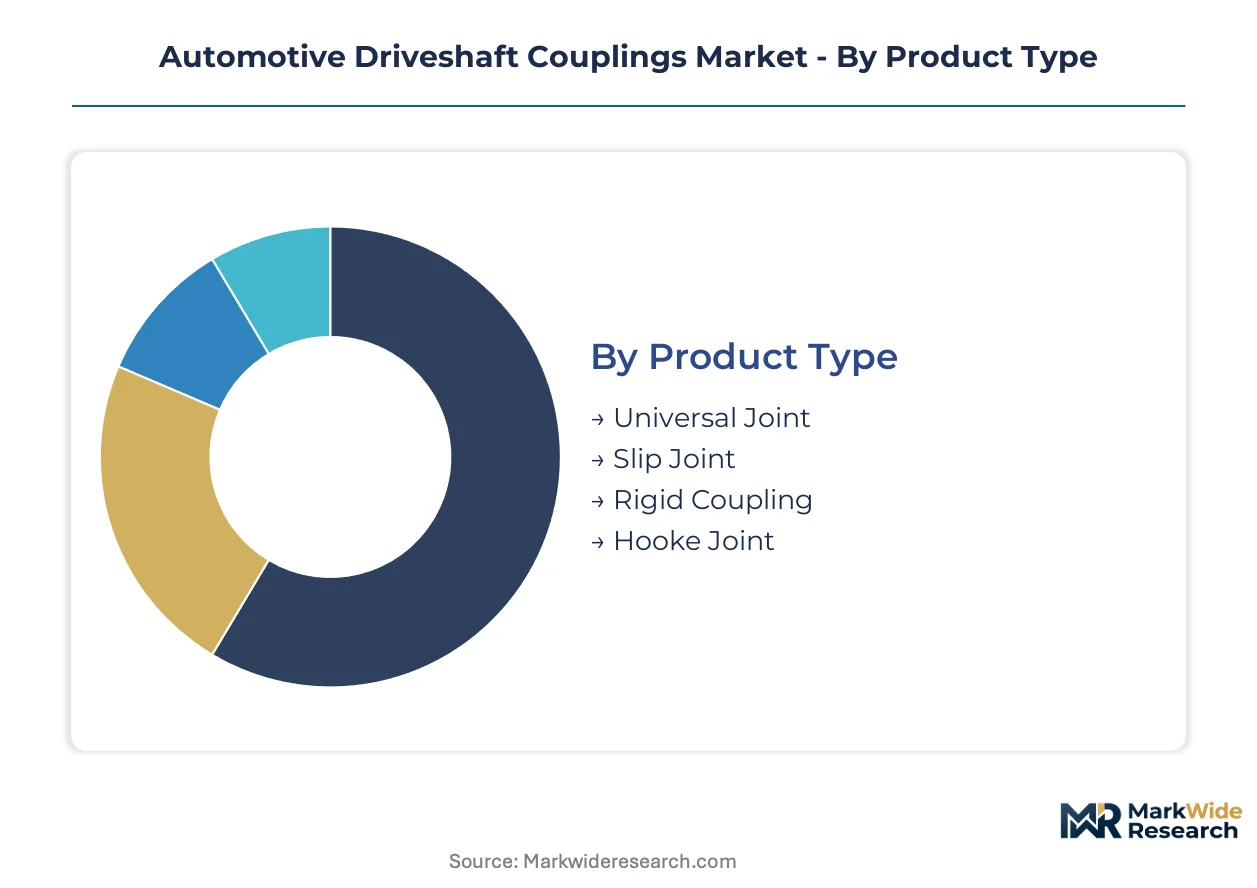
Segmentation in automotive driveshaft couplings reveals how torque transmission requirements diverge across vehicle architectures and duty cycles. Material selection and supply channel configuration directly determine margin capture and technical validation burden for component manufacturers.
Product Type:
Mature designs dominate installed base volume while emerging configurations capture specification-grade procurement in electrifying platforms.
- Universal Joint:Cross-journal assemblies with needle bearings accommodate angular misalignment up to 25 degrees in multi-piece driveshaft configurations. Passenger and light commercial vehicle OEMs in Germany specify these units for proven durability and established service infrastructure.
- Slip Joint:Telescoping splined sleeves permit axial displacement during suspension travel and powertrain movement. Heavy-duty fleet operators in North America prioritize slip joint integration for maintenance interval extension in long-haul applications.
- Rigid Coupling:Fixed flange connections transmit torque without accommodating misalignment, suited for precision-aligned e-axle modules.
- Hooke Joint:Historical double-cardan geometry persists in specialized off-road and industrial driveline conversions.
Universal joint handles the majority of throughput; slip joint is the fastest mover on share.
Application:
Cost tier stratification separates specification-grade heavy-duty procurement from price-sensitive passenger vehicle supply.
- Commercial Vehicles:Medium-duty trucks and delivery vans require couplings rated for 8,000-15,000 Nm with balanced weight targets. German fleet operators concentrate demand through centralized procurement functions in Stuttgart and Munich corridors.
- Heavy-Duty Vehicles:Class 8 tractors and vocational trucks specify forged steel or hybrid aluminum-steel assemblies for torque capacities exceeding 15,000 Nm. EPA Phase 2 fuel economy penalties in the US accelerate lightweight material substitution in this segment.
- Passenger Vehicles:Compact cross-journal units prioritize NVH suppression and packaging efficiency.
- Off-Road Vehicles:Mining and construction equipment demands sealed bearing configurations for contamination resistance.
Commercial vehicles anchor procurement volume; heavy-duty vehicles are expanding most quickly on specification-grade demand.
Material:
Supply concentration in primary metal processing shapes regional manufacturing footprint and certification pathway requirements.
- Steel:Forged alloy compositions dominate aftermarket replacement demand due to part interchangeability and minimal tooling requirements for independent repair networks. Scrap metal price volatility compresses margin on conventional production.
- Composite:Carbon-fiber reinforced polymer assemblies reduce mass 40-60% versus steel equivalents in heavy-duty configurations. Australian and North American mining fleets pilot CFRP driveshafts for payload optimization and fuel compliance.
- Aluminum:Cast and extruded housings balance weight reduction with cost containment in medium-duty specifications.
- Rubber:Elastomeric elements provide vibration isolation in auxiliary driveline connections.
Steel maintains installed base dominance; composite is climbing the fastest on fleet fuel economy mandates.
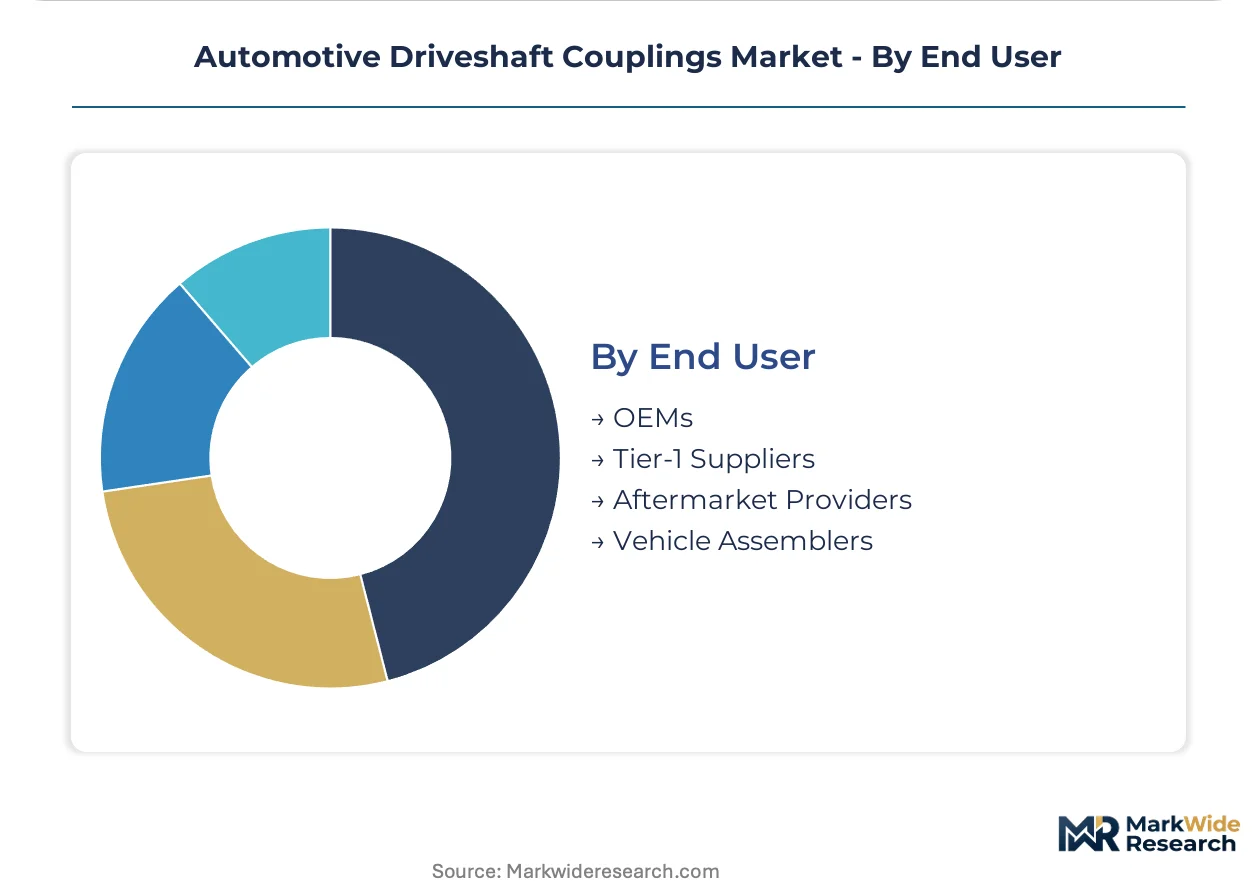
End User:
Customer type determines contract structure, with lifecycle service agreements displacing unit sales in consolidated fleet channels.
- OEMs:Vehicle manufacturers delegate driveline specification to Tier-1 suppliers while retaining platform integration authority. Direct OEM relationships require simultaneous NHTSA FMVSS and EU type-approval certification.
- Aftermarket Providers:Independent distributors and repair chains prioritize inventory breadth and cross-reference compatibility. Steel universal joint demand concentrates here due to minimal capital requirements for service bay installation.
- Tier-1 Suppliers:Integrated driveline specialists bundle coupling, bearing, and shaft assemblies for vehicle assemblers.
- Vehicle Assemblers:Contract manufacturers and specialty builders procure validated subassemblies for low-volume production.
OEMs control specification-grade volume; aftermarket providers are gaining share fastest on fleet age extension and repair interval compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement elasticity varies sharply across geographies. German buyers prioritize specification-grade validation and lifecycle cost guarantees. Indian operators remain acutely price-sensitive, prioritizing interchangeability and minimal tooling investment in aftermarket channels.
United States
Class 8 tractor demand and EPA Phase 2 fuel economy penalties drive specification-grade procurement for torque capacities exceeding 15,000 Nm. NHTSA Federal Motor Vehicle Safety Standards govern driveshaft integrity and failure-mode containment for domestic-sold vehicles. Detroit-Warren corridor anchors heavy-duty OEM headquarters and Tier-1 supplier engineering centers, concentrating validation and prototype testing demand.
Germany
Commercial vehicle electrification and lightweight material substitution accelerate aluminum and composite coupling adoption in heavy-duty configurations. EU REACH restrictions on hexavalent chromium plating force coating substitutions affecting corrosion-resistant finishes. Stuttgart, Munich, and Wolfsburg concentrate OEM headquarters and supplier R&D centers, centralizing advanced coupling validation and fleet procurement authority.
China
Domestic commercial vehicle production expansion and dual carbon goals accelerate material substitution toward lightweight designs. MIIT efficiency mandates for medium- and heavy-duty vehicles cascade into driveline specifications delegated to Tier-1 suppliers. Yangtze River Delta manufacturing clusters concentrate forging capacity and surface treatment capabilities for export-oriented coupling production.
India
Domestic OEM capacity growth under PLI scheme incentives creates localized coupling supply demand for medium-duty truck production. BIS certification requirements and DGFT import substitution policies favor domestic fabrication over imported assemblies. Maharashtra and Gujarat industrial corridors concentrate forging and machining capacity serving commercial vehicle assemblers.
Japan
Precision manufacturing heritage and JIS standards compliance anchor specification-grade demand for high-speed balancing applications. METI industrial policy supports bearing-coupling integration convergence in advanced driveline assemblies. Kansai and Chubu manufacturing belts concentrate Tier-1 supplier engineering centers and prototype testing facilities.
Automotive Driveshaft Couplings Market Competitive Environment
Capability concentration sits with integrated driveline specialists; scale advantage sits with forged component fabricators serving aftermarket channels. The market structures around three tiers: bearing-coupling integrators capturing OEM specification-grade procurement; universal joint manufacturers anchoring aftermarket replacement demand; and aluminum-composite hybrid specialists penetrating heavy-duty lightweight segments. Dominant competitive moves include backward integration into forging and heat-treatment capabilities, and strategic partnerships with fleet telematics providers to capture lifecycle service contracts.
Among European-integrated driveline specialists, GKN Automotive and SKF Group exemplify the bearing-coupling convergence archetype, occupying positions that reduce total installed cost for vehicle assemblers through bundled rotating component assemblies. Dana Incorporated represents the North American heavy-duty direct-OEM supply model, anchoring authorized service network density to capture recurring maintenance streams. These three entities sit within distinct competitive vectors—European integration, bearing specialization, and North American fleet density—each representing a viable path to margin capture as electrification fragments traditional architectures.
| Leading Market Players |
|---|
| Neapco Holdings LLC |
| SKF Group |
| GKN Automotive |
| American Axle & Manufacturing |
| ZF Friedrichshafen AG |
| Dana Incorporated |
| JTEKT Corporation |
| Meritor, Inc. |
| NTN Corporation |
| Others |
Value Chain & Pricing Dynamics
Forged alloy supply concentration in China's Yangtze River Delta and Germany's Ruhr Valley feeds directly into margin capture at Tier-1 integrators, while aftermarket steel distributors compete on inventory velocity rather than specification premiums. Fleet operators consolidating procurement authority in Stuttgart and Detroit corridors are compressing unit economics for standalone component fabricators.
Pricing Analysis
Lifecycle service contracts now drive lifetime value, with European commercial vehicle lessors specifying total cost of ownership guarantees rather than per-unit pricing in coupling tenders. Three-tier pricing structure across premium specification-grade, standard OEM-fit, and economy aftermarket levels separates validation-burdened aluminum-composite hybrids from interchangeable steel universal joints. Cost compression in conventional forged steel production is intensifying because scrap metal volatility erodes margin on legacy universal joint output. Aftermarket repair channels exhibit highest price sensitivity, prioritizing cross-reference compatibility and minimal tooling investment over performance tier.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for surface treatment and forging equipment inputs. Manufacturing gravity centers on Germany, China, and the United States for precision forging and heat-treatment capabilities, with Mexico emerging as a nearshoring alternative for North American OEM supply. The supply chain draws from forged alloy steel billets, needle bearing assemblies, and trivalent chromium coating chemistries as critical inputs. Single-source vulnerability concentrates in German KBA homologation channels for EU-compliant surface finishes. Distribution runs through authorized service networks for fleet lifecycle contracts and independent distributors for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle electrification constitutes a high-growth disruption, with EPA Phase 2 and EU CO2 mandates accelerating material substitution toward lightweight coupling architectures that invalidate legacy steel-forging competencies.
For Market Incumbents: Pre-empt obsolescence in multi-piece driveshaft coupling demand by accelerating backward integration into e-axle integration module capabilities and high-speed balancing technician training pipelines. Capture stranded ICE coupling inventory risk through accelerated liquidation protocols while redirecting R&D spend toward bearing-coupling convergence architectures that reduce total installed cost for electrifying OEM platforms.
For New Entrants and Emerging Players: Build out localized forging and machining capacity in India's Maharashtra and Gujarat industrial corridors to serve PLI scheme incentivized domestic OEM production. Target medium-duty commercial vehicle specifications where validation burden remains lower than heavy-duty Class 8 requirements. Pursue direct supply relationships with emerging battery-electric truck assemblers seeking e-axle module partners outside incumbent Tier-1 networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed forged component specialists carrying stranded ICE coupling inventory and limited e-axle integration capabilities. Long-term viability over a multi-year horizon hinges on successful technology transition toward composite material processing and precision balancing services. Monitor fleet telematics adoption rates as the inflection signal for lifecycle service contract penetration and recurring revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Integration Module Development | Captures specification-grade procurement from electrifying OEM platforms in Germany and North America. |
| Composite Material Processing Scale-Up | Enables CFRP driveshaft supply to Australian and North American mining fleets under payload optimization mandates. |
| High-Speed Balancing Technician Training | Addresses vocational pipeline scarcity constraining e-axle module service capacity expansion. |
| Lifecycle Service Contract Migration | Converts transactional component sales into recurring revenue through fleet telematics integration. |
| Regional Manufacturing Footprint Expansion | Localizes supply for Indian PLI scheme incentivized commercial vehicle production in Maharashtra corridor. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed Tier-1 suppliers, and EPA regulatory dockets. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and fleet maintenance directors across Germany, the United States, China, and India. Bottom-up coupling demand modeling triangulated against top-down vehicle production forecasts and content-per-vehicle assumptions.
Forecast inputs incorporate vehicle class segmentation, propulsion architecture evolution from internal combustion to battery-electric and hybrid configurations, content per vehicle by torque rating tier, OEM tier stratification, and regional production cluster dynamics across the projection horizon. CAGRs derive from regression analysis of historical coupling procurement against vehicle production volumes, adjusted for material substitution elasticities and regulatory compliance cost pass-through assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric truck specialists or composite material startups would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Cylinder Block Market
Powertrain
Brazil Automotive Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Global Industrial Engine Market
Powertrain
EV Powertrain Market
Powertrain
Automotive Powertrain Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Global Automotive Tappet Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Clutch Friction Plate Market
Powertrain
Spark Plugs Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Powertrain Domain Control Unit Platforms Market