
 Drive Shaft Market | 2026-2036
Drive Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Drive Shaft Market Analysis
Aftermarket predictive maintenance services is expanding as a revenue layer beyond hardware sales, with fleet operators subscribing to vibration-monitoring platforms that extend component life. GKN Automotive leverages its hollow-shaft manufacturing depth to anchor European OEM supply chains for electric drivelines. Dana competes through vertical integration into forging and heat-treatment operations that control alloy-grade consistency. Hyundai WIA dominates Asian commercial-vehicle shaft supply through dedicated production campuses in South Korea.
A drive shaft is a rotating tubular component that transmits torque from an engine or motor to the wheels or driven axles, typically manufactured from alloy steel, aluminum, or carbon-fiber-reinforced polymer with critical tolerances for dynamic balance below 5 g-mm at operational speeds. Its primary purpose is to maintain power delivery efficiency while accommodating suspension travel and driveline angle variations in vehicles and industrial equipment. Single-piece carbon-fiber shafts command the highest margins in performance automotive applications where rotational inertia reduction justifies premium pricing. Multi-piece assemblies retain volume leadership in heavy commercial vehicles where modular repairability reduces total cost of ownership across extended duty cycles.
NHTSA crashworthiness standards and EPA Corporate Average Fuel Economy regulations in the United States compel manufacturers to validate shaft assemblies under combined torsional and bending load spectra, directly influencing material selection and joint-design protocols. The EU Green Deal and REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers to migrate toward trivalent chrome and zinc-nickel coating systems for corrosion protection. Stakeholders must monitor how battery-electric platform architectures eliminate traditional multi-piece drivelines in favor of integrated motor-gearbox units that compress addressable shaft volumes in passenger segments.
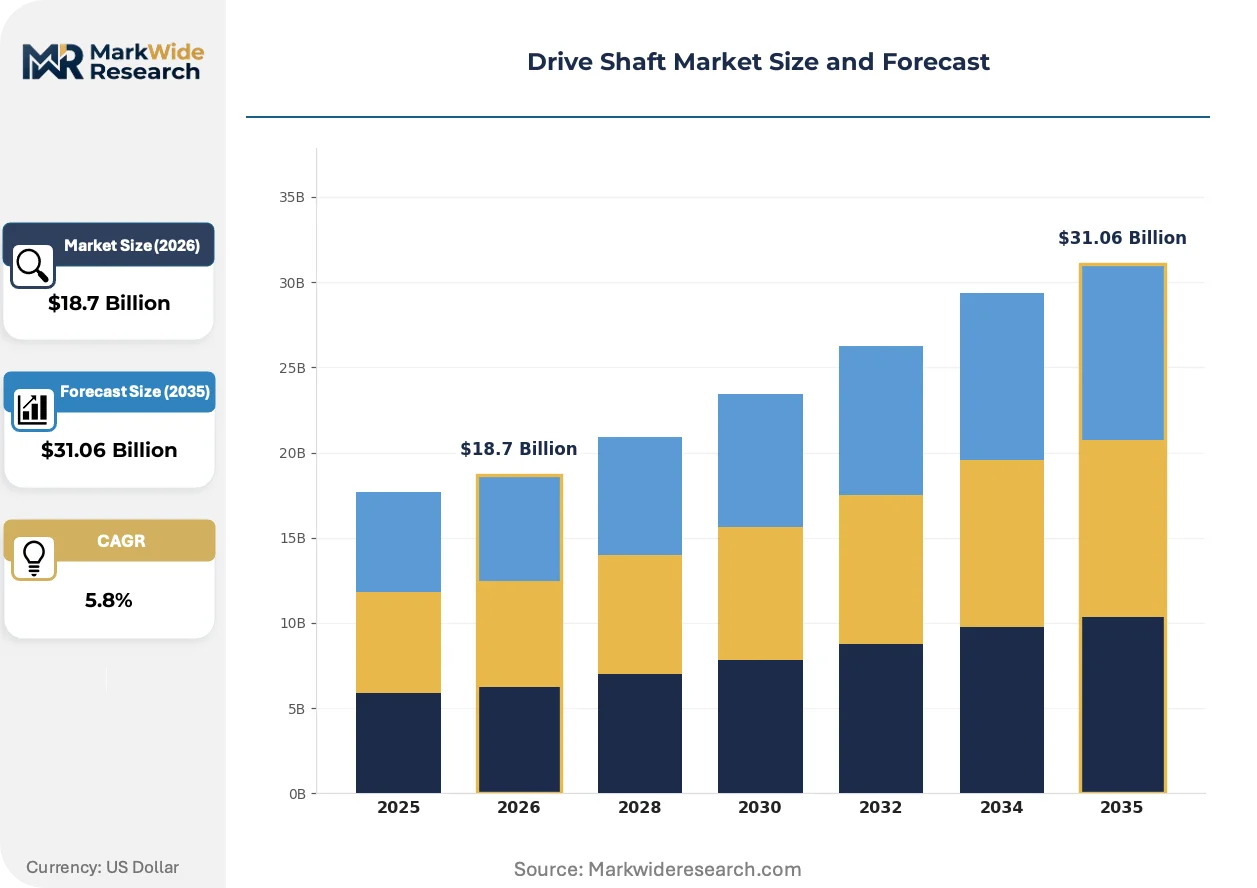
Market Dynamics
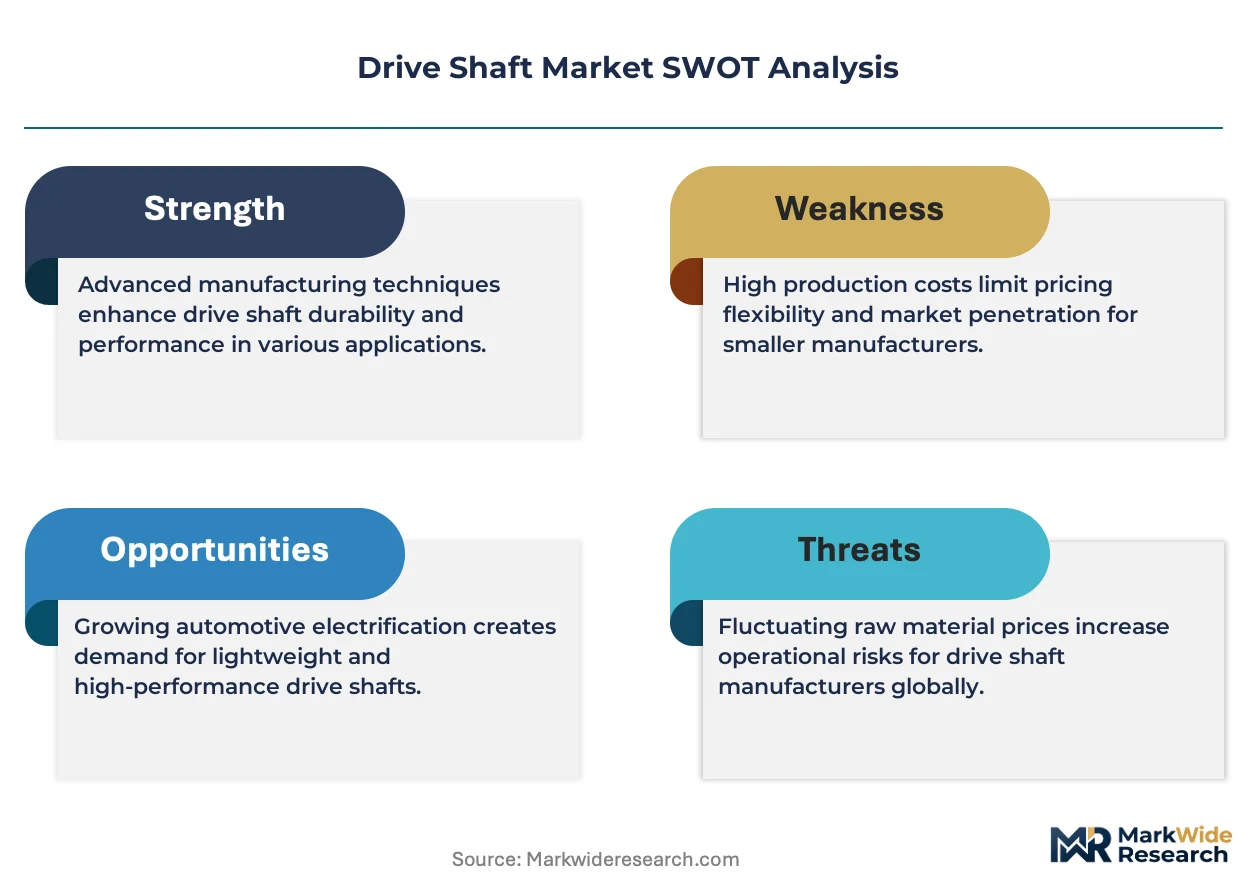
Electric vehicle platform architectures are eliminating traditional multi-piece drivelines in favor of integrated motor-gearbox units, compressing addressable shaft volumes in passenger segments while redirecting supplier investment toward lightweight hollow-shaft designs for remaining propulsion applications.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:NHTSA mandates in the United States compel OEMs to validate shaft assemblies under combined torsional and bending load spectra, accelerating material substitution toward carbon fiber composites.
- Commercial-vehicle fleet electrification:Heavy-duty truck operators in China are expanding procurement of lightweight propulsion shafts to offset battery mass penalties and extend electric range.
- Carbon fiber-reinforced polymer manufacturing:Advances in automated filament winding and resin transfer molding are reducing production cycle times for hollow-shaft geometries in performance automotive applications.
Market Restraints
- Alloy-grade steel price volatility:Input cost fluctuations for chromium-molybdenum billet stock constrain margin stability at forging-dependent suppliers serving commercial-vehicle OEMs.
- Supply concentration in East Asian forging capacity:Heavy reliance on South Korean and Japanese heat-treatment facilities creates vulnerability to regional logistics disruptions.
- Integrated e-axle substitution:Battery-electric platform architectures from European and Chinese OEMs are displacing discrete driveshaft assemblies with motor-gearbox units that eliminate intermediate shafts entirely.
Strategic Opportunities
- Aftermarket predictive maintenance platforms:Fleet operators in Germany are subscribing to vibration-monitoring services that extend component life and create recurring revenue beyond hardware sales.
- EU Green Deal REACH compliance:Trivalent chrome and zinc-nickel coating system mandates are creating upgrade cycles among European suppliers previously dependent on hexavalent chromium surface treatments.
- Autonomous mining vehicle deployment:Unmanned haul trucks in Australian iron ore operations are generating demand for sealed, maintenance-free shaft assemblies with extended service intervals.
Industry Challenges
- Dynamic balancing technician scarcity:Precision assembly operations require specialists capable of achieving sub-5 g-mm tolerances at operational speeds, with training pipelines failing to match OEM quality demands.
- Multi-material joint certification timelines:Validation protocols for carbon fiber-to-aluminum flange connections under combined fatigue loading extend new product introduction cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive Shaft Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Piece, Multi Piece, Rigid, Flexible Material: Steel, Aluminum, Composite, Carbon Fiber End User: Automotive, Commercial Vehicles, Industrial Machinery, Aerospace Installation Type: OEM, Aftermarket, Repair, Replacement |
| Companies Covered | JTEKT, NTN, GKN Automotive, IFA, Hyundai WIA, Dana, Nexteer Automotive, Neapco, American Axle & Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive Shaft Market Emerging Trajectories
Manufacturing processes and material systems are converging to reduce rotational inertia while maintaining crashworthiness, with regulatory pressure and procurement centralization accelerating adoption curves beyond historical replacement cycles.
Carbon fiber-reinforced polymer shaft construction is modularizing around automated preform assembly and out-of-autoclave curing, enabling tier-two suppliers to enter performance segments previously reserved for aerospace-qualified manufacturers. European sports car OEMs are qualifying these processes for series production at volumes exceeding 50,000 units annually. The technology is modularizing the supplier base by decoupling material preparation from final machining and balance operations.
REACH restrictions on hexavalent chromium surface treatments are forcing coating system migrations across European supply chains, with trivalent chrome and zinc-nickel alternatives requiring revised salt-spray validation protocols. German component suppliers are absorbing requalification costs to maintain OEM preferred supplier status. Commercial-vehicle segments face the steepest compliance burden due to extended corrosion warranty requirements.
Fleet procurement centralization is consolidating specification authority at headquarters level, displacing regional maintenance manager discretion with corporate engineering standards that favor approved supplier lists over price-based spot purchasing. North American Class 8 truck operators are mandating hollow-shaft designs across all new vehicle acquisitions regardless of upfront cost premium. This concentration is visible most acutely in long-haul freight corridors where total cost of ownership modeling dominates capital allocation decisions.
Drive Shaft Market Segmentation
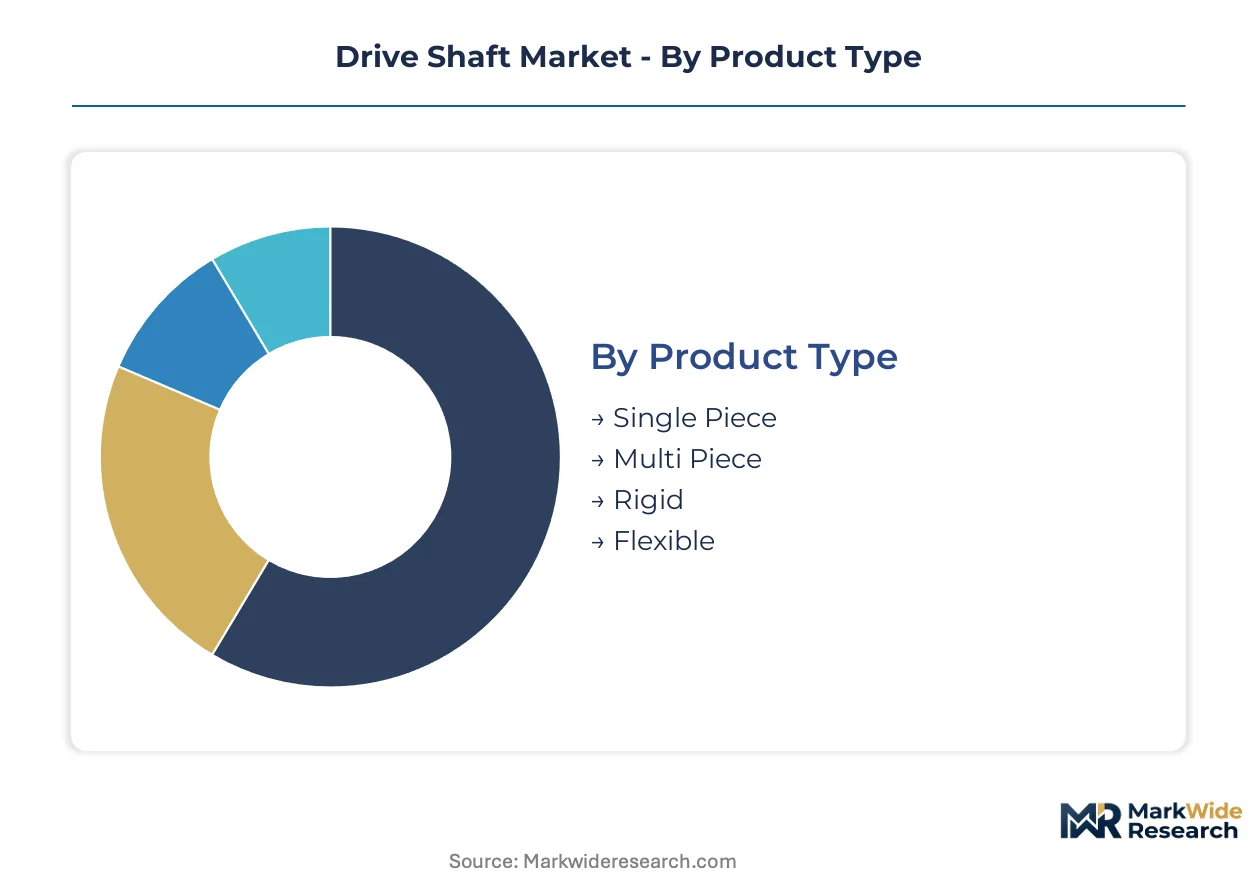
Drive shaft procurement patterns diverge sharply across vehicle architectures and duty cycles, with material substitution and electrification timelines creating distinct upgrade windows for each segment cluster. Fleet operators and OEM engineering teams prioritize different performance thresholds, fragmenting specification authority across passenger, commercial, and industrial applications.
Product Type:
Replacement cycles vary dramatically by shaft architecture, with modular designs extending service intervals in heavy-duty fleets while single-piece configurations dominate performance-oriented new vehicle programs.
- Single Piece:Manufactured as continuous tubular or solid assemblies without intermediate joints, these shafts minimize rotational mass and maintenance points. Carbon fiber single-piece shafts from European suppliers now qualify for series production volumes exceeding 50,000 units annually in sports car applications. Demand concentrates in German and Italian OEM performance divisions where rotational inertia reduction justifies premium procurement.
- Multi Piece:Modular assemblies with center bearings and slip joints accommodate longer wheelbases and suspension travel variations. Heavy-duty truck operators in China specify multi-piece architectures for repairability across extended duty cycles exceeding 1.5 million kilometers. Fleet procurement centralization in North American Class 8 corridors favors hollow-shaft multi-piece designs despite upfront cost premiums.
- Rigid:Fixed-geometry shafts without universal joints serve industrial power transmission and specialty vehicle applications with minimal driveline angle variation.
- Flexible:Constant velocity joint integration enables angular accommodation up to 54 degrees for independent suspension architectures and steering axle applications.
Multi Piece sits at the top of the volume ranking, with Single Piece climbing the fastest.
Material:
Cost tier stratification separates commodity steel from aerospace-qualified composites, with regulatory pressure compressing the timeline for mid-tier aluminum adoption.
- Steel:Chromium-molybdenum alloy grades dominate commercial-vehicle forging operations, with heat-treated billet stock supplying 80% of heavy-duty shaft tonnage. South Korean and Japanese heat-treatment facilities anchor global forging capacity, creating regional logistics vulnerability. NHTSA crashworthiness validation protocols govern steel shaft torsional and bending load spectra for US-market vehicles.
- Carbon Fiber:Automated filament winding and out-of-autoclave curing enable tier-two suppliers to enter performance segments previously reserved for aerospace-qualified manufacturers. European REACH restrictions on hexavalent chromium accelerate carbon fiber substitution where coating compliance costs erode steel economics. EU Green Deal procurement mandates favor lightweight materials in fleet electrification programs.
- Aluminum:Hollow extrusions with forged flange attachments serve mid-market passenger vehicles seeking 40-50% mass reduction versus steel without carbon fiber cost exposure.
- Composite:Glass-fiber-reinforced polymer shafts occupy niche industrial and agricultural equipment applications where corrosion resistance outweighs stiffness requirements.
Steel retains dominant volume share, though Carbon Fiber demonstrates the steepest expansion trajectory as automated manufacturing reduces production cycle times.
End User:
Application-specific duty cycles determine specification rigor, with aerospace and mining equipment imposing the most severe validation burdens.
- Automotive:Passenger vehicle electrification eliminates traditional multi-piece drivelines in favor of integrated motor-gearbox units, compressing addressable shaft volumes. Battery-electric platform architectures from Chinese and European OEMs displace discrete driveshaft assemblies entirely in front-wheel-drive configurations. Remaining demand concentrates on rear-wheel-drive performance variants and hybrid all-wheel-drive systems.
- Commercial Vehicles:Heavy-duty truck operators offset battery mass penalties through lightweight propulsion shaft procurement, extending electric range in China and European long-haul corridors. Fleet vibration-monitoring subscriptions from German service providers create recurring revenue layers beyond hardware replacement.
- Industrial Machinery:Mining and construction equipment shafts require sealed, maintenance-free assemblies with extended service intervals for autonomous vehicle deployment.
- Aerospace:Helicopter tail rotor and auxiliary power unit shafts demand sub-5 g-mm dynamic balance tolerances with fatigue life validation under combined loading spectra.
Commercial Vehicles command the largest installed base, while Automotive faces the most severe volume pressure from electrification.
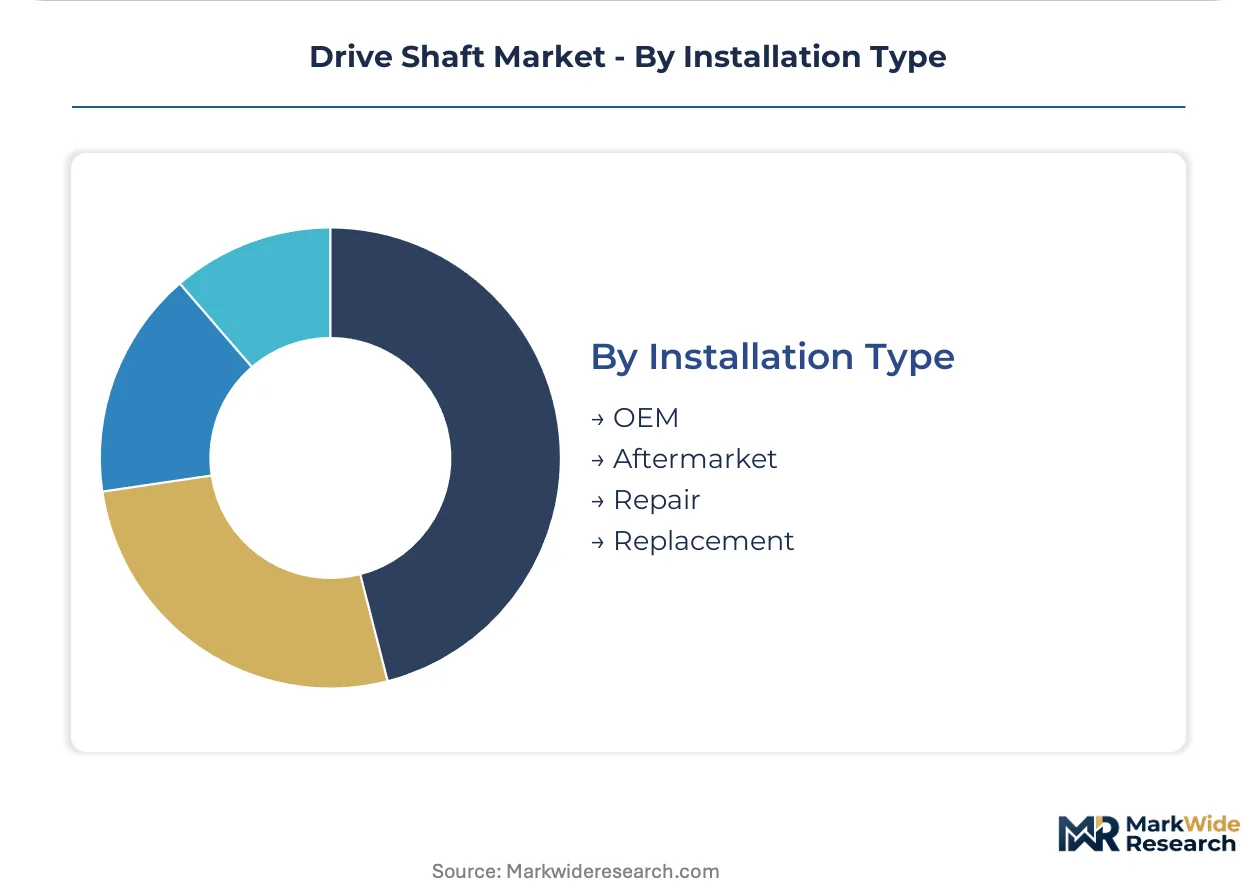
Installation Type:
Customer type fragmentation separates capital-intensive OEM programs from price-sensitive aftermarket procurement, with predictive maintenance platforms blurring traditional boundaries.
- OEM:Original equipment specifications consolidate at headquarters engineering level, displacing regional plant discretion with corporate-approved supplier lists. North American Class 8 truck operators mandate hollow-shaft designs across all new vehicle acquisitions regardless of upfront cost premium. NHTSA and EPA regulations directly influence material selection and joint-design protocols for US-bound production.
- Aftermarket:Predictive maintenance services expand as a revenue layer beyond hardware sales, with fleet operators subscribing to vibration-monitoring platforms that extend component life. German commercial-vehicle fleets lead adoption of condition-based replacement scheduling versus calendar-based maintenance.
- Repair:Modular multi-piece architectures dominate repair scenarios where field serviceability reduces downtime costs in remote mining and agricultural operations.
- Replacement:Salt-spray validation protocols for trivalent chrome and zinc-nickel coating systems drive upgrade cycles among European suppliers previously dependent on hexavalent chromium surface treatments.
OEM captures the highest value per unit, with Aftermarket gaining share fastest through recurring service revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates more OEM procurement activity than Germany and Japan combined, while the United States enforces the strictest fuel economy validation protocols. Each geography shapes supplier strategy through distinct regulatory and industrial configurations.
China
Heavy-duty truck electrification drives lightweight propulsion shaft procurement from fleet operators seeking range extension. MIIT dual carbon goals accelerate material substitution mandates for commercial-vehicle drivelines. Yangtze River Delta forging clusters around Shanghai supply hollow-shaft geometries to domestic EV platforms.
Germany
EU Green Deal procurement mandates favor carbon fiber adoption in fleet electrification programs across long-haul corridors. REACH restrictions on hexavalent chromium force coating system migrations toward trivalent chrome alternatives. Bavarian automotive suppliers absorb requalification costs to maintain preferred OEM status.
United States
North American Class 8 operators mandate hollow-shaft designs through centralized fleet procurement regardless of upfront premiums. NHTSA crashworthiness standards and EPA Corporate Average Fuel Economy regulations govern torsional and bending load validation protocols. Detroit-area engineering headquarters consolidate specification authority over regional plant discretion.
Japan
Heat-treatment facilities in Nagoya and Osaka anchor global forging capacity for chromium-molybdenum alloy grades. METI industrial standards govern precision assembly operations requiring sub-5 g-mm dynamic balance tolerances. Kyushu-based suppliers serve Asian commercial-vehicle shaft demand through dedicated production campuses.
South Korea
Battery-electric platform architectures from domestic OEMs displace discrete driveshaft assemblies in front-wheel-drive configurations. Korean forging-dependent suppliers face margin pressure from alloy-grade steel price volatility. Busan-Ulsan industrial corridors concentrate heat-treatment capacity serving regional logistics networks.
Drive Shaft Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hollow-shaft fabricators commanding premium positioning in performance automotive while forging-dependent suppliers serve commercial-vehicle volume. The supplier base organizes around three archetypes: integrated drivetrine system houses, precision forging specialists, and composite material entrants. Strategic moves concentrate on capacity consolidation in East Asian heat-treatment corridors and coating system compliance upgrades for European REACH mandates.
Within the integrated system tier, GKN Automotive and Dana exemplify divergent approaches to supply chain control, with the former leveraging European OEM relationships and the latter emphasizing in-house production of alloy-grade consistency. Hyundai WIA anchors Asian commercial-vehicle supply through scale-driven fabrication. These three occupy positions spanning the premium hollow-shaft segment through commodity forging operations.
| Leading Market Players |
|---|
| JTEKT |
| NTN |
| GKN Automotive |
| IFA |
| Hyundai WIA |
| Dana |
| Nexteer Automotive |
| Neapco |
| American Axle & Manufacturing |
| Others |
Supply Flow & Price Mechanics
Precision dynamic balancing technicians in Nagoya and Osaka command wage premiums that compress margin spreads between forged steel commodity shafts and hollow aluminum mid-tier alternatives. Labor-cost differentials between Japanese heat-treatment corridors and Yangtze River Delta forging clusters translate into pricing-tier spreads exceeding material cost deltas alone.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for chromium-molybdenum alloy shafts as Busan-Ulsan industrial corridors expand heat-treatment throughput. Three-tier pricing structure across carbon fiber premium, aluminum mid-market, and steel economy levels stratifies by rotational inertia performance and NHTSA validation tier. Cost compression in steel forging intensifies because alloy-grade billet stock volatility erodes contract-margin stability at volume-dependent suppliers. Fleet procurement centralization renders North American Class 8 operators least price-sensitive while spot-buying aftermarket distributors exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated fleet engineering headquarters, displacing regional distributor networks. Manufacturing gravity draws from South Korea, Japan, and China for heat-treatment capacity; Germany and the United States for precision machining; and Italy for carbon fiber preform assembly. Raw material feeds from chromium-molybdenum billet stock, carbon fiber tow, and aluminum extrusion ingot. Single-source vulnerability concentrates in East Asian forging corridors where regional logistics disruptions propagate through global commercial-vehicle supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through EPA Corporate Average Fuel Economy mandates that harden demand for lightweight shaft architectures across electrified platforms.
For Market Incumbents: Acquire hollow-shaft manufacturing depth to anchor OEM supply chains against integrated e-axle substitution. Secure captive heat-treatment capacity in South Korean or Japanese corridors to defend input cost stability against alloy-grade steel volatility. Cement preferred supplier status through REACH-compliant coating system investments that absorb competitor requalification burdens. For New Entrants and Emerging Players: Autonomous mining vehicle operators in Australian iron ore corridors represent underserved buyers seeking sealed, maintenance-free shaft assemblies with extended service intervals. Target aftermarket predictive maintenance platforms for German commercial-vehicle fleets where vibration-monitoring subscriptions outpace hardware replacement revenue. Enter through out-of-autoclave carbon fiber process licensing that decouples material preparation from balance operations. For Investors and Strategic Acquirers: Valuations sit cheapest among forging-dependent mid-caps facing margin pressure from alloy-grade steel volatility and integrated e-axle displacement. Long-term viability hinges on hollow-shaft fabrication capability and OEM preferred supplier status retention. Watch carbon fiber automated filament winding cost curves as inflection indicator for tier-two supplier competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment | Captive Nagoya or Busan capacity insulates margin stability against alloy billet volatility. |
| REACH-Compliant Coating Migration | Trivalent chrome qualification maintains OEM preferred status under EU Green Deal procurement. |
| Aftermarket Platform Subscription Launch | Vibration-monitoring services from German providers extend component life beyond hardware sales. |
| Carbon Fiber Process Licensing | Out-of-autoclave curing enables tier-two entry into 50,000-unit annual sports car programs. |
| Autonomous Mining Shaft Development | Sealed assemblies for Australian unmanned haul trucks address extended service interval demand. |
Methodological Framework
Bottom-up automotive and commercial-vehicle modeling reconciled against top-down forging capacity and heat-treatment tracking forms the analytical core of this analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket fleet maintenance heads, and precision forging plant managers combined with secondary validation from NHTSA crashworthiness filings, EPA fuel economy certification databases, EU REACH substance restriction registers, and vehicle production registration data.
Historical trendline analysis of material substitution patterns and electrification adoption curves informed projection framework construction across the analysis window. Segmentation dimensions modeled include shaft architecture, material grade tier, propulsion system type, end-use duty cycle, and regional regulatory cluster. CAGRs derived from installed base turnover rates and new platform penetration assumptions incorporate battery-electric platform displacement effects and carbon fiber manufacturing cost curve trajectories.
Underlying measurement precision varies by segment; carbon fiber performance shafts and integrated e-axle substitution rates carry tighter precision than aftermarket replacement volume estimates. Forecasts reflect assumptions regarding NHTSA regulatory stringency, EU Green Deal procurement enforcement, and alloy-grade steel price normalization. Periodic stress-testing of base assumptions against MIIT dual carbon goal acceleration and autonomous vehicle deployment timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Fuel Injection Systems Market
Powertrain
Power Assisted Steering Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Automotive Tuner Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Engine Starter Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Engine Rocker Arm Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Automotive Powertrain Components Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market