
 Europe Turbocharger Market | 2026-2036
Europe Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Turbocharger Market Insights
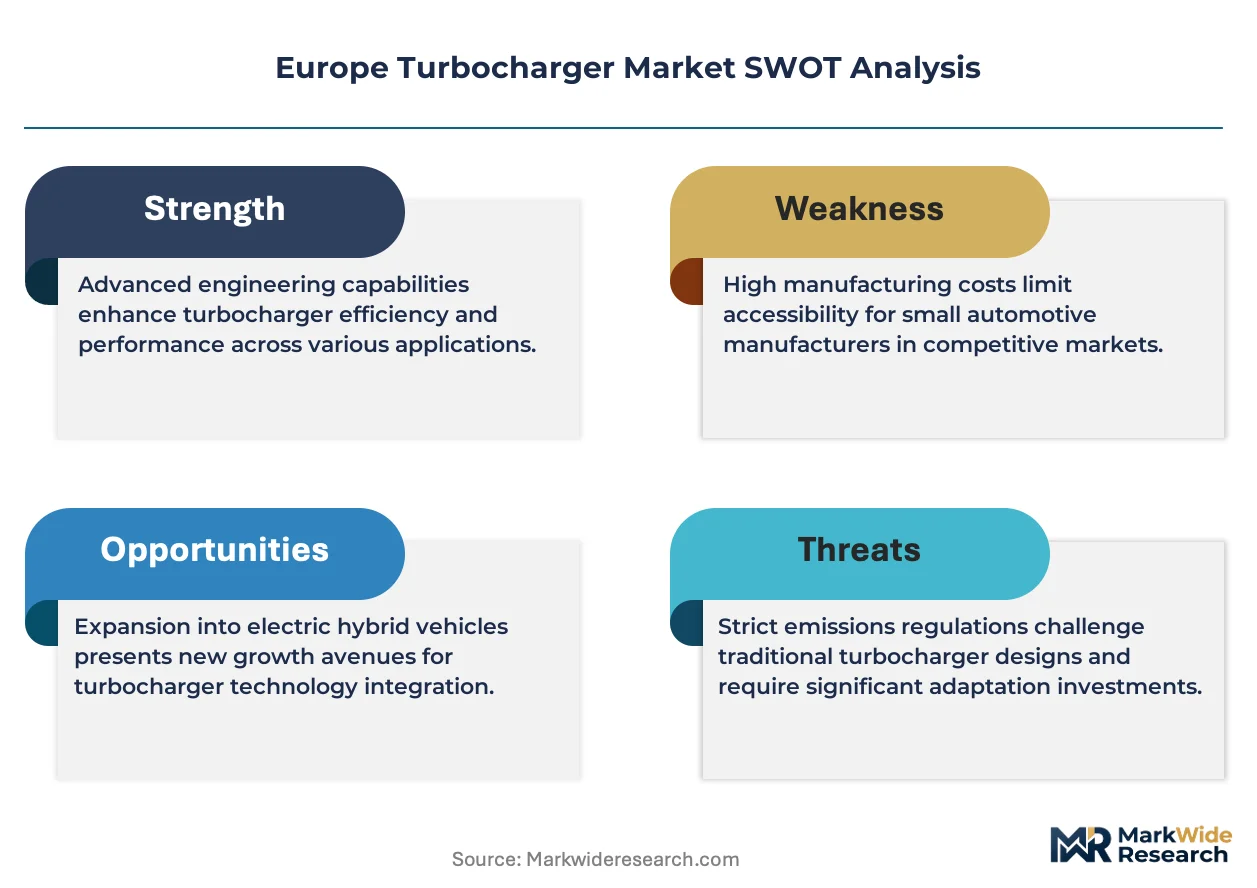
The EU Green Deal is restructuring demand trajectories across the European turbocharger supply base. BorgWarner Inc. leverages its electric turbocharger portfolio to anchor premium passenger vehicle programs in Germany. Garrett Motion Inc. competes through advanced variable geometry systems designed for downsized gasoline engines. Mitsubishi Heavy Industries Ltd. sustains manufacturing scale across multiple European production nodes.
A turbocharger is a forced induction device driven by exhaust gas energy, typically operating at turbine speeds exceeding 150,000 RPM to compress intake air and boost engine power density without proportional displacement growth. Variable geometry turbochargers dominate current OEM fitment due to their broad efficiency mapping across engine load profiles. Electric turbochargers represent the fastest-expanding product category as 48V mild-hybrid architectures proliferate. Twin-turbocharger configurations retain strong positioning in heavy-duty truck applications where sequential staging addresses wide torque band requirements.
The EU F-Gas Regulation and EMA emissions frameworks mandate progressive NOx and CO2 reductions that tighten turbocharger efficiency thresholds. REACH compliance shapes material selection for turbine housings and bearing systems. Stakeholders must monitor how the EU AI Act and embedded software requirements affect electronic turbocharger control strategies and type-approval pathways.
Market Dynamics
The EU Green Deal is compressing turbocharger development cycles as passenger vehicle OEMs race to deploy electric-assist architectures ahead of 2035 fleet emission deadlines. This regulatory pressure is restructuring supplier relationships and R&D allocation across the European supply base.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas phase-down mandates are accelerating variable geometry turbocharger deployment in commercial vehicles to recover thermal efficiency without refrigerant-dependent climate systems.
- 48V mild-hybrid architectures:Electric turbocharger integration is expanding across German and French passenger vehicle platforms to eliminate turbo lag while supporting stop-start functionality.
- Italy's commercial vehicle corridor:Concentrated demand from heavy-duty truck manufacturers around Turin and Milan is sustaining multi-shift production of sequential twin-turbo systems.
Market Restraints
- Raw material cost volatility:Inconel and titanium alloy price swings for turbine wheels are compressing margin structures for casting-dependent suppliers.
- Bearing system supply concentration:Ceramic ball bearing production clusters in southern Germany create single-source vulnerability for high-speed turbocharger assemblies.
- Technical thermal ceiling:Exhaust gas temperatures exceeding 1050°C in downsized gasoline engines are limiting conventional material durability and extending validation timelines.
Strategic Opportunities
- Poland and Czech Republic manufacturing nodes:Greenfield production capacity in Central European automotive corridors offers labor cost arbitrage for tier-two turbocharger component suppliers.
- EU AI Act compliance services:Embedded control software validation for electronic turbocharger actuators represents an emerging service revenue stream for engineering consultancies.
- Remanufacturing channel expansion:Circular economy mandates under REACH are opening secondary market pathways for refurbished commercial vehicle turbocharger cartridges.
Industry Challenges
- Electromechanical engineering talent scarcity:Hybrid skill sets combining turbomachinery aerodynamics with 48V motor control are concentrated among senior specialists approaching retirement.
- Type-approval timeline compression:Coordinated EU Whole Vehicle Type Approval and F-Gas certification processes are extending program lead times by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Turbocharger Market |
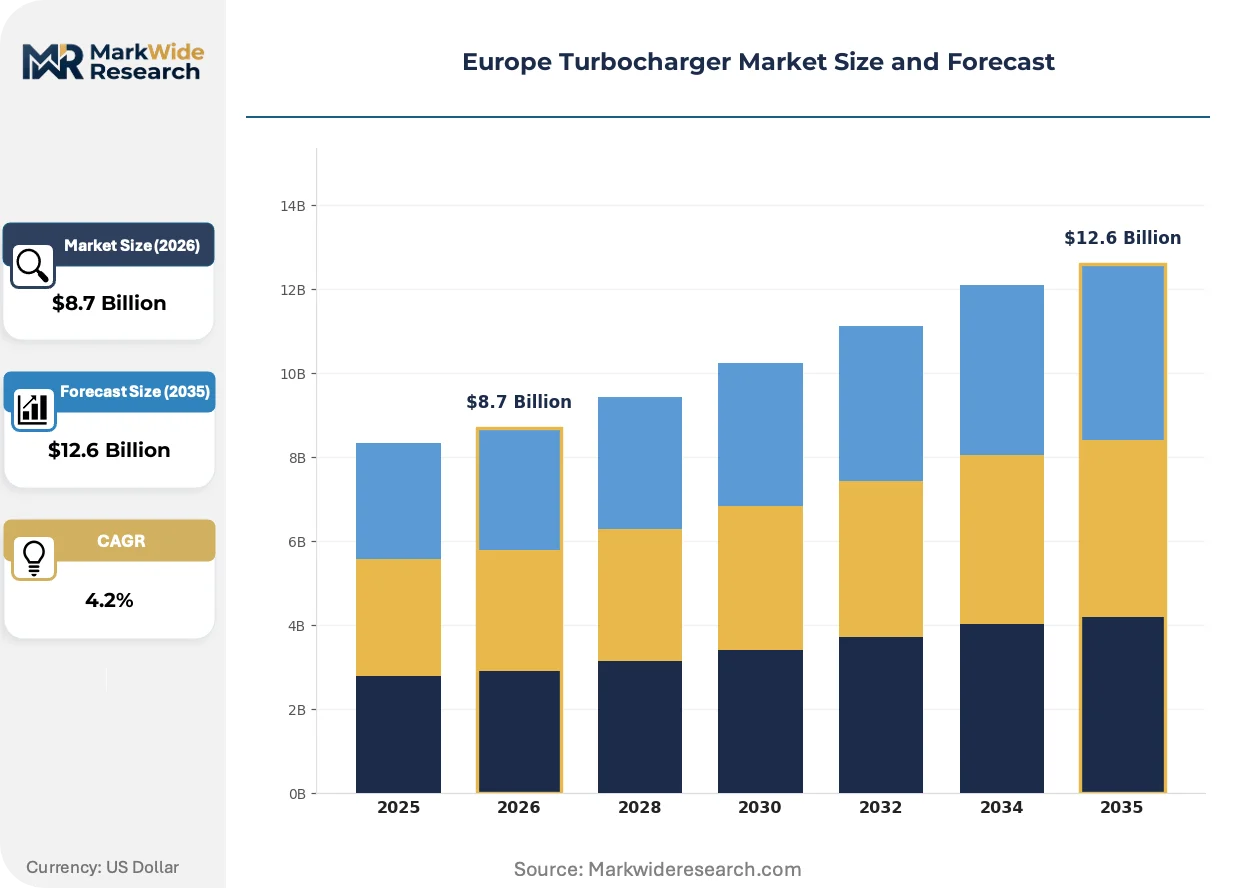
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbine Turbochargers, Twin-Turbochargers, Variable Geometry Turbochargers, Electric Turbochargers End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Installation Type: OEM, Aftermarket, Retrofit, Integrated Systems Fuel Type: Diesel, Gasoline, CNG, Others |
| Companies Covered | Mitsubishi Heavy Industries Ltd., BMTS Technology GmbH & Co. KG, BorgWarner Inc., Eaton Corporation Plc, Cummins Inc., Garrett Motion Inc., IHI Corporation, Mitsubishi Turbocharger and Engine Europe B.V., Continental AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Turbocharger Market Trends and Innovations
Electrification is fragmenting turbocharger product architectures as suppliers split development resources between conventional exhaust-driven systems and motor-assisted variants. This divergence is creating parallel engineering tracks with distinct supplier ecosystems.
Electric turbocharger technology is unifying boost response and energy recovery functions in a single rotating assembly. German premium OEMs are deploying these systems across four-cylinder mild-hybrid platforms at scale. The technology is unifying previously separate supercharger and turbocharger supply chains into consolidated electric compressor procurement programs.
REACH compliance is mandating material substitutions in turbine housings and bearing cages. ECHA substance restriction updates are forcing reformulation of high-temperature coatings and lubricant additives. Commercial vehicle manufacturers in France and the Benelux are responding with accelerated supplier qualification programs for alternative nickel alloys.
Fleet procurement departments are consolidating turbocharger aftermarket purchasing through authorized service networks rather than independent distributors. This channel compression is displacing traditional jobber networks in Spain and Portugal. Heavy-duty truck operators in Germany are driving the shift through total cost of ownership contracts that bundle turbocharger replacement into powertrain service agreements.
Europe Turbocharger Market Segmentation
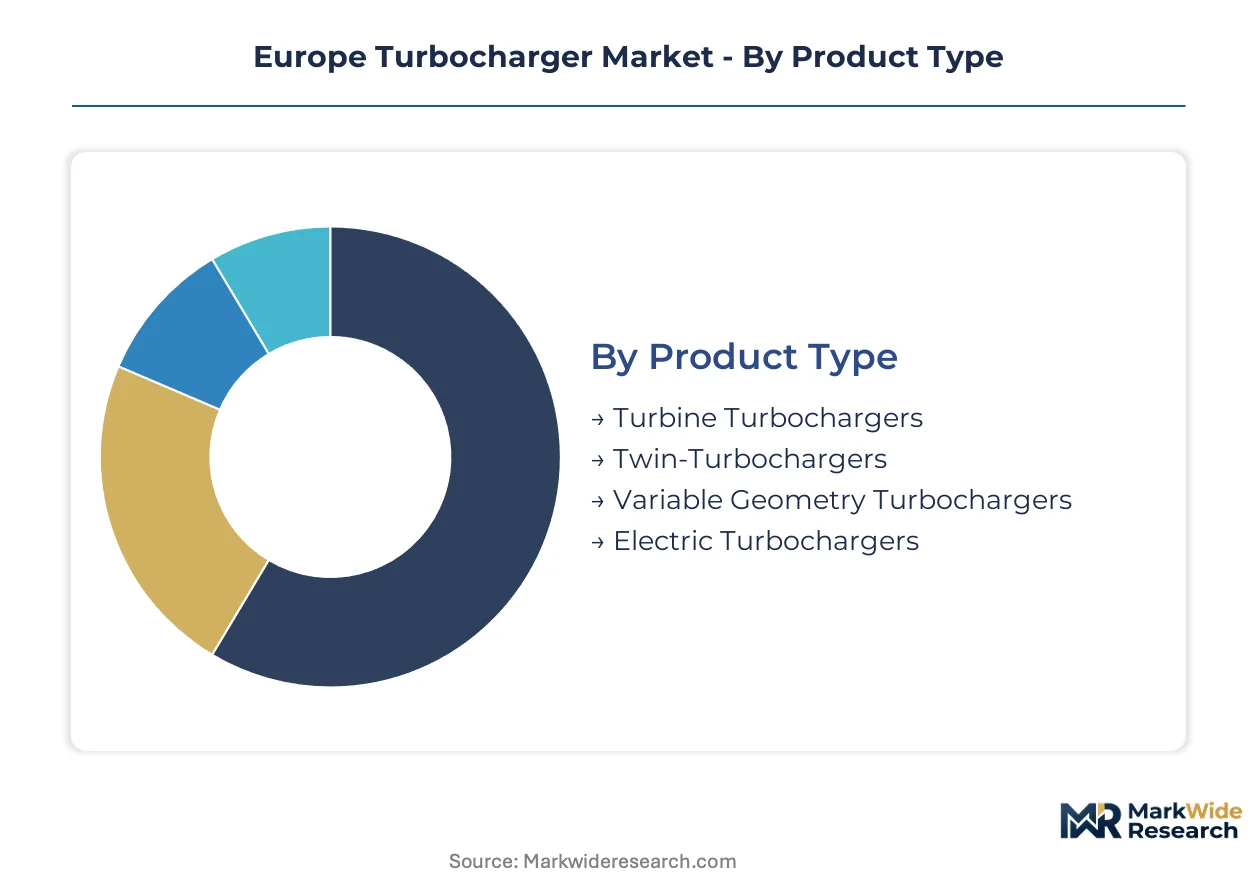
Turbocharger segmentation in Europe reflects divergent capital requirements across electrification pathways and emission compliance tiers. Product architecture choices determine foundry investments, software development intensity, and aftermarket service infrastructure.
Product Type:
Capital intensity varies sharply: electric turbochargers demand motor-winding equipment and power electronics integration, while conventional variants require precision casting and machining capacity.
- Variable Geometry Turbochargers:Vane-adjustable turbine housings enable broad efficiency mapping across load profiles. German and French passenger vehicle OEMs specify these for downsized gasoline engines under EU F-Gas Regulation pressure.
- Electric Turbochargers:Integrated 48V motor-assist eliminates lag while recovering exhaust energy. BorgWarner and Garrett Motion are scaling production for German premium platforms ahead of fleet emission deadlines.
- Turbine Turbochargers:Conventional exhaust-driven designs retain cost advantage in price-sensitive segments.
- Twin-Turbochargers:Sequential staging configurations dominate Italy's heavy-duty truck corridor around Turin and Milan.
Variable geometry systems absorb the bulk of installed capacity; electric turbochargers are expanding most quickly.
End User:
Application requirements split engineering priorities between transient response optimization and continuous-duty thermal durability.
- Passenger Vehicles:Four-cylinder downsizing drives demand for compact, electrically assisted units. French and German OEM procurement programs specify integrated 48V architectures.
- Heavy-Duty Trucks:Sequential twin-turbo systems address wide torque bands under sustained high-load operation. Italian manufacturers around Milan sustain multi-shift production lines.
- Commercial Vehicles:Fleet operators in the Benelux specify total cost of ownership contracts bundling turbocharger replacement into powertrain service agreements.
- Motorcycles:Niche displacement segment with concentrated demand from Italian and German performance brands.
Passenger vehicles command the largest production volumes; heavy-duty trucks generate the highest per-unit margins through specialized engineering.
Installation Type:
Channel structure determines warranty exposure and software validation obligations under EU AI Act embedded control requirements.
- OEM:Factory-fit systems carry full type-approval liability and coordinated EU Whole Vehicle Type Approval timelines.
- Integrated Systems:Powertrain-embedded designs with shared cooling and control architectures. German premium OEMs favor these for mild-hybrid platforms.
- Aftermarket:Authorized service networks are consolidating procurement in Spain and Portugal, displacing traditional jobber distribution.
- Retrofit:Commercial vehicle emission upgrade programs in France and Germany drive qualified installer demand.
OEM installation dominates value capture; integrated systems are climbing the fastest as electrification unifies powertrain component sourcing.
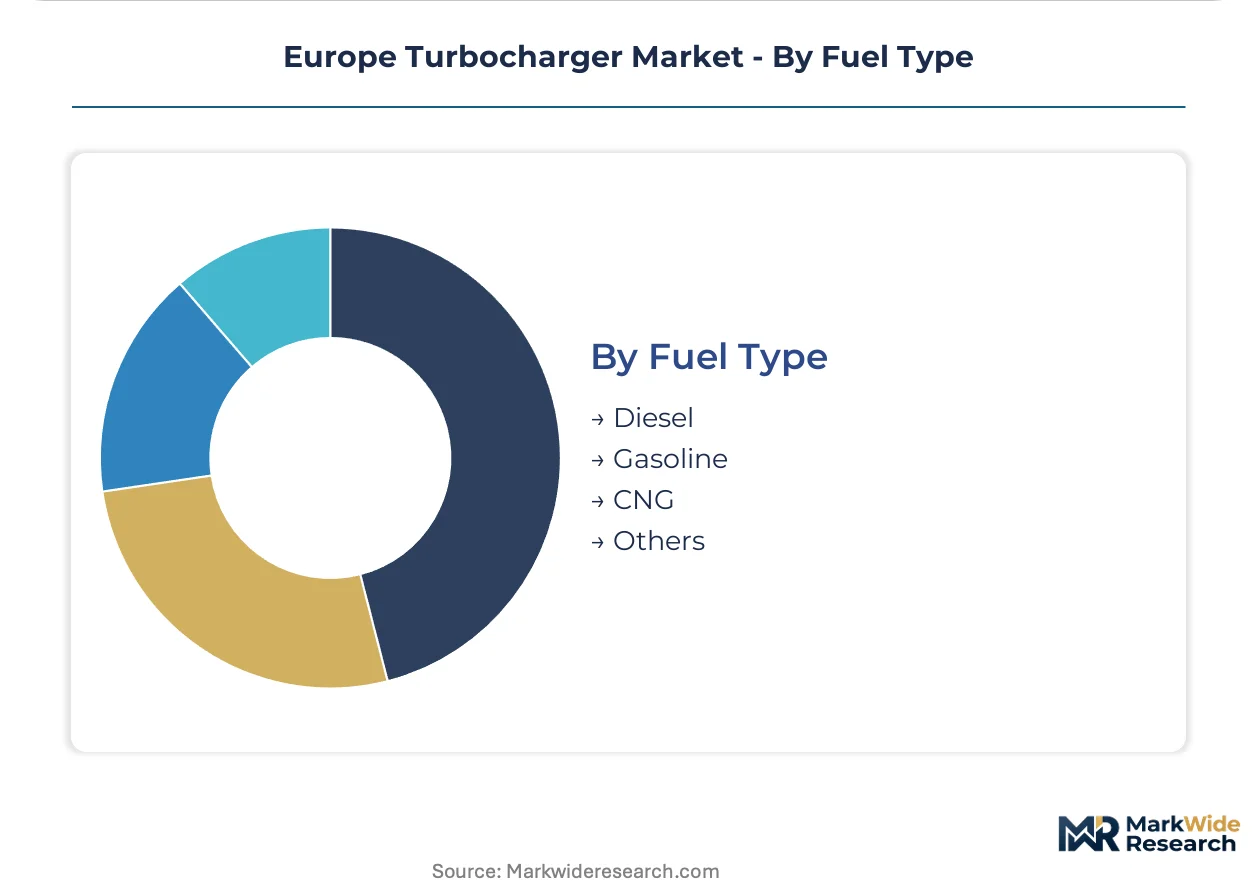
Fuel Type:
Combustion chemistry dictates turbine inlet temperature limits and material specification tiers.
- Gasoline:Downsized direct-injection engines exceed 1050°C exhaust temperatures, forcing Inconel turbine wheel adoption and extended validation cycles.
- Diesel:Lower peak temperatures enable conventional material sets, though EU Green Deal NOx targets demand precision boost control.
- CNG:Cleaner combustion profiles reduce thermal stress but require specialized fuel system integration.
- Others:Emerging synthetic fuel compatibility testing is underway at German technical centers.
Gasoline applications stress material science most severely; diesel retains volume leadership in commercial vehicle fitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Central European automotive corridors while demand clusters in Western European premium passenger vehicle markets. This spatial mismatch structures logistics networks and supplier relationships across the continent.
Germany
Passenger vehicle OEMs in Stuttgart and Munich are scaling 48V mild-hybrid architectures ahead of fleet emission deadlines. The KBA enforces EU Whole Vehicle Type Approval timelines that compress development cycles. Baden-Württemberg hosts precision casting operations for Inconel turbine wheels serving downsized gasoline engine programs.
France
French premium brands specify electric turbocharger integration across four-cylinder platforms to eliminate lag. The EU F-Gas Regulation drives variable geometry adoption in commercial fleets operating climate-sensitive routes. The Île-de-France region anchors powertrain engineering centers coordinating pan-European supplier qualification.
Italy
Heavy-duty truck manufacturers around Turin sustain multi-shift production of sequential twin-turbo systems for wide torque band applications. ECHA substance restrictions under REACH mandate material substitutions in turbine housings. Lombardy's commercial vehicle corridor captures concentrated demand from Milan-based fleet operators bundling turbocharger replacement into service agreements.
Poland
Greenfield production nodes in Lower Silesia offer labor cost arbitrage for tier-two turbocharger component suppliers serving Western European OEMs. The EU Green Deal's circular economy mandates open remanufacturing pathways for commercial vehicle cartridges. Automotive corridors near Wrocław attract bearing system suppliers seeking proximity to German assembly plants.
Czech Republic
Central European manufacturing clusters near Ostrava support precision machining capacity for turbocharger housings and actuator mechanisms. CSRD reporting requirements shape supplier ESG qualification protocols for multinational OEMs. The country's technical universities feed engineering talent into turbomachinery aerodynamics programs serving the regional supply base.
Europe Turbocharger Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive automotive supply divisions. Tier-one suppliers with precision casting and electronics integration capabilities occupy the center of gravity. Three archetypes dominate: integrated powertrain specialists, standalone turbocharger engineering houses, and diversified heavy-industry groups with automotive divisions. Capacity expansion and strategic technology licensing represent the dominant competitive moves as electrification fragments product architectures.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd. and IHI Corporation exemplify the heavy-industry archetype with automotive supply divisions. BorgWarner Inc. and Garrett Motion Inc. occupy positions within the integrated powertrain specialist tier. BMTS Technology GmbH & Co. KG represents the standalone engineering house model concentrated on turbocharger-specific R&D. Continental AG and Eaton Corporation Plc anchor diversified supplier positions spanning multiple powertrain domains. These groupings reflect how electrification is unifying previously separate component supply chains into consolidated procurement programs.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd. |
| BMTS Technology GmbH & Co. KG |
| BorgWarner Inc. |
| Eaton Corporation Plc |
| Cummins Inc. |
| Garrett Motion Inc. |
| IHI Corporation |
| Mitsubishi Turbocharger and Engine Europe B.V. |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Performance-grade divergence between electric turbochargers and conventional exhaust-driven units manifests in parallel supply chain configurations across Europe. Premium electric-assist systems command foundry investments in motor-winding equipment and power electronics integration, while commodity turbine housings flow from precision casting networks anchored in Germany and the Czech Republic. This bifurcation concentrates pricing power among suppliers with captive 48V motor control capabilities, while tier-two component producers compete on labor cost arbitrage from Poland and Slovakia.
Pricing Analysis
Cost-down pressure on conventional turbine housings accelerates because Inconel and titanium alloy price volatility compresses margin structures for casting-dependent suppliers. Three-tier pricing structure across premium electric-assist, standard variable geometry, and economy fixed-geometry levels reflects certification grade under EU F-Gas Regulation and REACH compliance tiers. Price differentiation hinges on thermal durability ratings and integrated motor control complexity. Fleet procurement departments in Germany exhibit lowest price sensitivity through total cost of ownership contracts, while independent aftermarket distributors in Spain and Portugal face acute margin compression from authorized service network consolidation.
Supply Chain Analysis
Ceramic ball bearing supply rests on precision manufacturing clusters in southern Germany, creating single-source vulnerability for high-speed turbocharger assemblies. Raw material flows draw from Inconel foundries in Baden-Württemberg, titanium alloy processors in the Czech Republic, and rare-earth magnet suppliers for electric motor integration. Distribution runs through OEM-authorized service networks consolidating procurement in Western Europe, displacing traditional jobber channels. Tariff exposure on Chinese-sourced rare-earth elements presents structural risk for electric turbocharger motor production scaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic bearing production concentration in southern Germany props pricing for high-speed assemblies, constraining supply elasticity as 48V mild-hybrid adoption accelerates. This bottleneck sustains margin capture for incumbents with captive precision manufacturing while exposing new entrants to qualification timeline risk.
For Market Incumbents: Anchor defensive positioning through backward integration into Inconel turbine wheel casting capacity in Baden-Württemberg, securing thermal material supply against REACH-mandated substitution cycles. Deepen channel control by acquiring authorized service network capacity in Spain and Portugal before aftermarket consolidation completes. Electromechanical engineering talent scarcity among retirement-age turbomachinery specialists threatens R&D velocity; lock hybrid skill sets through targeted technical university partnerships in the Czech Republic. For New Entrants and Emerging Players: Capture white-space opportunity in remanufactured commercial vehicle turbocharger cartridges under Poland's circular economy infrastructure development. Poland and Czech Republic greenfield nodes offer lowest barrier to entry for tier-two bearing system and actuator mechanism suppliers. Target fleet procurement departments in the Benelux with outcome-based total cost of ownership contracts bundling turbocharger replacement into powertrain service agreements, bypassing established OEM-authorized networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking automotive supply division expansion, with strategic buyers valuing captive electric turbocharger motor control capabilities. Long-term viability favors targets with dual-track engineering competency spanning conventional exhaust-driven and electric-assist architectures. Watch ceramic bearing supply qualification timelines as the inflection signal—delays beyond standard validation cycles indicate incumbent pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Turbocharger Platform Standardization | Unifies 48V motor-assist and energy recovery functions for German premium OEM procurement programs. |
| Backward Integration into Inconel Casting | Secures turbine wheel supply against REACH-mandated material substitution and thermal durability thresholds. |
| Authorized Service Network Acquisition | Consolidates aftermarket channel control in Spain and Portugal ahead of fleet procurement bundling trends. |
| Circular Economy Remanufacturing Scale-Up | Captures secondary market pathways for commercial vehicle cartridges under Poland's EU Green Deal infrastructure. |
| EU AI Act Compliance Service Development | Opens embedded control software validation revenue for electronic turbocharger actuators under coordinated type-approval. |
Research Methodology
Independent corroboration across OEM platform engineering disclosures, tier-one supplier procurement patterns, and ECHA substance restriction filings underwrites the qualitative findings. Primary interviews with turbocharger product directors, OEM powertrain procurement leads, aftermarket service network managers, and foundry operations heads combined with secondary validation from vehicle production databases, EU Whole Vehicle Type Approval records, and REACH compliance documentation. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the projection horizon.
Rate-of-change decomposition separates volume growth from value expansion across product type, end user, installation channel, and fuel type segmentation dimensions. CAGRs derive from production capacity buildout trajectories, fleet emission deadline compliance schedules, and 48V mild-hybrid platform penetration curves. Forecast inputs incorporate EU F-Gas Regulation phase-down mandates, ECHA substance restriction timelines, and CSRD reporting requirements shaping supplier ESG qualification protocols.
The model holds under stable EU regulatory enforcement and continuous rare-earth magnet supply; deviation in ceramic bearing production disruption or REACH acceleration would shift capacity allocation assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Engines Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Engine Flush Market
Powertrain
Car Active Purge Pump Market
Powertrain
Automotive Turbocharger Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Tuning Box Market
Powertrain
Brazil Automotive Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Automotive Fuel Cock Market