
 India Automotive Engine Oils Market | 2026-2036
India Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Engine Oils Market Foresight
Authorized dealer networks for automotive engine oils in India is narrowing as direct-to-workshop digital platforms and lubricant company-operated service stations capture fleet accounts. Indian Oil Corporation Limited leverages its 50,000-plus fuel retail footprint to push bundled engine oil sales at highway touchpoints. Bharat Petroleum Corporation Limited sustains dominance in the commercial vehicle segment through co-branded workshops with OEMs. Gulf Oil International competes aggressively in the two-wheeler aftermarket via hyperlocal distributor apps.
Automotive engine oils are formulated lubricants comprising base stocks and additive packages designed to reduce friction, dissipate heat, and neutralize combustion acids in internal combustion engines, with synthetic variants using Group III or PAO bases to meet lower viscosity targets like 0W-20 under high-temperature shear stability protocols. Synthetic grades command the dominant value share as OEM fill specifications shift toward fuel-economy-focused low-viscosity formulations. Fleet operators represent the fastest-growing end user category as consolidated logistics players mandate centralized bulk procurement with used-oil traceability. Drum packaging anchors the commercial segment while bottle formats retain strength in the fragmented two-wheeler service market.
BIS certification requirements and the Automotive Research Association of India's emission testing protocols shape product approval timelines, while the Central Pollution Control Board's used oil handling rules tighten reverse logistics obligations on manufacturers and distributors. The Ministry of Petroleum and Natural Gas's ethanol blending roadmap indirectly pressures lubricant thermal stability standards as engine operating profiles shift. Stakeholders must monitor how BS VII anticipation and potential carbon intensity disclosures alter base stock sourcing strategies and refiner-chemical supplier partnerships.
Market Dynamics
BS VI Stage II emission norms are compressing formulation cycles as lubricant manufacturers reformulate base stocks to meet lower viscosity targets and thermal stability requirements under ethanol-blended fuel operating profiles.
Growth Catalysts
- Fleet Consolidation:Large logistics operators in Maharashtra and Gujarat are mandating centralized bulk procurement with used-oil traceability, pulling volume through synthetic-grade contracts.
- BIS Certification Mandates:The Bureau of Indian Standards' tightened approval timelines for engine oil specifications are filtering out sub-scale blenders and concentrating volume with certified manufacturers.
- Ethanol Blending Roadmap:The Ministry of Petroleum and Natural Gas's push toward higher ethanol blends is forcing thermal stability upgrades across passenger car and commercial vehicle lubricant portfolios.
Market Restraints
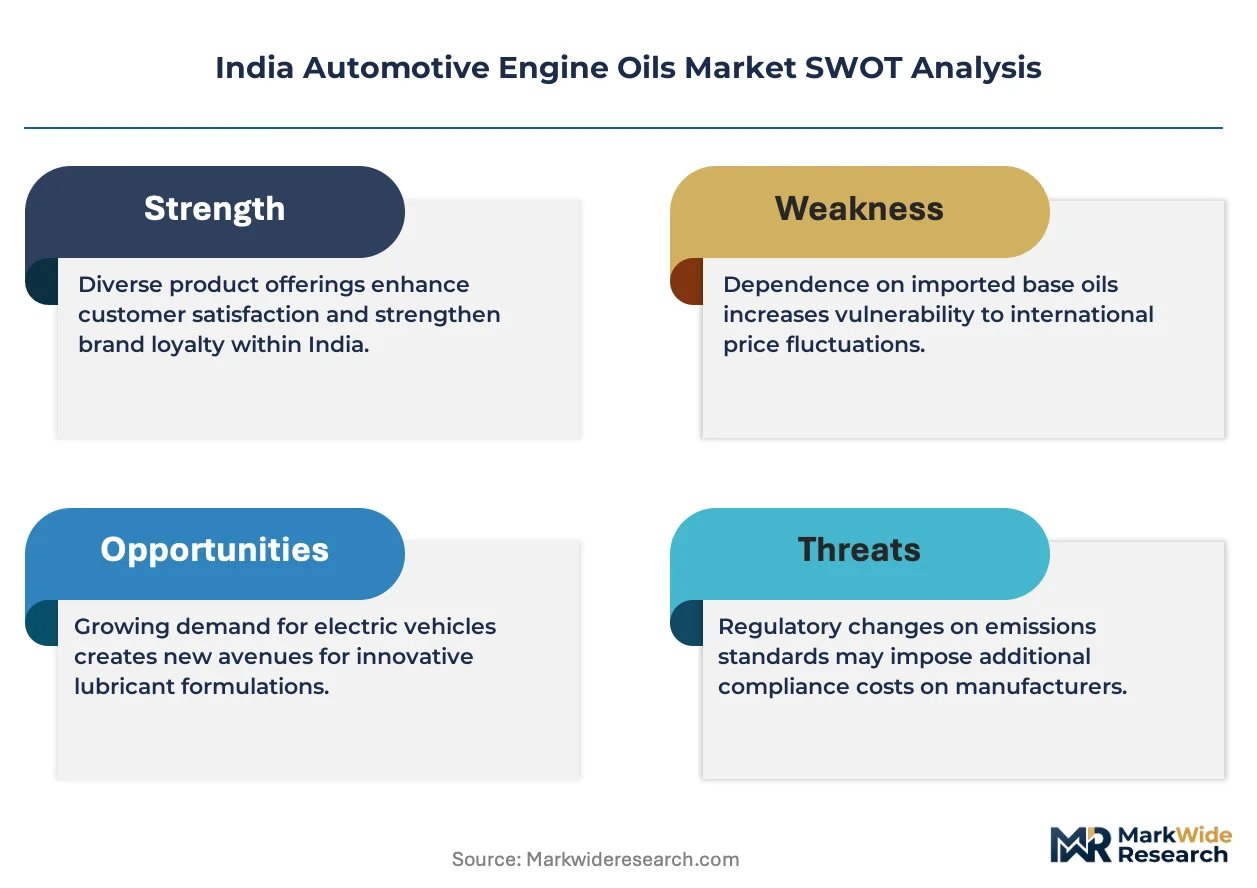
- Group III Base Stock Import Dependency:Domestic refiners lack sufficient hydrocracker capacity for synthetic-grade feedstock, exposing margins to Middle Eastern supply volatility.
- Additive Package Concentration:Four global chemical suppliers control friction-modifier and detergent chemistry, creating bottleneck risk for Indian blenders seeking rapid reformulation.
- BS VII Anticipation Freeze:Uncertainty around timing and stringency of the next emission standard is delaying R&D commitments on ultra-low-ash formulations for gasoline particulate filters.
Strategic Opportunities
- Tamil Nadu Manufacturing Corridor:OEM assembly plants in Chennai and Sriperumbudur are creating captive demand for factory-fill synthetic contracts with multi-year supply agreements.
- Digital Workshop Platforms:Direct-to-fleet procurement apps are bypassing traditional distributor tiers, allowing lubricant marketers to capture margin and data simultaneously.
- Used Oil Reverse Logistics:Central Pollution Control Board re-refining mandates are opening licensed collection and processing infrastructure as a regulated service layer.
Industry Challenges
- Formulation Chemist Scarcity:Indian technical institutes produce insufficient tribology and lubricant chemistry specialists, forcing manufacturers to recruit from polymer and coatings sectors.
- Test Protocol Backlogs:Automotive Research Association of India's engine dynamometer availability constraints are stretching new product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Engine Oils Market |
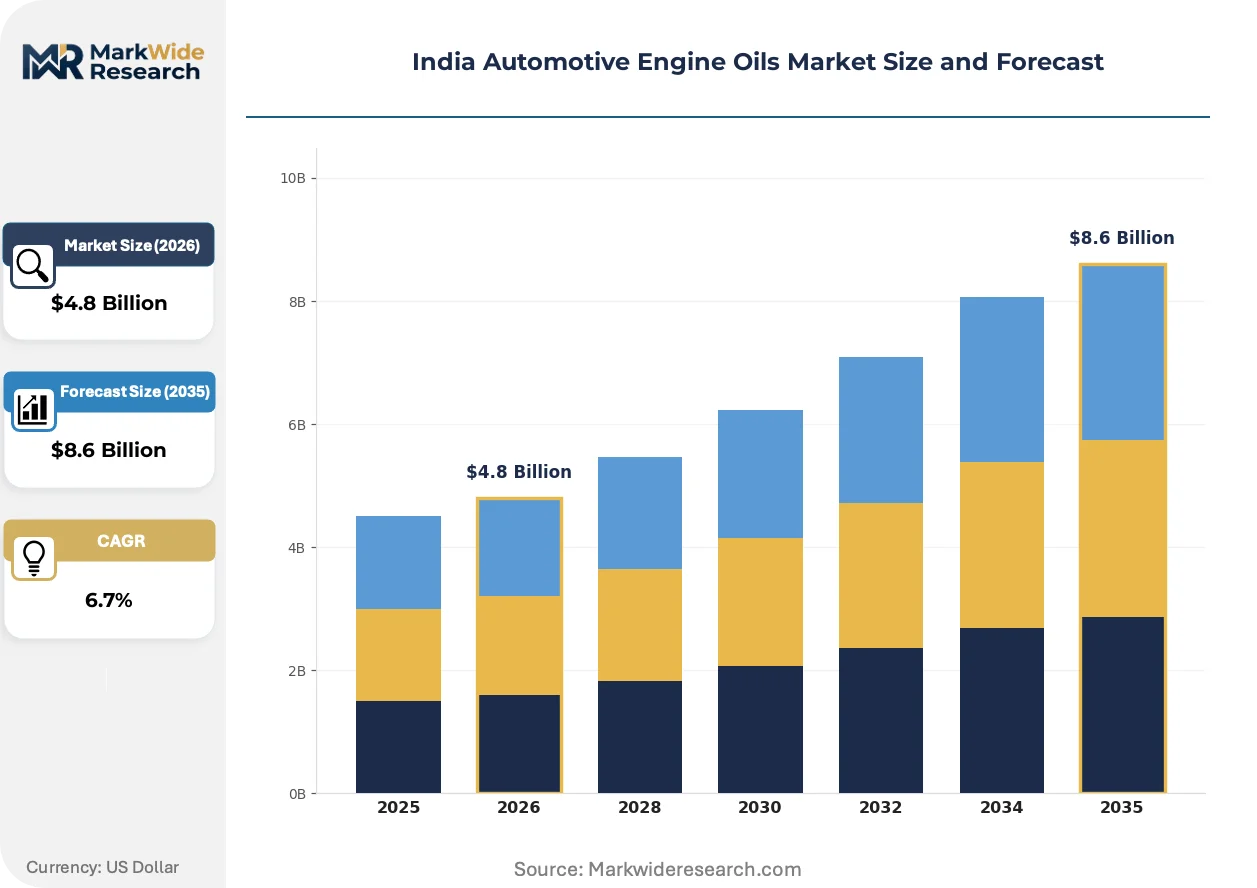
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Semi-Synthetic, Bio-Based End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Operators Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Drum, Bottle, Pail, Bulk |
| Companies Covered | BP plc, ExxonMobil Corporation, Indian Oil Corporation Limited, TotalEnergies, Royal Dutch Shell Plc, Bharat Petroleum Corporation Limited, Gulf Oil International, Valvoline Inc., Hindustan Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Engine Oils Market Shifts & Advancements
Reformulation pressures are intersecting with distribution digitization and procurement centralization to reshape how lubricant value flows from refinery to engine sump across Indian automotive markets.
Polyalphaolefin-based 0W-20 and 0W-16 grades are penetrating OEM fill specifications as fuel-economy regulations tighten. Passenger car manufacturers in Gujarat and Tamil Nadu are specifying these viscosities for new compact SUV and sedan platforms. Higher additive treat rates for wear protection under low-viscosity operation are rendering obsolete older Group I and Group II mineral formulations in the factory-fill channel.
BIS certification timelines have compressed from eighteen months to ten months for new viscosity grade approvals. The Bureau of Indian Standards' alignment with ACEA and API sequences is forcing domestic blenders to maintain parallel testing protocols. Maharashtra-based commercial vehicle operators are responding by consolidating supplier lists to those with pre-approved product ranges, reducing qualification overhead.
Fleet operators are unbundling lubricant procurement from vehicle maintenance contracts. Large road logistics players in Delhi-Mumbai and Chennai-Bengaluru corridors are establishing direct supply agreements with blenders, bypassing traditional automotive spare parts distributors. This disintermediation is most visible in the containerized freight segment, where fuel economy tracking creates transparency on lubricant performance claims.
India Automotive Engine Oils Market Segmentation
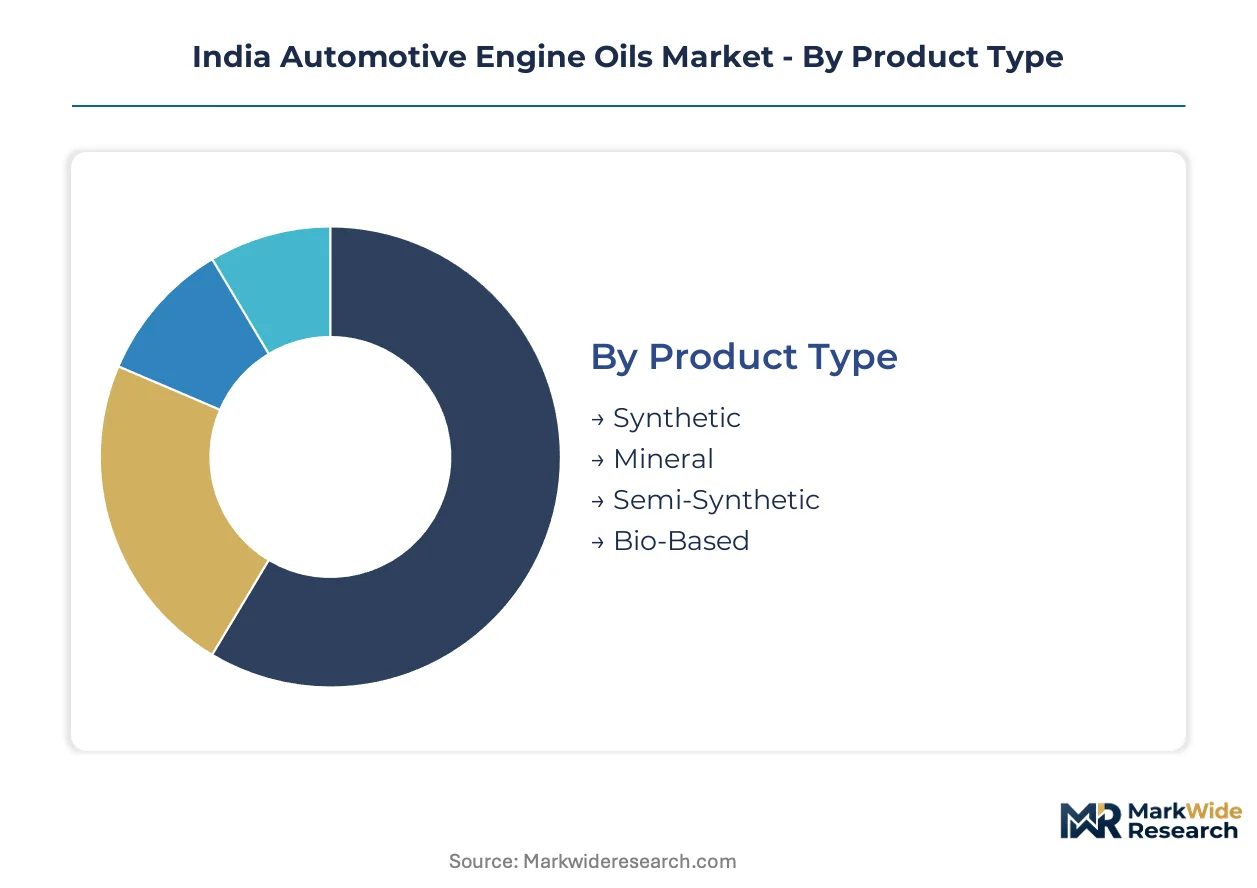
Segmentation in India's automotive engine oils market reveals how formulation technology, procurement scale, and distribution format intersect to determine competitive positioning. Understanding these dimensions exposes where margin pools concentrate and which customer configurations are rotating toward synthetic-grade dominance.
Product Type:
Cost tier stratification separates premium synthetic formulations from commodity mineral bases, with reformulation cycles and margin structures diverging sharply across these chemistry categories.
- Synthetic:Group III and PAO base stocks deliver thermal stability under ethanol-blended fuel profiles and BS VI Stage II operating temperatures. Fleet operators in Maharashtra and Gujarat are consolidating procurement around synthetic contracts with used-oil traceability mandates, compressing supplier lists to certified blenders.
- Mineral:Group I and Group II base formulations retain residual volume in price-sensitive two-wheeler service channels where drain intervals remain shorter and OEM specifications less stringent. Tamil Nadu's independent workshops continue stocking mineral grades for older vehicle parc, though factory-fill specifications are excluding these formulations from new platforms.
- Semi-Synthetic:Blended formulations occupy a narrowing mid-tier as OEM fill specifications polarize toward full synthetic for fuel economy compliance.
- Bio-Based:Ester and vegetable-derived base stocks remain experimental in Indian formulations, constrained by BIS approval timelines and thermal oxidation stability under tropical operating conditions.
Synthetic holds installed capacity. Semi-Synthetic is rotating up the share rankings.
End User:
Application-based segmentation tracks how vehicle duty cycles, annual mileage accumulation, and maintenance contract structures reshape lubricant procurement authority.
- Fleet Operators:Consolidated logistics players with centralized maintenance operations are mandating direct blender relationships, bypassing automotive spare parts distributors entirely. Delhi-Mumbai and Chennai-Bengaluru corridor operators now track fuel economy per vehicle, creating performance transparency that validates synthetic-grade claims and locks in multi-year supply agreements.
- Commercial Vehicles:Highway operators and intracity freight fleets generate the highest per-vehicle lubricant consumption volumes, with drum packaging and bulk delivery formats dominating procurement. Bharat Petroleum Corporation Limited's co-branded OEM workshops sustain channel control in this segment through maintenance bundling.
- Passenger Vehicles:OEM factory-fill specifications and authorized service networks shape demand, with 0W-20 and 0W-16 grades penetrating compact SUV and sedan platforms from Gujarat and Tamil Nadu assembly plants.
- Two-Wheelers:Fragmented independent service channels retain bottle-format dominance, with Gulf Oil International's hyperlocal distributor apps capturing aftermarket share through convenience positioning.
Fleet Operators are climbing the fastest. Commercial Vehicles retains volume concentration.
Viscosity Grade:
Volume distribution across viscosity grades reflects the tension between fuel-economy-driven low-viscosity OEM specifications and thermal protection requirements under Indian operating conditions.
- 0W-20:Polyalphaolefin-based formulations meeting high-temperature shear stability protocols are penetrating factory-fill specifications for new passenger car platforms, displacing higher-viscosity legacy grades.
- 5W-30:The broadest compatibility range across passenger and light commercial vehicle segments sustains this grade's position as the highest-volume specification in aftermarket channels.
- 10W-40:Commercial vehicle engines and older passenger car parc continue generating demand, though specifications are tightening toward lower-viscosity alternatives.
- 15W-50:Heavy-duty commercial applications and high-performance two-wheeler segments retain this grade for extreme load and temperature conditions.
5W-30 holds installed capacity. 0W-20 is rotating up the share rankings.
Packaging Type:
Customer type and procurement scale determine packaging format selection, with format economics directly influencing distributor margin structures and logistics configuration.
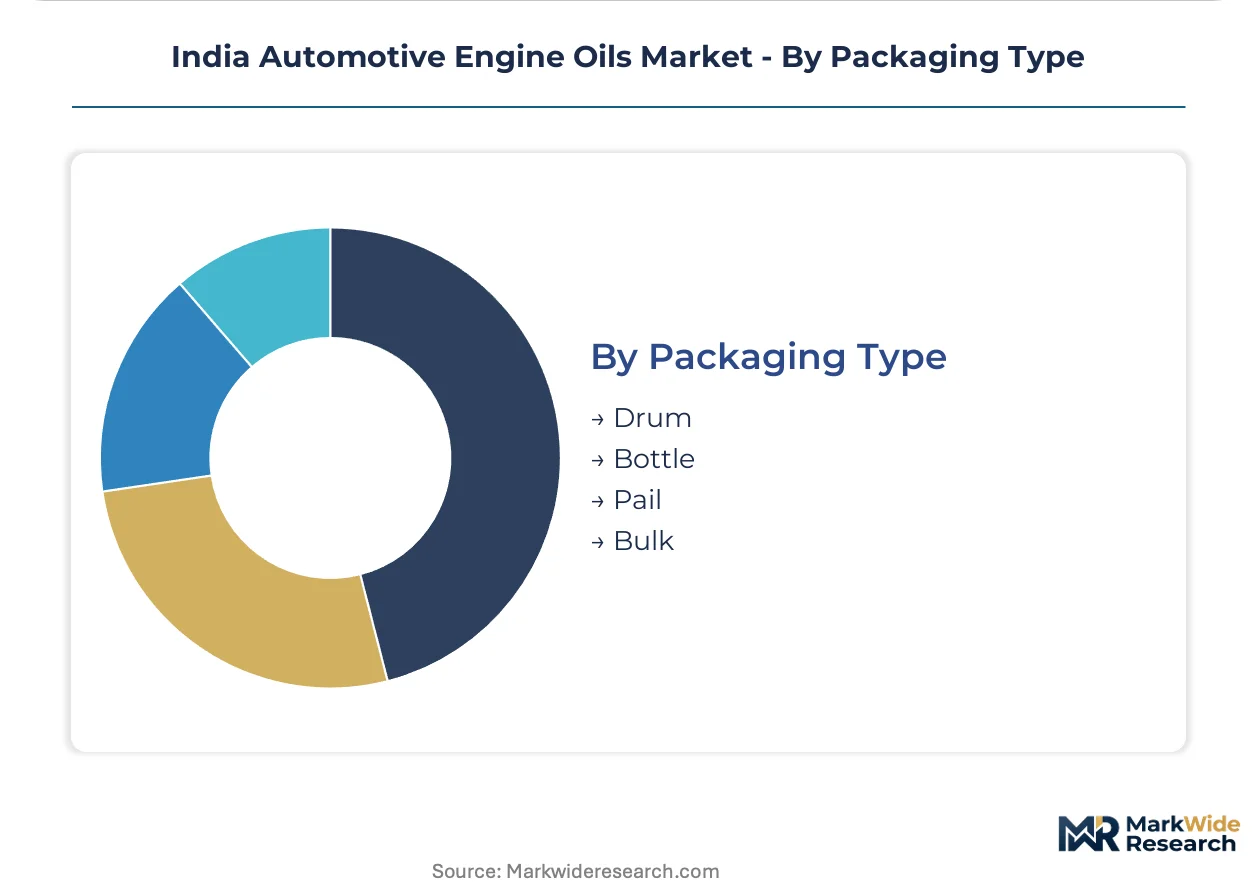
- Drum:200-liter steel and composite drums anchor commercial vehicle fleet procurement, with Maharashtra-based operators specifying drum delivery to centralized depot facilities for distribution to maintenance bays.
- Bulk:Direct-to-workshop tanker delivery is penetrating large fleet accounts in Gujarat's logistics corridors, eliminating packaging cost and enabling real-time inventory monitoring through digital procurement platforms.
- Bottle:1-liter and 4-liter retail formats retain dominance in two-wheeler service channels where transaction sizes remain small and brand visibility at point-of-service influences selection.
- Pail:20-liter plastic pails serve mid-scale independent workshops and smaller fleet operators with intermittent consumption patterns, bridging drum and bottle economics.
Drum holds installed capacity. Bulk is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor freight rail network underwrites Maharashtra's position as India's dominant lubricant consumption zone. Bulk procurement contracts from fleet operators concentrate along this logistics artery.
Maharashtra
Containerized freight operators in the Pune-Nashik belt mandate synthetic-grade contracts with used-oil traceability. The state's pollution control board enforces hazardous waste handling protocols that compress supplier lists to certified blenders. Mumbai's port infrastructure feeds base stock imports to formulation plants in Thane and Raigad districts.
Gujarat
Commercial vehicle assembly plants in Sanand and Halol generate captive factory-fill demand for low-viscosity formulations. The state's petroleum regulator coordinates with BIS on ethanol-blended fuel compatibility testing. Hazira's industrial zone hosts bulk lubricant storage terminals serving Delhi-Mumbai corridor fleets.
Tamil Nadu
Passenger car OEMs in Sriperumbudur and Oragadam specify 0W-20 grades for compact SUV platforms. The state's industrial policy incentivizes lubricant blending capacity near automotive clusters. Chennai's port handles additive package imports for southern formulation facilities.
Karnataka
Two-wheeler service density in Bengaluru sustains bottle-format demand through hyperlocal distribution apps. The state's transport department mandates emission testing that accelerates drain interval compliance. Hosur's automotive component belt generates ancillary lubricant consumption from precision machining operations.
Haryana
Commercial vehicle manufacturing in Gurugram and Faridabad pulls drum-format procurement through co-branded workshop networks. The National Capital Region's air quality regulations tighten particulate emission standards affecting lubricant ash content specifications. Manesar's logistics parks concentrate fleet operator accounts for bulk supply negotiations.
India Automotive Engine Oils Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: national oil companies with fuel retail infrastructure, international majors with technical licensing depth, and specialized lubricant marketers with hyperlocal distribution agility. Competitive positioning hinges on BIS certification velocity, base stock supply security, and fleet account capture through digital procurement platforms. M&A activity targets additive formulation capabilities and used-oil reverse logistics licensing.
Within the national oil company tier, Indian Oil Corporation Limited and Bharat Petroleum Corporation Limited anchor market presence through bundled fuel-lubricant propositions at highway retail points. Gulf Oil International occupies a position exemplifying specialized marketer agility in fragmented two-wheeler channels. These three entities represent the dominant competitive configurations: infrastructure-integrated supply, OEM workshop co-branding, and digital platform disintermediation respectively.
| Leading Market Players |
|---|
| BP plc |
| ExxonMobil Corporation |
| Indian Oil Corporation Limited |
| TotalEnergies |
| Royal Dutch Shell Plc |
| Bharat Petroleum Corporation Limited |
| Gulf Oil International |
| Valvoline Inc. |
| Hindustan Petroleum Corporation Limited |
| Others |
Supply & Pricing Matrix
The Delhi-Mumbai Industrial Corridor's freight density compresses logistics costs for bulk lubricant deliveries while amplifying price differentiation between synthetic-grade contracts and mineral-based spot purchases across Maharashtra and Gujarat procurement zones.
Pricing Analysis
Volume-discount tiering structures separate fleet operators securing multi-year synthetic contracts from independent workshops purchasing bottle-format mineral grades on spot terms. BIS certification grade and annual offtake volume serve as the primary price differentiation drivers, with certified blenders commanding premiums over sub-scale competitors. Pricing pressure stems from fleet procurement centralization mandating transparent fuel economy tracking that validates performance claims and compresses supplier margins. Commercial vehicle fleet operators exhibit the lowest price sensitivity due to total cost of ownership calculations, while two-wheeler service channels remain highly sensitive to per-liter differentials.
Supply Chain Analysis
Import dependency for Group III base stocks from Middle Eastern refiners dominates supply chain risk exposure for Indian synthetic-grade blenders. Domestic formulation plants draw from Singapore, South Korea, and Japan for additive packages containing friction modifiers and detergent chemistry. Single-source vulnerability concentrates around four global chemical suppliers controlling proprietary additive formulations. Distribution runs through Indian Oil Corporation's highway retail network, Bharat Petroleum's co-branded OEM workshops, and Gulf Oil International's hyperlocal distributor apps serving fragmented two-wheeler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against electric vehicle penetration eroding internal combustion engine lubricant demand while capturing fleet consolidation tailwinds in the interim window.
For Market Incumbents: Insulate factory-fill positions through captive supply agreements with Tamil Nadu and Gujarat OEM assembly plants as vehicle electrification timelines remain uncertain. Deepen backward integration into additive formulation capabilities to reduce dependency on the four global chemical suppliers controlling friction-modifier chemistry. Fleet operator consolidation represents the immediate volume threat requiring preemptive multi-year contract structures. For New Entrants and Emerging Players: Used oil reverse logistics licensing under Central Pollution Control Board mandates represents the most penetrable entry point for regulated service-layer positioning. Tamil Nadu's industrial policy incentives for blending capacity near automotive clusters offer geographic white space for synthetic-grade manufacturing footprint. Digital procurement platforms bypassing traditional distributor tiers provide the optimal go-to-market angle for fleet account acquisition without legacy channel investment. For Investors and Strategic Acquirers: Regional blenders with pre-approved BIS product ranges and established fleet relationships constitute the highest-signal acquisition archetype for consolidation plays. Long-term viability hinges on 5-10 year positioning around lubricant thermal stability requirements under escalating ethanol blending mandates. The signal to monitor is BS VII emission standard timing announcements, which will trigger R&D commitment cycles for ultra-low-ash formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Formulation | Reduces dependency on Lubrizol, Infineum, Afton, and Oronite chemistry bottlenecks. |
| Multi-Year Fleet Supply Agreements | Locks in Maharashtra and Gujarat logistics corridor volume against competitor poaching. |
| Used Oil Reverse Logistics Licensing | Captures Central Pollution Control Board-mandated re-refining service revenue streams. |
| Digital Procurement Platform Deployment | Bypasses automotive spare parts distributors to capture fleet operator margin and data. |
| Ethanol-Blend Thermal Stability R&D | Positions portfolios for Ministry of Petroleum and Natural Gas blending roadmap escalation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lubricant blenders, fleet procurement managers, OEM platform engineers, and additive suppliers; and secondary validation through BIS certification records, Ministry of Petroleum and Natural Gas policy circulars, Automotive Research Association of India test protocols, and Central Pollution Control Board hazardous waste handling filings. Bottom-up volume triangulation across viscosity grades and packaging formats was cross-checked against top-down refinery output and import trade data for Group III base stocks.
Forecast inputs encompassed vehicle production trajectories across passenger, commercial, and two-wheeler segments, ethanol blending roadmap implementation pacing, and BS VI Stage II emission compliance timelines. Segmentation modeling spanned product chemistry tier, end-user procurement authority, viscosity specification, and packaging format across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating fleet consolidation rates and synthetic-grade penetration assumptions. Industry-specific inputs included OEM factory-fill specification shifts and additive treat rate requirements for low-viscosity operation.
Stress conditions across crude price volatility, Middle Eastern base stock supply disruptions, and BS VII anticipation freeze scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet operator consolidation pacing and ethanol blend penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Camless Engine Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Automotive Tuner Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Global Industrial Engine Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Europe Hill-Start Assist System Market