
 Transmission Fluids Market | 2026-2036
Transmission Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Fluids Market Intelligence
China's additive blending capacity expansion is reshaping regional supply dynamics for transmission fluids. ExxonMobil Corporation leverages its integrated base oil and additive technology platforms to sustain formulation leadership across Asia-Pacific. Shell plc anchors its position through backward integration into Group III+ base stocks, while FUCHS SE specializes in factory-fill partnerships with German premium automakers.
Transmission fluids are formulated lubricants comprising base oils combined with additive packages containing friction modifiers, anti-wear agents, and oxidation inhibitors, engineered to transfer power, cool components, and synchronize gear engagement in automatic, manual, and dual-clutch transmission architectures. Synthetic base oil formulations command premium positioning due to their thermal stability and extended service intervals under severe-duty cycles. Automatic transmission fluids occupy the largest volume pool given the technology's dominance in passenger vehicles, while dual-clutch transmission fluids represent the fastest-growing category as wet-clutch designs proliferate in European and Chinese light-vehicle segments.
The EPA regulates fuel economy and emissions standards that directly influence OEM transmission fluid specifications, while REACH in Europe restricts certain chemistries within additive packages, compelling reformulation investments. China's MIIT enforces domestic vehicle fuel consumption limits that accelerate adoption of lower-viscosity synthetic fluids. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate specification fragmentation and align R&D portfolios accordingly.
Market Dynamics
Dual-clutch transmission proliferation in Chinese and European light-vehicle manufacturing is compressing formulation development cycles, forcing additive suppliers to synchronize R&D timelines with OEM platform launches rather than traditional aftermarket replacement schedules.
Growth Catalysts
- MIIT fuel consumption limits:China's domestic vehicle efficiency mandates accelerate factory-fill specification upgrades to lower-viscosity synthetic chemistries, expanding addressable volume for premium base oil producers.
- Wet-clutch architecture proliferation:European premium automakers specify dedicated dual-clutch transmission fluids with enhanced friction durability, creating specification tier differentiation beyond conventional ATF categories.
- Commercial fleet TCO optimization:North American heavy-duty operators extend drain intervals through condition-based monitoring, directly consuming higher-performance synthetic formulations.
Market Restraints
- Group III+ base stock supply concentration:Asian refinery capacity additions lag formulation demand growth, creating input cost volatility for independent blenders without captive supply.
- REACH additive chemistry restrictions:ECHA-mandated substance evaluations force reformulation of friction modifier packages, extending validation timelines for European market access.
- Electrification substitution trajectory:Battery electric vehicle powertrain architectures eliminate multi-speed transmissions entirely, eroding long-term fluid demand in passenger vehicle segments.
Strategic Opportunities
- India commercial vehicle upfitting:Domestic logistics fleet modernization creates first-mover positioning for synthetic ATF suppliers ahead of BIS specification harmonization.
- Service contract bundling:OEM authorized workshop networks capture recurring revenue streams through captive fluid subscription models tied to warranty maintenance.
- Carbon border adjustment alignment:EU Green Deal compliance requirements favor low-carbon-intensity base oil sourcing, rewarding producers with integrated renewable feedstock capabilities.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in tribology and additive synergy optimization concentrates within incumbent suppliers, constraining new entrant technical staffing.
- OEM specification certification timelines:Factory-fill approval processes require 24-36 month validation cycles, locking out reformulated products from high-margin original equipment channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Fluids Market |
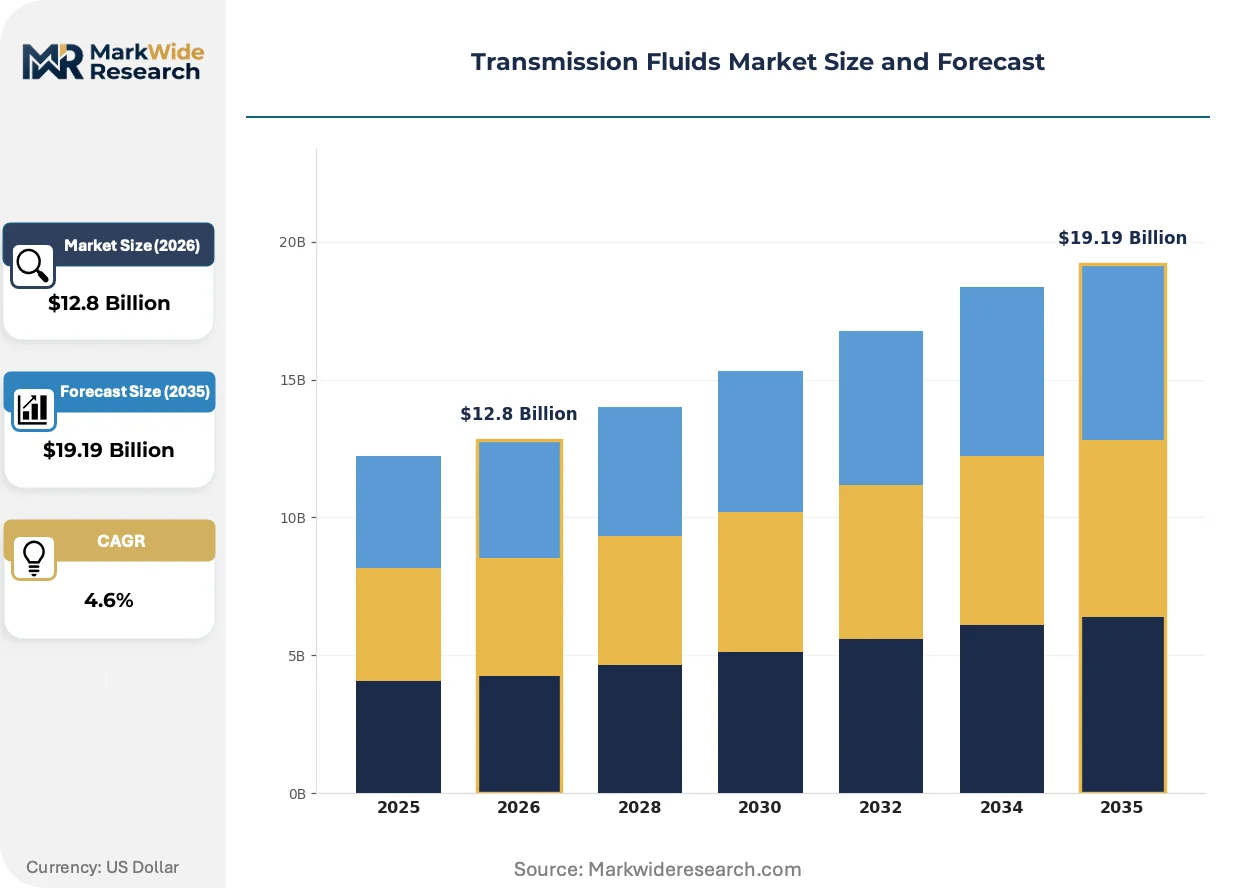
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transmission Fluids, Manual Transmission Fluids, Continuously Variable Transmission Fluids, Dual-Clutch Transmission Fluids Base Oil: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Oil Additive Package: Friction Modifiers, Anti-Wear Additives, Detergents, Oxidation Inhibitors End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Machinery |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, BP plc, TotalEnergies SE, FUCHS SE, Valvoline Inc., The Lubrizol Corporation, LUKOIL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Fluids Market Strategic Shifts & Innovations
Formulation science is pivoting toward thermal stability optimization as transmission hardware operates at elevated temperatures under downsized engine torque loads, compressing the performance gap between mineral and synthetic base stocks.
Ultra-low-viscosity 0W-8 and 0W-12 transmission fluid grades are rendering obsolete conventional 5W-30 and 10W-40 formulations in new vehicle platforms. German and Japanese OEMs specify these chemistries for factory-fill to maximize fuel economy test cycle performance. The shift is rendering obsolete legacy blending infrastructure designed for higher-viscosity base stock handling.
REACH authorization requirements for boron-containing friction modifiers are compelling additive package redesigns across European supply chains. ECHA substance evaluation timelines compress reformulation windows, forcing simultaneous chemistry substitution and performance validation. Wet-clutch transmission fluid categories face the most acute compliance pressure given their dependence on boron-based anti-shudder additives.
Fleet maintenance departments are consolidating supplier relationships through direct sourcing agreements with additive manufacturers, bypassing traditional lubricant distributors. Large North American commercial operators negotiate volume commitments in exchange for technical service integration and used-fluid analysis programs. This channel compression is most visible in long-haul trucking segments where total fluid cost visibility drives procurement centralization.
Transmission Fluids Market Segmentation
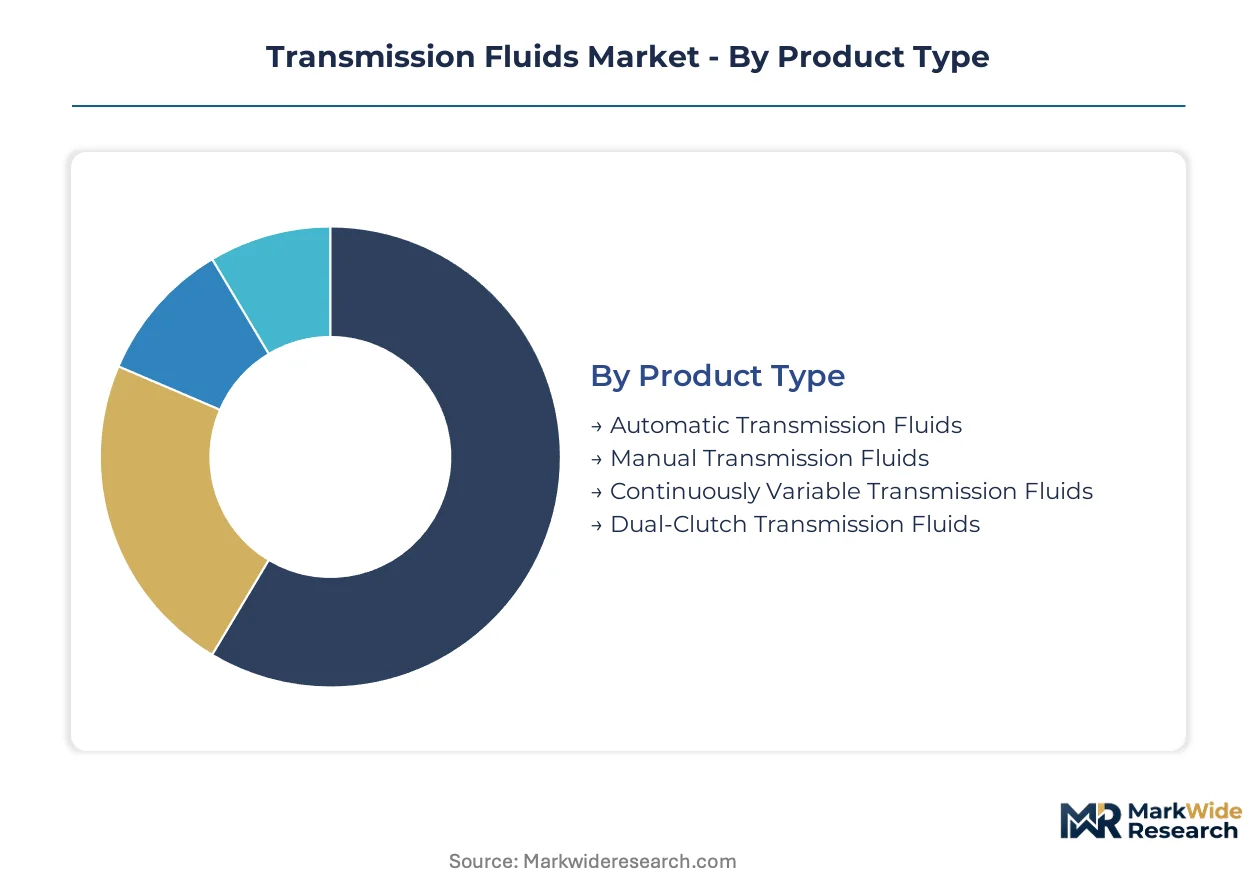
Transmission fluid specifications diverge sharply across powertrain architectures, with each transmission type demanding distinct friction profiles and thermal stability thresholds. Base oil selection and additive chemistry combine to create formulation tiers that align with OEM warranty requirements and fleet total cost of ownership targets.
Product Type:
Use-case spectrum spans conventional torque-converter automatics through emerging wet-clutch architectures, with each application imposing unique shear stability and anti-shudder demands.
- Automatic Transmission Fluids:Formulated for torque-converter and planetary gearset lubrication with emphasis on oxidation resistance and seal compatibility. Demand concentrates in US passenger vehicle aftermarket channels where extended drain intervals drive synthetic conversion.
- Dual-Clutch Transmission Fluids:Engineered for wet-clutch engagement dynamics requiring precise friction coefficient control across temperature cycles. Chinese and German OEM factory-fill specifications are expanding most quickly as dual-clutch production scales.
- Manual Transmission Fluids:Simpler additive packages prioritize gear protection and synchronizer compatibility over friction modification. Heavy-duty commercial applications in India sustain volume despite passenger vehicle decline.
- Continuously Variable Transmission Fluids:Specialized formulations manage metal-to-metal contact in pulley-sheave interfaces with extreme pressure additives. Japanese OEM captive specifications limit third-party blender access.
The dominant share belongs to Automatic Transmission Fluids, while Dual-Clutch Transmission Fluids are closing the gap fastest.
Base Oil:
Cost tier stratification separates commodity mineral formulations from premium synthetic chemistries required by severe-service specifications.
- Synthetic Oil:Group III+ and PAO base stocks deliver thermal oxidative stability enabling extended drain intervals. European REACH compliance pressures and US EPA fuel economy standards accelerate OEM specification migration.
- Mineral Oil:Solvent-refined Group I and II stocks serve price-sensitive aftermarket and legacy vehicle parc. Supply concentration in Asian refining corridors creates cost volatility for independent blenders.
- Semi-Synthetic Oil:Blended formulations balance performance upgrade with cost containment for mid-tier service channels. Latin American and Southeast Asian markets show resilient demand.
- Bio-Based Oil:Renewable feedstock-derived esters target carbon intensity reduction for EU Green Deal alignment. Limited scale and oxidation stability constraints restrict application to niche premium segments.
Synthetic Oil commands the value pool, with Bio-Based Oil gaining regulatory tailwinds despite volume constraints.
Additive Package:
Margin concentration flows to friction modifier and anti-wear chemistries where patent-protected molecular architectures create supplier stickiness.
- Friction Modifiers:Organic molybdenum complexes and boron-containing compounds manage clutch engagement smoothness. ECHA substance evaluation timelines are compressing reformulation windows for European market access.
- Anti-Wear Additives:Zinc dialkyldithiophosphate (ZDDP) and ashless alternatives protect gear surfaces under boundary lubrication. Heavy-duty machinery specifications in mining and construction sustain phosphate-based demand.
- Detergents:Calcium and magnesium sulfonate packages control deposit formation in high-temperature transmission environments. Factory-fill specifications demand ultra-clean performance for warranty compliance.
- Oxidation Inhibitors:Hindered phenols and amine antioxidants extend fluid service life under thermal stress. Commercial fleet condition-based monitoring programs prioritize inhibitor retention metrics.
Friction Modifiers extract premium pricing, though Anti-Wear Additives retain volume leadership across installed base.
End User:
Customer type segmentation reveals divergent procurement patterns between OEM factory-fill negotiations and fragmented aftermarket service decisions.
- Passenger Vehicles:OEM specification certification governs factory-fill access, while aftermarket channels compete on price and brand recognition. China's domestic automaker expansion is reshaping regional volume distribution.
- Commercial Vehicles:Fleet procurement centralization favors direct additive manufacturer relationships with technical service bundling. North American long-haul operators lead synthetic conversion for extended drain interval economics.
- Heavy-Duty Machinery:Mining, construction, and agricultural equipment impose severe-duty thermal and contamination loads. OEM captive service networks limit independent lubricant penetration.
- Two-Wheelers:Wet-clutch motorcycle transmissions require friction-modified formulations distinct from automotive ATF. Southeast Asian production hubs concentrate demand for economy-tier mineral oil products.
Passenger Vehicles generate absolute volume, while Commercial Vehicles offer superior margin capture through technical service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT fuel consumption limits in China are compressing formulation development cycles and accelerating factory-fill specification upgrades across the Asia-Pacific corridor. OEM procurement decisions in this market cascade into regional supply chain reconfigurations.
China
Domestic automakers are scaling dual-clutch transmission production at wet-clutch assembly plants in Shanghai and Chongqing. MIIT enforces progressively tighter vehicle efficiency mandates that compel lower-viscosity synthetic fluid adoption. The Yangtze River Delta additive blending capacity expansion is displacing imported formulation volumes.
United States
Commercial vehicle fleet operators extend drain intervals through condition-based monitoring systems to reduce total cost of ownership. EPA tightened fuel economy standards compel OEMs to specify ultra-low-viscosity chemistries for factory-fill. Detroit-area transmission engineering centers coordinate specification validation with additive suppliers.
Germany
Premium automakers specify dedicated dual-clutch transmission fluids with enhanced friction durability for wet-clutch architectures. REACH authorization requirements for boron-containing friction modifiers force additive package redesigns across European supply chains. Baden-Württemberg formulation laboratories concentrate OEM certification activity.
India
Domestic logistics fleet modernization creates first-mover positioning for synthetic ATF suppliers ahead of BIS specification harmonization. The PLI scheme for automotive components indirectly channels investment toward transmission hardware localization. Maharashtra and Gujarat manufacturing corridors concentrate commercial vehicle assembly.
Japan
Japanese OEM captive specifications for continuously variable transmission fluids limit third-party blender access to factory-fill channels. METI efficiency regulations align with corporate average fuel economy targets that favor lower-viscosity chemistries. Kanto region engineering headquarters coordinate tribology research with domestic additive suppliers.
Transmission Fluids Market Key Industry Players
Capability concentration sits with integrated base oil and additive technology platforms; scale advantage sits with global refining networks with captive Group III+ production. The market structure tiers between backward-integrated majors with in-house additive synthesis and independent blenders sourcing from merchant markets. Strategic archetypes include formulation specialists with OEM factory-fill partnerships, regional blenders with distribution density, and additive technology licensors. Dominant competitive moves encompass backward integration into base stock production and strategic partnerships for wet-clutch friction modifier development.
Among integrated majors, ExxonMobil Corporation and Shell plc occupy positions anchored by upstream control over base oil supply chains. FUCHS SE exemplifies the specialist archetype with concentrated factory-fill relationships. These entities represent the competitive spectrum from scale-driven refining integration to specification-certified formulation expertise.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP plc |
| TotalEnergies SE |
| FUCHS SE |
| Valvoline Inc. |
| The Lubrizol Corporation |
| LUKOIL |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container freight corridors transmit cost volatility directly into European blending operations, compressing margins for independent formulators while rewarding integrated majors with captive base oil supply. This logistics-cost asymmetry stratifies pricing power across synthetic and mineral oil tiers, with Group III+ producers capturing premium positioning as Asian refinery capacity lags formulation demand growth.
Pricing Analysis
Geographic price spreads between Asia-Pacific and European markets exceed transport-cost differentials, reflecting supply concentration effects and REACH compliance premiums. Contract-based long-term offtake agreements dominate factory-fill channels, while aftermarket transactions cluster around spot-indexed mineral oil benchmarks. Price differentiation rests on certification grade and volume scale, with OEM-approved synthetic formulations commanding substantial premiums over generic alternatives. Cost compression in economy-tier mineral products is intensifying as Chinese additive blending capacity displaces imported volumes, rendering North American fleet operators the least price-sensitive segment due to total cost of ownership optimization priorities.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated refiners in South Korea, Singapore, and the US Gulf Coast, where Group III+ hydrocracker capacity anchors synthetic base oil supply. Formulation draws from boron-containing friction modifiers, hindered phenol oxidation inhibitors, and Group II mineral stocks as primary inputs. Single-source vulnerability concentrates in wet-clutch additive packages, where ECHA substance evaluations threaten supply continuity for European-accessible friction modifier chemistries. Distribution runs through authorized OEM workshop networks for factory-fill volumes, while commercial fleet direct sourcing agreements bypass traditional lubricant distributors in North American heavy-duty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across dual-clutch, wet-clutch, and electrification-adjacent architectures fragments demand into addressable niches, rewarding specialized formulation expertise over commodity scale. This demand-side shift creates entry points for additive technology licensors and regional blenders with OEM certification capabilities.
For Market Incumbents: Build specification-certification moats through accelerated factory-fill validation timelines with Chinese and German OEMs. Deepen backward integration into Group III+ base stock production to insulate margin structures from Asian refinery supply volatility. Prioritize wet-clutch friction modifier R&D partnerships ahead of REACH-authorized chemistry substitutions, locking out reformulated competitors from premium European channels. For New Entrants and Emerging Players: India's commercial vehicle synthetic ATF segment, ahead of BIS specification harmonization, represents the most penetrable entry point for mid-tier suppliers with technical service bundling capabilities. Bio-based oil formulations for EU Green Deal compliance offer regulatory-tailwind positioning despite volume constraints. Target direct procurement relationships with large fleet operators, bypassing distributor markups through used-fluid analysis program integration. For Investors and Strategic Acquirers: Additive technology specialists with patent-protected friction modifier architectures and established OEM tribology partnerships present the highest-value acquisition targets within a five-to-ten-year electrification transition window. Monitor battery electric vehicle powertrain adoption rates in passenger vehicle segments as the critical demand erosion signal, with commercial vehicle electrification lag providing extended cash flow visibility for heavy-duty formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Stocks | Captive supply insulates margin structures from Asian refinery capacity constraints and price volatility. |
| Wet-Clutch Friction Modifier R&D Partnership | Boron-free chemistry development secures REACH compliance ahead of ECHA authorization timelines. |
| Factory-Fill Certification Acceleration | Compressed 24-36 month OEM validation cycles lock out reformulated competitors from high-margin channels. |
| Fleet Direct Sourcing Agreement Expansion | Condition-based monitoring integration captures recurring revenue from North American commercial operators. |
| Bio-Based Oil Formulation Scale-Up | Renewable feedstock capabilities align with EU Green Deal carbon border adjustment requirements. |
Research Approach
The analysis maps automatic transmission fluids, dual-clutch transmission fluids, manual transmission fluids, and continuously variable transmission fluids, each validated through plant managers at additive blending facilities, procurement leads at OEM transmission engineering centers, and aftermarket distribution channel partners. Primary interviews with technical R&D directors and commercial fleet maintenance supervisors combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up volume triangulation across base oil grades and additive package categories reconciled with top-down market sizing.
Assumptions held fixed include MIIT fuel consumption limit stringency, EPA fuel economy standard trajectories, and REACH authorization timelines for boron-containing chemistries, while variables included electrification substitution rates and Asian refinery capacity expansion schedules. Segmentation dimensions modeled encompass transmission architecture type, base oil grade tier, additive package chemistry, end-use industry, and regional production hub clustering. CAGRs derived from regression analysis against historical specification upgrade cycles and OEM platform launch schedules, with dual-clutch transmission penetration rates and synthetic conversion trends as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, container freight rates, or automotive production volumes would shift the trajectory. Quarterly review of MIIT efficiency mandate updates, ECHA substance evaluation announcements, and OEM electrification platform commitments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Fuel Injection Systems Market
Powertrain
Global Automotive Pumps Market
Powertrain
Automotive Crankshaft Market
Powertrain
Engine Starter Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Crankshaft Oil Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
High Speed Engine Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market