
 Liver Function Tests Market | 2026-2036
Liver Function Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Function Tests Market Outlook
Clinical laboratory technologist shortages across developed healthcare systems is reorganizing how diagnostic networks deploy liver function testing capacity. Abbott Laboratories leverages its automated immunoassay platform to sustain high-throughput operations in hospital core labs. Thermo Fisher Scientific anchors the research-grade segment with mass spectrometry workflows that serve academic medical centers. Siemens Healthcare GmbH competes through integrated chemistry analyzers that consolidate liver panels with broader metabolic testing.
Liver function tests measure serum enzyme levels, bilirubin concentration, and synthetic protein markers to assess hepatic injury, cholestasis, and metabolic capacity; enzymatic assays remain the dominant analytical method due to cost efficiency and CLIA-waived compatibility for moderate-complexity labs. The test type dimension shows ALT and AST panels occupying the highest volume tier, while alkaline phosphatase gains share in cholestatic disease monitoring. Automated testing dominates the delivery mode structure, though point-of-care formats are capturing emergency department and ambulatory surgery volumes where turnaround time drives clinical decisions.
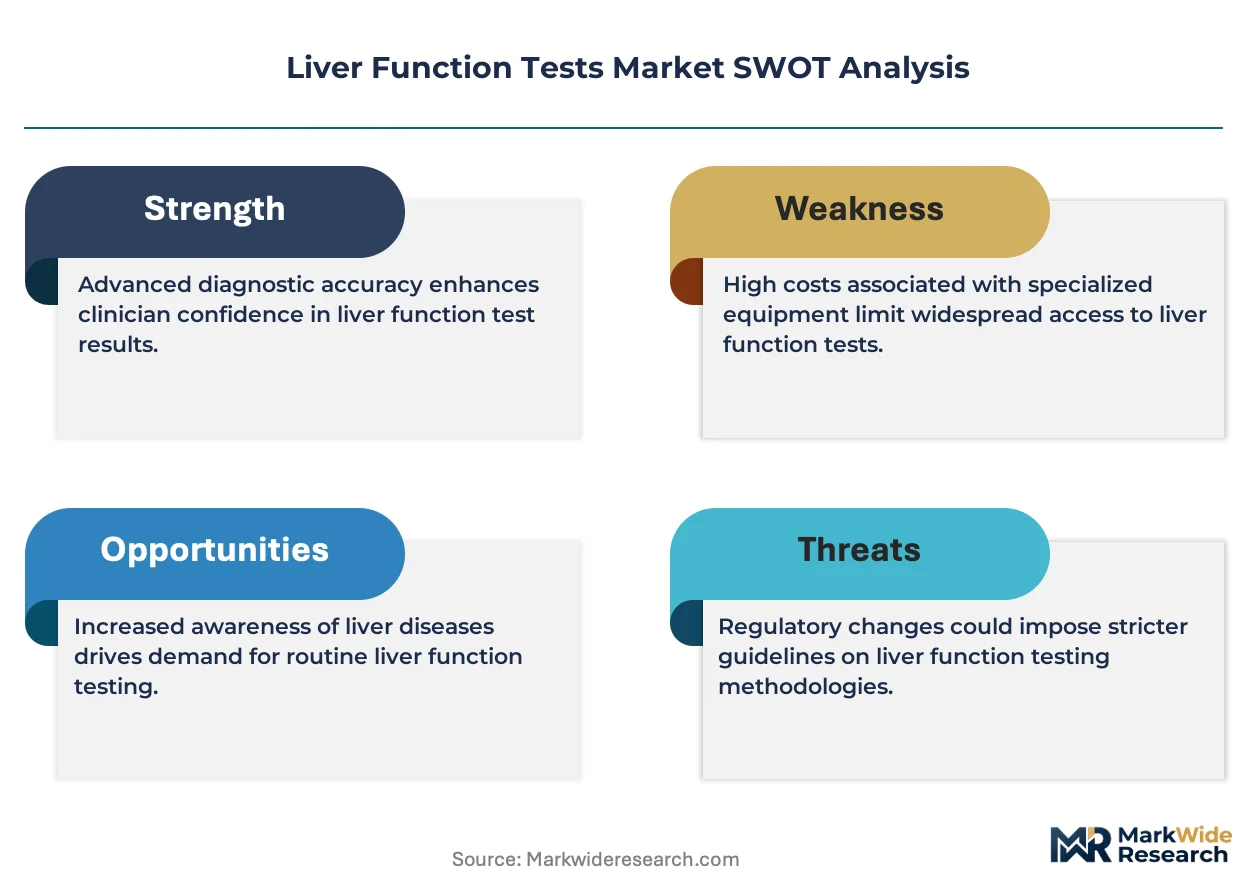
FDA 510(k) pathways and CLIA complexity categorization shape product development priorities for manufacturers seeking US market access, while EMA IVDR transition timelines are forcing European suppliers to revalidate legacy liver assays. The central bank of regulatory pressure sits with reimbursement coding, where CMS decisions on CPT bundling directly determine commercial viability of expanded liver panels. Stakeholders must monitor how laboratory benefit managers reshape preferred vendor contracts as health systems consolidate purchasing authority.
Market Dynamics
Automated enzymatic assay platforms are compressing turnaround times in hospital core laboratories while CLIA-waived point-of-care formats capture emergency department volumes, fundamentally restructuring how liver function testing capacity deploys across diagnostic networks.
Growth Catalysts
- Non-alcoholic fatty liver disease epidemiology:Rising NAFLD caseloads across aging populations in the United States and Germany are expanding routine screening protocols in primary care networks.
- FDA 510(k) pathway efficiency:Compressed clearance timelines for multiplex liver panels are accelerating commercialization schedules for diagnostic manufacturers seeking outpatient laboratory access.
- Medicare reimbursement favorability:CMS outpatient diagnostic policies in the United States are channeling hepatitis and cirrhosis monitoring volumes toward hospital-affiliated laboratories.
Market Restraints
- Clinical laboratory technologist shortages:Workforce gaps across the United States, United Kingdom, and Japan are constraining throughput expansion even where instrument capacity exists.
- Reagent supply concentration:Specialized enzyme and antibody inputs for ALT/AST assays concentrate among a limited supplier base in Germany and Switzerland, creating vulnerability to batch variability.
- EMA IVDR transition friction:European manufacturers face revalidation costs and timeline compression for legacy liver assays under the In Vitro Diagnostic Regulation.
Strategic Opportunities
- Point-of-care format penetration:Emergency departments and ambulatory surgery centers in the United States are adopting cartridge-based liver panels where turnaround time determines admission decisions.
- Mass spectrometry workflow expansion:Academic medical centers are integrating research-grade metabolomic profiling with standard enzymatic panels for non-alcoholic steatohepatitis stratification.
- Laboratory benefit manager consolidation:Health system purchasing authority concentration creates preferred vendor contract opportunities for integrated chemistry analyzer suppliers.
Industry Challenges
- Multiplex assay development complexity:Simultaneous ALT, AST, alkaline phosphatase, and bilirubin quantification on single platforms demands extensive cross-reactivity validation.
- CLIA complexity categorization navigation:Moderate-complexity laboratory certification requirements vary across United States state laboratory licensure boards, complicating national rollout strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Function Tests Market |
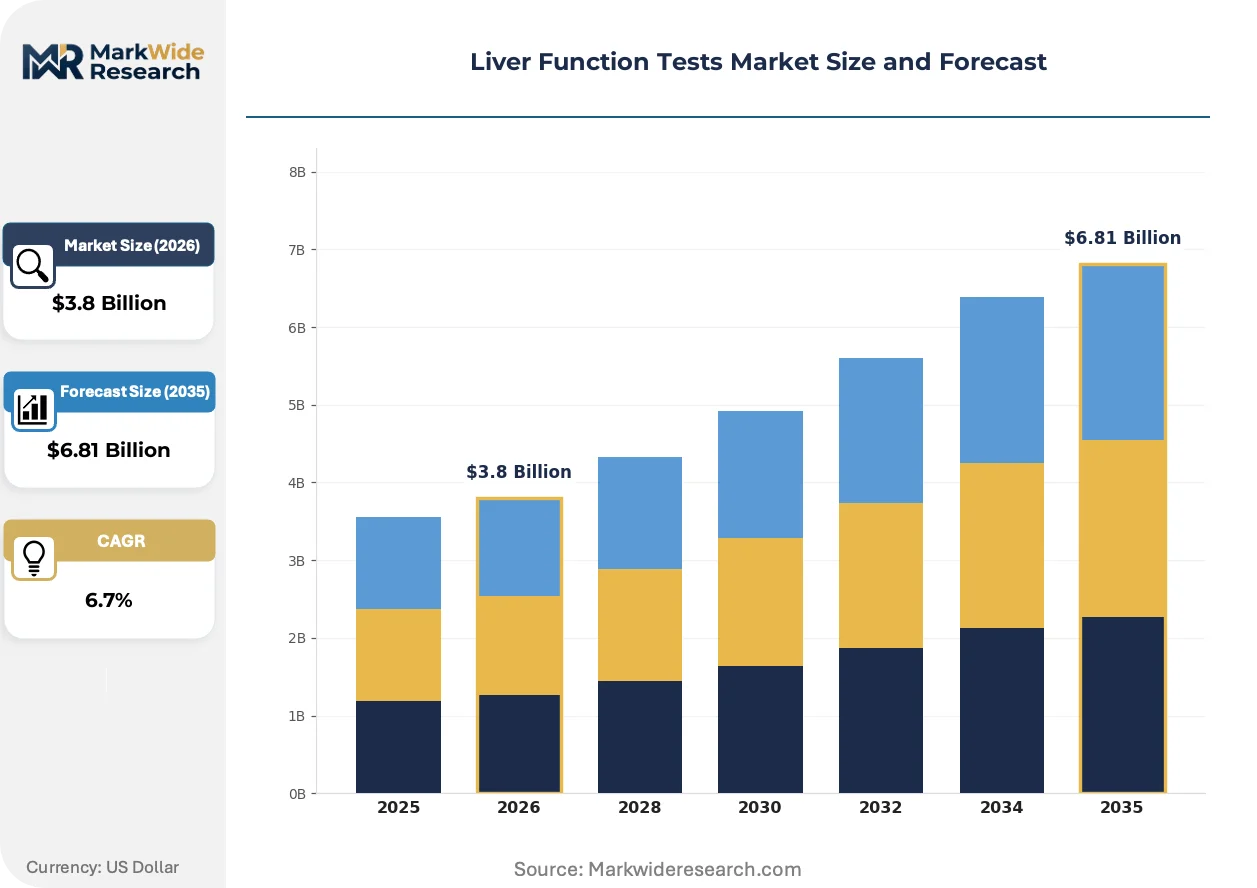
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Alanine Aminotransferase, Aspartate Aminotransferase, Alkaline Phosphatase, Bilirubin End User: Clinics, Hospitals, Diagnostic Laboratories, Research Institutions Delivery Mode: Manual Testing, Automated Testing, Point of Care Testing, Home Testing Technology: Enzymatic Assay, Immunoassay, Mass Spectrometry, Optical Analysis |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific Inc., Randox Laboratories Ltd, Laboratory Corporation of America Holdings, Horiba Medical, Siemens Healthcare GmbH, Quest Diagnostics, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Function Tests Market Strategic Shifts
Digital connectivity and artificial intelligence are penetrating liver function testing workflows, compressing interpretation cycles and enabling predictive analytics for disease progression monitoring.
Multiplex immunoassay technology is decomposing the traditional single-analyte testing sequence in hospital laboratories. Core labs in the United States and Germany are adopting consolidated panels that simultaneously quantify ALT, AST, alkaline phosphatase, and bilirubin from single serum samples. This convergence is decomposing the historical separation between hepatic injury, cholestasis, and synthetic function testing into unified diagnostic protocols.
EMA IVDR implementation timelines are forcing European manufacturers to revalidate legacy liver assays under stricter clinical evidence requirements. Diagnostic suppliers serving France, Germany, and Italy face compressed transition windows for technical documentation and post-market surveillance systems. Mid-sized European assay developers are responding by narrowing product portfolios to focus resources on high-volume ALT and AST panels.
Health system laboratory consolidation is concentrating purchasing authority among integrated delivery networks in the United States. Independent reference laboratories are losing preferred vendor status as hospital systems centralize contracts with automated chemistry analyzer suppliers. This concentration is most visible in Texas, California, and Florida, where multi-hospital networks are standardizing on single-platform liver panel workflows.
Liver Function Tests Market Segmentation
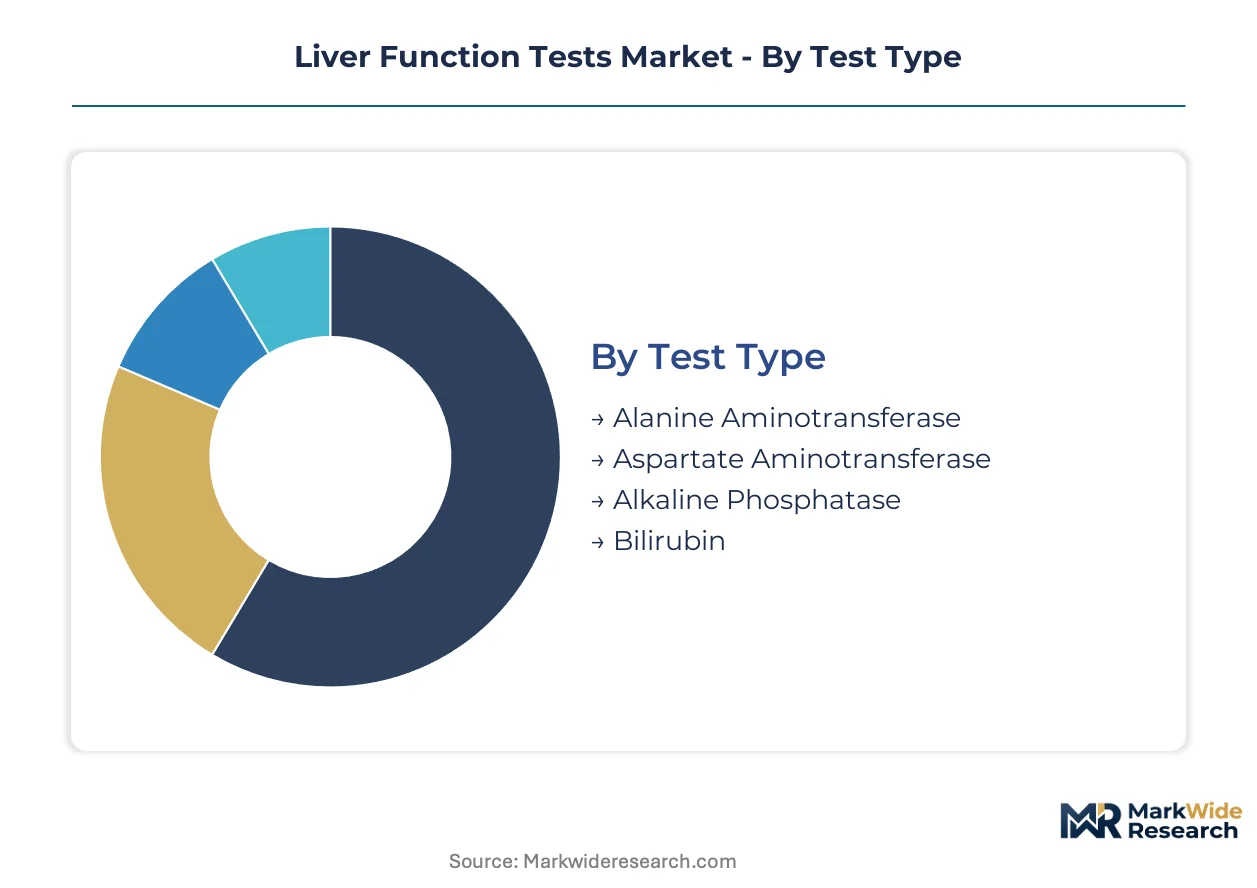
Liver function testing markets fragment across four analytical dimensions that determine procurement patterns and margin structures. Test type and delivery mode configurations dominate purchasing decisions, while technology selection separates hospital core laboratories from research-grade installations.
Test Type:
ALT and AST panels concentrate in domestic hospital networks managing hepatitis surveillance, while alkaline phosphatase demand spreads across export-oriented diagnostic manufacturers serving cholestatic disease protocols.
- Alanine Aminotransferase:This enzyme marker quantifies hepatocellular injury through serum catalytic concentration measurement. United States hospital laboratories deploy ALT as the primary screening tool for non-alcoholic fatty liver disease progression monitoring in Medicare-eligible populations. ALT commands the established base. The steepest expansion runs through alkaline phosphatase.
- Aspartate Aminotransferase:AST assays detect mitochondrial enzyme release from damaged hepatocytes and cardiac myocytes. German diagnostic manufacturers prioritize AST multiplexing for European hospital networks confronting EMA IVDR revalidation timelines. AST volumes concentrate in acute liver failure triage protocols.
- Alkaline Phosphatase:This cholestatic indicator measures biliary tract obstruction and bone metabolism disorders. Demand concentrates in ambulatory surgery centers across Florida and Texas where rapid turnaround drives cartridge-based adoption.
- Bilirubin:Direct and indirect bilirubin quantification supports neonatal jaundice protocols and hemolytic disorder assessment. Academic medical centers in California integrate bilirubin panels with mass spectrometry metabolomic workflows.
ALT and AST panels anchor routine screening volumes. Alkaline phosphatase gains share fastest in cholestatic monitoring applications.
End User:
Hospital laboratories absorb premium automated platforms while clinics and diagnostic laboratories fragment across CLIA-waived and moderate-complexity certification tiers.
- Clinics:Primary care networks in the United States deploy CLIA-waived point-of-care liver panels for hepatitis C screening expansion under Medicare reimbursement policies.
- Hospitals:Integrated delivery networks standardize on automated chemistry analyzers that consolidate liver panels with renal and metabolic testing. Texas and California health systems concentrate purchasing authority among single-platform vendors.
- Diagnostic Laboratories:Independent reference laboratories face contract consolidation pressure as hospital-affiliated labs capture preferred vendor status. Workforce shortages constrain throughput expansion despite instrument capacity.
- Research Institutions:Academic medical centers in Germany and the United States anchor mass spectrometry adoption for non-alcoholic steatohepatitis stratification studies. EMA IVDR documentation requirements compress European supplier margins.
Hospitals command the established base. The steepest expansion trajectory runs through clinics adopting waived testing formats.
Delivery Mode:
Automated platforms dominate high-volume hospital contracts while point-of-care formats penetrate emergency departments where turnaround time determines admission decisions.
- Manual Testing:Legacy benchtop enzymatic methods persist in resource-constrained settings and specialized reference applications requiring custom protocol modification.
- Automated Testing:Random-access chemistry analyzers process ALT, AST, alkaline phosphatase, and bilirubin from single serum samples. United States hospital core laboratories compress turnaround times through automated enzymatic assay platforms.
- Point of Care Testing:Cartridge-based liver panels capture emergency department volumes across the United States where thirty-minute turnaround supports disposition decisions. CLIA-waived certification enables deployment in moderate-complexity laboratories.
- Home Testing:Direct-to-consumer liver panel kits remain limited by FDA 510(k) pathway complexity and interpretive support requirements. Regulatory friction constrains commercialization schedules.
Automated testing commands the established base. The steepest expansion runs through point-of-care formats.
Technology:
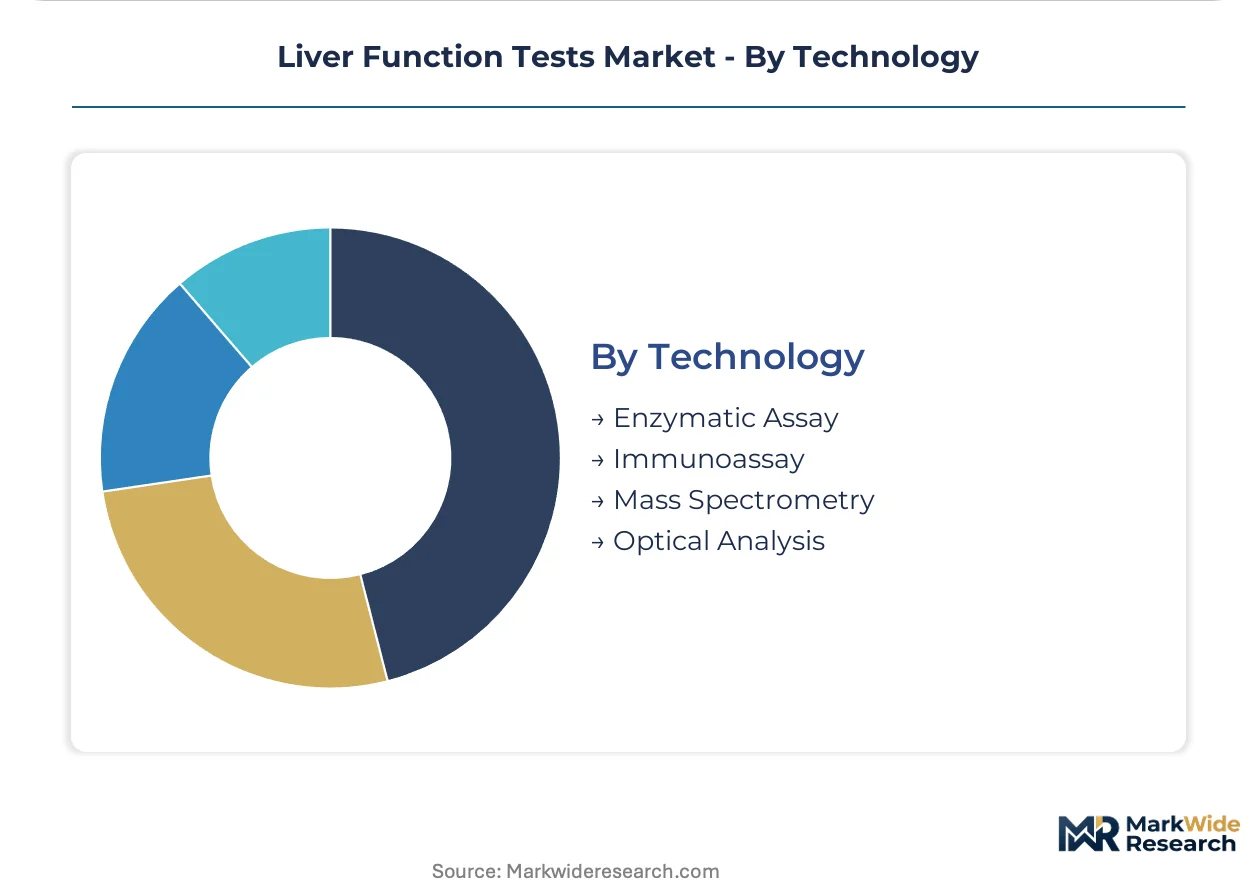
Enzymatic assays anchor cost-efficient high-throughput operations while mass spectrometry concentrates in research institutions and academic medical centers.
- Enzymatic Assay:Spectrophotometric measurement of enzyme catalytic activity dominates routine liver function testing. CLIA-waived compatibility and reagent cost efficiency sustain enzymatic method dominance in United States moderate-complexity laboratories.
- Immunoassay:Antibody-based quantification supports protein synthesis markers and specialized hepatic panels. Automated immunoassay platforms integrate with chemistry analyzers for consolidated metabolic testing workflows.
- Mass Spectrometry:Research-grade metabolomic profiling enables non-alcoholic steatohepatitis stratification beyond standard enzymatic panels. German and United States academic centers anchor mass spectrometry adoption.
- Optical Analysis:Biosensor and fluorescence-based methods penetrate point-of-care formats where miniaturization and rapid readout override sensitivity requirements.
Enzymatic assays command the established base. The steepest expansion runs through mass spectrometry in research applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratories in the United States deploy automated enzymatic platforms at scale, while German manufacturers navigate stricter EMA IVDR documentation requirements, and Japanese health systems grapple with technologist shortages that constrain throughput expansion despite available instrument capacity.
United States
Medicare reimbursement policies favor outpatient diagnostic testing, channeling hepatitis and cirrhosis monitoring volumes toward hospital-affiliated laboratories. FDA 510(k) pathways compress clearance timelines for multiplex liver panels, accelerating commercialization for diagnostic manufacturers. Texas and California health systems concentrate purchasing authority, standardizing on single-platform liver panel workflows across multi-hospital networks.
Germany
German diagnostic manufacturers prioritize AST multiplexing for European hospital networks confronting EMA IVDR revalidation timelines. The country's national pharmaceutical regulator enforces stricter clinical evidence requirements under In Vitro Diagnostic Regulation implementation. Bavaria and North Rhine-Westphalia anchor production clusters where mid-sized assay developers narrow portfolios to focus resources on high-volume ALT and AST panels.
Japan
Japan's aging population expands routine screening protocols for non-alcoholic fatty liver disease in primary care networks. The country's Ministry of Economy, Trade and Industry oversees industrial standards coordination for diagnostic equipment. Tokyo and Osaka metropolitan areas face acute clinical laboratory technologist shortages that constrain throughput expansion even where automated instrument capacity exists.
United Kingdom
Workforce gaps across the United Kingdom constrain diagnostic network expansion despite government investment in hospital infrastructure. The country's national health service procurement frameworks reshape preferred vendor contracts as health systems consolidate purchasing authority. Greater London and the Midlands concentrate reference laboratory capacity, with independent labs losing contract status to hospital-affiliated operations.
Switzerland
Specialized enzyme and antibody inputs for ALT/AST assays concentrate among Swiss suppliers, creating vulnerability to batch variability in global supply chains. Swissmedic maintains stringent post-market surveillance requirements for diagnostic devices. Basel and Zurich anchor precision reagent manufacturing clusters serving automated chemistry analyzer producers across European markets.
Liver Function Tests Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in liver function testing, with consolidated purchasing authority among United States health systems favoring vendors with full-platform automation capabilities. Three archetypes populate the competitive terrain: multinational conglomerates with chemistry analyzer integration, mid-sized European assay specialists navigating regulatory transitions, and point-of-care format innovators targeting emergency department workflows. Dominant competitive moves include portfolio consolidation around multiplex panel development and strategic partnerships with laboratory benefit managers to secure preferred vendor status in contracting cycles.
Among diversified diagnostic conglomerates, Roche Diagnostics and Abbott Laboratories exemplify integrated platform strategies that consolidate liver panels with broader metabolic testing workflows. Siemens Healthcare GmbH occupies a position within the European hospital network segment, anchoring chemistry analyzer installations that serve high-throughput core laboratory operations. Thermo Fisher Scientific represents the research-grade archetype, with mass spectrometry workflows that academic medical centers deploy for non-alcoholic steatohepatitis stratification beyond standard enzymatic assays.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Randox Laboratories Ltd |
| Laboratory Corporation of America Holdings |
| Horiba Medical |
| Siemens Healthcare GmbH |
| Quest Diagnostics |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term preferred vendor contracts between United States health systems and automated chemistry analyzer suppliers lock in multi-year reagent supply access while compressing price visibility for independent diagnostic laboratories. This contract-structure pattern concentrates purchasing leverage among integrated delivery networks in Texas and California, forcing mid-sized assay developers toward spot-market reagent sales with thinner margins.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between hospital-affiliated laboratories and automated platform vendors, with pricing stratifying across premium, standard, and economy tiers based on test panel breadth and CLIA complexity certification. Price differentiation hinges on FDA 510(k) clearance status and volume scale commitments, with academic medical centers showing least price sensitivity for mass spectrometry workflows. Cost compression in point-of-care cartridge formats is intensifying because CLIA-waived certification requirements fragment manufacturing scale economies.
Supply Chain Analysis
Port congestion on trans-Atlantic trade lanes elevates inbound logistics costs for German and Swiss reagent suppliers serving United States hospital networks. Enzyme and antibody inputs for ALT/AST assays concentrate in Switzerland, Germany, and Austria, with production drawing from specialized fermentation and bioprocessing facilities. Single-source vulnerability runs through Swiss precision reagent manufacturers, while distribution feeds from regional distribution centers through laboratory benefit manager consolidated contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States integrated delivery networks as multi-hospital systems centralize laboratory purchasing authority, fragmenting contract access for independent reference laboratories and mid-sized European assay developers.
For Market Incumbents: Consolidate platform integration depth by embedding liver panels within broader metabolic testing workflows to defend against point-of-care format substitution. Secure preferred vendor status through strategic partnerships with laboratory benefit managers, while investing in CLIA-waived certification pathways to capture emergency department volumes. For New Entrants and Emerging Players: Differentiate on rapid-turnaround cartridge-based formats targeting ambulatory surgery centers in Florida and Texas where admission decisions hinge on thirty-minute liver panel results. Penetrate the clinic segment through Medicare-reimbursable hepatitis C screening protocols, deploying direct sales teams to bypass consolidated hospital procurement channels. For Investors and Strategic Acquirers: European mid-sized assay specialists with EMA IVDR-compliant ALT/AST panels represent compelling acquisition targets as regulatory transition costs compress standalone margins. Watch for inflection signals in CMS CPT bundling decisions that would reshape commercial viability of expanded liver panels.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Panel Development | Simultaneous ALT/AST/alkaline phosphatase/bilirubin quantification reduces per-test operational cost for hospital core laboratories. |
| CLIA-Waived Certification Pathway | FDA clearance for moderate-complexity laboratories unlocks emergency department and ambulatory surgery center deployment. |
| Laboratory Benefit Manager Partnership | Preferred vendor contracts with United States health systems secure multi-year reagent offtake commitments. |
| EMA IVDR Revalidation Investment | Technical documentation compliance preserves European market access for legacy liver assays under stricter clinical evidence requirements. |
| Mass Spectrometry Workflow Integration | Research-grade metabolomic profiling anchors academic medical center relationships for non-alcoholic steatohepatitis stratification studies. |
Study Parameters
Cross-validation between primary interviews with clinical laboratory directors, hospital procurement managers, diagnostic manufacturer regulatory affairs leads, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA IVDR technical documentation. Bottom-up test volume modeling triangulates with top-down market sizing across enzymatic assay, immunoassay, mass spectrometry, and optical analysis technology tiers.
Sensitivity analysis around NAFLD epidemiology trajectories and Medicare reimbursement policy scenarios shapes the analytical framework across the analysis window. Segmentation dimensions include test type, end user, delivery mode, and technology, with CAGRs derived from instrument placement trends and reagent consumption patterns. Forecast inputs incorporate CLIA complexity certification adoption curves and EMA IVDR transition timelines.
Decision-makers should treat outputs as directional under stable FDA clearance pathway efficiency and CMS outpatient diagnostic policy continuity; material deviation would warrant model refresh. Specific risk factors include clinical laboratory technologist shortage acceleration and reagent supply batch variability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
LDL Test Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
IVD Antibody Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
Respiratory Pathogen Testing Kits Market