
 Hand Tools and Woodworking Tools Market | 2026-2036
Hand Tools and Woodworking Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Tools and Woodworking Tools Market Intelligence
Modular tool-kit bundling is repositioning how professional craftsmen and DIY enthusiasts evaluate purchase decisions. Stanley Black & Decker leverages its multi-brand portfolio to control shelf presence across retail channels. Snap-On Incorporated dominates mobile distribution networks serving automotive-adjacent maintenance services. Techtronic Industries Co. Ltd anchors cordless technology leadership through sustained R&D investment in lithium-ion power platforms.
Hand tools and woodworking tools encompass manually operated or power-assisted implements fabricated from alloy steel, carbon steel, or carbide-tipped substrates, engineered for material removal, fastening, surface preparation, or dimensional measurement in wood-based fabrication. The primary commercial purpose spans rough dimensioning through fine finishing in solid wood, engineered panel, and composite substrate processing. Cordless technology leads value expansion as lithium-ion battery density improvements extend runtime for professional applications; saws and planers capture disproportionate margin pools due to blade replacement ecosystems and precision calibration requirements. Manual tools sustain volume dominance in emerging markets where electrification remains incomplete and price sensitivity governs procurement.
OSHA workplace safety standards and the EU Machinery Directive govern product certification, ergonomic design mandates, and acoustic emission limits that manufacturers must satisfy for market access. The EPA's volatile organic compound regulations for finishes and adhesives indirectly shape tool specification requirements in furniture manufacturing workflows. Stakeholders must monitor evolving battery transport classifications and end-of-life recycling obligations as cordless platforms expand their share of professional-grade portfolios.
Market Dynamics
Cordless lithium-ion platforms are compressing replacement cycles for professional-grade equipment while simultaneously elevating performance benchmarks that manual tool segments struggle to match.
Growth Catalysts
- EU Green Deal material traceability:European manufacturers must document sustainable sourcing for alloy steel and carbon steel inputs, accelerating investment in certified supply chains and premium-grade tooling.
- Residential construction precision requirements:North American builders demand tighter tolerances in engineered wood and composite fabrication, driving specification upgrades for joinery equipment and measurement tools.
- India's incomplete electrification:Manual hand tools sustain dominant volume share where power infrastructure gaps and price sensitivity govern procurement decisions among artisanal woodworkers.
Market Restraints
- Alloy steel price volatility:Input cost swings for high-carbon and carbide-tipped substrates compress margin predictability for mid-tier manufacturers without captive metallurgical supply.
- Germany's Black Forest cluster concentration:Artisanal and industrial producer convergence in this single woodworking hub creates geographic supply vulnerability and regional pricing pressure.
- Battery transport classification friction:Evolving lithium-ion shipping regulations under IATA and DOT frameworks complicate cross-border distribution for cordless platform manufacturers.
Strategic Opportunities
- Brazil's furniture export expansion:São Paulo and Minas Gerais wood processing corridors present underpenetrated demand for precision finishing equipment serving international contract manufacturers.
- Modular tool-kit bundling:Professional craftsmen and DIY enthusiasts increasingly evaluate integrated systems over single-item purchases, repositioning shelf presence strategies across retail channels.
- OSHA ergonomic design mandates:Workplace safety standards for vibration exposure and acoustic emission limits create premium positioning for compliant tool lines in professional maintenance services.
Industry Challenges
- Precision calibration technician scarcity:Saw and planer blade replacement ecosystems require skilled labor for accuracy maintenance, yet vocational training pipelines for metrology and alignment functions remain underdeveloped.
- End-of-life battery recycling obligations:Extended producer responsibility frameworks for cordless platforms impose reverse logistics complexity and capital intensity for collection infrastructure.
- CE marking compliance timelines:EU Machinery Directive certification processes for new power-assisted implements create launch delays and testing cost burdens for product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Tools and Woodworking Tools Market |
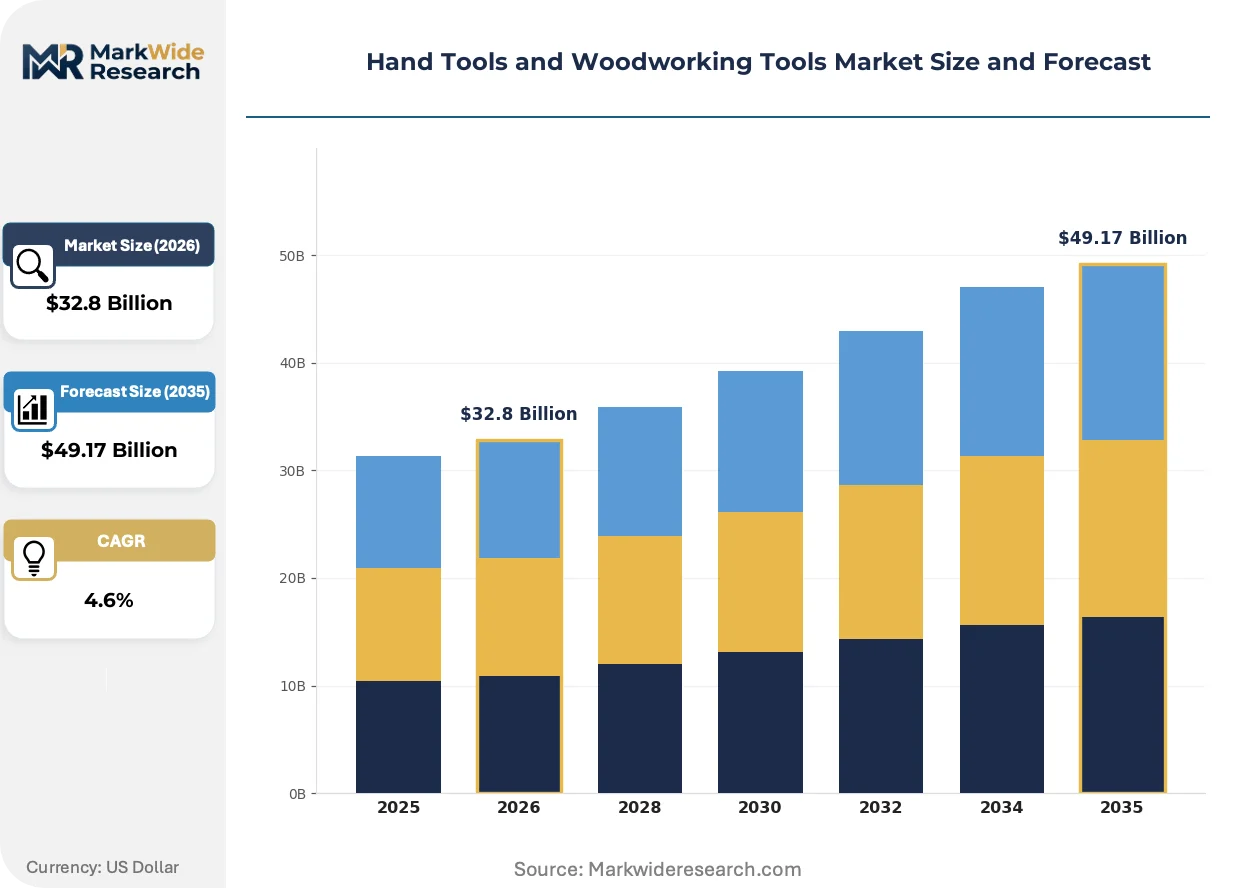
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screwdrivers, Hammers, Saws, Chisels, Planers, Measuring Tools Technology: Manual, Cordless, Pneumatic, Electric, Hydraulic Application: Carpentry, Cabinet Making, Joinery, Flooring Installation, Furniture Manufacturing, Door Fitting End User: Professional Craftsmen, DIY Enthusiasts, Carpentry Shops, Maintenance Services, Furniture Workshops |
| Companies Covered | Techtronic Industries Co. Ltd, Husqvarna, Stanley Black & Decker, Channellock, Hangzhou Great Star Industrial Co. Ltd., Apex Tool Group, Klein Tools, Estwing, Snap-On Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Tools and Woodworking Tools Market Strategic Shifts & Innovations
Active reshaping in this market centers on intelligent power management, regulatory-driven material accountability, and the unbundling of traditional distribution relationships between manufacturers and end-users.
Brushless motor controllers paired with higher-density lithium-ion cells are automating torque delivery and stall prevention in professional-grade cordless saws and planers. Cabinet shops and on-site construction crews in Germany and the United States are adopting these platforms at accelerated replacement cycles. This automation is compressing the performance gap between corded and cordless equipment while elevating runtime expectations that legacy nickel-cadmium platforms cannot satisfy.
REACH substance restrictions and the EU Green Deal's embodied carbon disclosure requirements are mandating supply chain documentation for alloy steel and carbide-tipped cutting edges. European manufacturers must now certify material provenance and end-of-life recyclability to maintain market access. Furniture manufacturing workflows in Italy and Poland are responding by specifying tools from suppliers with verified circular economy credentials, filtering procurement pools.
Mobile distribution networks serving automotive-adjacent maintenance services are fragmenting traditional wholesale relationships. Snap-On Incorporated's route-based model and similar direct-to-technician channels are displacing distributor intermediaries for high-frequency hand tool replacement. This pattern concentrates most visibly in North American fleet maintenance and industrial facility management contracts where downtime costs override brand loyalty.
Hand Tools and Woodworking Tools Market Segmentation
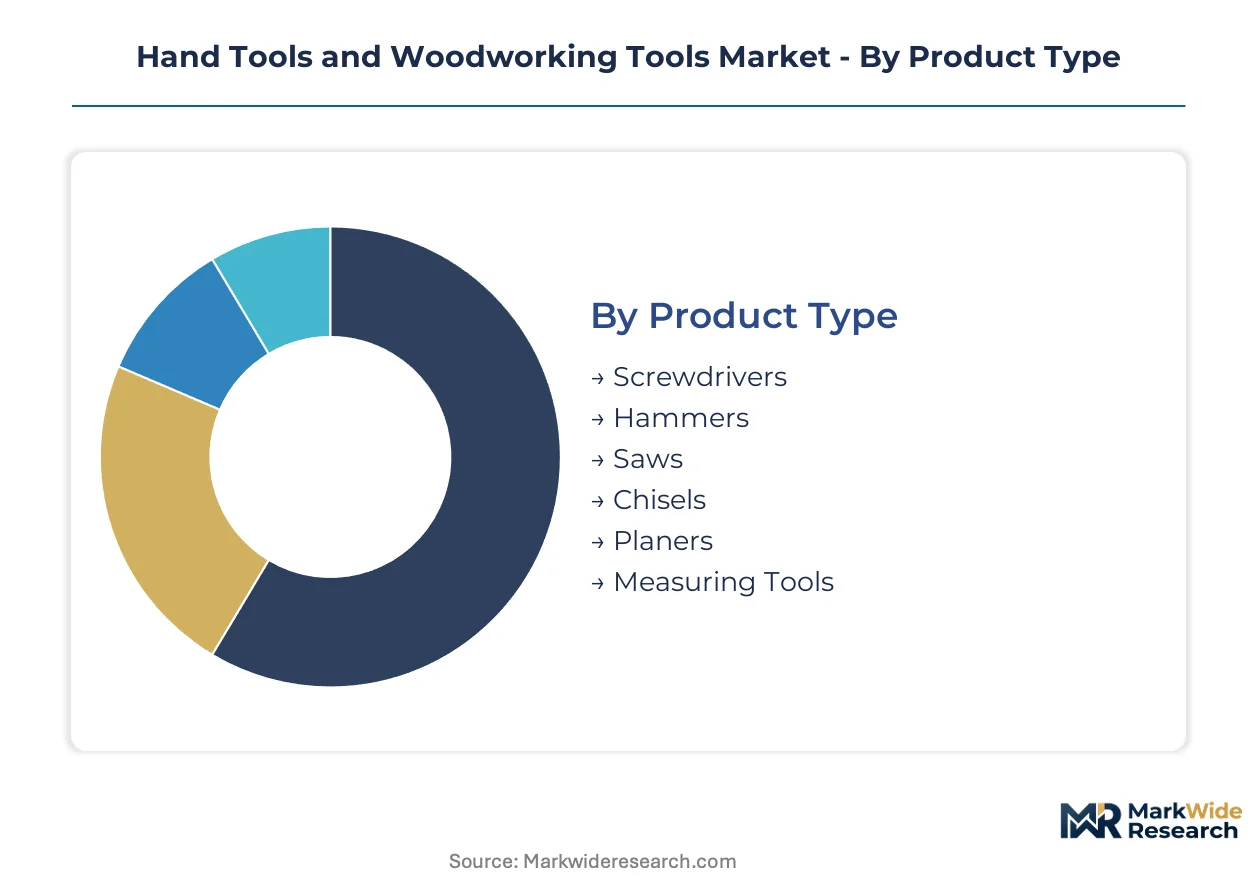
Segmentation in hand tools and woodworking tools reveals how procurement criteria diverge between precision-dependent professional workflows and price-sensitive hobbyist markets. Understanding these divides enables manufacturers to align R&D investment, distribution channel selection, and service infrastructure with buyer priorities.
Product Type:
Purchase decisions in this category pivot on blade replacement ecosystems and calibration frequency, with professional buyers prioritizing total cost of ownership over upfront price.
- Saws:Carbide-tipped circular and reciprocating blades dominate professional-grade portfolios due to runtime demands in engineered wood processing. Cabinet shops in Germany's Black Forest cluster specify these for composite substrate fabrication where kerf precision governs material yield.
- Planers:Brushless motor integration in cordless thickness planers is compressing replacement cycles among on-site construction crews. Runtime expectations from lithium-ion density improvements now match corded performance benchmarks for dimensioning hardwood stock.
- Screwdrivers:Ratcheting and impact variants serve furniture assembly lines where torque consistency prevents fastener stripping in hardwood frames.
- Hammers:Claw and framing patterns sustain volume dominance in emerging markets where electrification gaps limit power tool adoption.
- Chisels:High-carbon steel edge retention matters for joinery work requiring hand-fitted mortise-and-tenon joints in solid wood construction.
- Measuring Tools:Laser distance meters and digital calipers address tolerance tightening in North American residential construction specifications.
Saws lead on scale through blade ecosystem lock-in; planers lead on momentum through cordless platform migration.
Technology:
Power source selection tracks electrification completeness and runtime requirements, with professional buyers migrating toward lithium-ion platforms that eliminate generator dependency.
- Cordless:Higher-density lithium-ion cells paired with brushless motor controllers automate torque delivery and stall prevention. Runtime extensions now satisfy professional planer and saw applications that nickel-cadmium platforms could not support.
- Manual:Alloy steel hand tools retain dominant volume share in India where power infrastructure gaps and artisanal price sensitivity govern procurement. Black Forest woodworking traditions also sustain demand for hand-fitted joinery precision.
- Electric:Corded platforms persist in stationary shop environments where continuous runtime outweighs mobility requirements.
- Pneumatic:Compressed air systems anchor high-volume furniture manufacturing workflows in Brazil's São Paulo corridor.
- Hydraulic:Heavy-duty timber framing and industrial-scale rough dimensioning applications specify these for force multiplication in specialized millwork.
Manual tools lead on scale through emerging market penetration; cordless platforms lead on momentum through professional replacement cycles.
Application:
Workflow specificity determines tool specification, with contract manufacturers demanding tighter tolerances than renovation contractors.
- Furniture Manufacturing:Precision finishing equipment serves international contract manufacturers in Brazil's Minas Gerais wood processing corridor where export quality standards govern specification. REACH substance restrictions and EU Green Deal traceability requirements filter supplier pools toward certified tooling.
- Cabinet Making:Engineered panel processing demands measurement tool accuracy for hinge and hardware alignment in frameless construction.
- Carpentry:Rough dimensioning through fine finishing spans solid wood and composite substrates in residential construction.
- Joinery:Hand-fitted mortise-and-tenon and dovetail work persists in artisanal production clusters where craft certification matters.
- Flooring Installation:Pneumatic and cordless fastening systems address speed requirements in large-scale commercial fit-outs.
- Door Fitting:Hinge mortising and lockset installation tools serve maintenance services where mobile distribution networks concentrate replacement demand.
Furniture manufacturing leads on scale through export contract concentration; cabinet making leads on momentum through engineered wood specification upgrades.
End User:
Customer type segmentation separates specification-driven professional procurement from retail-channel DIY purchasing patterns.
- Professional Craftsmen:These buyers evaluate modular tool-kit bundling over single-item purchases, with OSHA ergonomic design mandates for vibration exposure creating premium positioning for compliant lines. Mobile distribution networks serving automotive-adjacent maintenance are fragmenting traditional wholesale relationships.
- DIY Enthusiasts:Stanley Black & Decker's multi-brand portfolio controls shelf presence across retail channels where price visibility and bundled accessories drive selection.
- Carpentry Shops:Stationary equipment investments prioritize corded electric platforms for continuous runtime in hardwood dimensioning.
- Maintenance Services:Snap-On Incorporated's route-based model concentrates high-frequency hand tool replacement in fleet and industrial facility contracts.
- Furniture Workshops:Artisanal and industrial convergence in Germany's Black Forest creates geographic supply vulnerability alongside premium positioning opportunities.
Professional craftsmen lead on scale through specification authority; DIY enthusiasts lead on momentum through retail channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hand tool craftsmanship traces its commercial lineage to Sheffield's steelworking tradition and Solingen's blade-forging heritage, where guild standards established quality benchmarks that persist in contemporary certification frameworks. These historical centers shaped metallurgical expertise that now diffuses across manufacturing clusters worldwide.
United States
Residential construction precision requirements and automotive-adjacent maintenance services drive specification upgrades for joinery equipment. OSHA workplace safety standards govern ergonomic design mandates for vibration exposure and acoustic emission limits. Cabinet shops in North Carolina's furniture corridor adopt cordless lithium-ion platforms for on-site hardwood dimensioning.
Germany
Artisanal and industrial producer convergence in the Black Forest woodworking cluster creates concentrated demand for hand-fitted joinery precision. EU Green Deal material traceability requirements and REACH substance restrictions reshape sourcing standards for alloy steel inputs. Stuttgart's tooling manufacturers invest in certified supply chains to maintain CE marking compliance for power-assisted implements.
China
Incomplete electrification in western provinces sustains manual hand tool volume dominance among price-sensitive artisanal woodworkers. GB standards and MIIT industrial policy guide domestic certification for power tool platforms. Zhejiang's Yongkang hardware cluster exports alloy steel implements to Southeast Asian contract manufacturers.
India
Power infrastructure gaps and artisanal price sensitivity govern procurement decisions for manual chisels and hammers in solid wood construction. BIS certification requirements and DGFT import regulations filter supplier pools for professional-grade equipment. Jodhpur's furniture manufacturing belt specifies measurement tools for export-quality hardwood frame fabrication.
Brazil
São Paulo and Minas Gerais wood processing corridors present underpenetrated demand for precision finishing equipment serving international contract manufacturers. ANVISA industrial safety standards and export quality protocols shape tool specification in furniture manufacturing workflows. Bento Gonçalves' furniture cluster adopts pneumatic fastening systems for large-scale commercial fit-outs.
Hand Tools and Woodworking Tools Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification grade and distribution channel control, with tiered pricing separating professional-grade portfolios from retail-channel consumables. The vendor base spans multi-brand conglomerates, mobile distribution specialists, and regional alloy steel fabricators. Three archetypes dominate: cordless technology leaders, route-based service networks, and captive metallurgy-integrated manufacturers. Competitive moves concentrate on modular tool-kit bundling strategies and direct-to-technician channel fragmentation.
Among diversified industrial conglomerates, Techtronic Industries Co. Ltd and Stanley Black & Decker exemplify multi-brand portfolio structures that control shelf presence across retail channels. Snap-On Incorporated occupies a distinct position within mobile distribution networks serving high-frequency replacement demand. These three anchors represent divergent channel strategies—cordless platform leadership, retail saturation, and route-based technician service—that collectively fragment traditional wholesale relationships.
| Leading Market Players |
|---|
| Techtronic Industries Co. Ltd |
| Husqvarna |
| Stanley Black & Decker |
| Channellock |
| Hangzhou Great Star Industrial Co. Ltd. |
| Apex Tool Group |
| Klein Tools |
| Estwing |
| Snap-On Incorporated |
| Others |
Cost & Logistics Intelligence
Alloy steel and carbide-tipped substrate costs cascade through three distinct pricing tiers as raw material provenance documentation becomes mandatory under EU Green Deal traceability frameworks. Black Forest artisanal buyers absorb premium-grade pricing for certified supply chains while Indian price-sensitive segments sustain economy-tier volume through uncertified alloy steel procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement pools as CE marking compliance and OSHA ergonomic certification separate professional-grade portfolios from retail consumables. Price differentiation hinges on material certification grade and after-sales calibration service bundling. Cost compression in mid-tier cordless platforms intensifies as lithium-ion cell density improvements compress replacement cycles. DIY enthusiasts exhibit highest price sensitivity through retail channel price visibility while professional craftsmen prioritize total cost of ownership.
Supply Chain Analysis
Reverse-logistics flows for end-of-life battery collection and blade refurbishment programs are gaining structural importance as extended producer responsibility frameworks mature. Manufacturing concentration spans China for alloy steel fabrication, Germany for precision cutting edge metallurgy, and the United States for brushless motor controller assembly. Raw material dependencies rest on cobalt and lithium compounds for power platforms, high-carbon steel for manual edges, and tungsten carbide for professional cutting inserts. Single-source vulnerability concentrates in German carbide substrate suppliers. Distribution runs through mobile route-based networks for high-frequency replacement alongside traditional wholesale for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cordless platform premiumization and certified supply chain tiering as battery technology costs compress and regulatory traceability mandates filter procurement pools toward documented provenance suppliers.
For Market Incumbents: Acquire captive metallurgical supply capabilities to defend against alloy steel price volatility and EU Green Deal sourcing documentation requirements. Secure CE marking pre-certification capacity to compress product launch timelines under Machinery Directive compliance burdens. Channel control through direct-to-technician route networks fragments traditional wholesale relationships and locks in replacement demand. For New Entrants and Emerging Players: Capture underpenetrated precision finishing demand in Brazil's São Paulo and Minas Gerais wood processing corridors where international contract manufacturers specify export-quality equipment. Target India's manual hand tool volume dominance through price-optimized alloy steel sourcing for power infrastructure gap markets. Go-to-market leverage rests on pneumatic system integration partnerships for furniture manufacturing workflows. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack backward integration into certified metallurgical supply and struggle with CE marking compliance cost burdens. Long-term viability favors cordless technology leaders with lithium-ion platform R&D depth and route-based distribution density. Target acquisition archetype: regional alloy steel fabricators with EU Green Deal traceability documentation infrastructure. Monitor IATA lithium-ion shipping classification evolution for distribution cost inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Metallurgical Supply | EU Green Deal traceability requirements filter procurement toward documented provenance suppliers with captive steel sourcing. |
| Cordless Platform Premium Tier Expansion | Brushless motor and lithium-ion density improvements elevate runtime benchmarks that compress replacement cycles. |
| Mobile Route-Based Distribution Buildout | Snap-On's technician-service model concentrates high-frequency hand tool replacement in fleet maintenance contracts. |
| CE Marking Pre-Certification Investment | Machinery Directive compliance timelines create launch delays that favor manufacturers with dedicated testing infrastructure. |
| Modular Tool-Kit Bundling Systems | Professional craftsmen evaluate integrated systems over single-item purchases, repositioning shelf presence strategies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German Black Forest cabinet shops, procurement leads at Brazilian furniture exporters, aftermarket service heads at North American maintenance contractors, and OEM sourcing teams at cordless platform manufacturers. Secondary validation drew from SEC filings of listed tool manufacturers, EU ECHA REACH substance restriction databases, OSHA workplace safety standard updates, and customs trade data for alloy steel implement flows. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated for convergence.
Segment-weighting approaches distributed value across product type, technology platform, application workflow, and end-user archetype dimensions throughout the projection horizon. CAGRs were derived from replacement cycle compression rates, electrification penetration curves, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated lithium-ion battery density improvement trajectories and EU Green Deal embodied carbon disclosure phase-in schedules.
Alloy steel price volatility, lithium-ion shipping reclassification under IATA frameworks, and precision calibration technician scarcity are the dominant revision risks that could alter trajectory assumptions. Practitioners should monitor cobalt compound supply disruptions, CE marking compliance timeline extensions, and vocational training pipeline development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cordless Fillet Weld Grinder Market
Tools
Post Drivers Market
Tools
Metal Cutting Tools Market
Tools
Global Metal Forming Machine Tools Market
Tools
Woodcarving Tool Market
Tools
Global Protractor Market
Tools
Hand and Power Tools Market
Tools
Grinding Discs Market
Tools
Manual Cutting Equipment Market
Tools
L Allen Wrench Market
Tools
Global Zero Point Clamping System Market
Tools
Theodolite Market
Tools
Water Pump Pliers Market
Tools
Vise-Grip Pliers Market
Tools
Hydraulic Tools Market
Tools
Europe Paint Spray Guns Market