
 Construction Anchors Market | 2026-2036
Construction Anchors Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Anchors Market Outlook
Market Overview
The capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with captive steel forging and heat-treatment capabilities. Hilti Corporation leverages its in-house metallurgy research to sustain premium positioning across seismic-rated wedge anchor lines. fischer Group anchors its European footprint through direct distribution to specialist contractors. Simpson Strong-Tie Company differentiates via building-code pre-approval dominance in North American wood-to-concrete connections.
Construction anchors are load-transfer devices engineered to secure structural elements to concrete, masonry, or steel substrates through mechanical interlock, adhesive bonding, or friction grip, with critical specifications including tensile strength ratings, embedment depths, and seismic performance classifications under ICC-ES AC193 and EOTA TR029 protocols. Mechanical anchors occupy the largest volume share due to installation speed and immediate load-bearing capacity, while chemical anchors capture expanding specification in infrastructure rehabilitation where adhesive bonding enables closer edge distances and reduced concrete stress. Sleeve anchors retain mature demand in light-duty commercial applications where cost sensitivity outweighs performance premiums.
Federal and state building codes across the United States, enforced through ICC-ES evaluation reports and ACI 318 appendix D provisions, mandate seismic qualification for post-installed anchors in high-risk zones, directly shaping R&D priorities and certification costs. The EU Construction Products Regulation and EOTA European Technical Assessments govern CE marking and performance declarations for anchors sold in member states, creating market access barriers for uncertified suppliers. Stakeholders must monitor evolving green building certification schemes and embodied-carbon disclosure requirements that will increasingly influence material selection between conventional steel and lower-carbon stainless or composite alternatives.
Market Dynamics
Seismic code harmonization across multiple jurisdictions is forcing anchor manufacturers to redesign product portfolios around unified performance test protocols rather than legacy national standards.
Growth Catalysts
- India's metro rail expansion:Underground and elevated transit corridors in Mumbai, Delhi, and Bangalore are specifying high-load post-installed anchors for tunnel lining and platform structures. Indian Railways mandates ICC-ES AC193-equivalent seismic qualification for all structural fasteners.
- EU Construction Products Regulation:Mandatory CE marking under EOTA European Technical Assessments is consolidating specification authority among certified suppliers and eliminating uncertified imports from Eastern European distribution channels.
- Carbon-reinforced polymer anchors:Composite tensioning elements are penetrating infrastructure rehabilitation where electromagnetic interference prohibits metallic fasteners near rail signaling and power transmission hardware.
Market Restraints
- Alloy steel price volatility:Forged anchor bodies depend on chromium-molybdenum bar stock concentrated in Chinese and Indian mill capacity, exposing margin structures to raw material surcharge fluctuations.
- Adhesive supply concentration:Vinyl ester and epoxy injection systems for chemical anchoring rely on specialty resin formulators in Germany and Switzerland, creating single-source vulnerability for qualified European producers.
- Seismic test facility scarcity:ICC-ES AC156 and EOTA TR029 shake-table certification requires accredited laboratories in the United States, Italy, and Japan, constraining new entrant market access.
Strategic Opportunities
- Indonesia's new capital Nusantara:The planned smart city development in East Kalimantan represents greenfield specification potential for corrosion-resistant stainless anchors in coastal humidity conditions.
- Digital torque monitoring:Integration of Bluetooth-enabled installation verification tools with contractor fleet management software is creating recurring revenue streams beyond hardware sales.
- EU Green Deal embodied-carbon disclosure:Upcoming requirements for Environmental Product Declarations will favor domestic European manufacturers with verified low-carbon steel sourcing over import-dependent competitors.
Industry Challenges
- Installer certification gaps:Proper adhesive anchor installation requires trained technicians competent in hole cleaning, injection technique, and cure-time management, yet contractor workforce development lags specification complexity in emerging markets.
- Legacy inventory stranding:Seismic code updates in California and Japan are rendering pre-2020 anchor models non-compliant, forcing distributors to absorb write-downs on non-conforming stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Anchors Market |
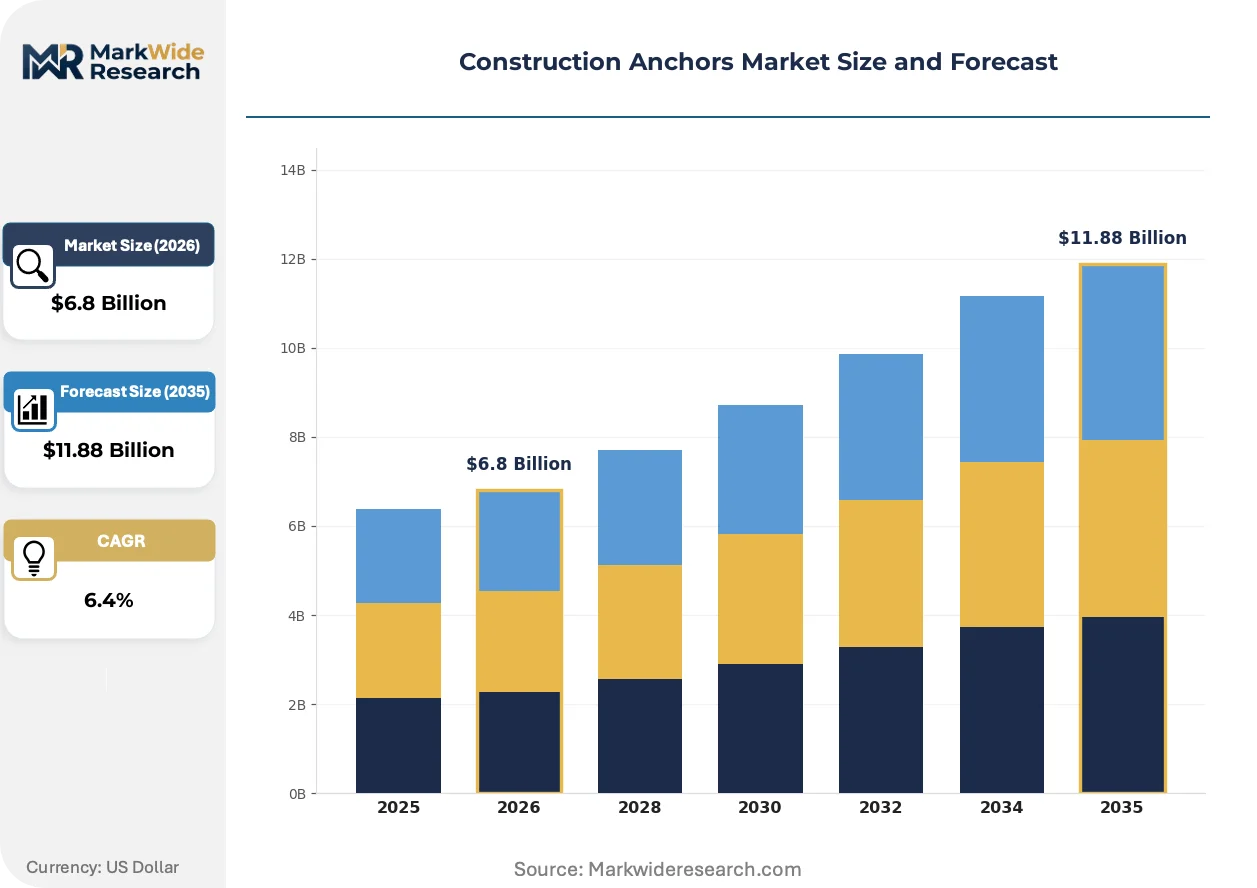
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Chemical Anchors, Sleeve Anchors, Wedge Anchors Installation Method: Drilled, Hammer Driven, Adhesive Bonding, Cast-in-Place End User: Residential Construction, Commercial Construction, Infrastructure Development, Industrial Sector Material: Steel, Stainless Steel, Plastic, Composite |
| Companies Covered | Hilti Corporation, Stanley Black & Decker, Illinois Tool Works, Würth Group, Simpson Strong-Tie Company, Sika AG, fischer Group, MKT Fastening, SFS Group Fastening Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Anchors Market Strategic Shifts
Anchor technology is converging with structural health monitoring and digital construction workflows, shifting value capture from commodity hardware to verified performance data and installation assurance services.
Corrosion-resistant micro-anchors are miniaturizing for facade cladding and curtain wall applications where reduced embedment depths and closer edge distances are essential. High-rise developers in Singapore and Dubai are specifying these systems to accelerate envelope installation schedules. The technology is miniaturizing traditional heavy-duty mechanical anchors into compact formats that maintain load ratings while eliminating concrete breakout risk in thin structural elements.
REACH chemical restrictions in the European Union are phasing out styrene-based vinyl ester resins used in chemical anchoring systems. Manufacturers are reformulating with acrylate and hybrid epoxy chemistries that maintain bond strength while meeting Substance of Very High Concern screening criteria. German and French specification engineers are driving the fastest adoption curves as public infrastructure tenders embed green chemistry compliance into technical evaluation criteria.
Specification authority is migrating from general contractors to specialist structural engineering consultants who control anchor selection through performance-based design submittals. This shift concentrates procurement decision-making in engineering firms with ICC-ES and EOTA evaluation report libraries, marginalizing traditional distributor influence. The United States and Australia exhibit the most advanced consultant-driven specification patterns, particularly in seismic retrofit and industrial facility upgrades.
Construction Anchors Market Segmentation
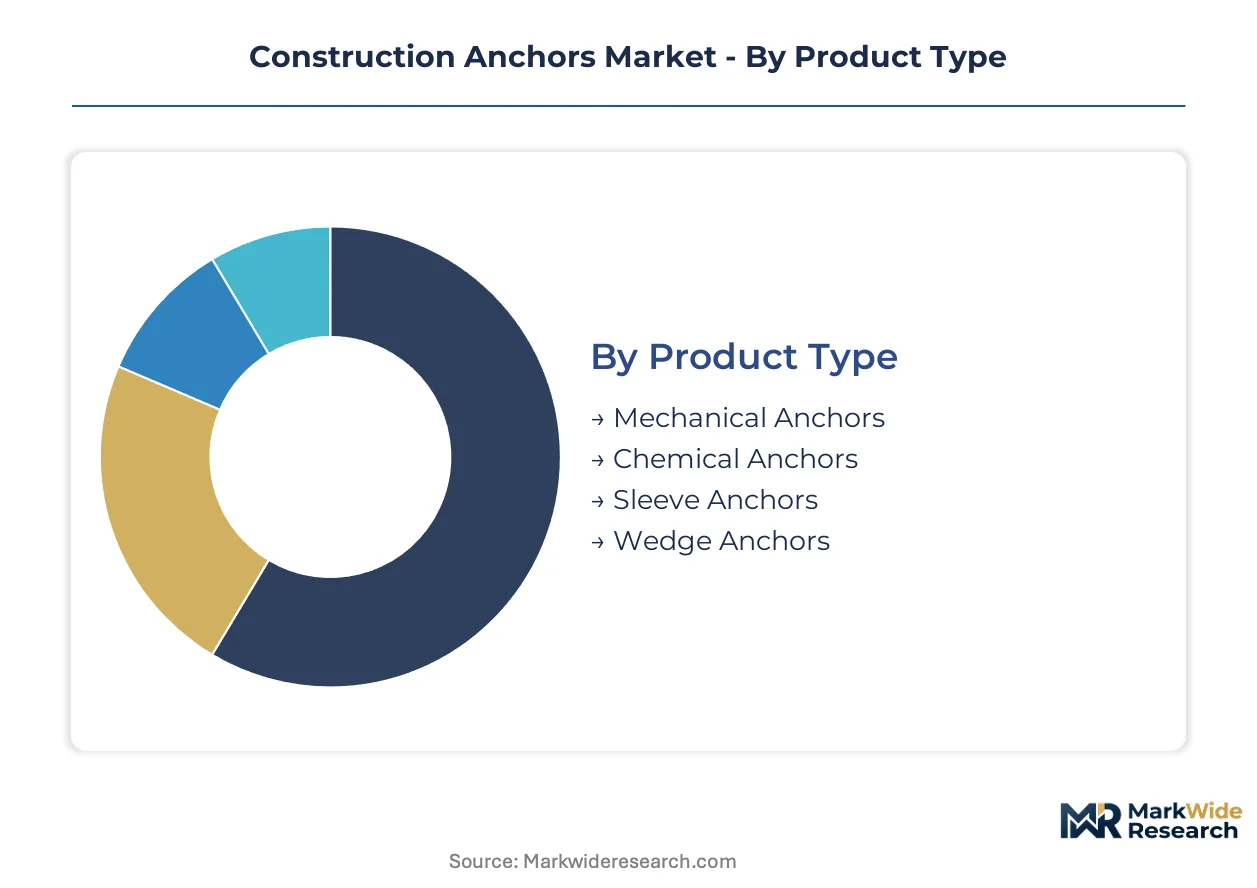
Segmentation in construction anchors reveals how specification authority migrates across product categories, installation methods, and material grades. Engineers, contractors, and distributors each prioritize different performance attributes, creating parallel demand hierarchies that reshape procurement patterns and margin structures.
Product Type:
Substitution pressure runs strongest against legacy mechanical formats as chemical bonding and composite alternatives capture specification in seismic-critical and corrosion-sensitive applications.
- Mechanical Anchors:Load transfer occurs through friction grip or mechanical interlock between expansion elements and concrete substrate. India's metro rail corridors in Mumbai and Delhi specify high-load mechanical anchors for tunnel lining and platform structures where immediate load-bearing capacity accelerates construction schedules.
- Chemical Anchors:Adhesive bonding via vinyl ester or epoxy injection systems enables closer edge distances and reduced concrete stress versus mechanical alternatives. Infrastructure rehabilitation across Germany and Switzerland favors chemical anchoring where substrate cracking limits mechanical anchor reliability.
- Sleeve Anchors:Mature demand persists in light-duty commercial applications where cost sensitivity outweighs performance premiums.
- Wedge Anchors:Seismic-rated wedge designs dominate North American wood-to-concrete connections under ICC-ES AC193 protocols.
Mechanical anchors retain volume leadership; chemical anchors hold the steepest expansion curve as infrastructure rehabilitation accelerates specification of adhesive-bonded systems.
Installation Method:
Cost tier stratification separates premium precision-drilled systems from economy hammer-driven formats, with adhesive bonding occupying the mid-tier value position.
- Drilled:Rotary-percussion or diamond-core drilling creates precise holes for post-installed mechanical or chemical anchors. High-rise envelope installation in Singapore and Dubai mandates drilled methods for facade cladding where reduced embedment depths eliminate concrete breakout risk.
- Hammer Driven:Nail-in and drive-pin anchors enable rapid installation in low-load applications. Residential framing contractors across the United States favor hammer-driven formats for speed-critical rough carpentry.
- Adhesive Bonding:Injection systems require trained technicians competent in hole cleaning, injection technique, and cure-time management.
- Cast-in-Place:Embedded anchor plates and headed studs specified during concrete pour eliminate post-installation variables.
Drilled methods command the highest specification authority; adhesive bonding is climbing the fastest as workforce certification programs expand in emerging markets.
End User:
Application maturity varies sharply, with infrastructure development exhibiting the most stringent performance certification requirements and residential construction showing the greatest price elasticity.
- Infrastructure Development:Bridges, tunnels, transit systems, and energy facilities demand seismic-qualified anchors under ICC-ES AC193 and EOTA TR029 protocols. Indonesian planners specify corrosion-resistant stainless anchors for the Nusantara smart city development in East Kalimantan coastal humidity conditions.
- Commercial Construction:High-rise cores, parking structures, and retail envelopes balance load ratings with installation speed. Australian structural engineering consultants increasingly control anchor selection through performance-based design submittals in commercial retrofit projects.
- Industrial Sector:Manufacturing facilities and process plants prioritize vibration resistance and chemical exposure tolerance.
- Residential Construction:Single-family and multi-family housing favor cost-optimized mechanical anchors for foundation and framing connections.
Infrastructure development retains specification rigor leadership; commercial construction is gaining share fastest as consultant-driven design patterns spread.
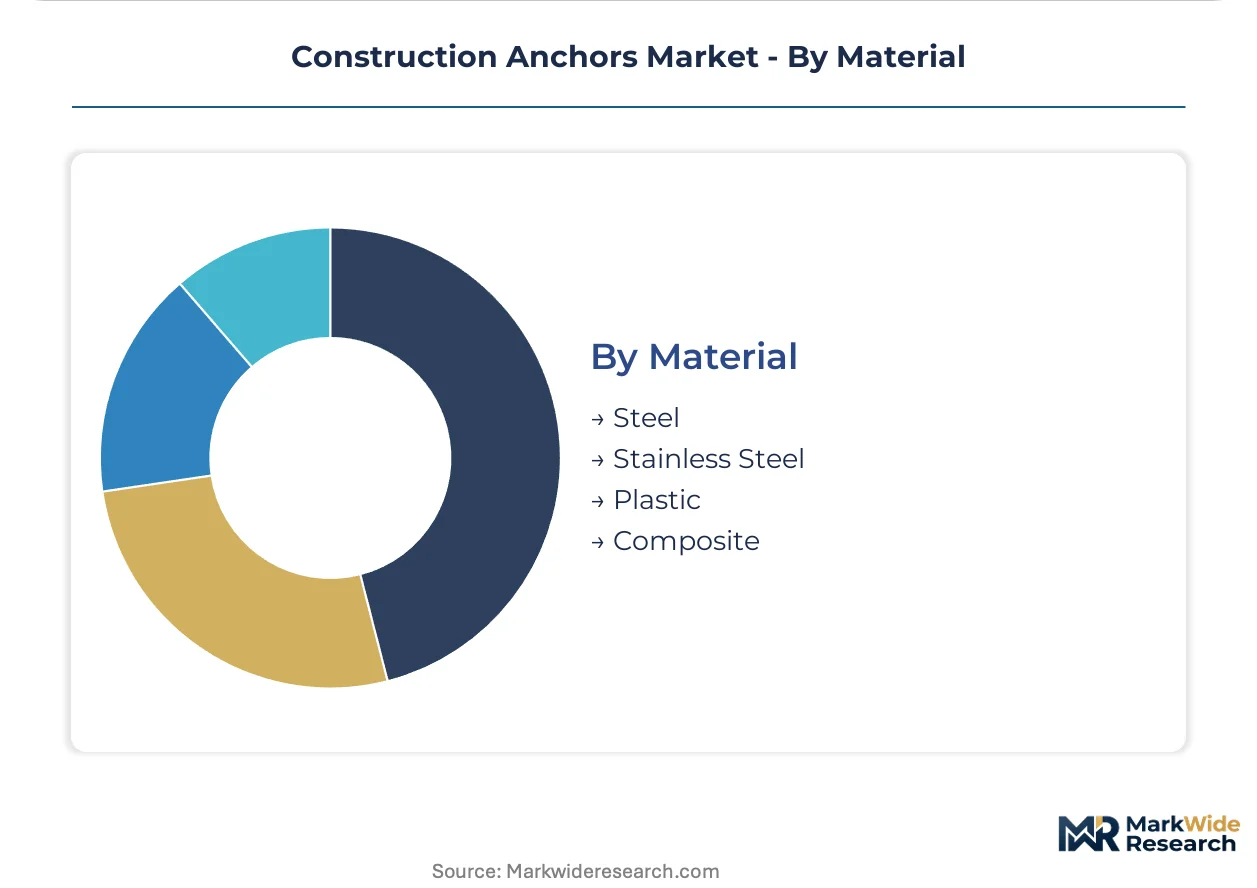
Material:
Supply concentration in Chinese and Indian mill capacity for alloy steel bar stock creates margin vulnerability, while stainless and composite alternatives capture premium positioning.
- Steel:Chromium-molybdenum forged bodies dominate volume production. REACH chemical restrictions in the European Union are forcing reformulation of associated coating systems.
- Stainless Steel:Corrosion resistance enables specification in coastal humidity, chemical exposure, and long-design-life infrastructure. EU Green Deal embodied-carbon disclosure requirements will favor European manufacturers with verified low-carbon stainless sourcing.
- Plastic:Nylon and polypropylene anchors serve light-duty applications in electrical and mechanical trades.
- Composite:Carbon-reinforced polymer tensioning elements penetrate infrastructure rehabilitation where electromagnetic interference prohibits metallic fasteners near rail signaling and power transmission hardware.
Steel retains volume dominance; composite materials are expanding most quickly as electromagnetic compatibility requirements proliferate in transit and energy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's residential construction segment exhibit acute price sensitivity, while infrastructure developers in Germany and the United States absorb substantial premiums for seismic-qualified certification. This elasticity divergence shapes procurement patterns across major demand centers.
United States
Seismic retrofit mandates in California and Pacific Northwest jurisdictions sustain demand for ICC-ES AC193-qualified post-installed anchors. The Federal Emergency Management Agency coordinates state-level adoption of ASCE 7-22 provisions that tighten fastening requirements in high-risk zones. Los Angeles and San Francisco metropolitan corridors concentrate specification authority among structural engineering consultants who control anchor selection through performance-based design submittals.
Germany
Infrastructure rehabilitation across aging Rhine-Ruhr industrial corridors favors chemical anchoring where substrate cracking limits mechanical alternatives. The EOTA European Technical Assessment framework and REACH chemical restrictions are consolidating specification authority among certified domestic suppliers. Stuttgart and Munich engineering clusters drive adoption of acrylate-based adhesive systems that satisfy Substance of Very High Concern screening criteria.
India
Metro rail expansion in Mumbai, Delhi, and Bangalore accelerates procurement of high-load mechanical and chemical anchoring solutions. Indian Railways mandates ICC-ES AC193-equivalent seismic qualification for all structural fasteners in underground transit applications. The Delhi-Mumbai Industrial Corridor anchors concentrated demand for corrosion-resistant stainless systems in coastal humidity conditions.
China
High-speed rail maintenance and urban renewal projects in the Yangtze River Delta sustain volume demand for cast-in-place and post-installed anchors. GB standards for seismic design of buildings and the Ministry of Housing and Urban-Rural Development's quality supervision protocols shape certification requirements. Shanghai and Shenzhen construction markets concentrate specification of carbon-reinforced polymer alternatives where electromagnetic interference prohibits metallic fasteners near rail signaling infrastructure.
Indonesia
The Nusantara smart city development in East Kalimantan represents greenfield specification potential for corrosion-resistant fastening systems in tropical coastal conditions. National infrastructure procurement guidelines under the Coordinating Ministry for Maritime Affairs and Investment emphasize durability certification for public works. The Jakarta-Bandung high-speed rail corridor concentrates demand for qualified chemical anchoring in elevated viaduct construction.
Construction Anchors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive metallurgy and heat-treatment capabilities rotating advantage toward firms controlling upstream steel forging operations. The vendor base stratifies between premium-positioned seismic specialists, mid-tier regional fabricators, and commodity assemblers dependent on outsourced components. Two dominant archetypes emerge: integrated manufacturers with in-house R&D laboratories and certification authority, and distribution-heavy specialists leveraging direct contractor relationships. Competitive moves concentrate on portfolio diversification into digital installation verification tools and backward integration into specialty resin formulation for chemical anchoring systems.
Within the integrated manufacturing tier, Hilti Corporation and fischer Group occupy positions defined by metallurgy research depth and European distribution density respectively. Simpson Strong-Tie Company anchors the North American specialist segment. These three firms exemplify contrasting strategic postures: Liechtenstein-based captive technology development, German direct-to-contractor channel control, and California-centric building-code pre-approval dominance.
| Leading Market Players |
|---|
| Hilti Corporation |
| Stanley Black & Decker |
| Illinois Tool Works |
| Würth Group |
| Simpson Strong-Tie Company |
| Sika AG |
| fischer Group |
| MKT Fastening |
| SFS Group Fastening Technology |
| Others |
Value Chain & Pricing Dynamics
ICC-ES AC193 and EOTA TR029 certification protocols gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb seismic test facility costs that stratify the vendor base into premium-certified and uncertified tiers. Certified anchors command substantial premiums in California and Pacific Northwest jurisdictions where FEMA-coordinated retrofit mandates eliminate non-compliant alternatives, while uncertified imports face exclusion from EU member states under mandatory CE marking.
Pricing Analysis
Digital torque monitoring and Bluetooth-enabled installation verification tools drive lifetime value expansion faster than hardware margins alone. Pricing stratifies across premium, standard, and economy tiers based on seismic qualification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese and Indian mill capacity surcharges on chromium-molybdenum bar stock transmit directly to forged anchor body costs. Residential contractors across the United States exhibit acute price sensitivity, while infrastructure developers in Germany absorb certification premiums without volume elasticity.
Supply Chain Analysis
China and India anchor global supply of chromium-molybdenum forged anchor bodies, while Germany and Switzerland concentrate specialty vinyl ester and epoxy resin formulation for chemical anchoring systems. The supply chain draws from alloy steel bar stock, injection-molded expansion elements, and adhesive resin chemistry as core inputs. Single-source vulnerability in qualified European resin formulators creates structural risk for chemical anchor producers dependent on REACH-compliant hybrid epoxy alternatives. Distribution runs through direct-to-contractor channels for premium seismic lines and construction distributor networks for commodity mechanical formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from digital installation verification and workforce certification programs is expanding faster than anchor hardware sales, repositioning competitive advantage toward firms controlling recurring performance data streams rather than unit production alone.
For Market Incumbents: Consolidate certification authority through captive control of ICC-ES and EOTA evaluation report libraries that marginalize distributor influence in consultant-driven specification markets. Deepen backward integration into heat-treatment capabilities that rotate advantage toward integrated manufacturers with in-house metallurgy research, defending against emerging Asian component assemblers dependent on outsourced steel forging. For New Entrants and Emerging Players: EOTA European Technical Assessment fast-tracks offer the most penetrable path into EU infrastructure rehabilitation markets where REACH chemical restrictions have stranded legacy styrene-based vinyl ester inventories. Target Indonesia's Nusantara smart city development for greenfield specification of corrosion-resistant stainless anchors in coastal humidity conditions, leveraging direct relationships with specialist structural engineering consultants rather than traditional distribution channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across seismic-rated product lines as shake-table certification requirements and in-house metallurgy R&D concentrate advantage among integrated manufacturers. Five-to-ten year viability favors acquisition of mid-tier European fabricators with verified low-carbon steel sourcing pathways ahead of EU Green Deal embodied-carbon disclosure mandates. Monitor adhesive resin formulation capabilities as the inflection indicator for chemical anchor margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment | Captive metallurgy research sustains premium positioning across ICC-ES AC193 wedge anchor lines. |
| Digital Torque Monitoring Platform Launch | Bluetooth-enabled verification tools create recurring revenue streams beyond hardware unit sales. |
| REACH-Compliant Resin Reformulation | Acrylate-based adhesive systems satisfy Substance of Very High Concern screening for EU infrastructure tenders. |
| Stainless Steel Sourcing Certification | Verified low-carbon supply chains defend margin position ahead of EU Green Deal disclosure requirements. |
| Installer Workforce Certification Program | Trained technician networks lock in specification authority for adhesive bonding in emerging markets. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with anchor manufacturers, structural engineering consultants, and construction distributor procurement heads; and secondary validation through ICC-ES evaluation report databases, EOTA European Technical Assessment registries, and customs trade data on alloy steel bar stock flows. Plant managers at integrated forging facilities, technical R&D directors at adhesive resin formulators, and aftermarket service heads at fastening distributors provided operational perspective. SEC 10-K filings, EU Construction Products Regulation compliance databases, and Indian Railways procurement circulars supplied financial and regulatory context. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Across the analysis window, forecasts reflect analytical framework segmentation by product type, installation method, end-use sector, and material grade. CAGRs were derived from regression analysis against infrastructure investment flows and seismic code adoption curves. Modeled inputs include metro rail capital expenditure pipelines in India, EU Green Deal implementation timelines, and REACH chemical restriction phase-out schedules for styrene-based resins.
Decision-makers should treat outputs as directional under sustained infrastructure investment and regulatory harmonization assumptions; material deviation in alloy steel pricing or seismic code adoption velocity would warrant model refresh. Recalibration cycles align with material shifts in certification protocol updates and green building mandate expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Rebar Cutter Market
Tools
Metal Forming Tools Market
Tools
Electric Power Tools Market
Tools
Fine Blanking Tools Market
Tools
Edge Banders Market
Tools
Sander Market
Tools
Press Machine Market
Tools
Land Survey Equipment Market
Tools
Global Protractor Market
Tools
Rivet Gun Market
Tools
Power Press Machines Market
Tools
Entrenching Tool Market
Tools
United States Machine Tools Market
Tools
Clamps Market
Tools
Gouging Torch Market
Tools
Woodpecker Tools Market