
 Key Cutting Machine Market | 2026-2036
Key Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Key Cutting Machine Market Insights
CE marking under the EU Machinery Directive is expanding compliance costs for automatic and CNC key cutting machines entering European markets. Silca leverages in-house manufacturing of laser cutting heads to sustain margin control across premium locksmith segments. Kukai anchors its position in Asian markets through compact semi-automatic designs suited for high-volume hardware stores. HPC competes on channel depth, with distribution networks spanning North American locksmith cooperatives and institutional procurement channels.
A key cutting machine is a precision mechanical or electromechanical device that replicates bitting patterns onto key blanks using milling cutters, grinding wheels, or laser ablation systems, typically achieving tolerances within 0.05 millimeters to ensure proper lock cylinder engagement. These machines serve commercial security infrastructure by producing duplicate keys for residential, automotive, and institutional lock systems. Automatic machines command the highest margin pools due to integrated digital decoding and code-cutting capabilities that reduce operator skill requirements. Laser cutting technology is displacing traditional milling in automotive key segments where sidewinder and dimple key geometries demand non-contact material removal.
FDA oversight applies indirectly through workplace safety standards for machine operators, while FCC regulations govern wireless key programming interfaces in mobile key cutter units. ISO 9001 quality management certification shapes supplier qualification for institutional security teams and government procurement channels. Stakeholders must weigh capital intensity against automation payback periods as labor shortages reshape locksmith shop economics.
Market Dynamics
Laser ablation systems are compressing tolerances below 0.03 millimeters in automotive key replication, forcing traditional milling equipment manufacturers to accelerate R&D cycles or cede premium fleet contracts to laser-capable suppliers.
Growth Catalysts
- EU Machinery Directive CE marking:Mandatory electrical safety certifications are filtering out low-cost competitors, creating protected margin pools for compliant automatic machine suppliers serving German and French locksmith cooperatives.
- Automotive sidewinder key proliferation:Non-contact laser cutting is displacing mechanical milling for complex dimple geometries, pulling equipment upgrades across dealership service centers and fleet maintenance depots.
- China hardware store densification:Compact semi-automatic designs are saturating high-volume retail channels in tier-two and tier-three cities where key duplication services anchor foot traffic.
Market Restraints
- Raw material concentration:Tungsten carbide cutter supply depends on Chinese powder metallurgy facilities, exposing margin stability to export quota fluctuations and geopolitical friction.
- Technical skill compression:Automatic decoding capabilities reduce operator training requirements but simultaneously depress locksmith labor rates, slowing payback justification for capital-intensive equipment.
- FCC wireless compliance:Mobile key programming units face certification delays and testing costs that disadvantage smaller equipment vendors against established players with dedicated regulatory affairs teams.
Strategic Opportunities
- India BIS standardization gap:Absence of mandatory domestic certification for key cutting equipment creates first-mover advantage for ISO 9001-certified suppliers targeting institutional security procurement channels.
- Cloud-connected fleet management:Integration of IoT diagnostics with predictive maintenance contracts is unifying hardware sales with recurring software revenue streams.
- US IRA commercial vehicle electrification:Federal tax incentives for fleet modernization are accelerating key management system upgrades at municipal and logistics operators.
Industry Challenges
- Mechatronics talent scarcity:Cross-training requirements spanning mechanical tolerances, laser optics, and embedded software are extending recruitment cycles for field service engineers.
- Legacy lock cylinder interoperability:Decades-old bitting specifications in institutional and residential installed bases force equipment makers to maintain backward-compatible cutter inventories that fragment production economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Key Cutting Machine Market |
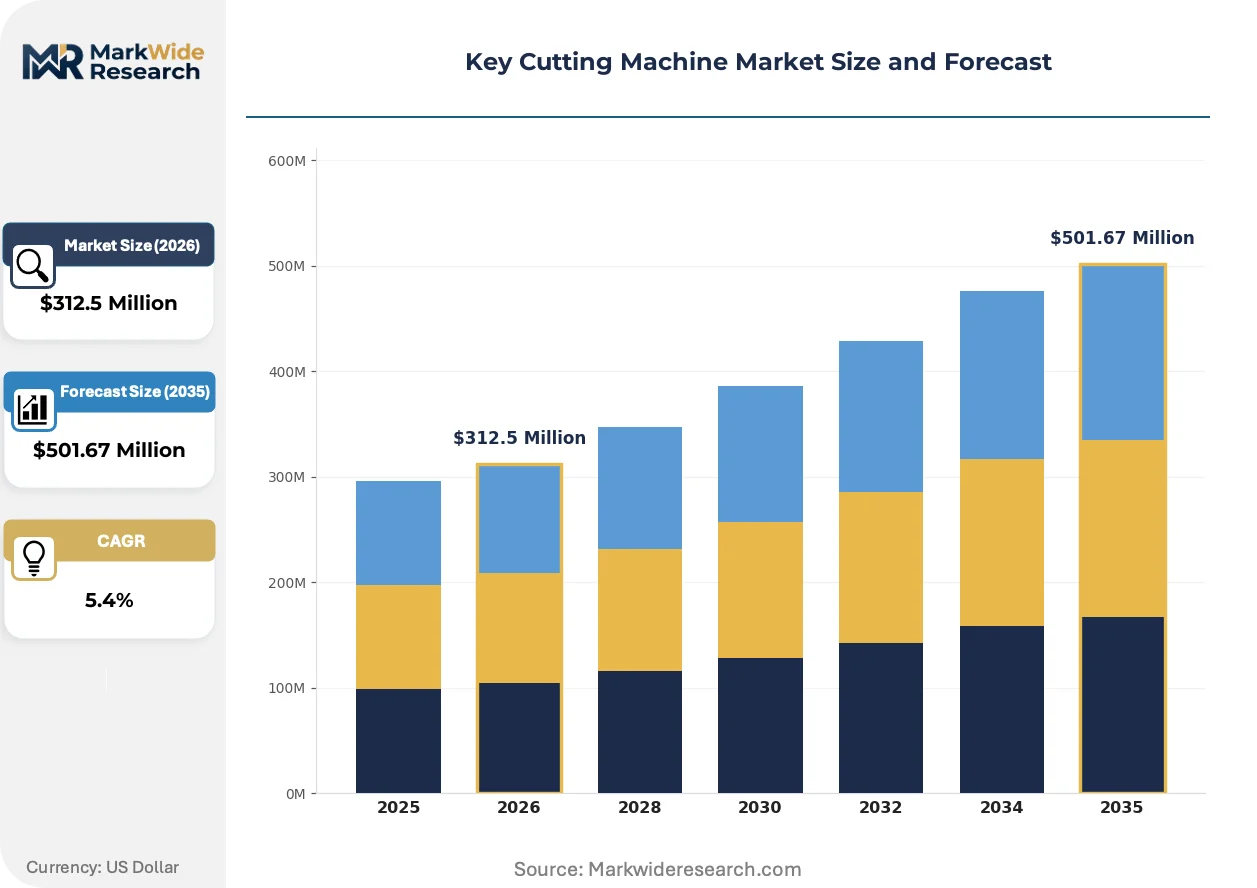
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Semi-Automatic Machines, Automatic Machines, CNC Machines, Mobile Key Cutters Technology: Laser Cutting, Milling Cutting, Impressioning, Jig & Clamp, Duplication Cutting Application: Locksmith Shops, Hardware Stores, Security Service Providers, Car Dealerships, Real Estate Agencies End User: Residential Locksmiths, Commercial Locksmiths, Automotive Key Specialists, Institutional Security Teams, Emergency Service Providers |
| Companies Covered | Black Widow, Kukai, Silca, Ninja, HPC, Keyline, Triton, 2M2 Technology, Xhorse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Key Cutting Machine Market Trends and Innovations
Digital code-cutting interfaces are collapsing the distinction between key duplication and key origination, enabling locksmith operators to serve automotive dealerships without maintaining proprietary manufacturer key blank inventories.
Multi-axis CNC control architectures are unifying laser, milling, and grinding functions within single-platform equipment. Fleet operators in the United States are specifying these hybrid systems to consolidate vendor relationships and reduce floor space requirements. The convergence is compressing capital deployment timelines by eliminating redundant safety enclosures and power infrastructure.
CE marking enforcement under the EU Machinery Directive is tightening electromagnetic compatibility testing for automated units with integrated touchscreens and wireless programming modules. German market surveillance authorities are conducting unannounced factory inspections that delay non-compliant shipments by 8-12 weeks. Manufacturers are responding by pre-certifying platforms through notified bodies in Munich and Stuttgart rather than relying on self-declaration routes.
Hardware store chains are bundling key cutting services with smart lock installation consultations, converting transactional duplication visits into higher-margin security solution engagements. This service unbundling is most visible in Chinese retail channels where property management companies negotiate volume contracts covering residential compound master key systems. The shift is pressuring standalone locksmith shops to diversify into access control integration or exit the market entirely.
Key Cutting Machine Market Segmentation
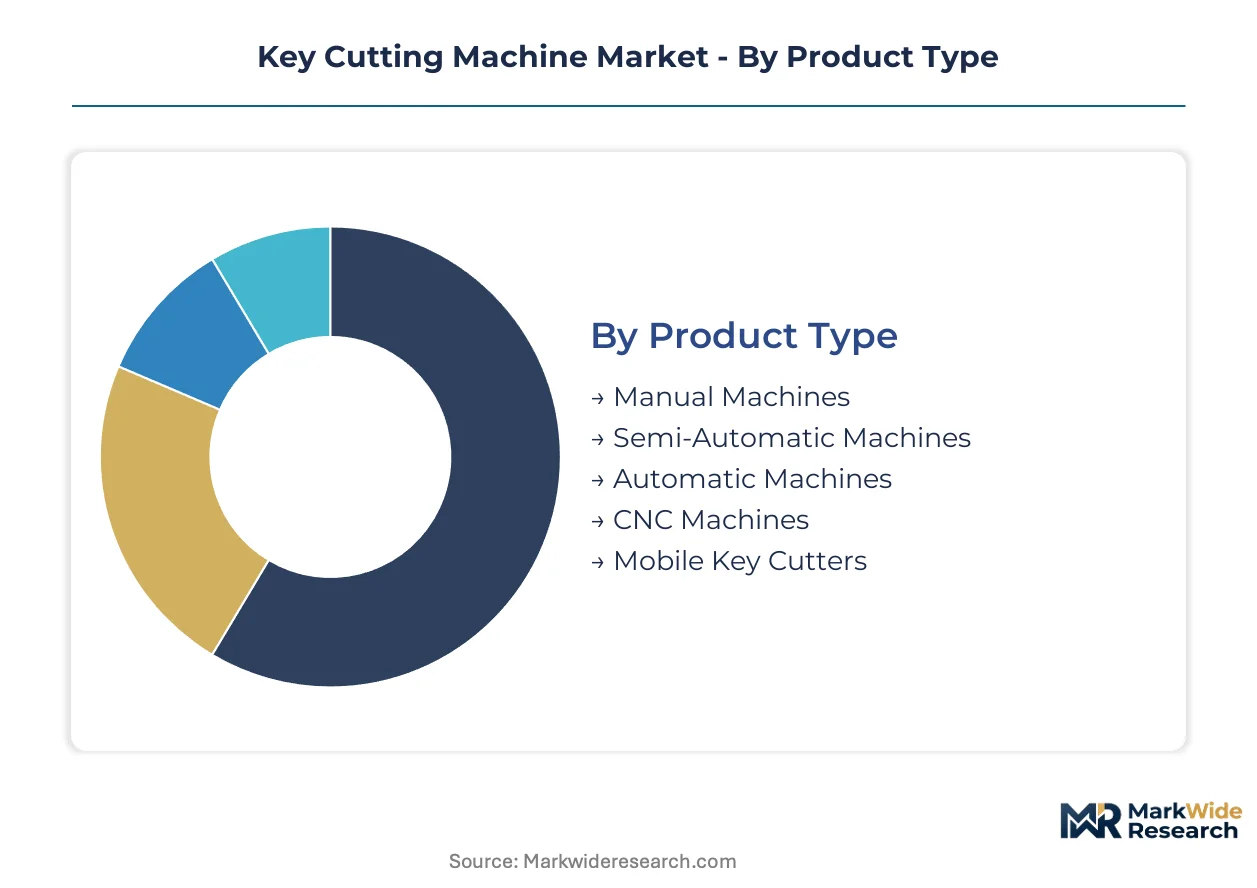
Equipment differentiation across the key cutting machine market determines capital deployment thresholds, operator skill requirements, and service revenue potential. Segmentation reveals where laser automation commands premium positioning versus where compact semi-automatic units saturate volume channels.
Product Type:
Capital intensity varies sharply across this dimension, with automated platforms requiring integrated digital decoding systems and precision motion control architectures that multiply upfront investment against manual alternatives.
- Automatic Machines:These platforms integrate electronic code databases with servo-driven cutter positioning to eliminate manual bitting interpretation. Fleet operators in Germany specify these units for dealership service centers where throughput consistency outweighs labor cost considerations.
- CNC Machines:Multi-axis control architectures unify laser, milling, and grinding functions within single safety enclosures. United States municipal procurement channels favor these hybrid systems to consolidate vendor relationships and reduce floor space requirements.
- Manual Machines:Hand-cranked mechanical platforms serve price-sensitive residential locksmiths with minimal electronic components.
- Semi-Automatic Machines:Compact electromechanical designs anchor hardware store densification in Chinese tier-two cities.
- Mobile Key Cutters:Battery-powered portable units face FCC wireless compliance delays that disadvantage smaller vendors.
Automatic machines absorb the bulk of installed capacity; CNC machines are expanding most quickly.
Technology:
Material removal methods segment by tolerance requirements and key geometry complexity, with non-contact systems displacing mechanical approaches in automotive applications.
- Laser Cutting:Ablation systems achieve sub-0.03 millimeter tolerances through non-contact material removal. Sidewinder and dimple key proliferation across United States fleet maintenance depots accelerates displacement of traditional milling.
- Milling Cutting:Rotary carbide cutters remain standard for residential key duplication where legacy bitting specifications dominate. Raw material concentration in Chinese tungsten carbide powder metallurgy exposes margin stability to export quota friction.
- Impressioning:Manual technique for originating keys without code data serves emergency service providers.
- Jig & Clamp:Mechanical holding fixtures support high-volume duplication in institutional security environments.
- Duplication Cutting:Trace-follower mechanisms anchor hardware store service counters.
Milling cutting retains the largest installed base; laser cutting is gaining share fastest.
Application:
Channel structure determines equipment specification, with dealership chains and fleet operators driving standardization toward automated platforms while independent retail favors compact footprint designs.
- Car Dealerships:Service centers require CE-marked automatic units with integrated manufacturer code databases. EU Machinery Directive enforcement through German market surveillance authorities filters non-compliant shipments.
- Hardware Stores:High-volume retail channels in China bundle key cutting with smart lock consultations. Property management companies negotiate residential compound master key contracts that convert transactional visits into security solution engagements.
- Locksmith Shops:Independent operators face pressure to diversify into access control integration.
- Security Service Providers:Institutional procurement channels specify ISO 9001-certified equipment.
- Real Estate Agencies:Turnover-driven duplication demand favors rapid-response service models.
Hardware stores deploy the most units by volume; car dealerships are climbing the fastest.
End User:
Customer type segmentation reflects diverging technical capabilities, with automotive specialists commanding premium pricing against residential operators facing labor rate compression.
- Automotive Key Specialists:These operators invest in laser-capable platforms to serve sidewinder and transponder key proliferation. Technical skill compression from automatic decoding capabilities simultaneously depresses labor rates and slows capital payback justification.
- Commercial Locksmiths:Cross-training requirements spanning mechanical tolerances and embedded software extend recruitment cycles. Cloud-connected fleet management with predictive maintenance contracts unifies hardware sales with recurring revenue.
- Residential Locksmiths:Price-sensitive segment concentrated in manual and semi-automatic equipment.
- Institutional Security Teams:Government procurement channels mandate ISO 9001 certification.
- Emergency Service Providers:Mobile response requirements favor portable battery-powered units.
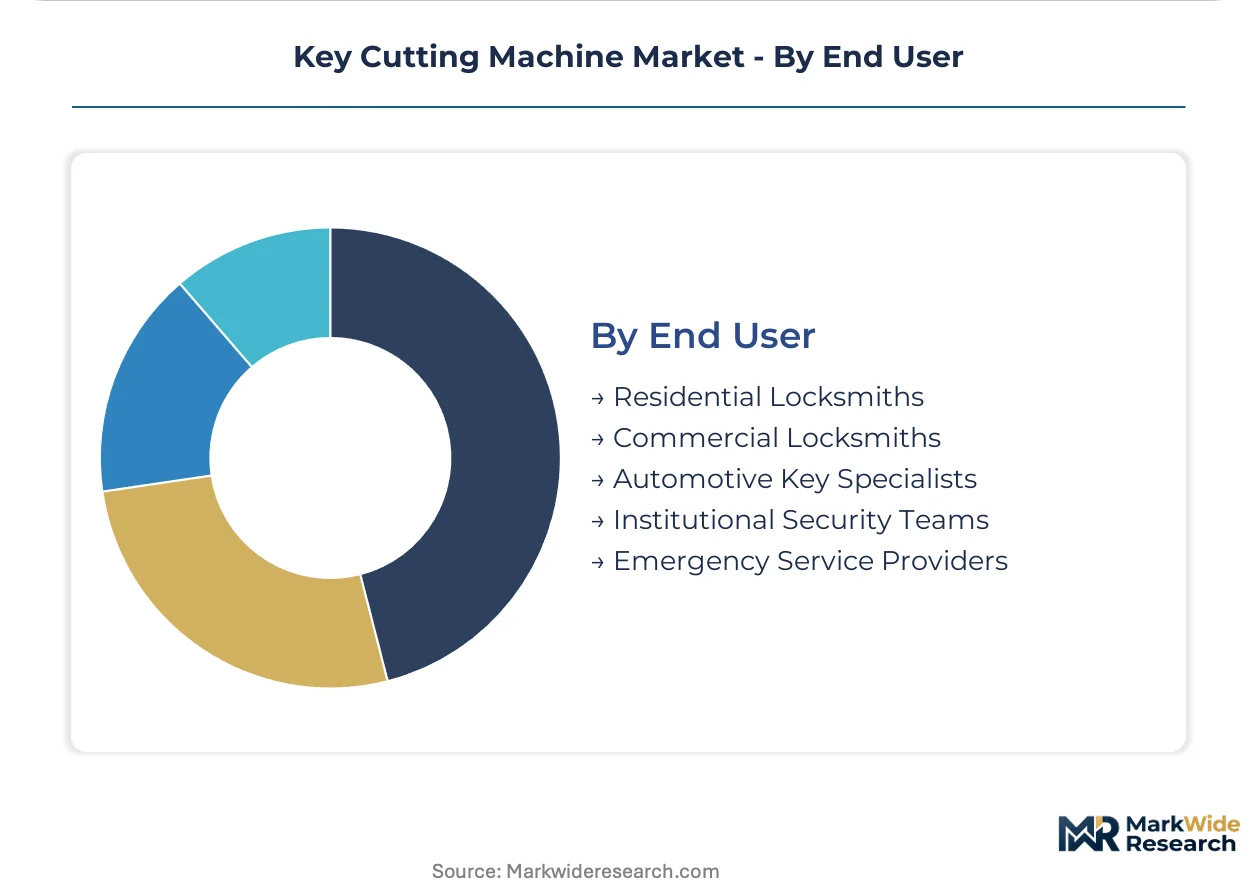
Commercial locksmiths represent the largest customer base; automotive key specialists show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Guangzhou concentrate key cutting machine manufacturing, with export-oriented clusters serving locksmith cooperatives across three continents. Tax incentives for precision machinery producers in these zones accelerate capacity expansion for laser-capable platforms.
China
Hardware store densification in tier-two and tier-three cities drives compact semi-automatic equipment demand. MIIT certification requirements for electromechanical devices filter substandard imports from neighboring manufacturing hubs. Guangdong province hosts the densest concentration of tungsten carbide cutter suppliers, exposing margin stability to export quota fluctuations.
Germany
Automotive key specialists across Bavaria and Baden-Württemberg upgrade service centers with CE-marked automatic units. EU Machinery Directive enforcement through KBA-notified bodies in Munich extends certification timelines for non-compliant shipments. Stuttgart's industrial automation cluster supplies servo-driven motion control systems to domestic equipment manufacturers.
United States
Fleet operators and municipal procurement channels specify multi-axis CNC systems to consolidate vendor relationships. FCC regulations govern wireless programming interfaces in mobile key cutter units, disadvantaging smaller vendors without dedicated regulatory affairs teams. Texas and California anchor the highest concentration of locksmith cooperatives modernizing duplication infrastructure.
India
Institutional security procurement channels seek ISO 9001-certified equipment amid absent BIS standardization for key cutting machinery. CDSCO workplace safety guidelines apply indirectly to machine operator environments. Maharashtra's industrial security market in Mumbai-Pune corridor shows fastest equipment upgrade cycles among commercial locksmiths.
Japan
METI subsidies for precision manufacturing equipment support adoption of laser ablation systems achieving sub-0.03 millimeter tolerances. JIS standards for electromechanical safety shape supplier qualification for institutional buyers. Osaka's automotive service cluster leads dealership service center modernization for transponder and sidewinder key replication.
Key Cutting Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base organizes around three strategic archetypes: laser automation specialists commanding premium positioning, compact semi-automatic fabricators saturating volume retail channels, and diversified security equipment suppliers leveraging cross-selling infrastructure. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as labor shortages reshape locksmith shop economics.
Among Asian equipment fabricators, Kukai and 2M2 Technology occupy positions within the compact semi-automatic tier serving high-volume hardware store channels. Silca represents the laser automation archetype through in-house manufacturing capabilities that sustain margin control across premium locksmith segments. HPC anchors North American distribution depth through locksmith cooperative and institutional procurement relationships.
| Leading Market Players |
|---|
| Black Widow |
| Kukai |
| Silca |
| Ninja |
| HPC |
| Keyline |
| Triton |
| 2M2 Technology |
| Xhorse |
| Others |
Pricing and Supply Chain Analysis
EU Machinery Directive CE marking gates qualified supply access and premium-tier pricing power, filtering non-compliant equipment from German and French locksmith cooperatives while compressing margins for manufacturers lacking notified body certification. This environmental and safety mandate forces pricing stratification across certification tiers, with compliant automatic machine suppliers capturing protected margin pools.
Pricing Analysis
Short lead-time premiums of 15-20 percent apply to CE-marked automatic units facing German KBA inspection delays, while spot inventory of semi-automatic designs trades at discounts in Chinese hardware store channels. Three-tier pricing structure across premium laser-capable, standard CNC hybrid, and economy manual equipment reflects certification grade and after-sales service bundling. Cost compression in economy tiers intensifies because tungsten carbide cutter supply volatility feeds raw material uncertainty into margin structures. Fleet operators and dealership chains show lowest price sensitivity due to throughput consistency requirements, whereas independent residential locksmiths face acute margin pressure from labor rate compression.
Supply Chain Analysis
Reverse-logistics flows for laser cutting head refurbishment and CNC controller remanufacturing extend equipment lifecycle value, with Silca and Keyline operating captive refurbishment centers in Italy and Germany. Manufacturing concentrates in China, Germany, and Italy, with Guangdong province hosting the densest tungsten carbide powder metallurgy clusters. Raw material dependencies center on Chinese tungsten carbide cutters, Japanese servo motors, and German precision bearings. Single-source vulnerability in Chinese cutter supply exposes margin stability to export quota friction and geopolitical disruption. Distribution runs through locksmith cooperative networks in North America, hardware store chains in China, and dealership service center procurement channels in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as CE marking enforcement and mechatronics talent scarcity force weaker players without notified body relationships or field service capabilities toward exit.
For Market Incumbents:Cement market position through backward integration into laser cutting head manufacturing and captive tungsten carbide cutter supply, mirroring Silca's in-house production model. Add certified service capacity in Stuttgart and Munich to compress KBA inspection delay exposure. Defend against emerging Asian compact semi-automatic entrants by locking exclusive procurement contracts with German automotive dealership chains.
For New Entrants and Emerging Players:Enter via India's institutional security procurement channels where absent BIS standardization creates first-mover advantage for ISO 9001-certified suppliers. Target Maharashtra's Mumbai-Pune corridor commercial locksmith market, which shows fastest equipment upgrade cycles. Pursue cloud-connected fleet management software bundling as the primary go-to-market angle to displace legacy hardware-only vendors.
For Investors and Strategic Acquirers:Unannounced factory inspection delays exceeding eight weeks at German market surveillance authorities is the leading indicator that regulatory compliance capabilities are becoming the primary valuation differentiator. Position acquisitions around laser automation specialists with in-house manufacturing and existing notified body relationships. Monitor CE marking enforcement intensity and KBA inspection backlog duration as early signals of consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Certification | Compresses German KBA inspection delays from 8-12 weeks to predictable clearance timelines. |
| Laser Cutting Head Backward Integration | Sustains margin control against tungsten carbide cutter supply volatility from Chinese sources. |
| Cloud-Connected Fleet Management Launch | Unifies hardware sales with recurring predictive maintenance revenue across locksmith networks. |
| Compact Semi-Automatic Geographic Expansion | Saturates Chinese tier-two and tier-three hardware store channels anchoring foot traffic. |
| Multi-Axis CNC Hybrid Platform Development | Consolidates laser, milling, and grinding functions to reduce floor space for US fleet operators. |
Research Methodology
Multi-period observation of equipment upgrade cycles, CE marking enforcement intensity, and laser technology adoption rates anchored the trend analysis, supplemented by interviews with automotive key specialists, commercial locksmith operators, hardware store procurement managers, and institutional security directors. Secondary validation drew from EU Machinery Directive implementation reports, MIIT electromechanical device certification databases, FCC wireless equipment authorization filings, and customs trade data on tungsten carbide cutter flows. Bottom-up channel volume estimates triangulated against top-down capital expenditure patterns across dealership service centers and fleet maintenance depots.
Segment-weighting across product type, technology, application, and end user dimensions shaped the analytical framework over the projection horizon. Automatic, CNC, semi-automatic, and manual equipment categories were modeled separately with technology transitions between laser and milling cutting systems tracked. End-user segmentation captured diverging price sensitivity between automotive specialists and residential operators. CAGRs were derived from installed base replacement cycles, fleet operator modernization timelines, and hardware store densification rates in Chinese tier-two cities.
Revisions become necessary when CE marking enforcement intensity shifts, tungsten carbide export quotas fluctuate, or FCC wireless compliance timelines extend unexpectedly. Forecasts reflect assumptions regarding regulatory stability, raw material supply continuity, and locksmith labor market conditions. Practitioners should monitor KBA inspection backlog duration, Chinese powder metallurgy facility operating rates, and mechatronics engineering salary inflation for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hydraulic Tools Market
Tools
Theodolite Market
Tools
Multi Spindle Machines Market
Tools
Mechanical Hand Tools Market
Tools
Cordless Impact Wrench Market
Tools
Indexable Tool Inserts Market
Tools
Flooring Tools Market
Tools
Diamond Core Drilling Market
Tools
Machine Tools Market
Tools
Spindle Shaper Market
Tools
Cordless Power Drill Market
Tools
Mechanical Puller Market
Tools
Hydraulic Tools and Equipment Market
Tools
Foldable Ladder Market
Tools
Automatic Lathe Machines Market
Tools
Stationary Wood Planer Market