
 Boring Tools Market | 2026-2036
Boring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Boring Tools Market Analysis
Carbide is repositioning high-speed steel across precision metal boring applications, as longer tool life and higher cutting speeds reduce changeover downtime in automated machining centers. Sandvik AB leverages its captive carbide substrate production to anchor supply security for aerospace tier-one suppliers. Kennametal Inc. competes through specialized geometries for difficult-to-machine alloys, while Mitsubishi Materials Corporation dominates coated-grade development for Japanese automotive powertrain operations.
Boring tools are cutting instruments designed to enlarge or finish pre-drilled holes to exact dimensional tolerances, typically featuring single-point or multi-point cutting edges with rake angles optimized for specific workpiece materials and operating at spindle speeds from hundreds to tens of thousands of RPM depending on diameter and material. Twist drill bits retain the largest volume share across general-purpose metalworking and construction, while carbide inserts command the highest margin pools in aerospace and die-mold finishing where tool life directly determines throughput economics. Metal boring applications lead absolute demand by value, though plastic drilling segments in medical device manufacturing are gaining structural importance as multi-material assemblies proliferate.
FDA device manufacturing regulations and OSHA metalworking fluid exposure limits in the United States, alongside REACH chemical restrictions and CE machinery directives in Europe, are elevating compliance costs for coating formulations and coolant system integration. Japan's METI industrial standards and China's GB certification requirements for cutting tools are fragmentating market access protocols across major manufacturing jurisdictions. Stakeholders must monitor evolving dual-use export controls on advanced carbide substrates and assess localized production strategies before capacity commitments solidify.
Market Dynamics
Carbide substrate supply concentration in China and tungsten sourcing bottlenecks are forcing boring tool manufacturers to reconfigure raw material procurement and captive production strategies across aerospace and automotive supply chains.
Growth Catalysts
- REACH-compliant coating mandates:European aerospace tier-one suppliers now require ECHA-registered chemistries, accelerating supplier qualification cycles for compliant coating houses.
- Titanium airframe boring demand:German and Japanese precision machining clusters are expanding dedicated boring cell capacity for next-generation commercial aircraft programs.
- Carbide insert geometry advances:Multi-point cutting edge designs with optimized rake angles are extending tool life in automated machining centers, reducing changeover frequency.
Market Restraints
- Tungsten carbide powder volatility:Raw material price swings and Chinese export licensing restrictions create input cost instability for substrate-dependent producers.
- High-speed steel substitution ceiling:Legacy equipment in general-purpose metalworking shops limits carbide penetration in cost-sensitive, low-volume applications.
- Dual-use export controls:Advanced carbide substrate classifications under multilateral regimes restrict technology transfer to certain manufacturing jurisdictions.
Strategic Opportunities
- China's eastern manufacturing corridor:Domestic tool producers in Jiangsu and Zhejiang provinces are capturing high-volume metalworking share previously held by imported brands.
- Medical device multi-material drilling:Plastic boring segments for implantable device assemblies represent underdeveloped margin pools with distinct certification requirements.
- ISO 13399 tool data standardization:Digital tool libraries are enabling predictive maintenance integration with machine tool OEM platforms.
Industry Challenges
- Coating formulation R&D timelines:REACH registration dossiers and EPA metalworking fluid exposure compliance require 18-24 month certification cycles before commercial deployment.
- Precision boring operator scarcity:CNC programming expertise for difficult-to-machine alloys remains concentrated among aging workforces in mature manufacturing economies.
- Legacy coolant system integration:Minimum Quantity Lubrication retrofits face compatibility constraints with existing machine tool infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boring Tools Market |
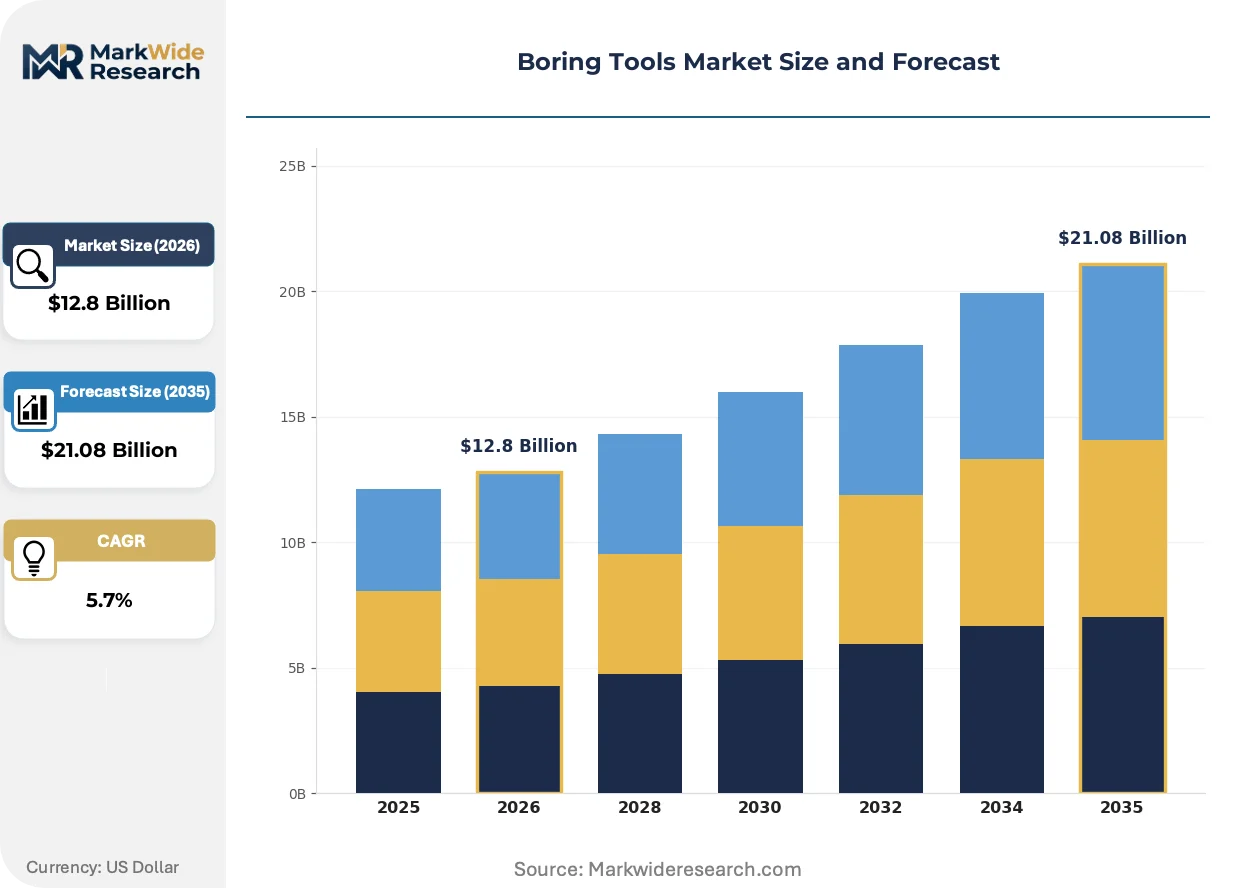
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spade Bits, Twist Drill Bits, Hole Saws, Core Bits End User: Construction, Automotive, Aerospace, Metalworking Material: High-Speed Steel, Carbide, Cobalt, Titanium Application: Woodworking, Metal Boring, Plastic Drilling, Concrete Drilling |
| Companies Covered | Sandvik AB, Kennametal Inc., BIG DAISHOWA Seiki Co., Ltd., Allied Machine & Engineering Corp., OSG Corporation, Mitsubishi Materials Corporation, Nachi-Fujikoshi Corp., KOMET Deutschland GmbH, Cogsdill Tool Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boring Tools Market Emerging Trajectories
Digital tool data exchange standards and predictive maintenance platforms are converging with advanced substrate materials to reshape how boring tool performance is specified, procured, and monetized across precision manufacturing.
Polycrystalline diamond compact inserts are absorbing ultra-precision finishing workloads previously assigned to conventional carbide grades. Japanese automotive powertrain operations are adopting these inserts for hardened steel boring at spindle speeds exceeding conventional limits. The technology is absorbing margin pools in die-mold finishing where single-digit micron tolerances determine contract awards.
EU F-Gas Regulation phase-down schedules are forcing coolant system redesigns for machining centers using fluorinated greenhouse gas-based temperature control. Equipment OEMs must certify alternative thermal management architectures before 2030 deployment windows. German machine tool builders are accelerating heat pump and liquid nitrogen system development for precision boring applications.
Buyers are consolidating supplier relationships around tool lifecycle cost guarantees rather than unit price minimization. Tier-one aerospace manufacturers in Japan and Germany now specify total cost-per-hole contracts with penalty clauses for unplanned downtime. This contracting shift is most visible in titanium airframe component supply chains where tool failure directly halts production cells.
Boring Tools Market Segmentation
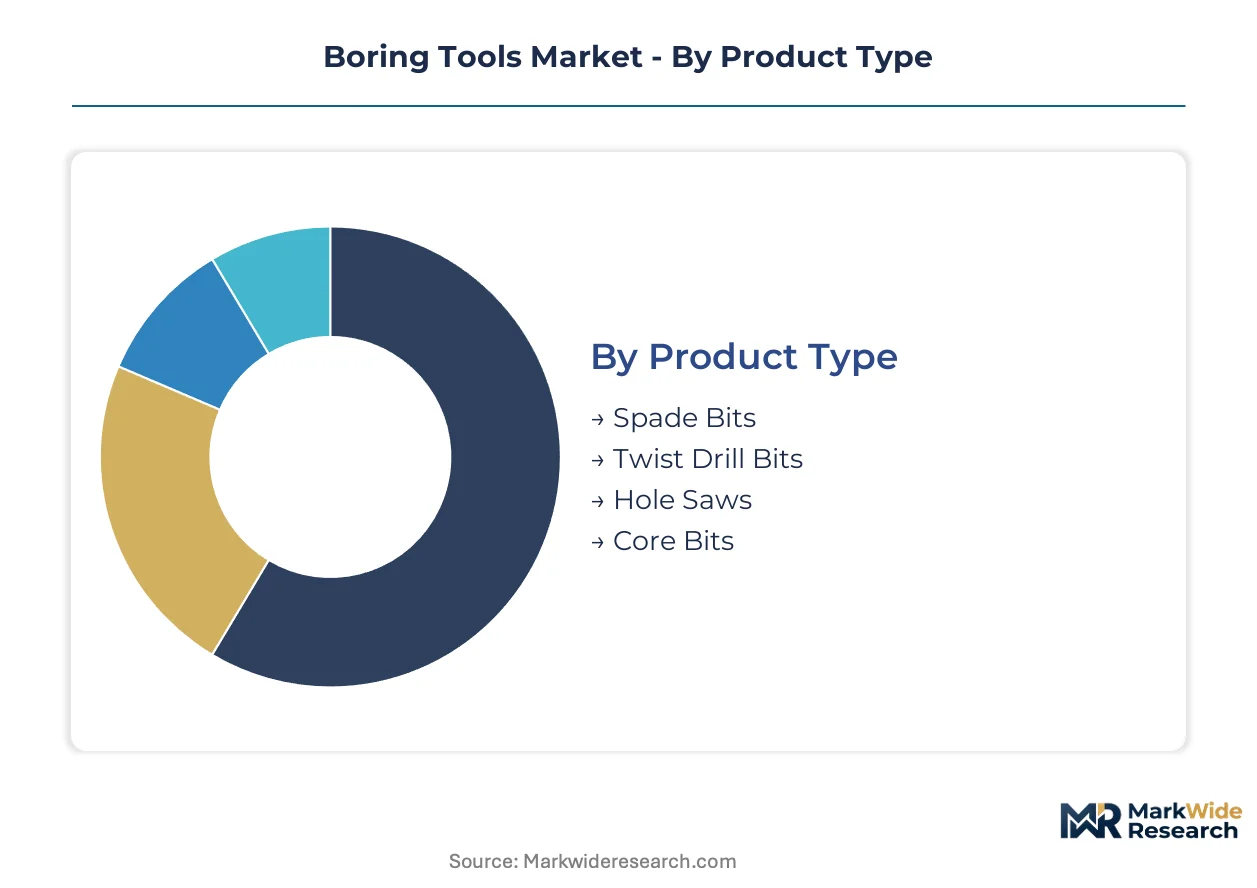
Boring tools fragment across four critical dimensions that determine procurement patterns and margin architecture. Product type governs volume economics while material composition locks in performance tiers for precision applications. End-user concentration and application specificity further stratify supplier relationships across construction, aerospace, and medical device supply chains.
Product Type:
Twist drill bits anchor absolute volume shipments across general-purpose metalworking and construction, while specialized formats command premium positioning in precision finishing cells.
- Twist Drill Bits:Helical flute designs with 118-degree or 135-degree point angles dominate high-throughput drilling across carbon steel, aluminum, and wood substrates. Construction contractors in China's Jiangsu province and German automotive tier-two suppliers consume these in pallet quantities for non-critical hole generation where changeover economics favor disposability over regrinding.
- Spade Bits:Flat paddle configurations with centering spur and cutting spurs at each corner excel in rough woodworking and utility electrical installation. Demand concentrates among North American residential construction contractors and European cabinetry producers where speed in soft materials outweighs finish quality requirements.
- Hole Saws:Annular cutting edges on cylindrical bodies enable large-diameter through-holes in sheet metal and wood without core removal. HVAC installers and electrical contractors specify bi-metal and carbide-toothed variants for conduit and junction box penetrations.
- Core Bits:Hollow cylindrical diamond or carbide segments designed for concrete, masonry, and stone extraction where complete core preservation matters. Infrastructure contractors in Japan and Germany deploy these for reinforced concrete sampling and anchor bolt installation.
Today's leader: Twist drill bits by unit economics. Tomorrow's challenger: Core bits by infrastructure renewal intensity.
End User:
Metalworking and aerospace procurement teams specify lifecycle cost contracts, while construction buyers prioritize unit price minimization on consumable tooling.
- Metalworking:Job shops and OEM captive machining centers drive demand for indexable carbide boring bars and precision-ground solid tools. Japanese automotive powertrain operations and German machine tool builders specify coated grades with predictable wear curves for lights-out manufacturing.
- Aerospace:Tier-one airframe manufacturers and engine OEMs enforce total cost-per-hole contracting with tool life guarantees. Titanium and nickel superalloy boring operations in Japan and Germany require substrate and coating traceability to AS9100 quality systems.
- Construction:General contractors and specialty trades purchase disposable twist and masonry bits in bulk through distributor channels. Chinese domestic brands displace imports in high-volume concrete and wood drilling for residential and commercial building.
- Automotive:Powertrain machining lines and chassis component suppliers balance tool life against changeover downtime in high-volume production. Engine block cylinder boring and transmission case machining represent critical precision applications.
Aerospace commands the steepest expansion trajectory through airframe program ramp-ups. Construction retains the deepest volume base through building stock turnover.
Material:
Carbide substrates separate premium precision applications from commodity metalworking, with coating compatibility determining final grade selection.
- Carbide:Tungsten carbide-cobalt composites with 6-12% binder content deliver hardness exceeding 90 HRA for high-speed machining of difficult alloys. REACH-compliant PVD and CVD coatings from ECHA-registered suppliers extend tool life in German and Japanese aerospace cells.
- High-Speed Steel:M2 and M7 grade tool steels retain dominance in general-purpose drilling where regrindability and toughness outweigh absolute hardness. Legacy equipment in cost-sensitive job shops limits carbide substitution despite superior speed capability.
- Cobalt:High-cobalt M35 and M42 grades offer enhanced red hardness for stainless steel and high-temperature alloy drilling where HSS fails but carbide fractures. Medical device manufacturers specify these for surgical instrument machining.
- Titanium:Titanium nitride and titanium aluminum nitride coatings deposited over carbide or HSS substrates reduce friction and extend edge life. Coating house qualification cycles span 18-24 months under FDA and EPA compliance protocols.
Carbide owns the premium tier by performance metrics. High-speed steel defends the volume tier by capital equipment inertia.
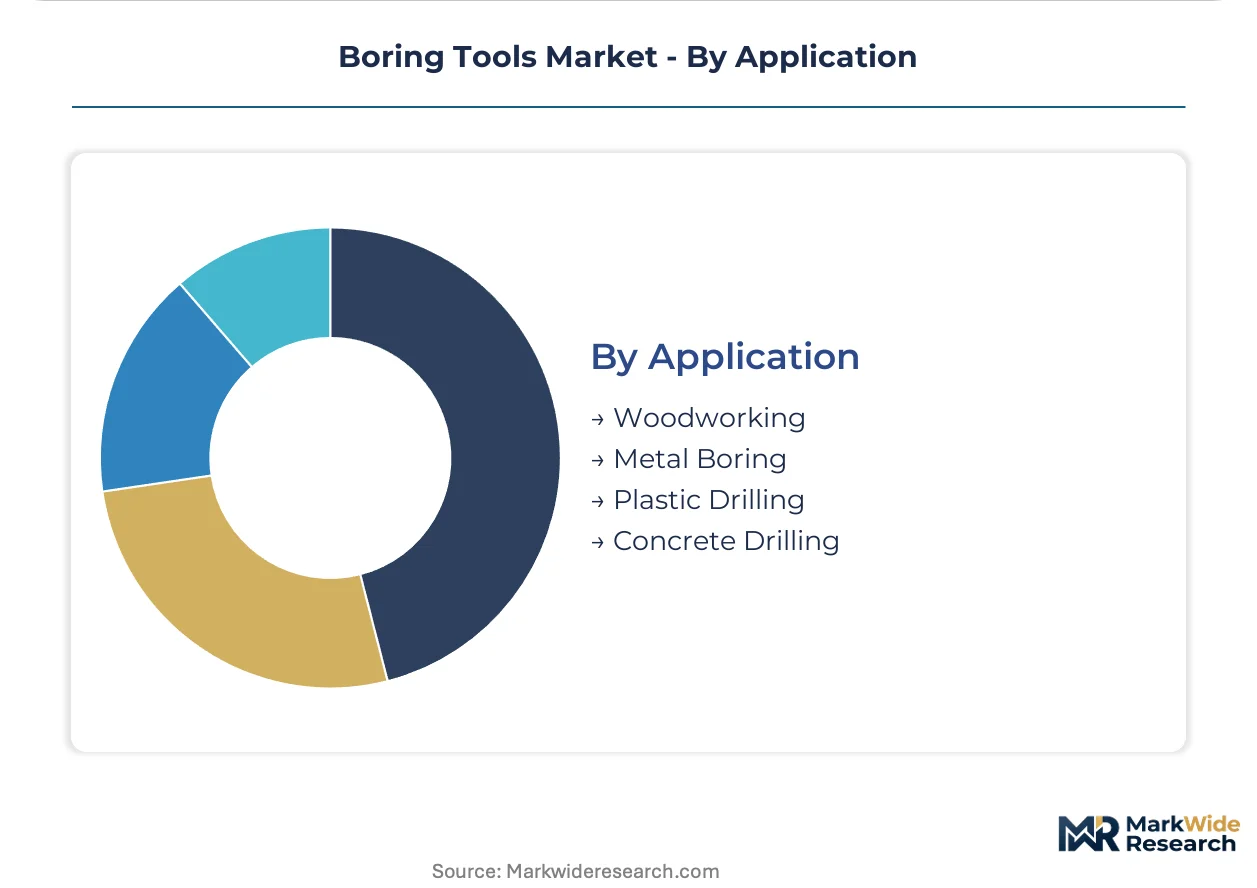
Application:
Metal boring generates absolute value while plastic drilling emerges as a distinct certification-intensive segment for medical device assembly.
- Metal Boring:Precision finishing of pre-drilled holes to tight tolerances in ferrous and non-ferrous alloys. Automotive powertrain and aerospace structural components demand single-digit micron repeatability with statistical process control.
- Plastic Drilling:Specialized geometries with high rake angles and polished flutes prevent melting and burr formation in thermoplastics and thermosets. Implantable medical device manufacturers face FDA device regulations and distinct material compatibility requirements.
- Woodworking:Spade bits, brad-point drills, and Forstner cutters for furniture, cabinetry, and structural timber. European and North American residential construction drives seasonal demand patterns.
- Concrete Drilling:Masonry bits with carbide inserts and diamond core tools for reinforced concrete penetration. Infrastructure maintenance and new construction in China absorb volume shipments.
Metal boring dominates current procurement value. Plastic drilling gains fastest by multi-material medical device proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision machining clusters anchor demand concentration for aerospace-grade boring tools, with regulatory pressure and automotive powertrain investments redistributing manufacturing capacity across four additional industrial economies.
United States
FDA device manufacturing regulations and OSHA metalworking fluid exposure limits tighten compliance requirements for coating formulations. EPA registration timelines for new chemistries extend supplier qualification cycles to 18-24 months. Precision machining corridors in Connecticut and Ohio absorb carbide insert volumes for medical device and aerospace subcontracting.
Germany
REACH-compliant coating mandates from ECHA accelerate supplier transitions to registered chemistries for aerospace tier-one contracts. EU F-Gas Regulation phase-down schedules force coolant system redesigns for machining centers by 2030. Stuttgart and Munich precision engineering clusters expand dedicated boring cell capacity for next-generation commercial aircraft programs.
Japan
METI industrial standards and JIS certification requirements fragment market access protocols for imported cutting tools. Automotive powertrain operations in Aichi and Shizuoka prefectures dominate coated-grade consumption for hardened steel machining. Aging CNC programming expertise concentrates among workforces in Nagoya and Hamamatsu manufacturing belts.
China
GB certification requirements and dual carbon goals redirect domestic tool producer R&D budgets toward REACH-equivalent coating development. Tungsten carbide powder supply concentration in Jiangxi and Hunan provinces creates input cost volatility for substrate-dependent manufacturers. Jiangsu and Zhejiang province tool producers displace imported brands in high-volume metalworking applications.
India
BIS standards and PLI scheme incentives for capital goods manufacturing attract boring tool supplier establishment. Automotive component machining in Pune and Chennai industrial corridors drives indexable insert demand. Domestic tool producers in Gujarat and Haryana capture share in general-purpose metalworking segments previously served by imports.
Boring Tools Market Vendor Landscape
Capacity expansion dominates the current landscape as substrate supply constraints force manufacturers toward captive production strategies. The vendor base stratifies across three tiers: integrated carbide substrate producers, specialized geometry designers, and regional volume fabricators. Consolidation pressure concentrates among mid-scale coating houses facing REACH registration cost barriers. Technology licensing agreements and backward integration into tungsten sourcing represent the two dominant competitive vectors reshaping supplier positioning.
Among Sweden-based integrated manufacturers, Sandvik AB occupies a position exemplifying captive carbide substrate control. Kennametal Inc. represents the specialized geometry archetype for difficult-to-machine alloys. Mitsubishi Materials Corporation anchors the coated-grade development tier for precision automotive applications.
| Leading Market Players |
|---|
| Sandvik AB |
| Kennametal Inc. |
| BIG DAISHOWA Seiki Co., Ltd. |
| Allied Machine & Engineering Corp. |
| OSG Corporation |
| Mitsubishi Materials Corporation |
| Nachi-Fujikoshi Corp. |
| KOMET Deutschland GmbH |
| Cogsdill Tool Products Inc. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down schedules gate qualified supply for REACH-compliant coating houses and lock premium-tier pricing access for aerospace tier-one contracts. Buyers without certified thermal management architectures face 18-24 month qualification delays while ECHA-registered suppliers capture margin pools in German and Japanese precision machining clusters.
Pricing Analysis
Input-cost pass-through from tungsten carbide powder volatility anchors contract pricing structures across substrate-dependent producers. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-traceable aerospace grades from general-purpose metalworking inserts and disposable construction bits. Cost compression in standard-tier carbide inserts is intensifying because Chinese domestic brands capture high-volume share in Jiangsu and Zhejiang provinces. Construction contractors exhibit highest price sensitivity, while aerospace procurement teams prioritize total cost-per-hole guarantees over unit minimization.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai coordinate hub-and-spoke patterns for coated-grade inventory positioning. Tungsten carbide powder supply concentrates in China's Jiangxi and Hunan provinces, with cobalt feedstock drawing from the DRC and refined in Belgium. Single-source vulnerability in Chinese substrate production creates input cost instability for manufacturers without captive powder operations. Distribution runs through authorized distributor networks for construction and direct OEM contracts for aerospace tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH-compliant coating mandates and EU F-Gas phase-down schedules continuously elevate qualified supplier barriers and concentrate margin pools among ECHA-registered coating houses.
For Market Incumbents: To counter tungsten carbide powder supply concentration in China, secure captive substrate production through backward integration into Jiangxi or Hunan powder operations, and defend aerospace tier-one relationships through AS9100-traceable coating qualification investments that extend qualification timelines for unregistered competitors. For New Entrants and Emerging Players: Specialized distributors serving medical device manufacturers in Connecticut and Ohio represent the most penetrable channel partner type for plastic boring segments with distinct FDA device regulations, enabling white-space entry through polished-flute geometries and material compatibility certifications absent from general-purpose metalworking portfolios. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale coating houses facing REACH registration cost barriers that exceed standalone revenue bases, with long-term viability hinging on consolidation into platforms with ECHA-registered dossier libraries; watch for dual-use export control expansions on advanced carbide substrates as inflection indicators for geographic production repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Powder | Captive substrate supply insulates Sandvik and Kennametal from Chinese export licensing volatility. |
| REACH-Compliant Coating House Acquisition | ECHA-registered dossier libraries accelerate aerospace tier-one qualification cycles for consolidated platforms. |
| Medical Device Plastic Boring Segment Entry | FDA device regulations create certification moats distinct from commoditized metalworking competition. |
| ISO 13399 Digital Tool Library Development | Predictive maintenance integration with machine tool OEM platforms locks in lifecycle cost contracting. |
| Minimum Quantity Lubrication System Partnership | EU F-Gas Regulation compliance enables 2030 deployment windows for German machine tool builders. |
Methodological Framework
Coverage spans Germany, Japan, China, the United States, and India, with primary inputs from each manufacturing jurisdiction through structured interviews with carbide substrate procurement directors, aerospace tier-one tooling engineers, coating house technical directors, medical device manufacturing managers, and construction distributor category buyers. Secondary validation draws from ECHA registration databases, METI industrial standard filings, GB certification records, customs trade data for tungsten carbide powder flows, and SEC 10-K disclosures from listed tool manufacturers. Bottom-up segment sizing triangulates against top-down manufacturing value-add estimates.
Granularity-level framing models product type, material composition, end-user industry, and application specificity at the country-segment intersection. CAGRs derive from regression analysis against industrial production indices and airframe program ramp schedules across the projection horizon. Forecast inputs incorporate tungsten price volatility assumptions, REACH registration timeline distributions, and automotive powertrain machining intensity by regional production cluster.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual-use export control expansions, Chinese tungsten export licensing shifts, and EU F-Gas Regulation enforcement trajectories. Outputs reflect documented assumptions around substrate supply concentration and regulatory qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Tooling Market
Tools
Tapping Machine Market
Tools
Brazing Torch Market
Tools
Power Nibbler Market
Tools
Reamer Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Engraver Machine Market
Tools
Hand Tools Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Power Tool Gears Market
Tools
Drain Cleaning Equipment Market
Tools
Machine Tools Market
Tools
Gear Cutting Machines Market
Tools
Lathe Machines Market
Tools
Wood Floor Grinding Machine Market
Tools
Portable Milling Machine Market