
 Diamond Hole Saw Market | 2026-2036
Diamond Hole Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Hole Saw Market Analytics
China's Zhejiang and Guangdong manufacturing belts is fragmenting as domestic producers scale carbide-to-diamond conversion capacity alongside multinational incumbents. DeWalt leverages its battery-integrated tool platforms to bundle cordless diamond hole saws with existing contractor ecosystems. Bosch anchors European distribution through its professional power tool service networks. Milwaukee Tool competes on REDLITHIUM battery compatibility across its expanding diamond accessory lineup.
A diamond hole saw is a cylindrical cutting tool with diamond grit electroplated or vacuum-brazed to a steel body, engineered to bore precise holes in hard, brittle materials such as ceramic tile, glass, and reinforced concrete. Wet variants circulate coolant to suppress dust and extend cutting life, while dry variants suit portable job sites without water access. Wet product types command premium pricing in commercial construction due to OSHA silica compliance requirements and extended bit longevity. Material segmentation shows concrete applications dominating volume, though glass and ceramic segments generate higher per-unit margins through specialized precision tooling.
OSHA silica standards and EPA jobsite dust enforcement shape product certification requirements in the United States, while China's GB standards and SAMR quality inspections govern domestic manufacturing compliance. The EU Machinery Directive and REACH chemical regulations influence import specifications for European distribution channels. Stakeholders must monitor regulatory divergence between wet-cutting mandates and emerging dry-system filtration technologies to align R&D spending with compliance trajectories.
Market Dynamics
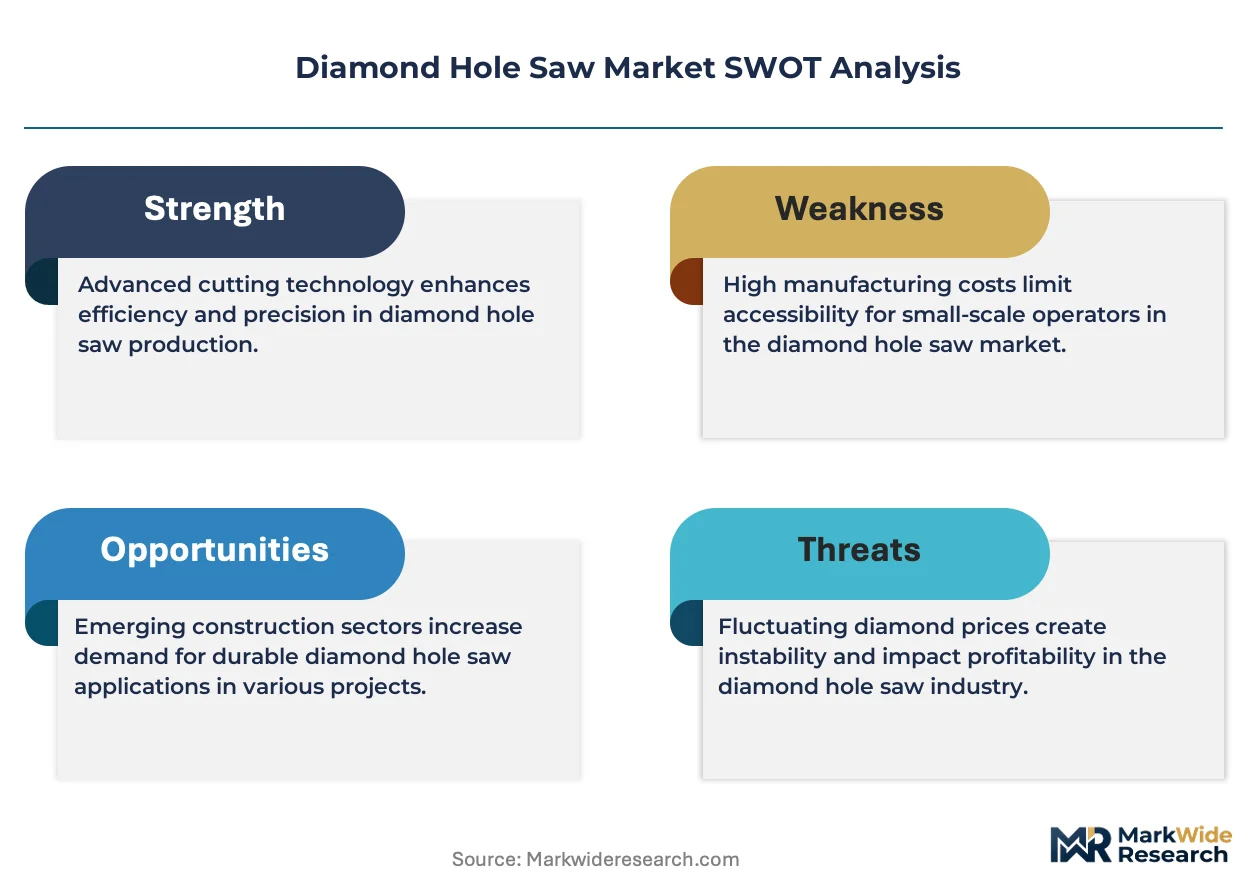
OSHA silica dust enforcement is compressing the viable product mix toward wet-cutting systems, forcing manufacturers to reengineer legacy dry-cutting portfolios or exit commercial construction channels entirely. This regulatory pressure now dictates R&D allocation across the competitive set.
Growth Catalysts
- EPA Silica Standards:Wet-cutting diamond hole saws achieve compliance with tightened jobsite exposure limits, creating mandatory replacement cycles in US commercial construction.
- Ceramic Processing Clusters:China's Zhejiang and Guangdong manufacturing belts generate concentrated bulk demand for precision glass and tile drilling equipment.
- Vacuum-Brazed Bonding:Advanced grit attachment technology extends cutting life in reinforced concrete applications, reducing per-hole tooling costs for contractors.
Market Restraints
- Synthetic Diamond Supply Concentration:Electroplated grit sourcing depends on a narrow supplier base in Henan Province, creating input vulnerability.
- Wet-System Infrastructure Requirements:Water circulation equipment adds capital burden for small-scale contractors and limits job site portability.
- Carbide Tool Substitution:Lower-cost tungsten carbide hole saws retain share in residential DIY and light commercial segments where precision tolerance permits.
Strategic Opportunities
- India Infrastructure Buildout:Metro rail and smart city projects create underpenetrated demand for concrete and tile drilling equipment in Mumbai, Delhi, and Bangalore corridors.
- Battery-Integrated Platforms:Cordless wet-cutting systems converging with REDLITHIUM and comparable battery ecosystems open mobile job site applications previously closed to water-dependent tools.
- EU Green Deal Procurement Mandates:Public construction tenders increasingly specify low-dust equipment, advantaging wet-cutting suppliers with CE-marked, REACH-compliant product lines.
Industry Challenges
- Silica Compliance Certification Timeline:Third-party testing for OSHA and EPA verification extends product launch cycles by 8-14 months.
- Electroplating Skill Scarcity:Vacuum-brazing and grit bonding expertise concentrates among aging technician cohorts in traditional manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Hole Saw Market |
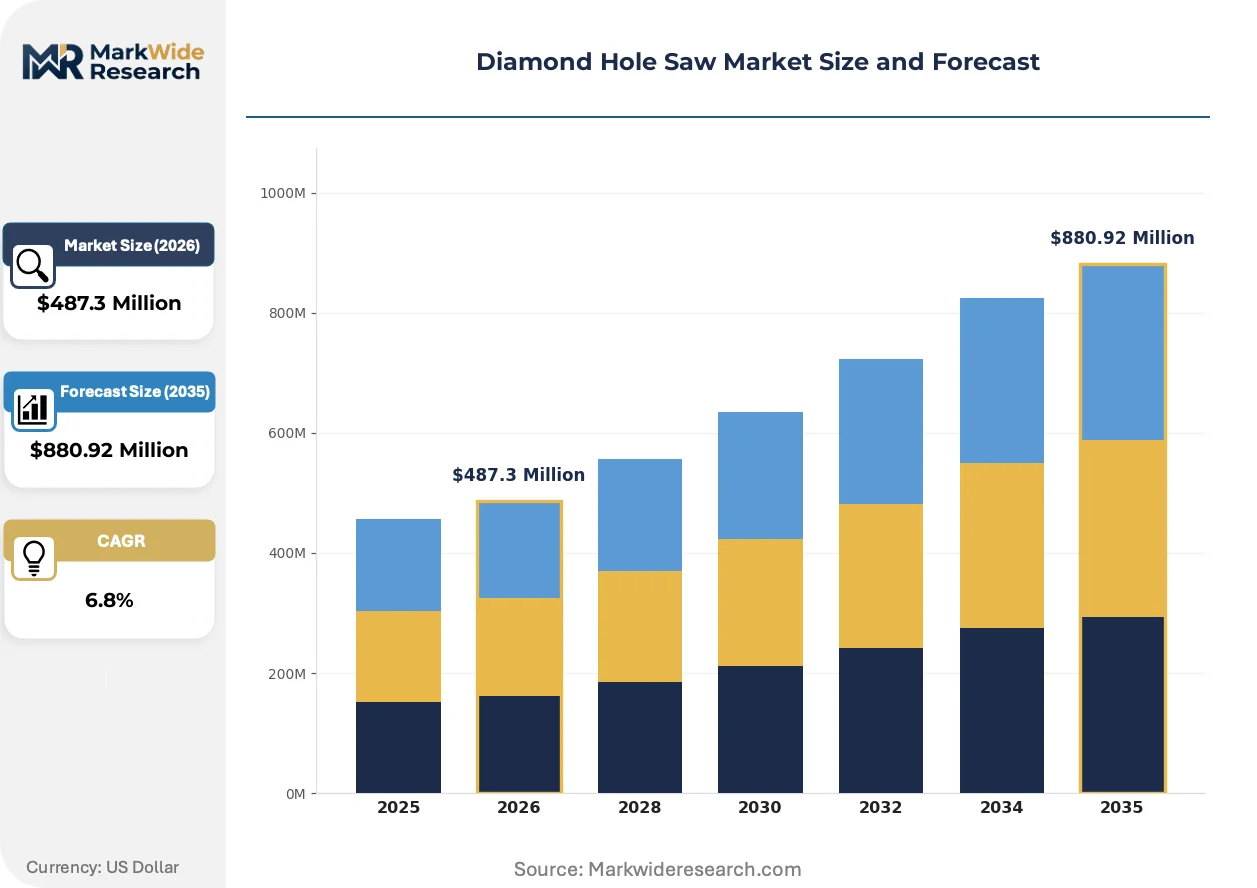
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet, Dry, Bi-metal, Cobalt Application: Construction, Plumbing, Electrical, HVAC Material: Concrete, Glass, Tile, Ceramic End User: Contractors, DIY Enthusiasts, Industrial Users, Retailers |
| Companies Covered | DeWalt, Milwaukee Tool, Bosch, Hilti, Makita, Starrett, Lenox, M.K. Morse, Diablo Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Hole Saw Market Evolving Landscape
Diamond hole saw technology is migrating from electroplated grit attachment toward vacuum-brazed and laser-welded bonding methods that withstand higher thermal loads. This transition is compressing the performance gap between premium and mid-tier product lines.
Vacuum-brazed diamond grit technology is migrating from aerospace and automotive prototyping into commercial construction tooling. Mid-size contractors in the US Southeast and Texas markets are adopting these systems at accelerating rates for high-volume concrete drilling. The technology is migrating from niche specialty applications toward standard job site equipment, eroding price premiums previously commanded by electroplated alternatives.
REACH chemical registration and the EU Machinery Directive are tightening import specifications for diamond tool coatings and steel body compositions. Industrial consequences include mandatory reformulation of bonding agents and extended documentation requirements for CE marking. Wet-cutting product categories face the most acute compliance burden, driving European distributors to consolidate supplier relationships around pre-certified manufacturing partners.
Contractor purchasing behavior is fragmenting across direct distributor relationships and integrated tool platform ecosystems. Professional end-users increasingly bundle diamond hole saw procurement with battery system commitments, displacing standalone accessory sales through traditional hardware channels. This pattern is most visible in North American commercial construction, where DeWalt and Milwaukee tool loyalty programs capture recurring consumable spend.
Diamond Hole Saw Market Segmentation
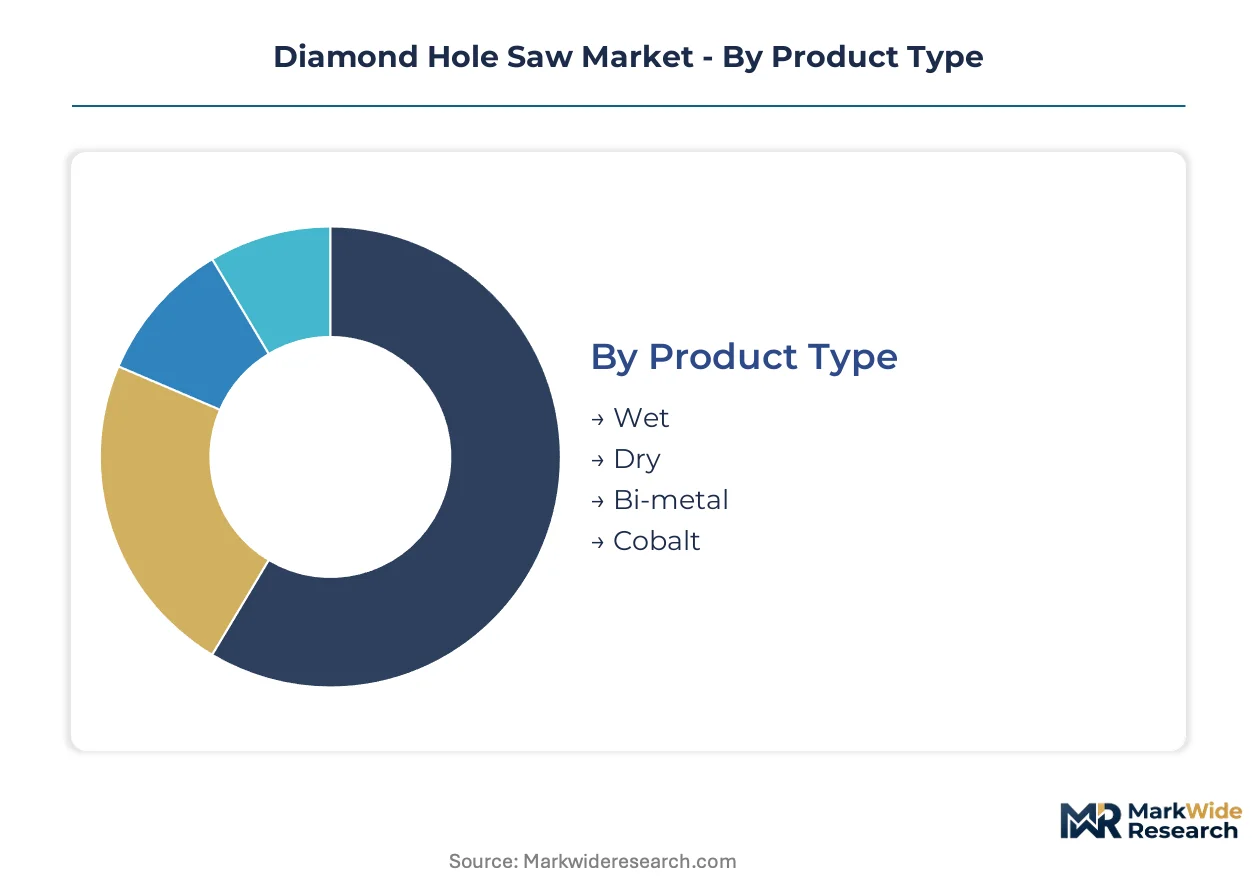
Diamond hole saw procurement patterns diverge sharply across product configurations and end-use contexts. Wet-cutting systems command premium positioning in regulated commercial environments, while dry variants serve mobility-constrained job sites. Material-specific tooling generates tiered margin structures that reshape manufacturer portfolio priorities.
Product Type:
Wet variants turn inventory fastest in commercial construction channels where OSHA silica compliance mandates drive replacement cycles. Dry systems rotate more slowly through retail and residential contractor segments where regulatory pressure remains attenuated.
- Wet:Water-cooled cutting systems suppress respirable silica dust below OSHA permissible exposure limits. Demand concentrates among US commercial construction contractors facing EPA jobsite enforcement, with procurement bundling into professional power tool platforms accelerating turnover.
- Dry:Portable systems operate without water infrastructure, suiting residential renovation and remote job sites. Adoption clusters in Texas and Florida residential markets where contractor mobility outweighs dust suppression requirements, though filtration add-ons are gaining specification.
- Bi-metal:Steel alloy bodies with hardened cutting edges serve softer material applications at lower price points. Demand persists in light commercial plumbing where tile penetration volume does not justify diamond premium.
- Cobalt:High-speed steel formulations with cobalt additive withstand elevated temperatures in metal drilling crossover applications. Specification remains niche among electrical contractors penetrating metal-clad building materials.
Wet systems dominate installed base value in regulated markets. Dry variants are where expansion concentrates in emerging economy infrastructure buildouts.
Application:
Construction absorbs the highest absolute tooling volume, though per-unit margins compress under competitive procurement. Electrical and HVAC applications generate superior returns through specialized diameter requirements and precision tolerances.
- Construction:General commercial and residential building drives bulk consumption of concrete and masonry drilling equipment. China's Zhejiang manufacturing corridor generates concentrated demand for wet-cutting systems in high-rise concrete work.
- Plumbing:Pipe penetration through tile, stone, and concrete walls requires precise diameter control. Specification concentrates among mechanical contractors in US Southeast markets where slab-on-grade construction dominates.
- Electrical:Conduit and junction box cutouts demand clean edge quality to prevent cable abrasion. Demand clusters in India's metro rail electrification projects across Mumbai, Delhi, and Bangalore corridors.
- HVAC:Ductwork penetration through fire-rated assemblies requires dust-controlled cutting methods. Procurement aligns with EU Green Deal mandates specifying low-emission equipment in public building retrofits.
Construction anchors volume throughput. Electrical and HVAC are climbing the fastest as building systems complexity increases.
Material:
Concrete applications generate the highest unit velocity but face severe price competition. Glass and ceramic segments sustain margin premiums through precision engineering requirements and shorter production runs.
- Concrete:Reinforced structural drilling demands vacuum-brazed grit bonding for thermal load tolerance. US Gulf Coast petrochemical construction and Middle East infrastructure projects drive specification of extended-life wet systems.
- Glass:Tempered and laminated glass penetration requires specialized edge chip control and minimal vibration. Guangdong province automotive glass fabrication clusters generate precision tooling demand with stringent defect tolerance.
- Tile:Ceramic and porcelain finishing work in residential and commercial bathrooms drives high-frequency consumable replacement. Italian and Spanish ceramic export manufacturing sustains OEM specification relationships.
- Ceramic:Technical ceramics in industrial applications require diamond grit density optimization for hardness gradients. Demand concentrates in Japanese precision manufacturing and German automotive supplier networks.
Concrete commands the broadest installed base. Glass and ceramic are gaining share fastest as premium finishing standards proliferate.
End User:
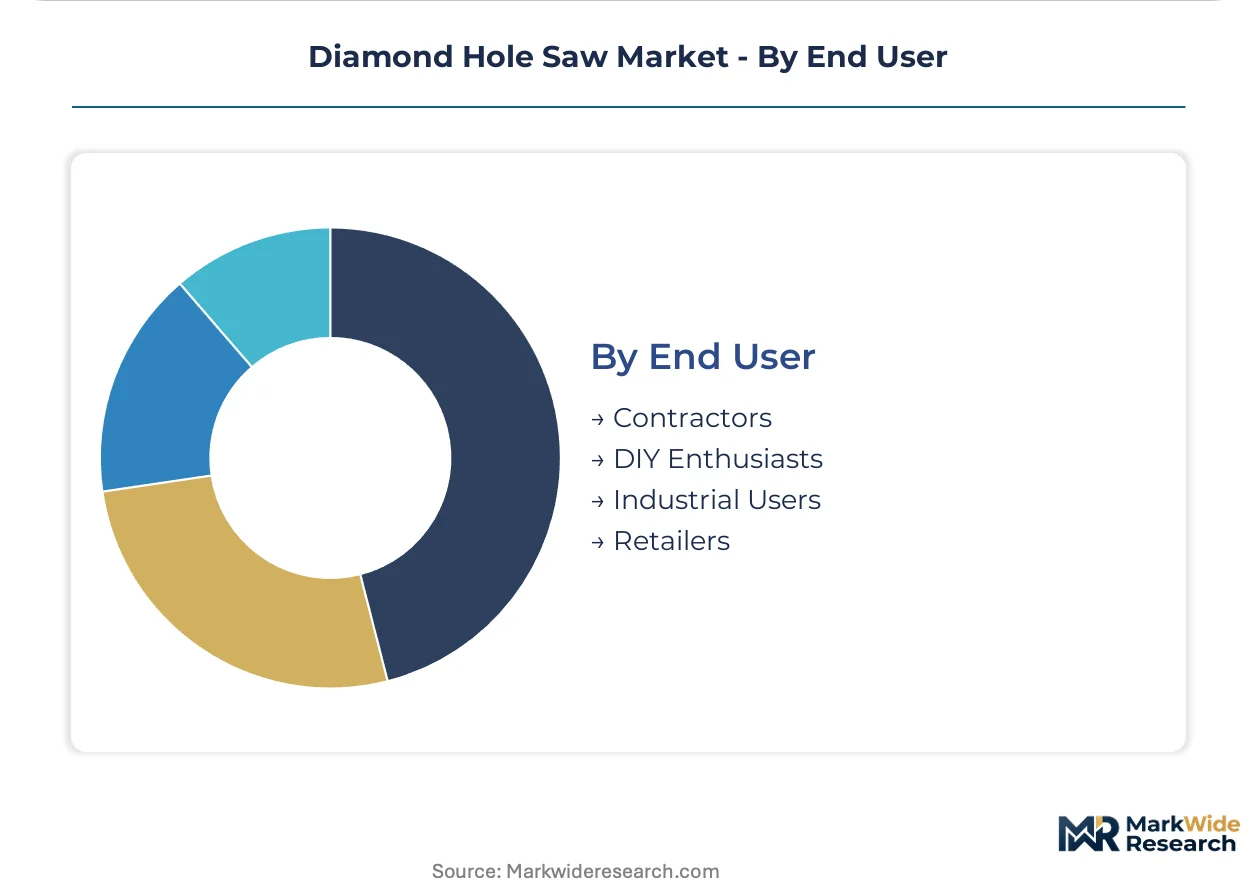
Industrial users and major contractors rotate inventory on preventive maintenance schedules, while DIY enthusiasts purchase episodically with extended replacement intervals. Retailer procurement patterns reflect channel positioning rather than end-use consumption.
- Contractors:Professional construction and trades firms specify wet-cutting systems for regulatory compliance and productivity. US commercial builders consolidate procurement through DeWalt and Milwaukee battery-integrated platform commitments.
- DIY Enthusiasts:Residential renovators prioritize cost accessibility over performance specifications. Demand flows through home improvement retail channels in suburban US and European markets.
- Industrial Users:Manufacturing facilities with in-house maintenance operations standardize on vacuum-brazed systems for life-cycle cost control. China's state-owned enterprise manufacturing bases drive bulk contractual sourcing.
- Retailers:Distributor and dealer networks stock breadth across price tiers to capture walk-up demand. Inventory concentration aligns with regional construction activity density rather than technical specification leadership.
Contractors and industrial users dominate value capture. Retailer channel development is where competitive investment concentrates for market access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's European distribution networks channel wet-cutting diamond hole saws into German industrial construction. China's Belt and Road rail corridors accelerate tool deployment across Central Asian infrastructure projects. Dubai's Jebel Ali port anchors Middle Eastern re-export flows for ceramic and glass fabrication equipment.
United States
Commercial construction contractors in Texas and Florida drive wet-system procurement for silica compliance. OSHA enforcement of permissible exposure limits mandates dust suppression technology on federal projects. Houston's petrochemical construction corridor specifies vacuum-brazed systems for reinforced concrete drilling.
China
Zhejiang and Guangdong manufacturing belts generate concentrated bulk demand for precision glass and tile drilling. SAMR quality inspections and GB standards govern domestic certification requirements for bonded abrasive tools. Shenzhen's electronics fabrication clusters import specialized ceramic drilling equipment for substrate processing.
Germany
EU Green Deal procurement mandates specify low-dust equipment in public building retrofits. REACH chemical registration tightens import specifications for diamond tool coatings and bonding agents. Bavaria's automotive supplier networks demand precision tooling for technical ceramics in powertrain components.
India
Metro rail electrification projects across Mumbai, Delhi, and Bangalore corridors create underpenetrated demand for concrete and tile drilling. BIS certification requirements shape product specifications for infrastructure tenders. Gujarat's ceramic export manufacturing clusters drive OEM relationships with European precision tool suppliers.
United Arab Emirates
NEOM and Red Sea Project construction mandates specify silica-compliant wet-cutting systems for worker safety. MOHAP occupational health regulations align with Gulf standardization efforts for construction equipment. Dubai's Jebel Ali free zone consolidates re-export distribution for African and South Asian markets.
Diamond Hole Saw Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in grit bonding and steel body fabrication. The vendor base separates into battery-integrated tool ecosystems, professional power tool service networks, and standalone accessory manufacturers. Three archetypes dominate: multinational platform owners bundling consumables with battery commitments; regional specialists serving price-sensitive construction segments; and industrial-grade fabricators targeting vacuum-brazed applications. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with R&D allocation shifting toward wet-system compliance certification.
Among US-based platform integrators, DeWalt and Milwaukee Tool represent the battery-ecosystem archetype, anchoring procurement consolidation through cordless platform commitments. Bosch exemplifies the professional service network model, with German-originated GmbH structures supporting European distribution density. These three occupy positions across the premium and mid-tier vectors without exclusive segment lock-in.
| Leading Market Players |
|---|
| DeWalt |
| Milwaukee Tool |
| Bosch |
| Hilti |
| Makita |
| Starrett |
| Lenox |
| M.K. Morse |
| Diablo Tools |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's container throughput cost dynamics compress margins for wet-cutting system imports while amplifying price differentiation between Henan-sourced electroplated grit and vacuum-brazed alternatives. Contractors in Texas and Florida absorb elevated landed costs through volume-commitment purchasing, whereas small-scale residential renovators face sticker shock at distribution endpoints.
Pricing Analysis
Volume-discount tiering separates OEM bulk contracts from retail walk-up purchases by 40-60 points on equivalent SKU specifications. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and battery-platform bundling intensity. Cost compression in mid-tier wet systems is intensifying because domestic Chinese producers are scaling carbide-to-diamond conversion capacity. DIY enthusiasts exhibit highest price sensitivity, while industrial users with preventive maintenance schedules prioritize life-cycle cost over unit outlay.
Supply Chain Analysis
Supplier-financing facilities from Zhejiang manufacturing belt exporters extend 90-120 day terms to European distributors, tightening working capital for incumbents without captive supply arrangements. Synthetic diamond grit production concentrates in Henan Province, China, with secondary vacuum-brazing capacity in Germany and Japan. Bonding agent formulations draw from petrochemical feedstocks in the US Gulf Coast and specialty chemical producers in the Netherlands. Single-source vulnerability in electroplated grit attachment expertise creates bottleneck risk as aging technician cohorts retire. Distribution runs through professional power tool service networks in Europe and battery-integrated platform ecosystems in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through DeWalt and Milwaukee battery-platform procurement consolidation, fragmenting standalone accessory channels and compressing distributor margins.
For Market Incumbents: Build certification moats around OSHA silica compliance and CE marking pathways to lock out unqualified competitors. Accelerate wet-system R&D allocation ahead of EPA enforcement tightening. Secure electroplating technician pipelines through apprenticeship partnerships in traditional manufacturing regions. Vertical integration into Henan Province grit sourcing insulates against supply concentration risk. For New Entrants and Emerging Players: Pursue cordless wet-cutting system development converging with REDLITHIUM-compatible battery architectures. Target India's metro rail electrification corridors where BIS certification requirements have kept multinational penetration shallow. Anchor go-to-market through HVAC contractor specification in EU Green Deal public building retrofits. For Investors and Strategic Acquirers: Vacuum-brazing specialists with automotive crossover expertise represent the most defensible acquisition archetype as thermal-load tolerance becomes standard specification. Long-term viability hinges on wet-system compliance certification infrastructure rather than dry-cutting legacy assets. Watch for OSHA permissible exposure limit revision announcements as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Supply | Henan Province grit sourcing captive supply reduces input vulnerability for wet-system manufacturers. |
| Wet-System Compliance Certification Investment | Third-party OSHA and EPA verification accelerates product launch cycles for commercial construction channels. |
| Battery-Platform Ecosystem Partnership | REDLITHIUM and comparable cordless compatibility opens mobile job site applications previously closed to water-dependent tools. |
| Vacuum-Brazing Capacity Expansion | Thermal-load tolerance technology migration from aerospace prototyping erodes electroplated premium pricing power. |
| EU Green Deal Procurement Alignment | REACH-compliant CE marking captures public construction tender specification in German and Dutch building retrofits. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at petrochemical construction firms, plant engineers in Zhejiang ceramic processing clusters, aftermarket service heads at professional power tool distributors, and OEM procurement teams in automotive glass fabrication. These interviews were refined against secondary validation from SEC 10-K filings, customs and trade data, OSHA enforcement action databases, and EU Machinery Directive implementation records. Bottom-up SKU-level demand modeling and top-down industrial construction spend triangulation anchored volume estimates.
Demand-supply-balance framing across the analysis window incorporated wet-system replacement cycles driven by silica compliance mandates, vacuum-brazing capacity expansion trajectories, and battery-platform ecosystem penetration rates. Segmentation dimensions modeled include product type, material application, end-user archetype, and regional regulatory cluster. CAGRs were derived from installed base turnover velocity and new-build infrastructure pipeline analysis. Forecast inputs included contractor purchasing behavior fragmentation patterns and REACH chemical registration timeline impacts on European import specifications.
Sensitivities concentrate around OSHA permissible exposure limit revisions, Henan Province synthetic diamond supply disruptions, and cordless wet-cutting technology maturation timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and platform ecosystem loyalty program effectiveness. Macroeconomic construction cycle deviation, unexpected regulatory acceleration, or breakthrough dry-system filtration technology would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Quick Release Pins Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Cordless Blind Rivet Gun Market
Tools
Cordless Impact Wrench Market
Tools
Gear Honing Machines Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Multi Spindle Machines Market
Tools
Europe Woodworking Power Tools Market
Tools
Machine Vise Market
Tools
US Chalk Reel and Line Market
Tools
Horizontal Milling Machine Market
Tools
Global DC Torque Tool Market
Tools
Metal Cutting Tools Market
Tools
Global Cordless Power Tools Market
Tools
Wood-Burning Tool Market
Tools
Global Staple Gun Market