
 Automatic Clay Brick Making Machine Market | 2026-2036
Automatic Clay Brick Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Clay Brick Making Machine Market Outlook
Premium-grade vacuum extrusion specifications is reorganizing competitive tiers across the automatic clay brick making machine landscape. Zhengzhou Yingfeng Machinery leverages captive manufacturing scale across Henan province to anchor its position in large-scale extrusion lines. Hydraform differentiates through mobile pressing technology tailored to remote construction sites with limited grid access. Xi'an Brictec Engineering competes on integrated kiln-to-cutter system design, sustaining margins through backward integration into thermal processing equipment.
An automatic clay brick making machine mechanizes the forming, cutting, and initial handling of clay-based masonry units, typically operating at extrusion pressures of 15–40 bar and firing temperatures exceeding 950°C to achieve compressive strengths suitable for load-bearing walls. Fully automatic extrusion systems command the largest installed base among product type categories, though mobile pressing configurations are gaining fastest in frontier construction zones lacking centralized infrastructure. Vacuum processing technology leads margin pools due to its material efficiency and defect reduction, while small-scale semi-automatic units retain dominance in rural manufacturing end-user segments where capital constraints limit technology uptake.
India's BIS clay brick standards, China's GB energy efficiency codes for ceramic production, and the EU F-Gas Regulation on kiln emissions collectively shape equipment specifications and market access thresholds for cross-border suppliers. Compliance with these frameworks now determines eligibility for government-backed housing tenders in multiple jurisdictions. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional product portfolios.
Market Dynamics
Vacuum extrusion technology is consolidating competitive advantage across the automatic clay brick making machine landscape, compressing margins for semi-automatic suppliers while rewarding integrated system providers. China's MIIT efficiency mandates and India's BIS certification requirements are accelerating this bifurcation.
Growth Catalysts
- India's BIS clay brick standards:Mandatory certification for fired clay products is forcing rural manufacturers toward vacuum processing upgrades, expanding the addressable base for fully automatic systems.
- Urban housing programs:State-level affordable housing targets across Gujarat and Maharashtra sustain procurement of large-scale extrusion lines from domestic and cross-border suppliers.
- China's dual carbon goals:MEE emission controls on ceramic production are pushing existing plants toward kiln modernization, creating retrofit demand for integrated thermal processing equipment.
Market Restraints
- Refractory material cost volatility:Magnesia and alumina price swings from Henan province suppliers compress margins for kiln component manufacturers.
- Capital intensity threshold:Vacuum extrusion lines require 2.5-4x the upfront investment of semi-automatic alternatives, excluding small rural fabricators from technology migration.
- EU F-Gas Regulation compliance:Emission controls on kiln insulating gases create certification friction for Chinese and Indian exporters targeting European housing tenders.
Strategic Opportunities
- Bangladesh housing pipeline:Dhaka's urban densification programs lack domestic extrusion capacity, creating import demand for mobile pressing configurations suited to limited grid access.
- PLI scheme alignment:India's production-linked incentives for capital goods manufacturing reward local assembly of automated cutting and handling systems.
- Solar-kiln hybridization:Convergence of photovoltaic thermal systems with traditional firing infrastructure opens frontier sites previously excluded by fuel logistics constraints.
Industry Challenges
- Retrofit integration complexity:Legacy semi-automatic plants face extended downtime during vacuum extrusion upgrades, disrupting contract delivery schedules for housing developers.
- Certification timeline compression:BIS and MIIT parallel approval processes for cross-border equipment create 8-14 month market entry delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Clay Brick Making Machine Market |
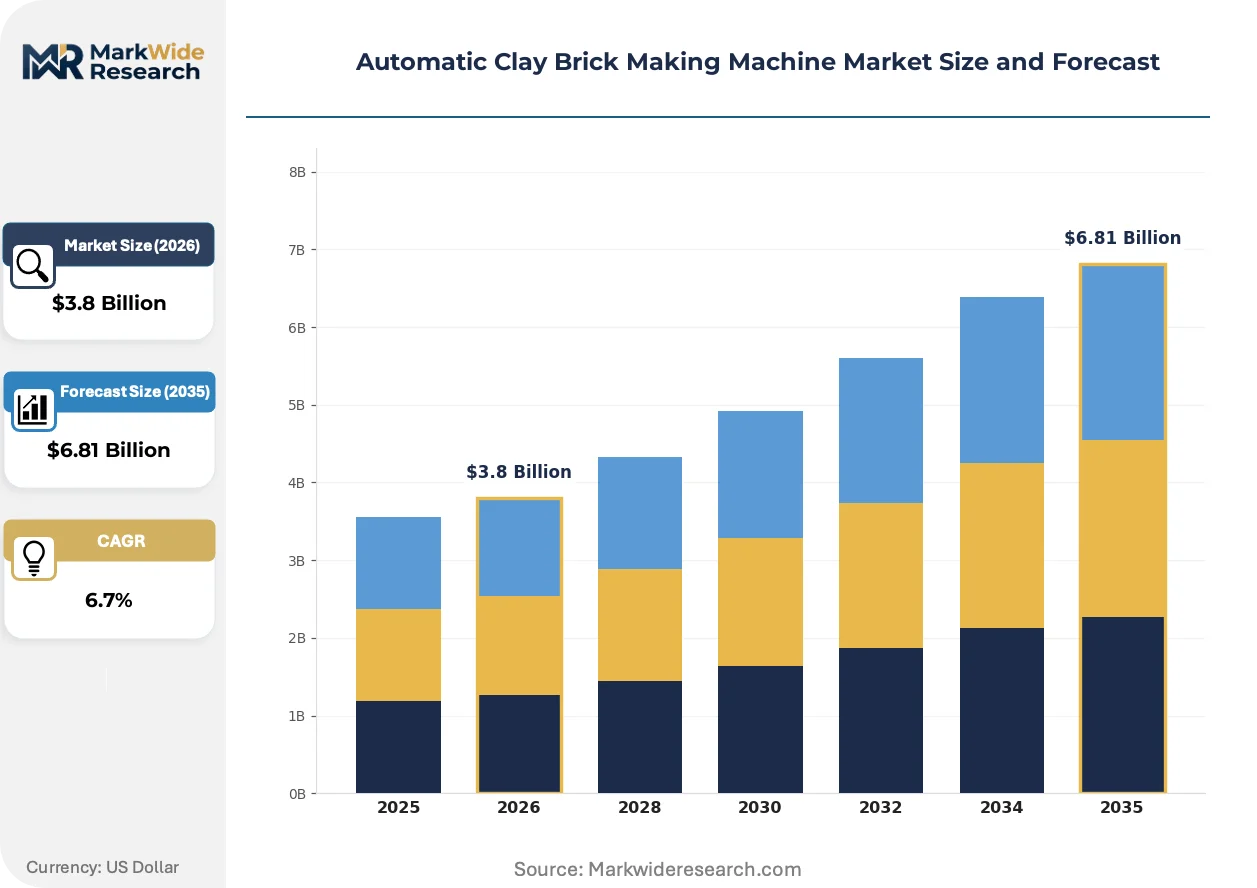
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Mobile End User: Construction, Manufacturing, Engineering, Natural Resource Management Technology: Extrusion, Pressing, Vacuum Processing, Molding Size: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | Zhengzhou Yingfeng Machinery Co., Ltd, Hydraform, Lontto Block Machine, Sadhana Engineering Industries, JC Steele Brick and Block Making Machines, Halstec Engineering Co., Ltd, GM Quangong Machinery (QGM), Press Makina, Xi'an Brictec Engineering Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Clay Brick Making Machine Market Strategic Shifts
Equipment architecture is fragmenting along automation depth and mobility axes, with stationary vacuum extrusion systems competing against containerized pressing units for overlapping project profiles. This divergence reflects diverging infrastructure realities across target construction zones.
Continuous de-airing vacuum extrusion is decomposing the traditional two-stage forming process by integrating mixing, pugging, and wire-cutting into single-pass operations. Large-scale housing developers in India's western corridor are specifying these systems for 50,000+ unit annual contracts. The technology is decomposing demand for standalone pug mill and slug preparation equipment, compressing supplier margins in auxiliary machinery segments.
China's GB energy efficiency codes for ceramic production now mandate heat recovery rates exceeding 35% in new kiln installations. This regulatory floor is forcing equipment manufacturers to embed regenerative burner systems as standard rather than optional configurations. Indian exporters targeting cross-border tenders are responding by partnering with Henan-based thermal equipment specialists to achieve compliance parity.
Builder procurement patterns are fragmenting between turnkey plant contracts and equipment-only purchases with third-party integration. State housing boards in Maharashtra and Gujarat increasingly unbundle after-sales service from initial capital expenditure, creating standalone maintenance contract markets. This unbundling is most visible in India's affordable housing vertical, where project finance constraints favor operational expenditure models over upfront capital deployment.
Automatic Clay Brick Making Machine Market Segmentation
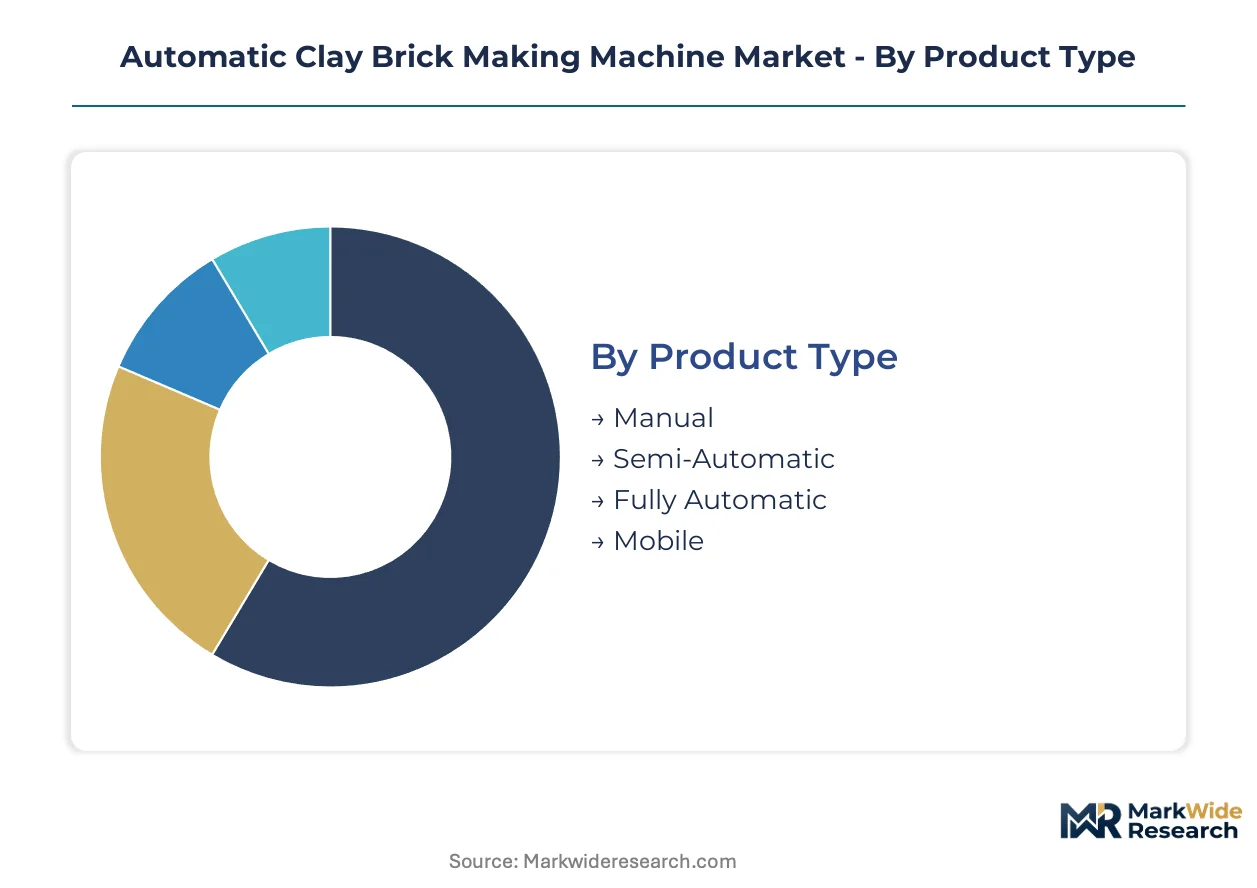
Equipment specification diverges sharply across procurement channels in the automatic clay brick making machine landscape. State housing boards, rural fabricators, and frontier construction operators each route through distinct product configurations, creating channel-specific technology tiers.
Product Type:
Channel mix splits between turnkey plant contractors favoring integrated systems and independent fabricators sourcing modular upgrades.
- Fully Automatic:These systems integrate extrusion, cutting, and automated handling at pressures of 15–40 bar, serving large-scale housing developers in India's Gujarat and Maharashtra corridors. State-level affordable housing targets sustain procurement volumes from domestic and cross-border suppliers.
- Mobile:Containerized pressing configurations operate on limited grid access, targeting remote construction sites and frontier zones lacking centralized infrastructure. Bangladesh's urban densification programs drive import demand for these units.
- Semi-Automatic:Hybrid configurations retain manual intervention stages, dominating rural manufacturing segments where capital constraints limit technology uptake.
- Manual:Basic forming equipment persists in artisanal production clusters with minimal mechanization requirements.
Fully automatic systems dominate installed base. Mobile configurations are where expansion concentrates fastest.
End User:
Cost tier stratification separates premium specification buyers from price-sensitive procurement.
- Construction:Load-bearing wall producers specify vacuum extrusion systems to meet BIS compressive strength requirements. India's western corridor housing contracts command the largest equipment deployments.
- Manufacturing:Dedicated brick fabricators balance throughput against capital intensity, with medium-scale semi-automatic lines retaining share in tier-2 and tier-3 production clusters.
- Engineering:Infrastructure project contractors source mobile pressing units for temporary site operations with rapid relocation requirements.
- Natural Resource Management:Mining and land reclamation operators deploy specialized configurations for site-specific soil stabilization applications.
Construction commands revenue concentration. Engineering applications show steepest expansion trajectory among project-based procurement.
Technology:
Margin pools concentrate where material efficiency and defect reduction justify premium positioning.
- Vacuum Processing:Continuous de-airing extrusion integrates mixing, pugging, and wire-cutting into single-pass operations. Large-scale Indian housing developers specify these systems for 50,000+ unit annual contracts.
- Extrusion:Conventional pressure forming remains standard for medium-volume producers balancing output quality against equipment cost.
- Pressing:Compression-based forming suits mobile configurations and specialized product geometries where extrusion limitations apply.
- Molding:Cast-forming technology serves niche architectural and decorative brick segments with complex surface requirements.
Vacuum processing leads margin pools. Extrusion retains volume dominance across installed capacity.
Size:
Customer type segmentation aligns capital deployment with operational scale and contract visibility.
- Large Scale:Integrated plant systems with annual capacities exceeding 50,000 units serve state housing board tenders and national infrastructure programs.
- Medium Scale:Regional fabricators in India's secondary cities deploy these configurations for district-level supply contracts.
- Small Scale:Rural entrepreneurs and cooperative societies dominate this tier, constrained by limited access to project finance.
- Custom:Project-specific engineering addresses non-standard product dimensions, specialized firing requirements, or unique raw material compositions.
Large scale systems anchor supplier revenue. Medium scale procurement is where technology upgrade cycles concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters concentrate in Henan province and Gujarat state, with demand dispersion following affordable housing pipelines across South Asia and Sub-Saharan Africa. Cross-border procurement flows through three dominant corridors: Chinese manufacturers supply turnkey extrusion plants, Indian fabricators serve regional housing board tenders, and European specialists capture kiln modernization retrofits.
China
Henan province hosts the densest concentration of extrusion system manufacturers, with Zhengzhou-based fabricators supplying vacuum processing lines to domestic and export markets. MIIT efficiency mandates and GB energy codes for ceramic production force kiln heat recovery rates above 35%, accelerating regenerative burner adoption. The Yangtze River Delta absorbs the largest share of integrated plant deployments for municipal infrastructure programs.
India
Gujarat and Maharashtra sustain the heaviest procurement volumes through state-level affordable housing targets exceeding 50,000 units annually. BIS certification requirements for fired clay products compress rural manufacturers toward vacuum extrusion upgrades, expanding the addressable base for fully automatic systems. The western corridor from Ahmedabad through Mumbai anchors domestic supplier revenue concentration.
Bangladesh
Dhaka's urban densification programs generate import demand for mobile pressing configurations suited to limited grid access and rapid site relocation. The absence of domestic extrusion capacity creates procurement dependency on Chinese and Indian cross-border suppliers. Chittagong port logistics constrain large-scale plant imports, favoring containerized equipment formats.
Nigeria
Federal housing initiatives and state-level infrastructure programs drive procurement of semi-automatic and fully automatic systems for load-bearing wall production. Lagos and Abuja construction corridors concentrate demand from commercial developers and government contractors. Currency volatility and project finance gaps limit technology migration to vacuum extrusion tiers.
Germany
EU F-Gas Regulation compliance requirements on kiln insulating gases shape equipment specifications for European housing tenders, creating certification friction for non-EU exporters. Bavaria and North Rhine-Westphalia retain specialized fabrication capacity for thermal processing equipment and kiln modernization retrofits. German engineering firms partner with Asian manufacturers to achieve regulatory parity in third-country markets.
Automatic Clay Brick Making Machine Market Competitive Environment
Concentration sits with integrated system providers possessing captive manufacturing scale and thermal processing expertise. The vendor base splits between large-scale extrusion specialists, mobile pressing innovators, and kiln-integrated solution architects. Three archetypes dominate: Henan-based fabricators leveraging provincial supply chain density, African-market mobile specialists, and European thermal equipment integrators. Competitive dynamics revolve around strategic partnerships with housing board procurement channels and technology licensing for vacuum processing upgrades.
Among Chinese fabricators, Zhengzhou Yingfeng Machinery Co., Ltd and Xi'an Brictec Engineering Co., Ltd exemplify the integrated system archetype, with geographic naming signaling provincial concentration in Henan and Shaanxi respectively. Hydraform occupies a distinct position in mobile pressing technology for frontier construction zones. These three anchors represent divergent automation depth strategies—stationary vacuum extrusion versus containerized mobility—competing for overlapping project profiles across South Asian and African housing pipelines.
| Leading Market Players |
|---|
| Zhengzhou Yingfeng Machinery Co., Ltd |
| Hydraform |
| Lontto Block Machine |
| Sadhana Engineering Industries |
| JC Steele Brick and Block Making Machines |
| Halstec Engineering Co., Ltd |
| GM Quangong Machinery (QGM) |
| Press Makina |
| Xi'an Brictec Engineering Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Refractory material substitution from magnesia-based to alumina-silicate kiln linings is compressing procurement costs for Indian fabricators while shifting supplier relationships toward Henan province ceramic specialists, simultaneously redrawing supply geography and eroding legacy pricing premiums for European thermal equipment.
Pricing Analysis
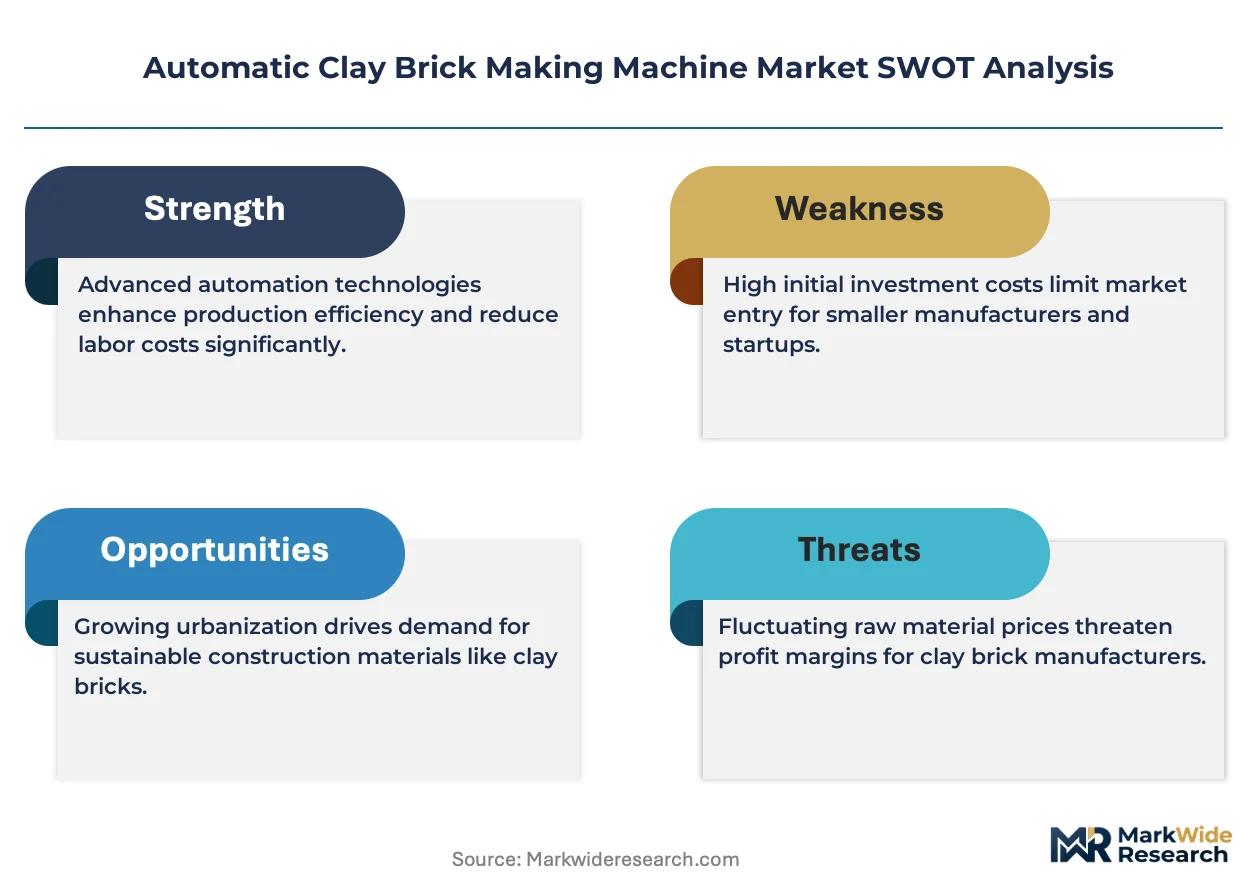
India's BIS certification requirements for fired clay products dictate the pricing tier structure across the automatic clay brick making machine landscape. Three-tier pricing structure across premium vacuum extrusion, standard semi-automatic, and economy manual configurations separates state housing board contractors from rural fabricators and artisanal producers. Pricing pressure stems from refractory cost volatility and capital intensity thresholds that exclude small-scale buyers. Rural manufacturing segments exhibit highest price sensitivity, while large-scale housing developers in Gujarat and Maharashtra prioritize certification compliance over unit cost.
Supply Chain Analysis
Yangtze River Delta port congestion and Chittagong container bottlenecks underwrite delivery timeline risk for turnkey plant shipments. Equipment fabrication concentrates in China's Henan province, India's Gujarat state, and Germany's North Rhine-Westphalia region. Supply chains draw from magnesia and alumina feedstock from Henan suppliers, precision cutting components from Yangtze Delta machining clusters, and regenerative burner systems from Bavarian thermal engineering specialists. Single-source vulnerability concentrates in vacuum pump and extrusion die manufacturing. Distribution runs through state housing board tender channels, regional equipment distributors, and direct OEM contracts with national infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling from capital expenditure creates a standalone maintenance contract market expanding faster than hardware shipments, particularly in India's affordable housing vertical where operational expenditure models displace upfront procurement.
For Market Incumbents: Consolidate captive manufacturing scale across Henan province to defend margin position against mobile pressing innovators targeting frontier construction zones. Deepen backward integration into thermal processing equipment to capture kiln modernization retrofit demand from China's MEE emission controls. Secure BIS and MIIT certification pipeline capacity to compress 8-14 month approval timelines that currently disadvantage cross-border competitors. For New Entrants and Emerging Players: Aftermarket vacuum extrusion upgrade services for legacy semi-automatic plants present immediate white-space opportunity, as incumbent OEMs under-serve rural fabricators facing extended downtime during technology migration. Target Bangladesh's urban densification programs with containerized pressing configurations suited to Chittagong port constraints and limited grid access. Pursue partnership-based go-to-market positioning with Indian state housing boards seeking unbundled maintenance contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European thermal equipment specialists possessing EU F-Gas Regulation compliance capabilities but limited Asia-Pacific manufacturing footprint. Five-to-ten year viability hinges on regulatory divergence management and platform standardization across BIS, MIIT, and EU certification frameworks. Watch for PLI scheme alignment announcements from Indian capital goods manufacturers as inflection signal for domestic assembly investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Extrusion Technology Licensing | Technology transfer agreements with Henan fabricators accelerate BIS compliance for Indian housing tenders. |
| Mobile Pressing Configuration Development | Containerized systems unlock Bangladesh and Nigeria frontier construction zones lacking centralized infrastructure. |
| Aftermarket Service Contract Unbundling | Standalone maintenance offerings capture operational expenditure preference in Maharashtra affordable housing programs. |
| Regenerative Burner System Integration | Heat recovery compliance with China's GB energy codes secures MIIT approval for kiln modernization retrofits. |
| PLI Scheme Manufacturing Localization | Indian production-linked incentives reward local assembly of automated cutting and handling systems. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at Gujarat and Maharashtra housing contractors, procurement officers at state housing boards, aftermarket service managers at Henan-based OEMs, and thermal equipment specialists at German kiln modernization firms, then refined against secondary validation from BIS certification databases, MIIT equipment approval registries, Indian customs import records for extrusion machinery, and EU F-Gas Regulation compliance filings. Bottom-up unit economics from individual plant deployments were triangulated with top-down market sizing from national housing program targets.
Variance decomposition across product type, automation depth, end-user segment, technology tier, and geographic procurement channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated state-level affordable housing unit targets, kiln heat recovery mandate compliance timelines, and refractory material cost trajectory assumptions.
Underlying assumptions cover regulatory certification timeline stability, refractory supply continuity from Henan province, and housing program funding execution, with deviation risk concentrated in currency volatility for Nigerian imports and EU F-Gas Regulation enforcement intensity for non-EU exporters. Practitioners should keep alternative scenarios live as BIS-MIIT regulatory convergence negotiations and PLI scheme expansion decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
India Construction Equipment Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Static Crane Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Winch Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Part Feeder Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Crane Pumps Market