
 Ripper Market | 2026-2036
Ripper Market Size, Share, and Industry Trends Forecast 2026-2036
Ripper Market Analytics
Chinese steel foundries is restructuring output grades to serve ripper tooth and shank producers. Caterpillar leverages captive metallurgy to sustain cost advantages across North American mining contracts. Komatsu anchors its position through integrated hydraulic systems that improve ripper-tractor compatibility. Xcentric Ripper International specializes in high-frequency vibration technology that differentiates its attachments from conventional static designs.
A ripper is a heavy-duty earthmoving attachment or standalone machine designed to fracture compacted soil, rock, or pavement through penetrating tines or shanks driven by mechanical, hydraulic, or percussive force. Typical specifications include shank lengths from 1,200 mm to 3,500 mm, operating weights between 500 kg and 12,000 kg, and penetration forces exceeding 200 kN for mining-grade units. Hydraulic rippers lead product type demand due to their compatibility with existing excavator fleets and adjustable force output, while electric rippers represent the fastest-growing category as quarry operators face diesel restriction zones. Steel dominates material selection for standard construction applications, though alloy and titanium variants command premium positioning in abrasive mining environments where tooth replacement cycles determine lifetime operating economics.
OSHA excavation safety standards and EPA Tier 4 Final emissions rules shape equipment specifications and engine choices across the United States. The EU Green Deal and F-Gas Regulation accelerate electrification timelines for construction machinery sold in member states. Stakeholders must monitor battery energy density improvements and charging infrastructure rollout at remote mining sites to determine optimal timing for electric ripper fleet transitions.
Market Dynamics
The transition from diesel to electric powertrains is restructuring capital allocation across ripper manufacturing, as battery energy density gains and charging infrastructure deployment at remote mining sites determine fleet replacement timelines.
Growth Catalysts
- EU Green Deal and F-Gas Regulation:These frameworks mandate electrification timelines for construction machinery, creating regulatory pull for electric ripper development across European quarry operations.
- Hard-rock extraction intensity:Mining operators in Australia and Chile are expanding hydraulic ripper deployments to fracture compacted ore bodies where blasting restrictions limit explosive use.
- Western China infrastructure corridor:Large-scale soil preparation projects in Sichuan and Xinjiang provinces are concentrating demand for heavy-duty excavation attachments.
Market Restraints
- Alloy steel input volatility:Specialized metallurgy for ripper teeth and shanks ties production economics to nickel and chromium price swings.
- Chinese foundry concentration:Restructuring of steel output grades at domestic mills creates supply uncertainty for tooth producers dependent on specific hardness specifications.
- Battery thermal limitations:Current lithium-ion chemistry struggles with sustained high-torque applications in abrasive mining environments.
Strategic Opportunities
- California emissions zones:CARB regulations are accelerating early electric ripper adoption ahead of federal mandates, creating a testbed market.
- Vibration-frequency convergence:Integration of percussive and hydraulic force modulation is opening new applications in frozen ground and permafrost regions.
- Rental channel expansion:Equipment-as-a-service models are penetrating mid-tier construction where capital constraints limit purchase decisions.
Industry Challenges
- Hydraulic systems integration:Ripper-tractor compatibility demands specialized engineering talent that OEMs struggle to retain.
- EPA Tier 4 Final compliance:Engine certification timelines extend product development cycles for diesel-powered units.
- Legacy fleet retrofit complexity:Electric conversion kits face mechanical interface mismatches with decade-old excavator architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ripper Market |
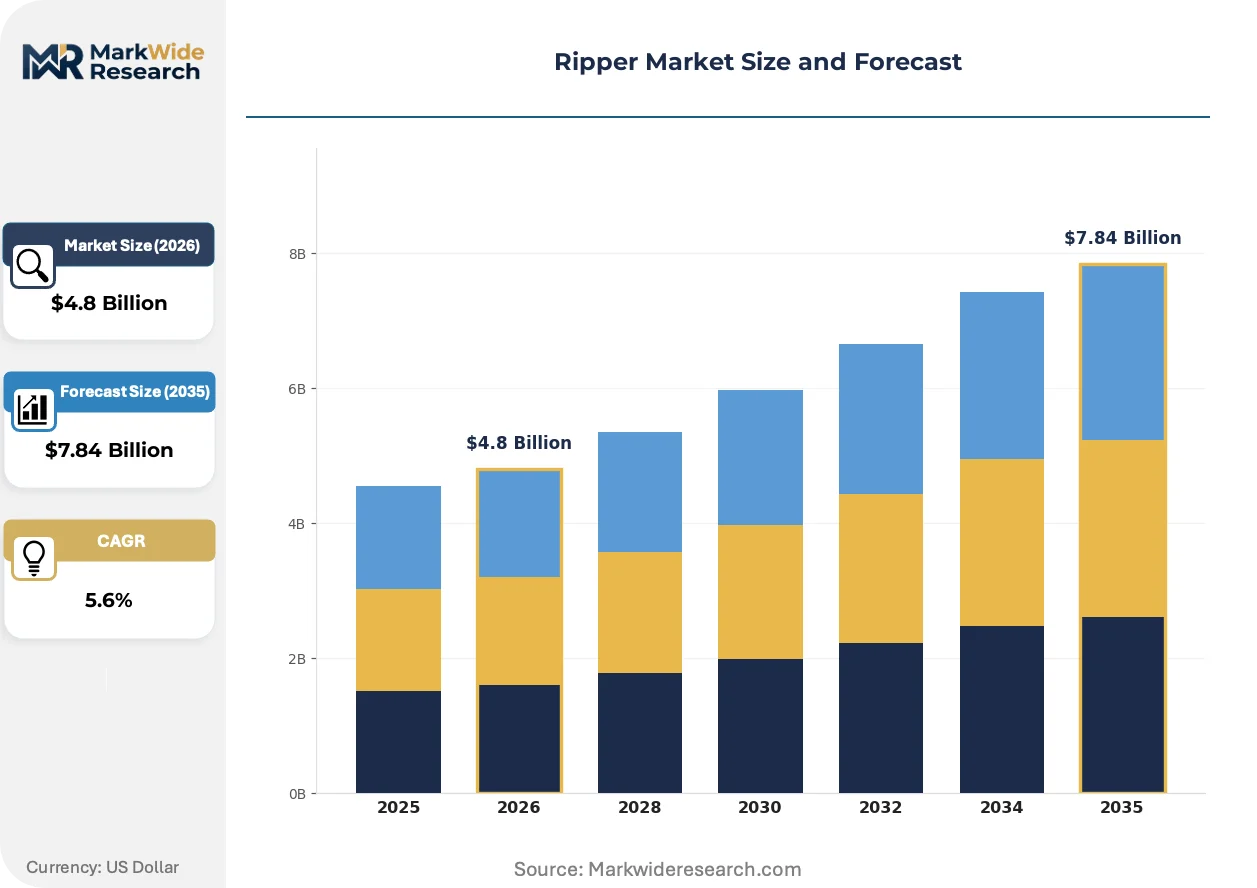
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Rippers, Hydraulic Rippers, Electric Rippers, Pneumatic Rippers End User: Construction, Mining, Agriculture, Landscaping Material: Steel, Alloy, Titanium, Composite Application: Soil Preparation, Demolition, Excavation, Road Repair |
| Companies Covered | Caterpillar, Xcentric Ripper International, Doosan, CNH Industrial, Strickland, Brandt, ESCO, JCB, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ripper Market Evolving Landscape
Active experimentation with force delivery mechanisms is fragmenting product architectures, as manufacturers test vibration-assisted, hydraulic, and fully electric systems against established static designs.
High-frequency vibration technology is rewriting performance benchmarks for rock fragmentation. Quarry operators in Scandinavia are adopting percussive ripper attachments that reduce fuel consumption per cubic meter extracted. This convergence of mechanical and electronic control systems is compressing the performance gap between specialized attachments and dedicated ripping machines.
REACH chemical restrictions and the EU AI Act are reshaping material selection and automation roadmaps. The F-Gas Regulation specifically targets hydraulic fluid formulations, forcing reformulation of sealed systems. Mining contractors in Germany and Poland are front-running compliance by specifying biodegradable hydraulic fluids in new procurement contracts.
Consolidated buying by multinational mining houses is compressing vendor negotiation cycles. Tier-one operators now bundle ripper attachments with full fleet service agreements, displacing standalone component purchases. This pattern is most visible in Chilean copper operations, where Codelco and BHP have centralized attachment procurement under multi-year framework contracts.
Ripper Market Segmentation
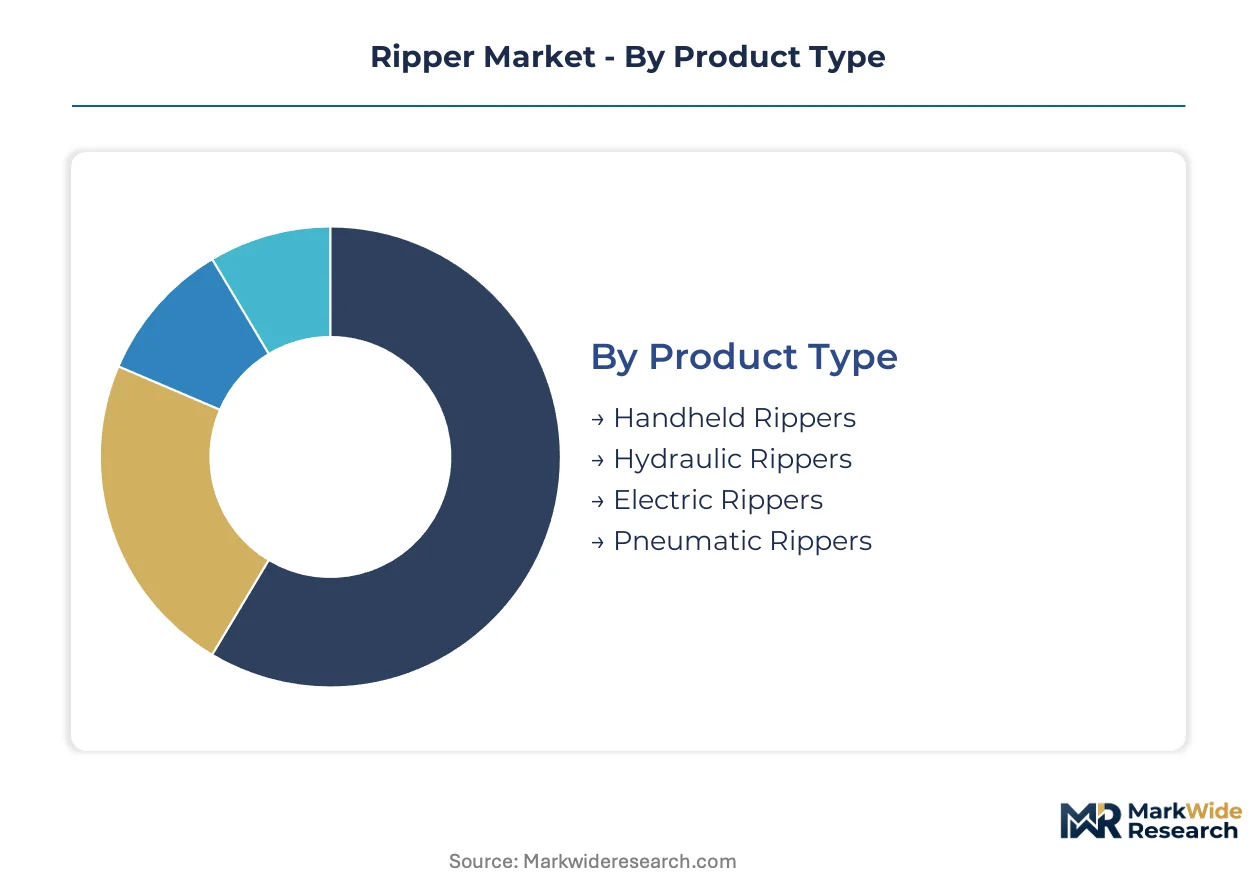
Ripper procurement decisions pivot on force delivery mechanism, material durability against abrasion, and compatibility with host machine hydraulics. Fleet operators weight capital cost against tooth replacement cycles and fuel access constraints.
Product Type:
Buyers select force generation systems based on existing fleet architecture and site power infrastructure availability.
- Hydraulic Rippers:These attachments channel pressurized fluid from excavator auxiliary circuits to drive penetrating shanks with adjustable force modulation. Australian and Chilean hard-rock mining operations are expanding deployments where blasting restrictions limit explosive use.
- Electric Rippers:Battery-electric units eliminate diesel particulate emissions and reduce ventilation requirements in underground headings. CARB regulations in California and EU Green Deal timelines are accelerating quarry adoption ahead of federal mandates.
- Handheld Rippers:Manual percussive tools serve confined demolition and precision concrete breaking where machinery access is restricted.
- Pneumatic Rippers:Compressed-air systems persist in legacy mining infrastructure with established compressor networks.
Hydraulic rippers lead on scale; electric rippers lead on momentum.
End User:
Application intensity and operating hour economics separate commercial segments.
- Mining:Continuous high-abrasion extraction demands alloy tooth metallurgy and integrated hydraulic systems. Tier-one operators in Chile bundle attachments under multi-year framework contracts with full fleet service agreements.
- Construction:Variable soil conditions and project-based procurement favor rental channel access and standard steel specifications.
- Agriculture:Seasonal subsoiling applications prioritize attachment interchangeability across tractor fleets.
- Landscaping:Low-hour utility work concentrates demand on compact hydraulic units with quick-coupler compatibility.
Mining commands the highest attachment values per unit; construction delivers the largest addressable fleet base.
Material:
Tooth replacement frequency drives lifetime cost calculations and material selection.
- Steel:Standard carbon grades dominate general construction where moderate abrasion permits economical replacement cycles.
- Alloy:Nickel-chromium formulations extend service intervals in abrasive mining environments. Chinese foundry restructuring creates supply uncertainty for specialized hardness specifications.
- Titanium:Lightweight corrosion resistance serves marine and chemical exposure applications.
- Composite:Emerging ceramic-matrix materials reduce weight for high-frequency vibration systems.
Steel dominates unit volume; alloy captures premium positioning.
Application:
Ground condition and fragmentation requirements determine shank geometry and force profiles.
- Excavation:Deep penetration in compacted formations requires extended shank lengths and high breakout force.
- Soil Preparation:Agricultural and civil earthmoving applications prioritize surface fracturing with minimal subsoil disturbance.
- Demolition:Reinforced concrete breaking demands percussive energy concentration at single points.
- Road Repair:Asphalt and base course removal operates on hardened surfaces with shallow penetration depths.
Excavation absorbs the heaviest equipment specifications; soil preparation spreads across the widest geographic deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate fabrication to jurisdictions with lower compliance costs for emissions and metallurgy standards. Cost-of-compliance gaps between the European Union and select Asian markets now exceed fifteen percentage points on equivalent equipment specifications.
United States
Copper and lithium extraction in Arizona and Nevada is driving hydraulic ripper deployments where blasting restrictions protect adjacent federal lands. EPA Tier 4 Final emissions rules and OSHA excavation safety standards govern equipment specifications across western mining operations. The Permian Basin in Texas anchors demand for road repair attachments servicing oilfield infrastructure maintenance.
Australia
Hard-rock iron ore and coal extraction in Western Australia's Pilbara region is expanding fleet deployments of mining-grade hydraulic units. The country's national mining safety regulator enforces strict equipment certification protocols that favor established OEM supply relationships. Perth-based equipment distributors are consolidating procurement under multi-year service agreements with tier-one operators.
Chile
Copper porphyry extraction in the Atacama Desert is concentrating demand for alloy-tooth rippers capable of fracturing compacted ore bodies. Codelco and BHP have centralized attachment procurement under framework contracts that bundle rippers with full fleet service agreements. The Antofagasta mining cluster is testing electric ripper prototypes in underground headings where ventilation constraints favor zero-emission equipment.
Germany
Quarry operations in North Rhine-Westphalia are front-running EU Green Deal compliance by specifying biodegradable hydraulic fluids in procurement contracts. The F-Gas Regulation is forcing reformulation of sealed hydraulic systems ahead of 2030 phase-out timelines. The Ruhr industrial corridor is emerging as a testbed for percussive-vibration attachments that reduce fuel consumption per cubic meter extracted.
China
Large-scale infrastructure projects in Sichuan and Xinjiang provinces are concentrating demand for heavy-duty soil preparation equipment. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate electrification timelines for construction machinery sold in eastern provinces. Xuzhou and Changzhou manufacturing clusters are restructuring steel foundry output grades to serve ripper tooth and shank producers.
Ripper Market Competitive Landscape
North American producers anchor one tier; Japanese and European specialists hold differentiated positions in integrated hydraulic systems and high-frequency vibration technology. The vendor base organizes around three strategic archetypes: diversified heavy equipment conglomerates with captive metallurgy, attachment specialists with focused vibration or percussive engineering, and regional fabricators serving rental and aftermarket channels. Competitive intensity concentrates on M&A activity targeting hydraulic systems integration capabilities and strategic partnerships with mining houses for multi-year framework contracts.
Within the diversified equipment tier, Caterpillar and Komatsu exemplify scale-driven positioning through integrated manufacturing and captive supply chains. Xcentric Ripper International occupies a specialist position representing focused engineering in high-frequency vibration technology that differentiates from conventional static designs. These three anchors illustrate the competitive spectrum from full-system integration to attachment-specific innovation.
| Leading Market Players |
|---|
| Caterpillar |
| Xcentric Ripper International |
| Doosan |
| CNH Industrial |
| Strickland |
| Brandt |
| ESCO |
| JCB |
| Komatsu |
| Others |
Value Network & Pricing Analysis
Sovereign-backed Chinese steel foundries and family-owned Italian attachment specialists anchor opposite ends of the supply base, with each ownership pattern imposing distinct pricing discipline on tooth and shank procurement. State-directed capacity adjustments in Xuzhou and Changzhou ripple through alloy pricing, while European fabricators defend margin through captive heat-treatment capabilities that OEMs struggle to replicate.
Pricing Analysis
Distributor margin layers concentrate value capture at the aftermarket service tier, where rental channel markups on hydraulic units exceed direct-to-mine procurement discounts by substantial spreads. Three-tier pricing structure across premium, standard, and economy levels separates titanium-tooth mining configurations from carbon-steel construction attachments, with alloy grades commanding intermediate positioning. Cost compression in standard steel tiers is intensifying because Chinese foundry restructuring has tightened spot availability of specified hardness grades. Rental fleet operators exhibit the highest price sensitivity, while tier-one mining houses prioritize tooth replacement cycle economics over upfront capital outlay.
Supply Chain Analysis
Freight cost differentials between bulk ocean lanes and containerized specialty shipments favor integrated producers with captive foundry-to-fabrication footprints. Supply concentrates in China, Australia, and Germany, with Xuzhou clusters feeding standard construction demand and Ruhr Valley specialists serving percussive-vibration engineering. Nickel-chromium alloy formulations and high-grade hydraulic seals draw from South Korean and Japanese specialty chemical producers. Single-source vulnerability in Chinese foundry capacity for specified hardness grades threatens alloy-tooth availability during mill restructuring periods. Distribution runs through Perth-based mining distributors, German quarry equipment specialists, and Chinese state-owned trading houses serving Belt and Road contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ripper market compounds steadily as hard-rock extraction intensity in copper and lithium operations sustains replacement demand regardless of construction cyclicality. Regulatory electrification mandates create predictable upgrade windows that stabilize OEM order books.
For Market Incumbents: Extend service agreement bundling to capture multi-year attachment procurement from Chilean and Australian mining houses, insulating revenue from spot-price volatility in alloy inputs. Deepen backward integration into heat-treatment capabilities to offset Chinese foundry supply uncertainty. Prioritize hydraulic systems engineering talent retention as Komatsu and Caterpillar compete for scarce integration specialists.
For New Entrants and Emerging Players: Mid-tier construction contractors in Western China represent an underserved buyer archetype with capital constraints that favor equipment-as-a-service rental penetration over direct purchase. Percussive-vibration attachments for frozen ground applications in Scandinavian and Canadian markets offer white-space positioning against static-design incumbents. Pursue regional fabrication partnerships with Xuzhou foundries to bypass captive metallurgy barriers at established OEMs.
For Investors and Strategic Acquirers: Valuations sit cheapest among hydraulic systems integration specialists with mining-house framework contracts but limited brand recognition beyond regional markets. Long-term viability hinges on electrification transition timing and battery thermal management breakthroughs for sustained high-torque applications. Monitor charging infrastructure deployment at remote Australian and Chilean mine sites as the inflection signal for electric ripper fleet replacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Hydraulic Fluid Transition | German quarry operators front-run EU F-Gas Regulation compliance ahead of 2030 phase-out timelines. |
| High-Frequency Vibration R&D Partnership | Scandinavian percussive attachment adoption reduces fuel consumption per cubic meter extracted. |
| Alloy Steel Backward Integration | Captive metallurgy insulates Caterpillar from Chinese foundry restructuring and nickel price swings. |
| Electric Ripper Prototype Testing | Chilean underground copper operations validate zero-emission equipment under ventilation constraints. |
| Multi-Year Service Agreement Expansion | Codelco and BHP centralized procurement displaces standalone attachment purchases in Atacama operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mining maintenance directors, quarry operations managers, OEM procurement teams, and aftermarket service heads with secondary validation. SEC filings from diversified equipment manufacturers, customs trade data on alloy steel shipments, Australian mining safety regulator certification records, and EU F-Gas Regulation implementation guidance anchored the data foundation. Bottom-up unit deployment estimates across Australian Pilbara and Chilean Atacama operations were triangulated against top-down market value reconstruction.
Segment-weighting approaches distributed value across hydraulic, electric, handheld, and pneumatic product types, with end-use intensity differentials separating mining, construction, agriculture, and landscaping applications. Material grade tiers and application-specific force profiles provided cross-cutting segmentation dimensions throughout the projection horizon. CAGRs were derived from regression against mining capital expenditure cycles and infrastructure project pipelines, with battery energy density improvement curves and charging infrastructure rollout schedules informing electric ripper adoption pacing.
Inputs from mining house procurement officers and foundry operations managers were available through the study window; gaps in real-time Chinese steel mill grade restructuring timelines introduce uncertainty bands around alloy-tooth supply assumptions. Forecasts reflect modeled adoption curves and regulatory compliance deadlines that could accelerate or delay fleet replacement decisions. Stakeholders should weight assumptions against their own operating context and site-specific power infrastructure availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Multi-Tasking Machine Tools Market
Tools
Global Standard Parts for Tool Making Market
Tools
Bar Clamp Market
Tools
Global Table Saws Market
Tools
Tapping Machine Market
Tools
Hydraulic Torque Wrench Market
Tools
Auger Drill Bits Market
Tools
Digital Cutting Machine Market
Tools
Rebar Cutter Market
Tools
Global Vertical Grinding Machine Market
Tools
Machining Centers Market
Tools
Aluminum Folding Ladders Market
Tools
Leather Cutting Machine Market
Tools
Floor Scraper Market
Tools
Theodolite Market
Tools
Deburring Tool Market