
 Asia Pacific Access Control Software Market | 2026-2036
Asia Pacific Access Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Access Control Software Market Insights
Cloud-native architecture is reconfiguring how access control platforms deliver credential lifecycle management and real-time policy enforcement across distributed facilities. Honeywell International Inc. leverages its building automation heritage to anchor integrated security suites in commercial high-rises across Southeast Asia. Hangzhou Hikvision Digital Technology Co., Ltd. dominates edge-AI camera deployments that feed directly into access decision engines. Fujitsu sustains competitive position through specialized palm-vein biometric modules that differentiate its enterprise offerings from fingerprint-dependent rivals.
Asia Pacific access control software comprises credential management platforms, policy orchestration engines, and audit logging systems that authenticate identities and govern physical entry points through cryptographic tokens, biometric templates, or mobile-derived keys. These systems typically enforce multi-factor verification with sub-second latency while maintaining tamper-evident audit trails for compliance forensics. Cloud-based deployment leads value generation as operators shift capital expenditure to subscription models, though hybrid architectures retain traction among healthcare end users bound by data residency requirements. Biometric technology segments capture premium margins where liveness detection and anti-spoofing algorithms determine procurement decisions in government and banking verticals.
China's MIIT enforces GB standards for biometric data storage and transmission, while India's TRAI frameworks intersect with CEA guidelines on critical infrastructure cybersecurity, collectively elevating compliance costs for foreign vendors entering these jurisdictions. Japan's METI drives interoperability mandates through JIS standards that shape product development roadmaps for regional suppliers. Stakeholders must monitor divergence between national data localization regimes and cross-border cloud service architectures when scaling platform delivery across multiple Asia Pacific jurisdictions.
Market Dynamics
Cloud-native credential platforms are collapsing the traditional three-tier architecture of on-premise access control, compressing deployment timelines from months to days while forcing incumbent vendors to restructure their channel economics.
Growth Catalysts
- Digital India biometric mandates:Government infrastructure projects require fingerprint and iris enrollment for civil identification, creating installed bases that extend into building access applications.
- Mobile credential adoption:Enterprise campuses in Singapore and Australia are replacing physical card readers with smartphone-based authentication, eliminating card production and distribution costs.
- GB standards enforcement:China's MIIT mandates encrypted biometric storage and transmission protocols, accelerating hardware refresh cycles among municipal smart city operators.
Market Restraints
- Semiconductor supply concentration:Edge-AI camera chipsets depend on Taiwan and South Korean foundry capacity, exposing deployment schedules to geopolitical disruption.
- Data localization compliance costs:Divergent national regimes in China, India, and Indonesia force vendors to maintain jurisdiction-specific cloud instances, fragmenting platform economics.
- Legacy system entrenchment:Wired RS-485 infrastructure in Japan's commercial building stock resists wireless retrofit without substantial rewiring expenditure.
Strategic Opportunities
- Vietnam manufacturing corridor expansion:Industrial park developers in Binh Duong and Bac Ninh provinces seek integrated security suites for new speculative construction.
- Palm-vein convergence with payment systems:Biometric access templates are merging with contactless transaction authentication in South Korean retail and transit hubs.
- Australia's critical infrastructure cybersecurity regime:CEA guidelines mandate multi-factor authentication for energy and water utilities, opening regulated procurement channels.
Industry Challenges
- Embedded systems cybersecurity expertise scarcity:Firmware hardening against side-channel attacks requires talent pools concentrated in Israel and Estonia, not Asia Pacific.
- Interoperability certification timelines:JIS standards in Japan and BIS requirements in India impose sequential testing protocols that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Access Control Software Market |
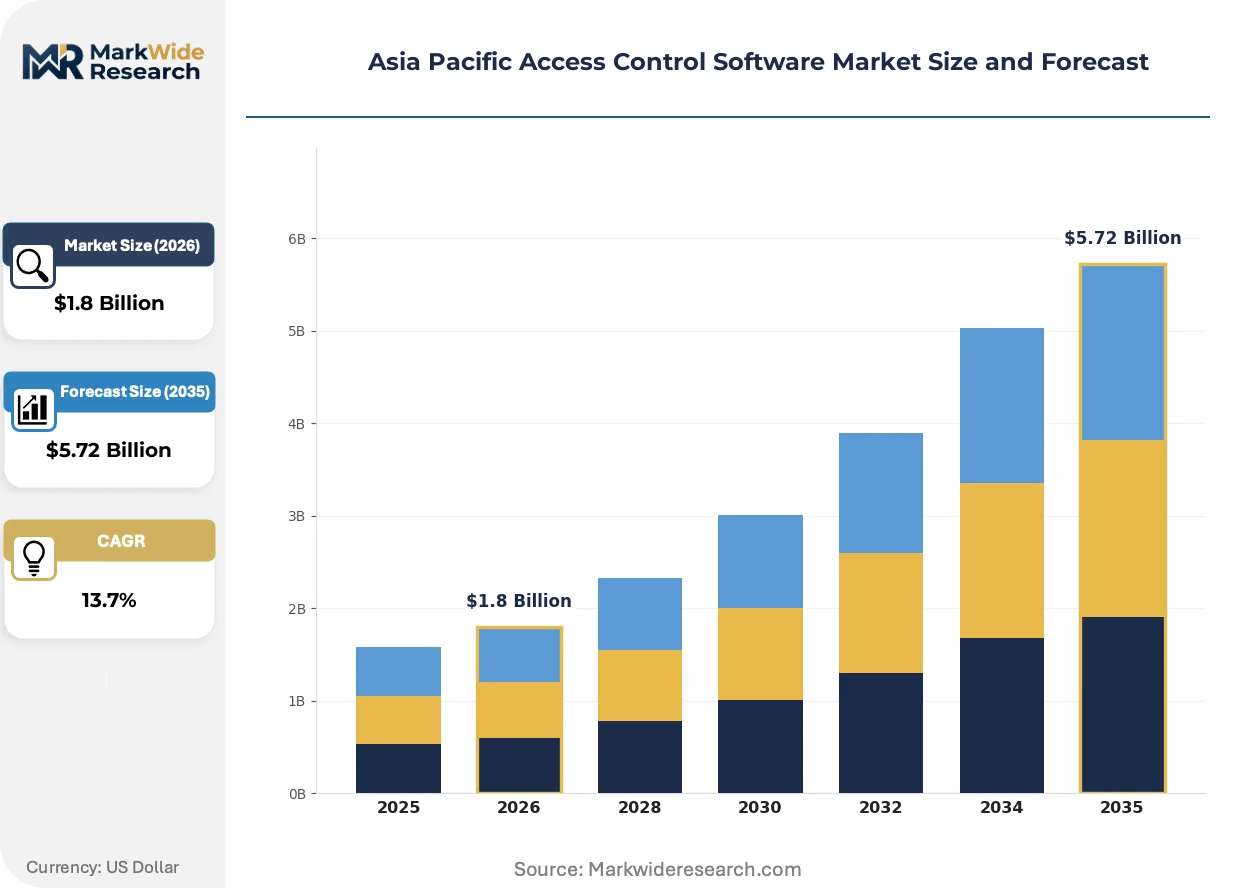
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Government, Healthcare, Education, Commercial Technology: Biometrics, RFID, Bluetooth, Internet of Things Application: Identity Verification, Time & Attendance, Access Management, Visitor Management |
| Companies Covered | Honeywell International Inc., Fujitsu, Hangzhou Hikvision Digital Technology Co., Ltd., IDEMIA, Thales Group, Bosch Security and Safety Systems, Axis Communications AB, Genetec Inc., Johnson Controls, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Access Control Software Market Trends and Innovations
Architectural convergence between physical security and IT identity management is dissolving traditional procurement boundaries, with facility managers and CISOs now jointly evaluating unified platforms.
Zero-trust network access principles are collapsing the perimeter-based security model that dominated access control for three decades. Financial services firms in Hong Kong and Sydney are deploying continuous authentication that re-verifies identity at each door transition rather than single-point entry validation. This architectural shift is compressing vendor margins on standalone hardware while expanding recurring software revenue pools.
China's MIIT enforcement of GB/T 35273 personal information security specifications is mandating on-device biometric template storage rather than centralized cloud repositories. Domestic camera manufacturers are redesigning edge processors to handle liveness detection locally, avoiding cross-border data transfer restrictions. Foreign platform vendors must establish domestic cloud partnerships or cede government and state-owned enterprise verticals entirely.
Subscription pricing for credential lifecycle management is displacing perpetual license models across Southeast Asian commercial real estate. Property management firms in Bangkok and Kuala Lumpur prefer operational expenditure treatment for security upgrades tied to tenant churn cycles. This preference shift is most visible in flex-office and co-working segments where monthly membership models demand correspondingly fluid access provisioning.
Asia Pacific Access Control Software Market Segmentation
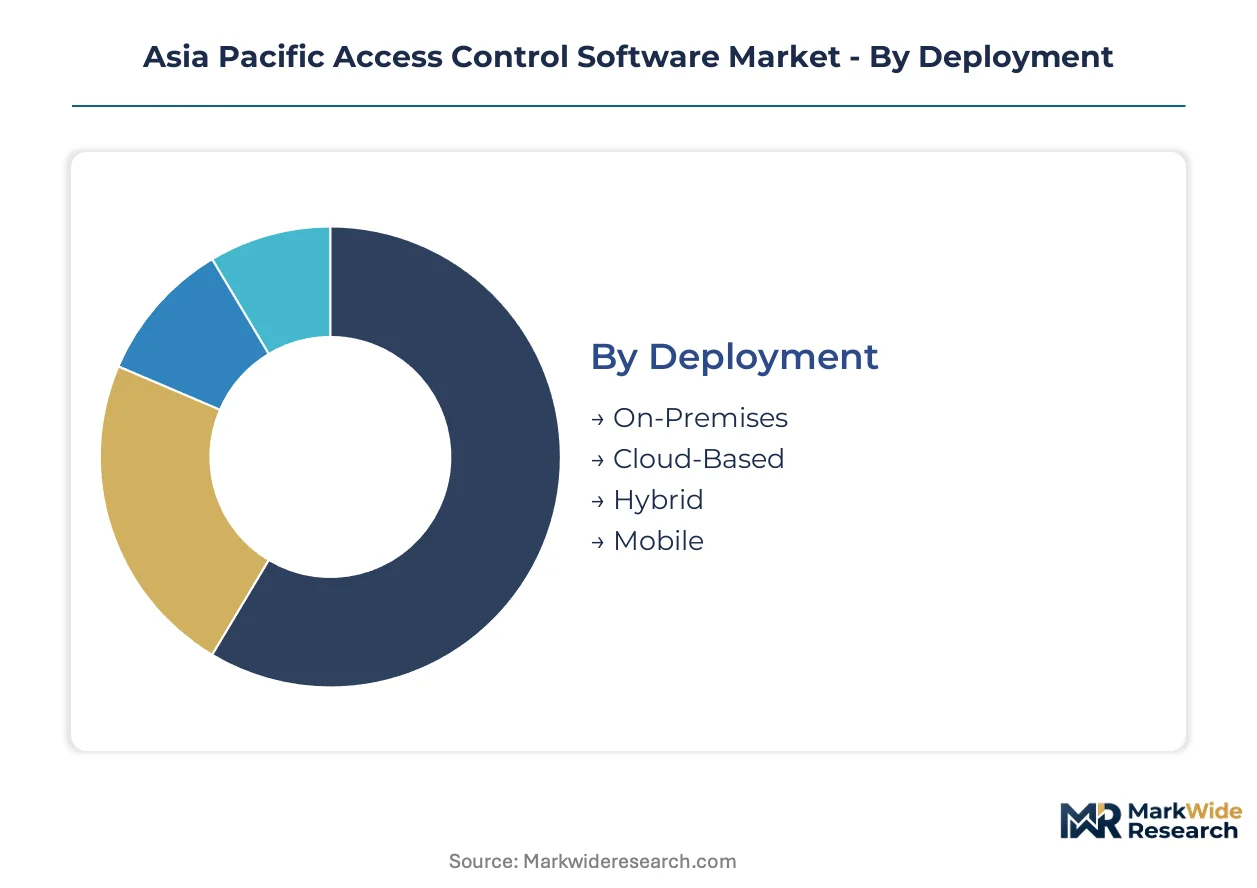
Segmentation reveals how deployment architectures, credential technologies, and compliance requirements fragment procurement patterns across Asia Pacific jurisdictions. Understanding these divides exposes where platform vendors must localize product roadmaps versus where standardized offerings suffice.
Deployment:
Mature on-premise installations coexist with emerging cloud-native platforms as regulatory divergence shapes infrastructure choices.
- On-Premises:Legacy server-based architectures persist in Japan's commercial building stock where JIS interoperability mandates and data residency preferences delay SaaS migration. Banks in Singapore maintain air-gapped credential databases to satisfy MAS cybersecurity notices.
- Cloud-Based:Subscription credential lifecycle management dominates Southeast Asian flex-office operators in Bangkok and Kuala Lumpur seeking operational expenditure alignment with tenant churn cycles. Multi-tenant platforms compress deployment timelines from months to days.
- Hybrid:Healthcare networks in Australia split sensitive biometric templates across on-premise storage while leveraging cloud policy orchestration to satisfy TGA data sovereignty requirements and clinical workflow demands simultaneously.
- Mobile:Smartphone-derived credentials eliminate card production costs across Singapore and Australian enterprise campuses, though fragmented OS security patch cycles introduce firmware vulnerability management overhead.
On-Premises retains volume leadership; Cloud-Based holds the steepest expansion curve.
End User:
Procurement sophistication varies sharply across institutional buyers, with regulated verticals demanding certified compliance architectures.
- Government:India's Digital India biometric mandates create installed bases extending into building access, while China's MIIT GB standards enforce encrypted template storage for state-owned enterprise corridors.
- Healthcare:Australian hospitals bind access control to patient data governance under TGA frameworks, requiring tamper-evident audit trails for clinical zone entry forensics.
- Education:University campuses in South Korea deploy palm-vein authentication for dormitory and laboratory access, merging physical security with student payment system convergence.
- Commercial:Property management firms across Southeast Asia prioritize subscription pricing models that align security upgrade cycles with lease renewal patterns.
Commercial captures widest addressable scope; Government commands highest compliance-driven pricing premiums.
Technology:
Credential modalities stratify across performance tiers where liveness detection capabilities determine premium positioning.
- Biometrics:Fujitsu's palm-vein modules differentiate through vascular pattern recognition resistant to spoofing, commanding premium placement in South Korean retail-transit convergence deployments.
- RFID:Legacy card-based credentials face replacement pressure from mobile alternatives, though wired RS-485 infrastructure in Japan's building stock resists wireless retrofit without substantial rewiring expenditure.
- Bluetooth:Low-energy beacon proximity authentication enables frictionless entry for co-working members in Kuala Lumpur, though signal interception risks demand rotating key protocols.
- Internet of Things:Edge-AI camera deployments feed directly into access decision engines across China's smart city corridors, with municipal operators bundling facial recognition with building management systems.
Biometrics anchors premium margin pools; Internet of Things gains share fastest through smart city bundling.
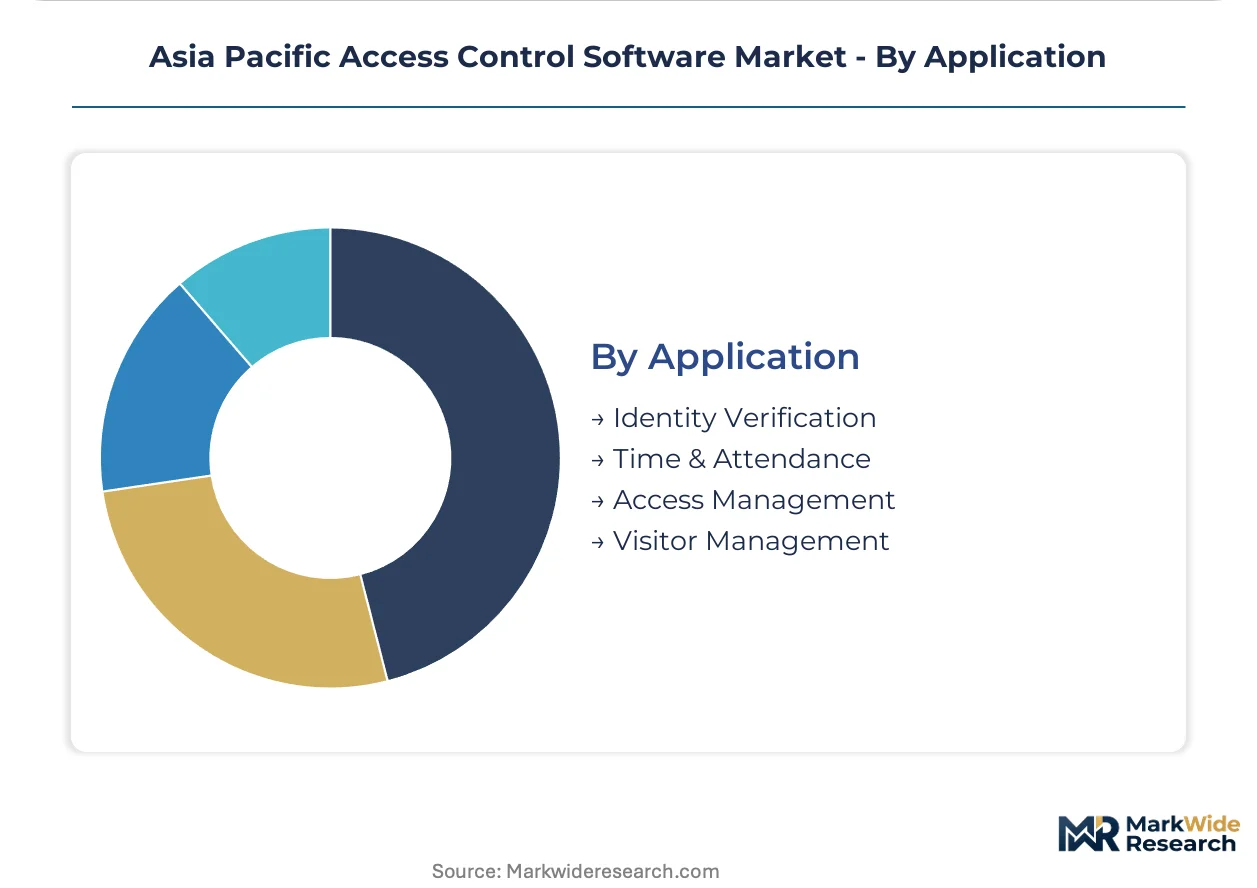
Application:
Use case specialization drives platform configuration complexity as facility managers and CISOs jointly evaluate unified systems.
- Identity Verification:Continuous re-authentication at each door transition replaces single-point validation in Hong Kong financial services firms deploying zero-trust physical security architectures.
- Time & Attendance:Biometric clock-in systems intersect with labor compliance requirements across India's manufacturing zones, creating integrated workforce management demand.
- Access Management:Policy orchestration engines enforce multi-factor verification with sub-second latency across distributed facilities, compressing traditional three-tier deployment timelines.
- Visitor Management:Temporary credential provisioning for contractor and guest populations demands fluid lifecycle management in flex-office segments where monthly membership models predominate.
Access Management retains functional centrality; Identity Verification climbs fastest through zero-trust security adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports integrated security suites to Southeast Asian smart city operators, while Japan supplies precision biometric components to Australian healthcare networks. South Korean manufacturers ship palm-vein authentication modules to retail-transit convergence projects across the region.
China
Municipal smart city corridors in Hangzhou and Shenzhen bundle facial recognition with building management systems, creating concentrated demand clusters. MIIT enforces GB/T 35273 standards mandating encrypted biometric storage and on-device template processing. Domestic camera manufacturers redesign edge processors for local liveness detection to avoid cross-border data transfer restrictions.
Japan
Commercial building stock in Tokyo and Osaka retains wired RS-485 infrastructure resisting wireless retrofit without substantial rewiring expenditure. METI drives interoperability mandates through JIS standards that shape product development roadmaps for regional suppliers. Banks in the Kanto region maintain air-gapped credential databases to satisfy financial regulator cybersecurity notices.
India
Digital India biometric mandates for civil identification create installed bases extending into building access applications across government infrastructure. TRAI frameworks intersect with CEA guidelines on critical infrastructure cybersecurity, elevating compliance costs for foreign vendors. Manufacturing zones in Gujarat and Maharashtra deploy biometric clock-in systems intersecting with labor compliance requirements.
Australia
Healthcare networks in Sydney and Melbourne split sensitive biometric templates across on-premise storage while leveraging cloud policy orchestration to satisfy TGA data sovereignty requirements. CEA guidelines mandate multi-factor authentication for energy and water utilities, opening regulated procurement channels. Enterprise campuses replace legacy card readers with smartphone-based authentication platforms.
Singapore
Commercial high-rises and flex-office operators in the central business district prioritize subscription pricing models aligning security upgrade cycles with lease renewal patterns. MAS cybersecurity notices drive air-gapped credential database requirements among financial institutions. Mobile credential platforms eliminate card production and distribution costs across enterprise campuses.
Asia Pacific Access Control Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architectures and credential modalities. The market structure shows moderate consolidation among building automation heritage firms and edge-AI camera manufacturers, with fragmentation in biometric module specialists. Two strategic archetypes dominate: integrated security suite providers leveraging building management heritage, and edge-AI specialists feeding camera data directly into access decision engines. Competitive moves concentrate on cloud partnership formations for data localization compliance and edge processor redesigns for on-device biometric processing.
Within the integrated security suite tier, Honeywell International Inc. and Johnson Controls occupy positions anchored by building automation heritage across Southeast Asian commercial high-rises. Among edge-AI specialists, Hangzhou Hikvision Digital Technology Co., Ltd. exemplifies the camera-to-access-engine convergence dominating China's smart city corridors. Fujitsu sits within the biometric differentiation segment through specialized palm-vein modules resistant to spoofing attacks. These three archetypes represent the competitive vectors reshaping procurement patterns as facility managers and CISOs jointly evaluate unified platforms.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Fujitsu |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| IDEMIA |
| Thales Group |
| Bosch Security and Safety Systems |
| Axis Communications AB |
| Genetec Inc. |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor's freight cost volatility shapes procurement economics for edge-AI camera manufacturers, compressing margins on hardware-bound access control suites while amplifying price differentiation between cloud-native platforms and legacy on-premise systems. Supply concentration in Taiwan and South Korean foundry capacity feeds directly into tiered pricing structures that separate subscription-based credential management from capital-intensive biometric hardware deployments.
Pricing Analysis
Current-generation cloud-native platforms command subscription premiums against prior-generation perpetual license systems, while next-generation edge-AI biometric modules price at hardware-plus-software bundles. Three-tier pricing structure across premium, standard, and economy levels separates Fujitsu's palm-vein authentication from fingerprint-dependent alternatives and basic RFID card systems. Cost compression in mid-tier biometric hardware is intensifying because foundry capacity constraints limit chipset availability. Government and banking verticals show least price sensitivity due to compliance mandates, while Southeast Asian flex-office operators drive hardest bargain for operational expenditure alignment.
Supply Chain Analysis
Upstream feedstock for edge-AI camera chipsets draws from Taiwan Semiconductor Manufacturing, South Korean memory fabricators, and Japanese precision sensor suppliers. Raw material dependencies span silicon wafers, CMOS image sensors, and specialized biometric algorithm licensing. Single-source vulnerability concentrates in advanced node semiconductor fabrication where geopolitical disruption threatens deployment schedules. Distribution runs through building automation integrators in Southeast Asia and direct municipal procurement channels in China's smart city corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
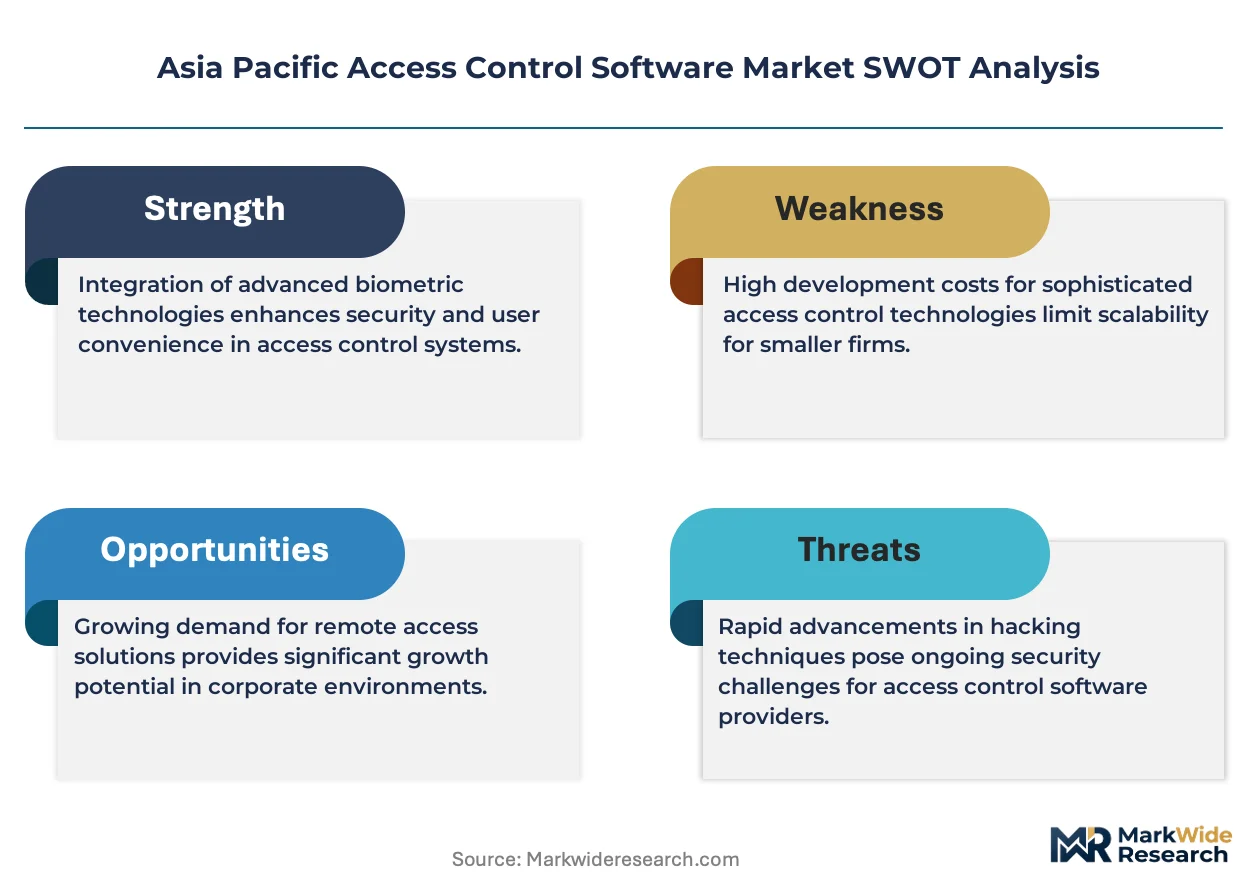
The Asia Pacific access control software market sits at a platform-economics inflection where JIS-METI interoperability mandates in Japan and MIIT GB standards in China are fragmenting previously unified procurement specifications into jurisdiction-specific ecosystem requirements.
For Market Incumbents: Harden firmware architectures against side-channel exploitation by recruiting embedded cybersecurity talent from Israel and Estonia rather than relying on regional pools. Deepen backward integration into edge processor design to satisfy China's on-device biometric template storage mandates without ceding government verticals to domestic competitors. Certification investment in sequential JIS and BIS testing protocols protects channel position against 8-14 month launch delays.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Binh Duong and Bac Ninh industrial corridors where speculative construction lacks incumbent security infrastructure. Target Australia's CEA-mandated critical infrastructure vertical where multi-factor authentication procurement channels remain underpenetrated by foreign specialists. Cloud partnership formations with domestic operators in Indonesia and Philippines bypass data localization compliance costs that fragment platform economics for direct entrants.
For Investors and Strategic Acquirers: Carve-out targets emerge from building automation heritage firms whose channel control in Southeast Asian commercial real estate outpaces their cloud-native platform development capabilities. Long-term viability centers on recurring software revenue pools expanding as zero-trust architectures displace hardware-centric security spending. Watch for inflection when palm-vein biometric templates achieve payment system convergence in South Korean retail-transit hubs, signaling template portability across physical and financial access domains.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Partnership Formation | Domestic cloud alliances in China satisfy MIIT data localization requirements without foreign vendor infrastructure investment. |
| Edge Processor Redesign | On-device liveness detection capability avoids cross-border biometric template transfer restrictions under GB/T 35273. |
| Mobile Credential Platform Launch | Smartphone-derived authentication eliminates card production costs across Singapore and Australian enterprise campuses. |
| Palm-Vein Biometric Integration | Vascular pattern recognition modules command premium placement in South Korean retail-transit convergence deployments. |
| Zero-Trust Architecture Deployment | Continuous re-authentication at door transitions expands recurring software revenue pools for Hong Kong financial services firms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across facility management, CISO offices, building automation integrators, and municipal smart city procurement departments. Primary interview insights combined with secondary validation from MIIT GB standard filings, JIS certification registries, TRAI infrastructure security advisories, and TGA data sovereignty guidance. Bottom-up credential deployment estimates triangulated against top-down building automation market sizing.
Calibration against historical cloud migration patterns in Southeast Asian commercial real estate anchored the projection framework. Segmentation dimensions modeled span deployment architecture, credential technology modality, end-user vertical compliance requirements, and regional regulatory cluster divergence. CAGRs derived from technology substitution curves weighted by jurisdiction-specific enforcement timelines for biometric data localization mandates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor foundry utilization rates and cross-strait logistics stability would shift the trajectory of hardware-dependent deployment schedules. Cross-checking against hyperscaler capex disclosures for Asia Pacific edge infrastructure buildout is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Perimeter Intrusion Detection Systems Market