
 North America Home Security System Market | 2026-2036
North America Home Security System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Security System Market Intelligence
Single-family homeowners is collapsing as the dominant buyer archetype while rental property managers and smart home integrators capture expanding share. ADT leverages its national monitoring infrastructure to sustain recurring revenue density across suburban markets. SimpliSafe competes through direct-to-consumer channel control and self-install hardware economics. Vivint dominates the integrated smart home segment with professionally installed panel systems and home automation bundling.
A home security system comprises interconnected electronic devices including motion detectors, door and window sensors, surveillance cameras, and central monitoring panels designed to detect intrusion, environmental hazards, or unauthorized access and alert occupants or monitoring services through wired, wireless, or cellular communication protocols. Video surveillance occupies the largest product type position due to camera hardware margin pools and cloud storage subscription attachment, while IoT-enabled technology segments expand fastest as Matter protocol interoperability and voice assistant integration reduce friction for non-technical users. Residential end users remain the volume base, though smart home integrators represent the premium margin tier where whole-home automation bundling elevates average contract values.
FCC regulates wireless transmission frequencies for security sensors under Part 15 rules, while UL certification standards govern panel reliability and monitoring center response protocols across the United States and Canada. State-level licensing requirements for alarm installation and monitoring vary considerably, creating compliance complexity for national providers expanding across provincial and state boundaries. Stakeholders must weigh the capital requirements of proprietary monitoring infrastructure against the flexibility of third-party central station partnerships as buyer preferences fragment between professional and self-monitored architectures.
Market Dynamics
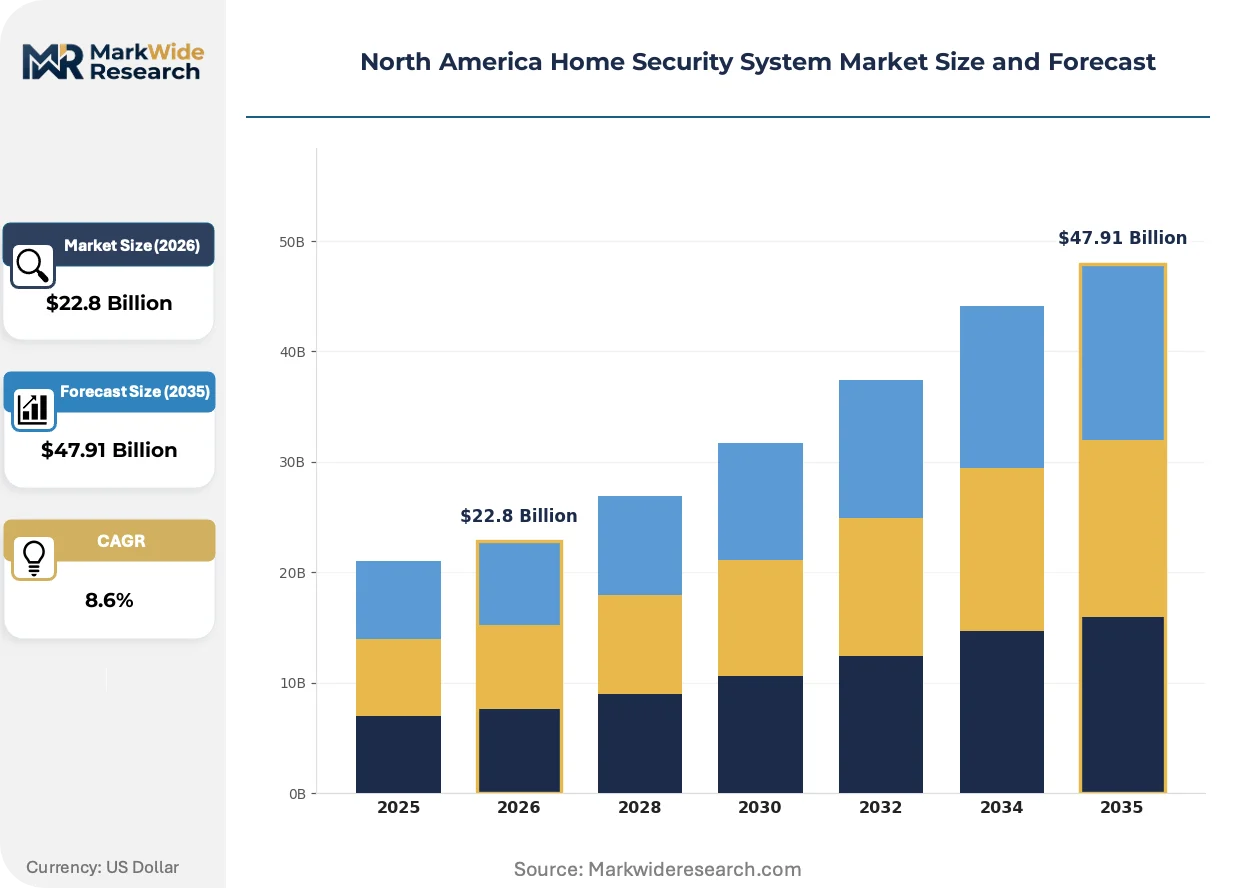
Professional monitoring contracts are fragmenting across buyer archetypes as rental property managers and smart home integrators displace single-family homeowners from volume leadership, compressing traditional channel economics while expanding recurring revenue pools in multifamily and integrated automation segments.
Growth Catalysts
- Hurricane retrofit cycles:Storm damage in Florida and Texas accelerates hardware replacement and professional monitoring subscriptions across coastal counties where insurance carriers mandate certified systems.
- FCC Part 15 spectrum allocation:Unlicensed wireless transmission rules enable low-cost sensor deployment without per-device licensing fees, reducing barriers for self-install product lines.
- Matter protocol standardization:Cross-platform interoperability between Amazon Alexa, Google Home, and Apple HomeKit reduces friction for non-technical users adopting integrated security and automation bundles.
Market Restraints
- Semiconductor supply concentration:RF chip and image sensor fabrication concentrates in East Asian foundries, exposing hardware manufacturers to lead time volatility and tariff exposure on finished modules.
- Installation labor licensing fragmentation:State-level alarm contractor requirements vary across 50 US jurisdictions and Canadian provinces, creating compliance overhead for national service expansion.
- Cellular module cost structure:4G LTE and emerging 5G modem components represent 15-20% of panel bill-of-materials, compressing margins on entry-tier hardware SKUs.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia multifamily construction permits lag US penetration rates by 8-12 percentage points, offering whitespace for professional monitoring contract growth.
- Voice assistant integration convergence:Natural language processing embedded in security panels enables hands-free arming and status queries, differentiating premium tiers from app-only competitors.
- Insurance carrier channel partnerships:Property and casualty underwriters in Texas and Florida increasingly require monitored systems for coastal coverage, creating referral demand pull through agent networks.
Industry Challenges
- UL 827 certification timelines:Central station monitoring facility accreditation requires 12-18 month validation cycles, constraining rapid geographic expansion for new entrants building proprietary infrastructure.
- Legacy panel integration complexity:Hardwired zones from 1990s-2000s installations resist seamless migration to wireless ecosystems, forcing costly rip-and-replace or hybrid converter deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Security System Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Surveillance, Alarms, Access Control, Sensors Technology: Wired, Wireless, Cloud-based, IoT-enabled End User: Residential, Homeowners, Rental Properties, Smart Home Integrators Service Type: Installation, Monitoring, Maintenance, Consultation |
| Companies Covered | Cove Security, Brinks Home Security, ADT, Alder Security, Ring Alarm, SimpliSafe, Frontpoint Home Security, abode, Vivint, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Security System Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is compressing cloud dependency for video analytics, while regulatory pressure on data localization and buyer preference for subscription flexibility reshape hardware and service architectures across residential and commercial segments.
Edge-based computer vision is decomposing the traditional cloud-only analytics model. On-device person, vehicle, and package detection reduces latency and bandwidth costs for camera-heavy installations. Multifamily property managers in Texas and Florida are prioritizing local processing to avoid cellular data overages across hundreds of units per property. This shift compresses cloud storage attachment rates while elevating hardware BOM costs and firmware complexity.
FCC Part 15 enforcement actions against non-compliant RF transmitters intensified in 2023-2024, with unlicensed spectrum congestion in the 915 MHz ISM band triggering coexistence failures between security sensors and smart home devices. Manufacturers are responding with frequency-agile radio designs and dynamic channel selection algorithms. The certification burden falls heaviest on white-label sensor suppliers serving the self-install segment, where rapid SKU turnover conflicts with 3-6 month FCC approval timelines.
Subscription unbundling is fragmenting the traditional all-in-one contract model. Buyers increasingly separate hardware purchase from monitoring service selection, with self-install users toggling between professional, self-monitored, and no-monitoring states through app-based configuration. This behavior concentrates among younger homeowners in urban Texas markets and snowbird communities in Florida, where seasonal occupancy patterns favor flexible activation. Channel partners must now support hardware margins independent of recurring revenue attachment, reversing two decades of subsidized equipment economics.
North America Home Security System Market Segmentation
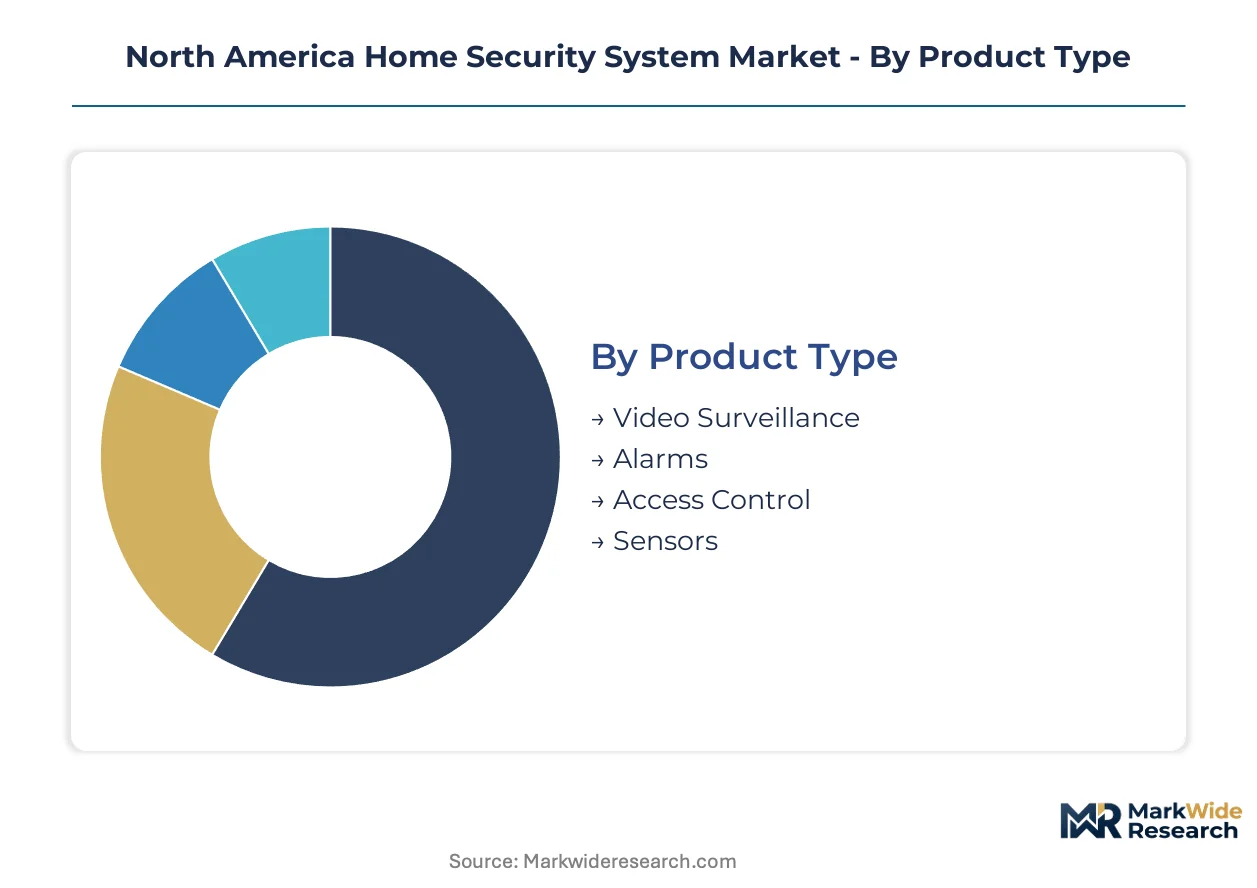
Segmentation in the North America home security market reveals divergent margin structures across hardware categories and service models. Buyers fragment between self-install direct channels and professionally integrated systems, forcing suppliers to maintain parallel product architectures.
Product Type:
Domestic demand concentrates in camera hardware and sensor networks, while Canadian markets show stronger uptake of integrated panel systems relative to standalone devices.
- Video Surveillance:Camera hardware spans indoor dome, outdoor bullet, and video doorbell form factors with IP-based PoE and Wi-Fi connectivity options. Texas and Florida coastal counties drive replacement cycles where insurance carriers mandate certified equipment, compressing hardware margins but elevating cloud storage attachment.
- Alarms:Central panel systems coordinate intrusion detection through hardwired and wireless zone configurations. Multifamily property managers in Ontario and British Columbia are expanding professional monitoring contracts across rental portfolios, outpacing single-family penetration rates.
- Access Control:Biometric readers, key fobs, and mobile credential systems manage entry points.
- Sensors:Motion detectors, door/window contacts, and glass-break detectors form the perimeter detection layer.
Video Surveillance commands the established base. The steepest expansion runs through Alarms as rental property managers scale monitoring contracts.
Technology:
Cost tiers separate legacy infrastructure from next-generation deployments, with wireless and IoT-enabled systems capturing premium positioning against wired baseline configurations.
- Wireless:RF-based sensor networks operate in FCC Part 15 unlicensed spectrum bands, eliminating per-device licensing overhead. Florida and Texas self-install markets favor wireless retrofit solutions where hardwired legacy zones resist cost-effective migration.
- IoT-enabled:Matter protocol interoperability enables cross-platform integration between Amazon Alexa, Google Home, and Apple HomeKit ecosystems. Smart home integrators in suburban Texas markets bundle these systems with whole-home automation, elevating average contract values substantially.
- Wired:Hardwired zones deliver reliability for new construction installations.
- Cloud-based:Remote arming, status monitoring, and firmware updates shift functionality to hosted infrastructure.
Wired systems anchor legacy infrastructure. IoT-enabled configurations are climbing the fastest as protocol standardization reduces integration friction.
End User:
Customer type determines channel economics, with residential volume contrasting against integrator-driven premium margins and rental property recurring revenue density.
- Rental Properties:Multifamily operators deploy scaled sensor networks and centralized monitoring across hundreds of units per property. Texas and Florida markets lead this segment where institutional property managers professionalize security infrastructure to reduce liability exposure and satisfy carrier requirements.
- Smart Home Integrators:Professional installation firms bundle security panels with lighting, climate, and entertainment automation. These buyers concentrate in high-income suburban clusters across the United States and Canada, commanding the highest service margins in the value chain.
- Residential:Single-family homeowners represent the volume foundation.
- Homeowners:Owner-occupied dwellings with direct purchasing authority.
Residential buyers form the volume base. Rental Properties represent the steepest expansion trajectory as institutional operators consolidate monitoring contracts.
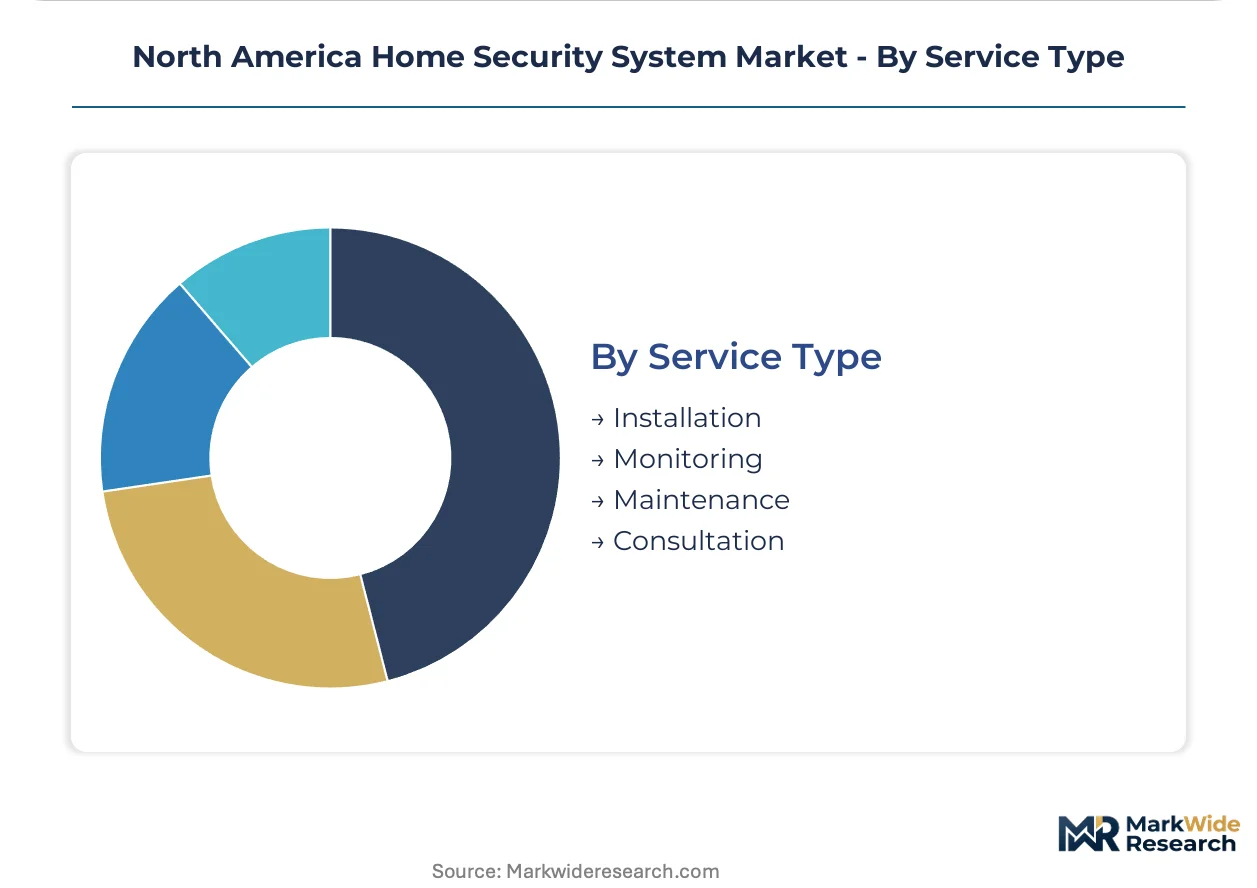
Service Type:
Application context separates one-time hardware deployment from recurring revenue streams, with monitoring services commanding the highest lifetime value per customer relationship.
- Monitoring:Central station operators respond to alarm signals through UL 827-certified facilities, dispatching emergency services per contracted protocols. Hurricane exposure in Florida and Texas accelerates subscription uptake where carriers link coverage to certified professional response.
- Installation:Labor services span self-install guidance, professional panel programming, and hardwired zone termination. State-level licensing fragmentation across United States jurisdictions and Canadian provinces creates compliance overhead for national service providers.
- Maintenance:Ongoing hardware testing, battery replacement, and firmware updates.
- Consultation:System design and risk assessment services for complex deployments.
Installation captures the upfront revenue pool. Monitoring delivers the steepest expansion as recurring contract models displace transactional hardware sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing and monitoring infrastructure concentrate in the United States, though Canadian markets present underpenetrated expansion corridors for professional service contracts.
United States
Hurricane retrofit cycles in Florida and Texas drive replacement demand where insurance carriers mandate certified professional monitoring systems for coastal coverage. FCC Part 15 rules govern unlicensed wireless sensor transmissions, enabling low-cost RF deployment without per-device licensing overhead. Dallas-Fort Worth and Houston metropolitan clusters anchor multifamily property manager procurement at scale.
Canada
Ontario and British Columbia multifamily construction permits lag US penetration rates by 8-12 percentage points, creating whitespace for monitoring contract expansion. Health Canada and PMRA coordinate with UL standards for central station certification across provincial boundaries. Toronto and Vancouver institutional property managers are consolidating security infrastructure across rental portfolios faster than national averages.
Mexico
Northern border states exhibit growing demand for cross-compatible systems serving binational residential developments and commercial facilities. The national telecommunications regulator IFT manages spectrum allocation for IoT-enabled security devices operating near US frequencies. Monterrey and Tijuana manufacturing clusters supply sensor assemblies and panel enclosures to North American integrators.
North America Home Security System Market Key Industry Players
Concentration sits with national monitoring infrastructure operators and direct-to-consumer hardware platforms, creating a tiered structure where recurring revenue density competes against self-install economics. Three archetypes dominate: established central station networks with suburban market penetration, direct-to-consumer brands controlling channel margins, and integrated smart home specialists bundling automation. Competitive moves center on multifamily property manager contract consolidation and voice assistant integration partnerships.
Within the national infrastructure tier, ADT and Brinks Home Security anchor positions through recurring revenue density across suburban markets. Vivint occupies the integrated automation vector with professionally installed panel systems. SimpliSafe exemplifies the direct-to-consumer archetype through self-install hardware economics and channel control.
| Leading Market Players |
|---|
| Cove Security |
| Brinks Home Security |
| ADT |
| Alder Security |
| Ring Alarm |
| SimpliSafe |
| Frontpoint Home Security |
| abode |
| Vivint |
| Others |
Cost & Logistics Intelligence
Cellular module substitution for RF-only panels is redrawing component sourcing maps and compressing hardware margin structures across entry-tier SKUs. This transition simultaneously elevates East Asian semiconductor exposure and intensifies price competition between self-install direct channels and professionally integrated systems.
Pricing Analysis
FCC Part 15 dictates the pricing tier structure by imposing certification overhead that stratifies hardware costs across professional-install and self-install product lines. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified panel systems from uncertified sensor bundles and white-label commodity hardware. Cost compression in economy tiers is intensifying because cellular modem components represent a disproportionate share of entry-SKU bill-of-materials. Rental property managers exhibit the lowest price sensitivity due to liability-driven carrier mandates, while younger urban homeowners in Texas markets demonstrate the highest elasticity.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai and Busan elevates inbound logistics costs for RF chip and image sensor deliveries to North American assembly facilities. Hardware manufacturing concentrates in China, Taiwan, and South Korea, where foundry capacity for cellular modems and computer vision processors rests on concentrated East Asian fabrication networks. Supply chain risk centers on tariff exposure for finished modules crossing Pacific trade lanes. Distribution runs through national integrator networks, direct-to-consumer fulfillment centers, and big-box retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hurricane retrofit cycles position this market in recovery phase, with storm-driven replacement demand in Florida and Texas coastal counties creating cyclical uplift for professional monitoring subscriptions.
For Market Incumbents: Compound recurring revenue density through multifamily property manager contract consolidation across Texas and Florida rental portfolios. Deepen backward integration into cellular modem sourcing to offset semiconductor supply concentration. Invest in UL 827 certification infrastructure to defend against self-install channel erosion. For New Entrants and Emerging Players: Differentiate on Matter protocol interoperability to capture smart home integrator segments in suburban Texas markets. Target Canadian provincial whitespace in Ontario and British Columbia where multifamily penetration lags US benchmarks. Pursue insurance carrier channel partnerships as the primary go-to-market vector. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated monitoring infrastructure operators with UL-certified central station networks. Long-term viability over the coming decade hinges on recurring revenue attachment rates and geographic expansion velocity. Watch FCC Part 15 enforcement intensity as the signal indicating regulatory barrier height for new hardware entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Integration | Cross-platform interoperability reduces friction for non-technical users adopting bundled automation. |
| Insurance Carrier Partnership | Property and casualty underwriters in Texas and Florida mandate monitored systems for coastal coverage. |
| Cellular Module Backward Integration | In-house sourcing of 4G LTE components mitigates East Asian foundry concentration risk. |
| Canadian Provincial Expansion | Ontario and British Columbia multifamily permits lag US rates by 8-12 percentage points. |
| Edge AI Video Analytics | On-device processing reduces cloud dependency and cellular data overages for multifamily properties. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with central station monitoring directors, smart home integration firm owners, multifamily property managers, FCC compliance officers, and insurance carrier risk assessors. Secondary validation drew from FCC equipment authorization databases, UL certification registries, state-level alarm contractor licensing records, and municipal construction permit filings. Bottom-up hardware shipment estimates triangulated against top-down monitoring contract value pools.
Across the analysis window, forecasts model product type segmentation across video surveillance, alarms, access control, and sensors; technology tiers spanning wired, wireless, IoT-enabled, and cloud-based architectures; and service type splits between monitoring, installation, maintenance, and consultation. CAGRs derive from regression analysis against housing starts, insurance penetration rates, and retrofit cycle timing. Forecast inputs incorporate Matter protocol adoption curves and cellular module cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained hurricane frequency, stable FCC spectrum allocation, or intact transpacific logistics lanes would require recalibration. Forecasts reflect documented assumptions regarding multifamily construction permit velocity and insurance carrier mandate expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
China Access Control Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Global Barrier Systems Market