
 APAC Home Security System Market | 2026-2036
APAC Home Security System Market Size, Share, and Industry Trends Forecast 2026-2036
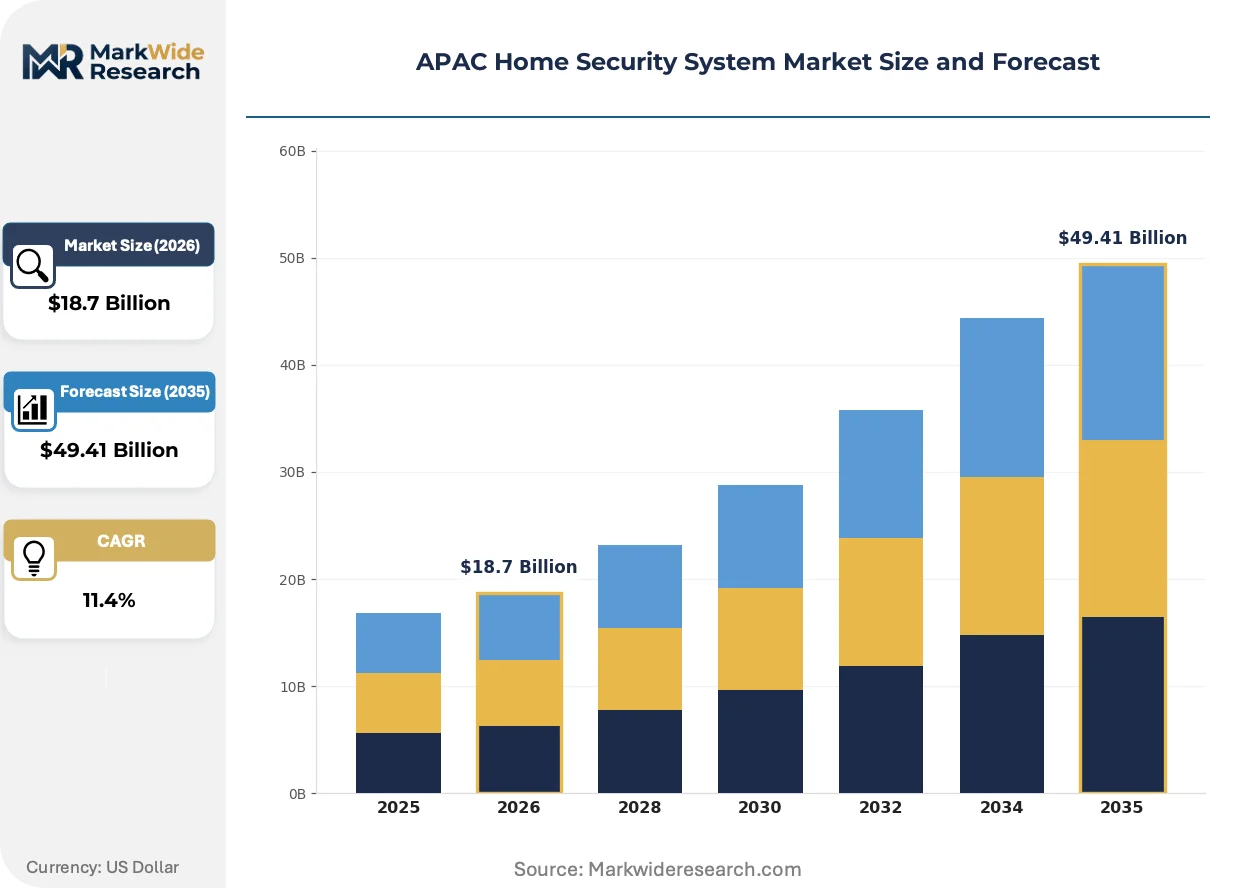
APAC Home Security System Market Outlook
Aftermarket service revenue is fragmenting across the APAC Home Security System landscape as hardware margins compress and vendors chase recurring income streams. Hangzhou Hikvision Digital Technology dominates video surveillance manufacturing through captive component supply and in-house sensor production. SECOM Co. Ltd. anchors Japan's professional monitoring segment with technician-dense service networks. Xiaomi Inc. competes aggressively on Wi-Fi-enabled device ecosystems priced for mass residential penetration.
An APAC home security system comprises integrated electronic components designed to detect intrusion, environmental hazards, and unauthorized access through sensor arrays, control panels, and communication gateways operating on protocols from 2.4 GHz wireless to dedicated cellular bands. These systems serve primarily to reduce property risk, lower insurance premiums, and enable remote premises management for residential and commercial owners. Video surveillance captures the largest installed base across the region due to declining camera unit costs and cloud storage bundling, while smart locks represent the fastest-expanding product category as Bluetooth and Wi-Fi connectivity eliminates hard-wiring barriers in retrofit applications. Managed services installation types command premium pricing through 24/7 monitoring contracts that lock in multi-year subscriber relationships.
China's MIIT enforces GB standards for networked security devices that mandate encryption protocols and domestic data residency, effectively raising compliance costs for foreign suppliers. Japan's METI issues efficiency guidelines for connected home equipment that shape power consumption benchmarks for battery-backed alarm systems. Australia's state-level insurance regulators increasingly tie premium discounts to certified professional installation, directly steering consumer choices toward monitored service packages. Stakeholders must weigh the trade-off between DIY hardware volumes and the stickier lifetime value of subscription-backed managed services as connectivity standards proliferate.
Market Dynamics
Aftermarket service revenue fragmentation is compressing hardware margins across the APAC Home Security System landscape, forcing vendors to pivot toward recurring income streams through managed monitoring contracts and cloud storage bundling.
Growth Catalysts
- Insurance-linked installation mandates:Australian state-level regulators tie premium discounts to certified professional installation, steering consumer choices toward monitored service packages in metropolitan property markets.
- GB standards enforcement:China's MIIT mandates encryption protocols and domestic data residency for networked security devices, raising compliance barriers that favor established suppliers with localized infrastructure.
- Bluetooth and Wi-Fi connectivity:Wireless protocols eliminate hard-wiring barriers in retrofit applications, accelerating smart lock adoption across suburban residential developments in India.
Market Restraints
- Component supply concentration:Captive sensor production by dominant video surveillance manufacturers creates dependency risks for downstream system integrators lacking upstream control.
- METI efficiency compliance costs:Japan's power consumption benchmarks for battery-backed alarm systems force redesign cycles that extend product development timelines.
- Cellular module input volatility:Dedicated communication gateway components face price pressure from semiconductor foundry capacity allocation to higher-margin sectors.
Strategic Opportunities
- Suburban retrofit penetration:India's residential smart lock deployment remains underpenetrated outside gated community developments, offering volume expansion for Wi-Fi-enabled device ecosystems.
- Cloud storage bundling models:Video surveillance vendors can capture recurring revenue by packaging AI-enhanced analytics with tiered storage subscriptions.
- Technician-dense service networks:Professional monitoring infrastructure in Japan provides a template for replication in Australia's insurance-mandated installation corridors.
Industry Challenges
- Multi-protocol integration complexity:Control panels must bridge 2.4 GHz wireless, dedicated cellular bands, and emerging Matter standards simultaneously.
- Certification timeline compression:Dual compliance with China's GB encryption requirements and Australia's insurance certification standards extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Home Security System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Surveillance, Alarm Systems, Access Control, Smart Locks Technology: Wi-Fi, Wired, Cellular, Bluetooth End User: Residential, Commercial, Government, Educational Installation Type: Do-It-Yourself, Professional, Managed Services, Integrated Solutions |
| Companies Covered | Hangzhou Hikvision Digital Technology, SECOM Co. Ltd., Honeywell International, Johnson Controls, Bosch Security Systems, Schneider Electric, Xiaomi Inc., Samsung Electronics, ASSA ABLOY, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Home Security System Market Strategic Shifts
Connectivity standard proliferation is fragmenting competitive moats across the APAC Home Security System market, with protocol convergence and regulatory data localization reshaping product architecture decisions.
AI-powered edge analytics embedded directly into camera firmware is rendering obsolete centralized NVR-dependent processing architectures. Mid-market residential installers across Australian metropolitan corridors are specifying on-device person-vehicle-package detection to reduce bandwidth costs and cloud dependency. This shift is compressing gross margins for traditional DVR/NVR hardware suppliers while elevating semiconductor content value in camera bill-of-materials.
METI energy efficiency guidelines for connected home equipment are tightening standby power thresholds for battery-backed alarm systems in Japan. Manufacturers must redesign power management circuits and source lower-leakage components to maintain product eligibility. Professional monitoring providers with technician-dense service networks face the steepest compliance recertification burdens as their installed base spans multiple product generations.
Subscription unbundling is fragmenting buyer-seller relationships across the region. Australian property owners increasingly separate hardware procurement from monitoring service selection, comparing standalone cloud storage pricing against integrated packages. This behavior is most pronounced in Sydney and Melbourne insurance-linked installation corridors where premium discounts depend on certified professional work rather than brand-specific monitoring contracts.
APAC Home Security System Market Segmentation
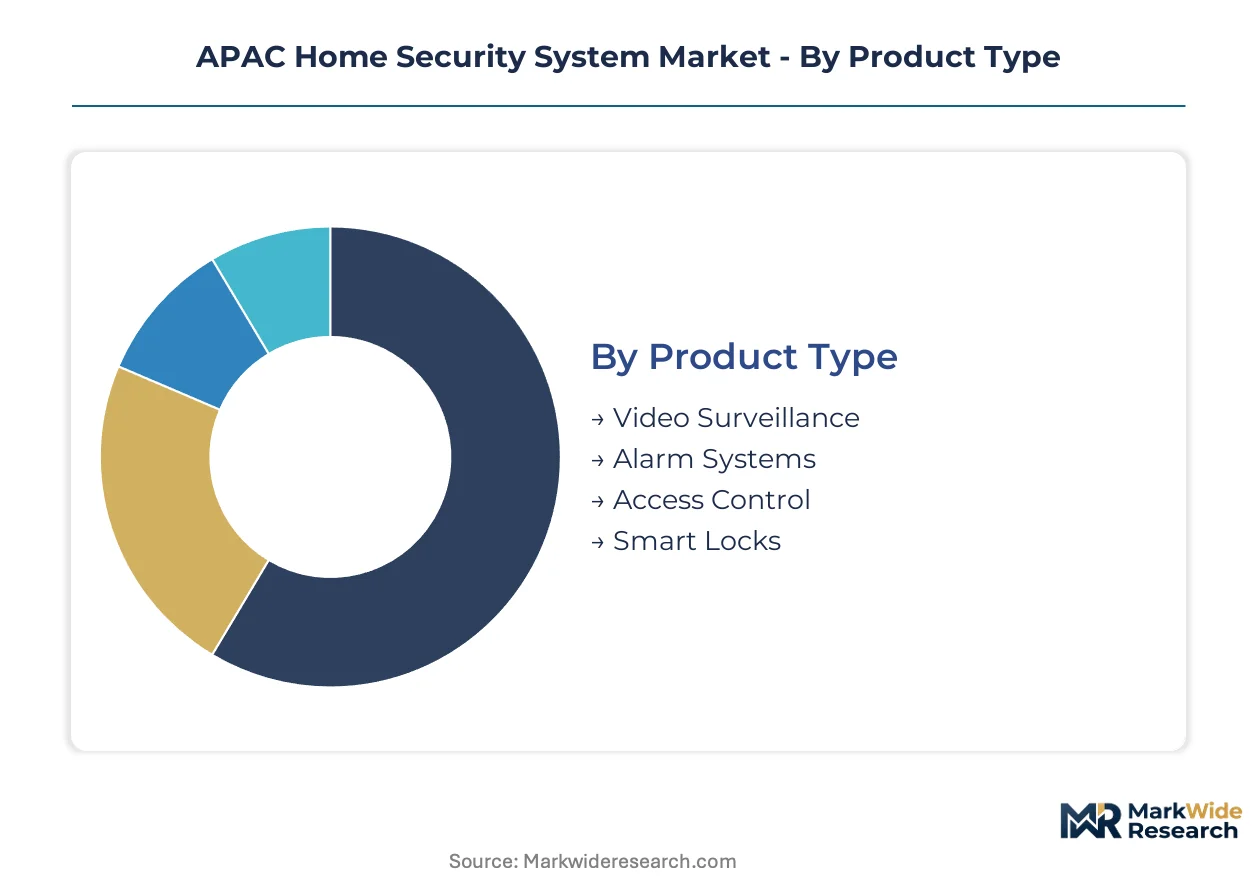
Segmentation in the APAC Home Security System market reveals how technology choices and service models fragment purchasing behavior across price-sensitive residential buyers and compliance-driven commercial operators. Product architecture decisions cascade through installation complexity, recurring revenue potential, and regulatory alignment requirements.
Product Type:
Cost tier differentiation separates mass-market hardware from premium integrated systems with bundled monitoring services.
- Video Surveillance:Camera arrays with edge AI processing now embed person-vehicle-package detection directly into firmware, displacing centralized NVR architectures. Demand concentrates in Australian metropolitan corridors where insurance-linked installation mandates favor certified professional deployment with cloud storage bundling.
- Smart Locks:Bluetooth and Wi-Fi connectivity eliminates hard-wiring barriers, enabling rapid retrofit penetration across suburban residential developments in India. Battery-backed designs face METI efficiency compliance costs that extend product redesign cycles for Japan market entry.
- Alarm Systems:Sensor arrays and control panels operating on dedicated cellular bands serve property risk reduction and insurance premium reduction objectives.
- Access Control:Biometric and credential-based entry management systems address unauthorized access prevention in commercial and government facilities.
Video Surveillance commands the established base. The steepest expansion runs through Smart Locks.
Technology:
Application requirements dictate protocol selection, with retrofit flexibility competing against reliability guarantees in buyer decisions.
- Wi-Fi:2.4 GHz wireless connectivity enables mass-market residential penetration through smartphone-managed ecosystems priced for volume. China's GB standards enforcement mandates encryption protocols and domestic data residency, raising compliance barriers for foreign Wi-Fi device suppliers lacking localized infrastructure.
- Cellular:Dedicated communication bands provide backup connectivity during internet outages, critical for professional monitoring contracts. Semiconductor foundry capacity allocation to higher-margin sectors creates input price volatility for gateway module procurement.
- Bluetooth:Low-energy pairing supports smart lock activation and sensor proximity detection with minimal power draw.
- Wired:Hard-wired installations deliver reliability guarantees for commercial and government end users with infrastructure investment capacity.
Wi-Fi dominates residential volume. Cellular secures the premium monitoring tier.
End User:
Customer type determines compliance burden, with institutional buyers facing certification requirements that residential purchasers avoid.
- Residential:Suburban property owners across India and Australia drive smart lock and Wi-Fi camera adoption through insurance premium incentives and remote premises management needs. Subscription unbundling behavior in Sydney and Melbourne separates hardware procurement from monitoring service selection.
- Commercial:Retail, office, and industrial facilities require integrated solutions with 24/7 monitoring contracts that lock in multi-year subscriber relationships and command premium pricing.
- Government:Public sector procurement follows domestic data residency mandates under China's MIIT regulations for networked security devices.
- Educational:Campus security programs specify access control and video surveillance with centralized monitoring for facility protection.
Residential captures volume scale. Commercial yields the highest lifetime value per installation.
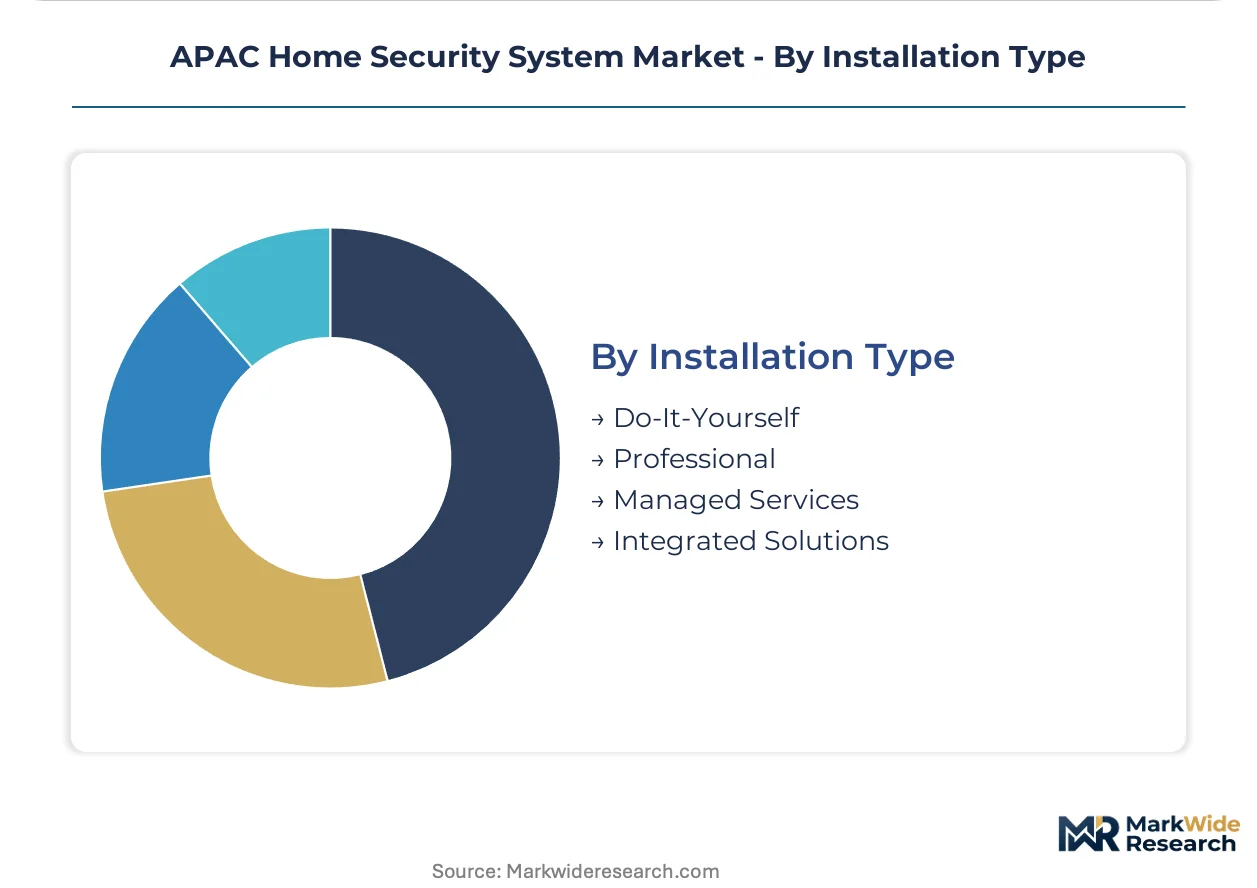
Installation Type:
Margin structure varies dramatically across self-service and technician-dependent deployment models.
- Managed Services:24/7 professional monitoring with technician-dense service networks anchors Japan's market structure and provides a template for Australia's insurance-mandated installation corridors. Multi-year contracts generate recurring revenue that offsets hardware margin compression.
- Do-It-Yourself:Self-installation kits with smartphone configuration expand addressable market reach for Wi-Fi-enabled device ecosystems competing on mass residential penetration.
- Professional:Certified installer deployment satisfies Australia's state-level insurance regulator requirements for premium discount eligibility.
- Integrated Solutions:Multi-system unification across video, access, and alarm components serves large commercial and government facilities.
Managed Services commands pricing power. Do-It-Yourself expands fastest across price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in China dominate upstream supply, while service-intensive markets in Japan and Australia concentrate downstream value capture through professional monitoring networks.
China
MIIT enforcement of GB encryption standards and domestic data residency mandates reshapes product architecture for networked security devices. Zhejiang province hosts the densest concentration of video surveillance manufacturing, with Hangzhou-based suppliers integrating captive sensor production to offset hardware margin compression.
Japan
METI standby power thresholds for battery-backed alarm systems force redesign cycles across multi-generation installed bases. Technician-dense service networks in the Kanto corridor anchor professional monitoring revenue streams that lock in multi-year subscriber relationships.
Australia
State-level insurance regulators tie premium discounts to certified professional installation, concentrating demand in Sydney and Melbourne metropolitan corridors. Subscription unbundling behavior separates hardware procurement from monitoring service selection, fragmenting vendor-buyer relationships.
India
Bluetooth and Wi-Fi connectivity eliminates hard-wiring barriers, accelerating smart lock deployment across suburban residential developments. Gated community penetration runs ahead of broader retrofit adoption, leaving volume expansion opportunities in price-sensitive mass residential segments.
South Korea
Semiconductor foundry capacity allocation to higher-margin sectors creates input price volatility for cellular gateway modules. Seoul Capital Area demand concentrates in integrated smart home ecosystems where security functions bundle with broader device management platforms.
APAC Home Security System Market Competitive Environment
Video surveillance specialists and professional monitoring providers split the market along hardware-versus-service fault lines. Captive component supply and in-house sensor production characterize the manufacturing archetype, while technician-dense service networks define the recurring revenue archetype. Competitive moves cluster around cloud storage bundling and multi-protocol control panel integration as connectivity standards proliferate.
Among China-based manufacturers, Hangzhou Hikvision Digital Technology exemplifies the vertically integrated production archetype through captive supply chain control. SECOM Co. Ltd. occupies a position within Japan's professional monitoring tier, representing the technician-dense service network model. Xiaomi Inc. sits within the mass-market ecosystem archetype, competing on Wi-Fi-enabled device penetration priced for volume residential adoption.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology |
| SECOM Co. Ltd. |
| Honeywell International |
| Johnson Controls |
| Bosch Security Systems |
| Schneider Electric |
| Xiaomi Inc. |
| Samsung Electronics |
| ASSA ABLOY |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo freight corridor carries semiconductor and sensor components from Zhejiang manufacturing clusters to assembly facilities across Southeast Asia, with freight cost volatility feeding directly into hardware margin compression and widening the spread between certified professional installation premiums and mass-market DIY pricing.
Pricing Analysis
Australia's state-level insurance certification standards dictate the pricing tier structure across the APAC Home Security System landscape. Three-tier pricing structure across premium, standard, and economy levels separates managed services with 24/7 monitoring from self-install kits and professional-only deployment. Cost compression in the Wi-Fi-enabled device tier is intensifying because Xiaomi and ecosystem competitors race for suburban residential volume in India. Commercial facilities with multi-year monitoring contracts show the least price sensitivity, while mass residential buyers in price-sensitive segments drive aggressive bundling of hardware with cloud storage subscriptions.
Supply Chain Analysis
Export-control restrictions on advanced AI chipsets and edge-processing semiconductors limit flows from Taiwan and South Korea to mainland China-based camera manufacturers. Component supply concentrates in Zhejiang province for video surveillance assembly, with South Korean foundries producing cellular gateway modules and Japanese suppliers providing battery management ICs for METI-compliant alarm systems. Single-source vulnerability runs through captive sensor production at dominant manufacturers like Hangzhou Hikvision Digital Technology. Distribution runs through technician-dense service networks in Japan and certified installer channels in Australia's insurance-mandated metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription unbundling as Australian property owners separate hardware procurement from monitoring service selection, fragmenting vendor-lock-in potential across the APAC Home Security System landscape.
For Market Incumbents: Harden cloud storage bundling architectures against AI-powered edge analytics embedded directly into camera firmware, which threatens centralized NVR-dependent revenue streams. Deepen backward integration into captive sensor production to offset hardware margin compression from Wi-Fi-enabled mass-market competitors. Lock in multi-year subscriber relationships through technician-dense service network expansion in Australia's insurance-linked installation corridors.
For New Entrants and Emerging Players: Pursue suburban retrofit penetration outside India's gated community developments, where Bluetooth and Wi-Fi smart lock deployment remains underpenetrated among price-sensitive mass residential segments. Target cloud storage unbundling behavior in Sydney and Melbourne metropolitan property markets by offering standalone AI-enhanced analytics tiers. Lead with smartphone-managed ecosystem pricing to capture volume before incumbents adapt subscription models.
For Investors and Strategic Acquirers: Technician-dense professional monitoring providers with multi-generation installed bases represent the most defensible acquisition archetype in a market pivoting toward recurring revenue. Long-term viability hinges on navigating METI efficiency compliance recertification burdens and China's GB encryption localization requirements without product launch cycle disruption. Watch for inflection when insurance regulators in additional Australian states tie premium discounts to certified installation, expanding the addressable market for managed services.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Integration | On-device person-vehicle-package detection reduces bandwidth costs and cloud dependency for Australian metropolitan installers. |
| Cellular Gateway Supply Diversification | Dual-sourcing from South Korean and Taiwanese foundries mitigates semiconductor capacity allocation volatility for professional monitoring providers. |
| GB Standards Localization Infrastructure | Domestic data residency compliance in China raises barriers favoring established suppliers with localized encryption architecture. |
| Technician Network Replication | Japan's Kanto corridor service density provides template for Australia's insurance-mandated installation corridor expansion. |
| Subscription Unbundling Response | Standalone cloud storage pricing tiers capture hardware-procurement-only buyers in Sydney and Melbourne property markets. |
Study Parameters
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings in this study. Primary interviews with professional monitoring service directors, cellular module procurement managers, and insurance certification specialists combined with secondary validation from MIIT GB standards publications, METI efficiency guideline releases, and Australian state-level insurance regulator circulars. Bottom-up triangulation across product-type shipment estimates and top-down reconciliation against national smart home penetration surveys ensure consistency.
Calibration against historical adoption curves in comparable connected-device markets informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, connectivity protocol, installation type, and regulatory compliance tier. CAGRs derive from fitted growth curves adjusted for insurance mandate expansion timelines and semiconductor foundry capacity allocation patterns. Edge AI adoption rates and subscription unbundling velocity serve as industry-specific forecast inputs.
Sensitivities concentrate around MIIT enforcement intensity for domestic data residency, METI standby power threshold revisions, and Australian state-level insurance mandate expansion. Forecasts reflect documented assumptions about protocol convergence timelines and cloud storage pricing elasticity. Material shifts in semiconductor export-control restrictions or cellular module foundry capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Access Control Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Border Security System Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Mode Locking Device Market