
 Germany Access Control Market | 2026-2036
Germany Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Access Control Market Insights
Healthcare provider demand is broadening as German hospitals replace legacy card readers with contactless biometric systems to meet infection-control protocols. Bosch leverages its industrial automation heritage to anchor integrated building-security platforms. ASSA ABLOY competes through door-hardware specialization that extends into electronic access ecosystems. Siemens dominates smart-building integration, controlling energy and security from unified dashboards.
Germany access control encompasses physical and logical entry-management systems that authenticate identity through credentials, biometrics, or mobile tokens before releasing electronic locks or network gates. Typical biometric readers process fingerprint or iris templates within 500 milliseconds against encrypted templates stored locally or on federated servers, primarily protecting personnel, data, and regulated assets across commercial and institutional environments. Biometric systems lead product-type margin pools where liveness-detection algorithms command premium pricing, while cloud-based solutions grow fastest as multi-site operators abandon on-premise server maintenance. Mobile access technology displaces proximity cards in commercial buildings where smartphone-carrying rates approach ubiquity among white-collar workforces.
Germany's Federal Office for Information Security (BSI) shapes technical baseline requirements through Common Criteria certification mandates for critical infrastructure access components. The EU AI Act, enforced by national regulators, imposes risk-classification obligations on biometric identification systems deployed in public-sector and high-security industrial settings. Stakeholders must monitor whether BSI updates its technical guidelines to incorporate AI Act conformity routes before procurement cycles lock in multi-year access-control investments.
Market Dynamics
German healthcare networks are dismantling legacy card-based entry systems as infection-control mandates and BSI technical guidelines converge on biometric authentication architectures. This structural pivot is redrawing procurement specifications across hospital groups, industrial campuses, and federal facilities.
Growth Catalysts
- BSI Critical Infrastructure Mandates:Germany's Federal Office for Information Security compels Common Criteria certification for access components protecting energy, transport, and healthcare assets. Facility operators must upgrade non-compliant systems before contract renewals.
- Healthcare Biometric Adoption:German hospital networks are replacing contactless card readers with palm-vein and facial recognition terminals to eliminate shared-surface transmission vectors in surgical wards and intensive care units.
- Bavaria Industrial Corridor Concentration:Manufacturing compounds around Munich and Nuremberg are consolidating multi-site access management through cloud-connected platforms, creating demand density for integrated building-security ecosystems.
Market Restraints
- Semiconductor Input Volatility:Access control hardware depends on specialized microcontrollers and secure-element chips sourced from concentrated Asian foundry capacity, exposing German manufacturers to allocation delays and cost spikes.
- EU AI Act Classification Burden:Biometric identification systems deployed in public-sector and high-security industrial settings face mandatory risk-classification obligations and conformity assessment procedures that extend procurement timelines.
- Legacy System Interoperability Friction:Existing Siemens Desigo and Bosch building-management installations use proprietary protocols that resist seamless integration with third-party biometric readers, forcing costly middleware development or full-stack replacement.
Strategic Opportunities
- Mobile Access Convergence:Smartphone-carrying rates among German white-collar workforces enable Bluetooth Low Energy and NFC credential deployment, displacing plastic proximity cards in commercial real estate portfolios.
- Berlin Public-Sector Modernization Pipeline:Federal and municipal facility renovation programs are specifying unified physical-logical access platforms that authenticate personnel for both building entry and network resource access.
- Liveness Detection Premium Tier:Anti-spoofing algorithms using 3D depth sensing and infrared spectral analysis command pricing premiums in banking and defense applications where presentation attacks pose existential security risks.
Industry Challenges
- Cyber-Physical Security Skill Convergence:German system integrators face acute shortages of engineers fluent in both OT network protocols and IT security frameworks, slowing deployment of converged access platforms.
- Common Criteria Certification Timelines:BSI evaluation and assurance procedures for critical infrastructure components extend 12-18 months, compressing vendor revenue recognition and complicating product roadmap synchronization with procurement cycles.
- Multi-Vendor Platform Integration Complexity:End-users assembling best-of-breed solutions from disparate hardware and software suppliers encounter API fragmentation and inconsistent firmware update mechanisms that degrade operational reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Access Control Market |
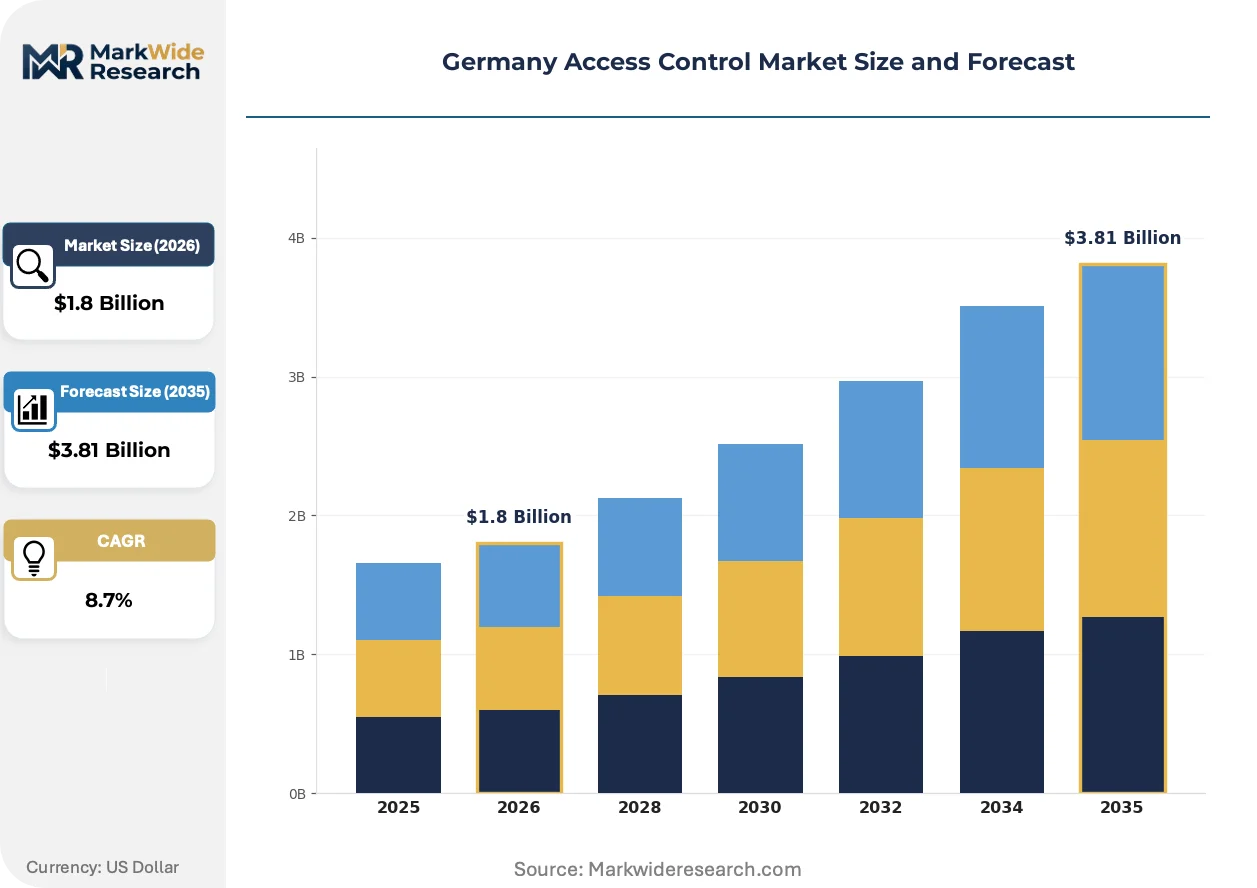
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Keypad Systems, Proximity Cards, Smart Locks Application: Commercial Buildings, Residential Properties, Industrial Facilities, Government Institutions Technology: Cloud-Based Solutions, On-Premise Systems, RFID Technology, Mobile Access End User: Retail Businesses, Educational Institutions, Healthcare Providers, Hospitality Sector |
| Companies Covered | Bosch, Honeywell International, ASSA ABLOY, Allegion, Siemens, Johnson Controls, Dormakaba, KEENFINITY, HID Global, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Access Control Market Trends and Innovations
Biometric authentication architectures are displacing credential-based systems across German critical infrastructure, while regulatory frameworks harden technical requirements and procurement patterns favor integrated platform contracts over point-product purchases.
Contactless biometric terminals using palm-vein and facial recognition templates are consolidating market share in healthcare and high-security industrial deployments. German hospital procurement departments specify these systems to eliminate card-loss replacement costs and reduce infection transmission surfaces. The technology is consolidating previously fragmented hardware categories—time-attendance, physical access, and logical network entry—into single-authentication-event architectures.
The EU AI Act, enforced by German national regulators, imposes risk-tier obligations on biometric identification systems deployed in public spaces and critical infrastructure. High-risk classification triggers mandatory conformity assessments, human oversight protocols, and fundamental-rights impact evaluations that reshape vendor development priorities. German federal facility operators are now requiring AI Act compliance documentation alongside traditional BSI Common Criteria certification in tender specifications.
Facility management departments are bundling physical access, energy management, and surveillance contracts into single-vendor platform agreements with decade-long service terms. German commercial real estate investment trusts favor this consolidation to reduce vendor relationship overhead and standardize operational procedures across distributed portfolios. The shift is most visible in Frankfurt's financial district and Hamburg's harbor logistics zones, where integrated building-automation platforms now dominate new construction and major renovation specifications.
Germany Access Control Market Segmentation
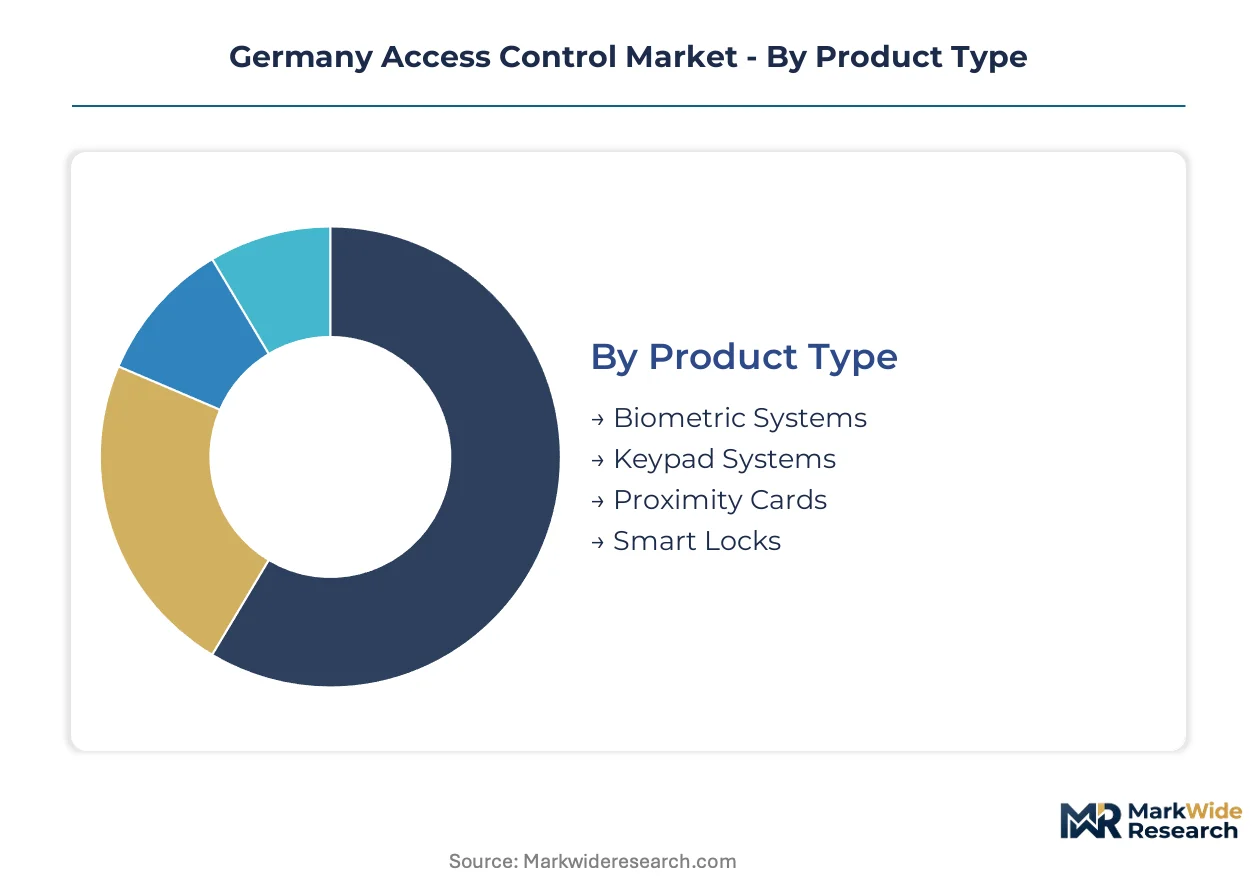
German access control procurement splits sharply between premium biometric installations in critical infrastructure and volume-driven proximity card deployments across commercial real estate. Understanding these segment dynamics reveals where margin pools concentrate versus where scale economics dominate purchasing decisions.
Product Type:
Biometric systems capture premium pricing through liveness-detection capabilities, while proximity cards and keypad systems serve cost-sensitive mass deployment scenarios.
- Biometric Systems:Palm-vein and facial recognition terminals process encrypted templates against federated identity stores within 500 milliseconds. Bavarian automotive manufacturing campuses and Berlin federal facilities specify these for surgical wards and high-security zones to eliminate shared-surface transmission vectors.
- Smart Locks:Battery-powered electromechanical cylinders with Bluetooth Low Energy and NFC interfaces enable smartphone credentialing without wiring infrastructure. Frankfurt commercial real estate investment trusts favor these for retrofitting aging office stock where pulling cable proves cost-prohibitive.
- Proximity Cards:Legacy 125 kHz and 13.56 MHz credential systems dominate existing installed bases across German industrial parks, though procurement is plateauing as mobile access gains traction.
- Keypad Systems:PIN-entry terminals with tamper-resistant enclosures serve secondary perimeter gates and time-attendance tracking in logistics facilities where biometric throughput would create bottlenecks.
Mature deployment sits with proximity cards and keypad systems across legacy industrial estates. Newer deployment is concentrated in biometric systems and smart locks where infection-control mandates and mobile-first workforces reshape specifications.
Application:
Commercial buildings generate recurring service revenue through multi-year platform contracts, while government institutions impose the strictest certification requirements.
- Commercial Buildings:Integrated building-automation platforms bundle physical access, energy management, and surveillance into single-vendor agreements with decade-long terms. Hamburg harbor logistics zones and Frankfurt financial district towers specify these consolidated contracts to reduce vendor relationship overhead.
- Industrial Facilities:Harsh-environment readers with IP67 ratings and anti-vibration mounting protect production floors where electromagnetic interference and particulate contamination threaten standard electronics.
- Government Institutions:BSI Common Criteria certification and EU AI Act conformity documentation are mandatory tender requirements for federal and municipal facility upgrades.
- Residential Properties:Smart intercom and package-delivery access systems serve multi-tenant housing developments, though per-unit economics limit feature depth compared to commercial deployments.
Procurement sophistication peaks in government institutions where dual certification burdens extend sales cycles. Commercial buildings offer the steepest expansion trajectory as facility management consolidation accelerates across German metropolitan cores.
Technology:
Cloud-connected architectures are displacing on-premise server installations as multi-site operators abandon hardware maintenance responsibilities.
- Cloud-Based Solutions:Federated identity management with API-driven integration into HR and visitor-management systems enables centralized policy enforcement across distributed locations. Munich-headquartered manufacturing groups deploy these for unified access governance across Nuremberg satellite plants.
- Mobile Access:Smartphone credentials using Bluetooth Low Energy and NFC protocols displace plastic proximity cards where white-collar workforce smartphone penetration approaches saturation.
- On-Premise Systems:Air-gapped servers with localized biometric template storage persist in defense and critical infrastructure settings where network exposure is unacceptable.
- RFID Technology:Ultra-high frequency and near-field communication readers support legacy credential populations during transition periods toward mobile-first architectures.
Deployment maturity clusters in on-premise and RFID installations across regulated industrial sites. Cloud-based solutions and mobile access are gaining share fastest as IT-security skill shortages make self-managed infrastructure unsustainable.
End User:
Healthcare providers and educational institutions present divergent procurement patterns—one driven by infection-control mandates, the other by budget constraints and scale economics.
- Healthcare Providers:German hospital networks specify contactless biometric terminals to eliminate card-loss replacement costs and reduce pathogen transmission surfaces in surgical wards and intensive care units. BSI technical guidelines and hygiene protocols converge on palm-vein architectures.
- Educational Institutions:University campuses and vocational training centers balance security requirements against tight public-sector budgets, favoring phased proximity card deployments with future mobile-access upgrade paths.
- Retail Businesses:Loss-prevention integration with point-of-sale and inventory-management systems drives access-control purchasing for stockrooms and cash-handling areas.
- Hospitality Sector:Guest-room mobile-key platforms and staff-area biometric time-attendance systems serve hotels and conference centers seeking operational differentiation.
Established purchasing patterns dominate educational institutions where capital replacement cycles stretch across decades. Healthcare providers represent the most dynamic demand segment as regulatory and clinical pressures force accelerated technology refresh schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facility concentration across Germany's special economic zones and high-tech clusters is accelerating access control procurement, with federal infrastructure mandates and state-level digitization programs converging on biometric and cloud-connected architectures.
Bavaria
Automotive manufacturing campuses around Munich and Nuremberg are consolidating multi-site access management through federated identity platforms. The BSI IT Security Act compels Common Criteria certification for energy and transport infrastructure components. Industrial compounds in Ingolstadt and Regensburg specify palm-vein biometric terminals for high-security production zones.
North Rhine-Westphalia
Chemical and steel processing facilities in the Ruhr industrial belt demand explosion-proof readers with IP67 environmental ratings. Germany's Critical Infrastructure Protection Ordinance mandates encrypted credential systems for water and energy utilities. Düsseldorf and Cologne commercial real estate portfolios are migrating from proximity cards to Bluetooth Low Energy mobile credentials.
Baden-Württemberg
Precision engineering and medical device manufacturers in Stuttgart and Karlsruhe require cleanroom-compatible contactless entry systems. The EU AI Act risk-classification framework shapes procurement specifications for biometric identification in pharmaceutical production environments. Heidelberg's university hospital network exemplifies accelerated healthcare biometric adoption.
Berlin-Brandenburg
Federal ministry buildings and municipal facilities drive demand for unified physical-logical access platforms. Germany's Federal Office for Information Security technical guidelines enforce air-gapped biometric template storage in defense-adjacent installations. Potsdam government data centers anchor procurement for converged cyber-physical security systems.
Hamburg
Harbor logistics zones and container terminals specify harsh-environment readers with anti-vibration mounting and electromagnetic interference shielding. The EU Green Deal building renovation targets accelerate smart-lock retrofitting in aging commercial stock. HafenCity development projects bundle decade-long integrated building-automation contracts covering access, energy, and surveillance.
Germany Access Control Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated building-security platforms commanding premium positioning in federal and healthcare verticals while volume-driven proximity card suppliers defend position in legacy industrial estates. The vendor base organizes around three strategic archetypes: industrial automation conglomerates extending into security ecosystems, door-hardware specialists pivoting toward electronic credentials, and pure-play biometric technology developers. Dominant competitive moves include strategic partnerships between hardware fabricators and cloud-identity platforms, plus selective backward integration into secure-element chip sourcing to reduce foundry allocation exposure.
Among Germany-based industrial conglomerates, Siemens and Bosch exemplify the integrated-platform archetype, leveraging building-automation heritage to anchor unified energy-security dashboards. ASSA ABLOY occupies a position bridging mechanical door-hardware specialization with electronic access ecosystem expansion. These three companies represent distinct strategic postures: one emphasizing smart-building convergence, another industrial automation DNA, and the third hardware-to-electronics migration.
| Leading Market Players |
|---|
| Bosch |
| Honeywell International |
| ASSA ABLOY |
| Allegion |
| Siemens |
| Johnson Controls |
| Dormakaba |
| KEENFINITY |
| HID Global |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal building renovation targets gate qualified supply for German access control vendors, restricting premium-tier pricing access to manufacturers whose smart-lock and biometric portfolios carry certified lifecycle assessments and circular-economy compliance documentation.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency procurement premiums from standard contract discounts. Three-tier pricing structure across premium, standard, and economy levels reflects BSI Common Criteria certification grade and bundled after-sales service intensity. Cost compression in economy-tier proximity card systems intensifies because Asian contract manufacturers flood spot markets with legacy 125 kHz credentials. Municipal facility managers exhibit highest price sensitivity, while defense-adjacent federal operators accept substantial premiums for air-gapped biometric architectures.
Supply Chain Analysis
BSI Common Criteria certification gates component sourcing, restricting qualified microcontroller and secure-element suppliers to Taiwanese, South Korean, and German foundries with evaluated assurance facilities. German access control hardware draws from concentrated Asian semiconductor capacity for fingerprint sensors, NFC controllers, and Bluetooth Low Energy chipsets. Single-source vulnerability in palm-vein imaging modules threatens production continuity for healthcare-focused terminal manufacturers. Distribution runs through authorized system integrators and direct OEM relationships with Siemens, Bosch, and ASSA ABLOY anchoring channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure-element chip allocation constraints prop pricing power for certified vendors, as foundry capacity prioritizes automotive and consumer electronics over security-specialized microcontrollers.
For Market Incumbents: Deploy backward integration into secure-element chip sourcing to reduce foundry allocation exposure. Siemens and Bosch should expand captive semiconductor partnerships with evaluated assurance facilities. Certification investment in EU AI Act conformity documentation defends position against emerging biometric pure-plays lacking compliance infrastructure.
For New Entrants and Emerging Players: Mid-sized commercial real estate investment trusts in secondary German cities represent underserved buyer archetype seeking mobile-access retrofit without decade-long platform lock-in. White-space concentrates in Hamburg's aging harbor logistics stock and Cologne's peripheral office parks. Cloud-native identity platforms with API-first architecture enable rapid deployment without legacy protocol middleware.
For Investors and Strategic Acquirers: BSI technical guideline updates incorporating AI Act conformity routes are the leading indicator that procurement specifications will harden certification barriers and consolidate vendor pools. Long-term viability favors platforms with dual cyber-physical security capabilities spanning OT network protocols and IT identity frameworks. Acquisition targets should demonstrate evaluated assurance partnerships and healthcare vertical penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Certification Investment | BSI evaluation procedures extend sales cycles but lock out unqualified competitors from federal procurement. |
| Cloud-Native Platform Migration | Multi-site operators abandon on-premise maintenance, favoring API-driven identity governance across Munich-Nuremberg industrial corridors. |
| Liveness Detection Algorithm Development | Anti-spoofing capabilities command banking and defense premiums where presentation attacks threaten security. |
| Mobile Access Credential Expansion | Bluetooth Low Energy and NFC deployment displaces plastic proximity cards in Frankfurt commercial real estate. |
| Healthcare Vertical Specialization | Palm-vein terminals eliminate infection vectors in Berlin and Heidelberg hospital networks. |
Research Methodology
BSI technical guideline archives, EU AI Act implementation documents, and German federal procurement databases formed the secondary backbone, cross-referenced against primary interviews with hospital biomedical engineers, critical infrastructure security officers, commercial real estate facility managers, and system integration specialists. Bottom-up and top-down triangulation validated segment sizing across biometric systems, smart locks, and cloud-connected platforms.
Bottom-up modeling anchored volume projections to identified procurement pipelines in Bavaria's automotive corridor and Berlin's federal modernization programs. Segmentation dimensions spanned product type, application vertical, deployment architecture, and end-user category. CAGRs were derived from trend extrapolation of contract award velocities and technology refresh cycles, incorporating BSI certification timeline impacts and semiconductor supply constraints.
Revisions become necessary when BSI updates technical guidelines, EU AI Act enforcement patterns shift, or secure-element chip allocation crises disrupt hardware production. A model refresh is warranted upon material change in federal facility renovation appropriations or healthcare network consolidation activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Italy Access Control Market
Access Control Systems
Access Control Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
South Korea Access Control Market
Access Control Systems
Canada Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Car Security System Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
Border Security System Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
North America Access Control Market