
 Parking Access Control Market | 2026-2036
Parking Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Access Control Market Insights
Cloud-native platform architecture is reconfiguring how parking operators deploy access control across distributed real estate portfolios. SKIDATA leverages its ski-resort heritage to sustain expertise in high-throughput credential validation for peak-load environments. Amano Corp. anchors its position through dense channel relationships with Japanese municipal operators. Westfalia Technologies differentiates by extending automated storage retrieval competencies into robotic parking structures.
Parking access control encompasses electromechanical barriers, credential readers, and software platforms that authenticate vehicles or pedestrians before granting entry to restricted parking facilities, typically operating with sub-five-second transaction thresholds to prevent throughput bottlenecks. The system's primary commercial purpose is revenue protection, occupancy optimization, and liability reduction for asset owners. License plate recognition technology leads deployment in airport and commercial segments where frictionless experience commands premium pricing, while mobile app integration represents the fastest-growing category as property managers seek to eliminate physical credential costs. RFID maintains structural importance in government and educational settings where closed-loop security protocols override convenience priorities.
FCC certification requirements govern wireless credential transmission in United States deployments, while CE marking under the EU Machinery Directive shapes barrier safety specifications for European installations. China's GB standards and MIIT network security regulations constrain how foreign platform providers architect cloud connectivity for domestic smart parking projects. Stakeholders must weigh the capital efficiency of retrofitting legacy hardware against the operational flexibility of greenfield cloud-native installations as procurement criteria shift from equipment durability to software extensibility.
Market Dynamics
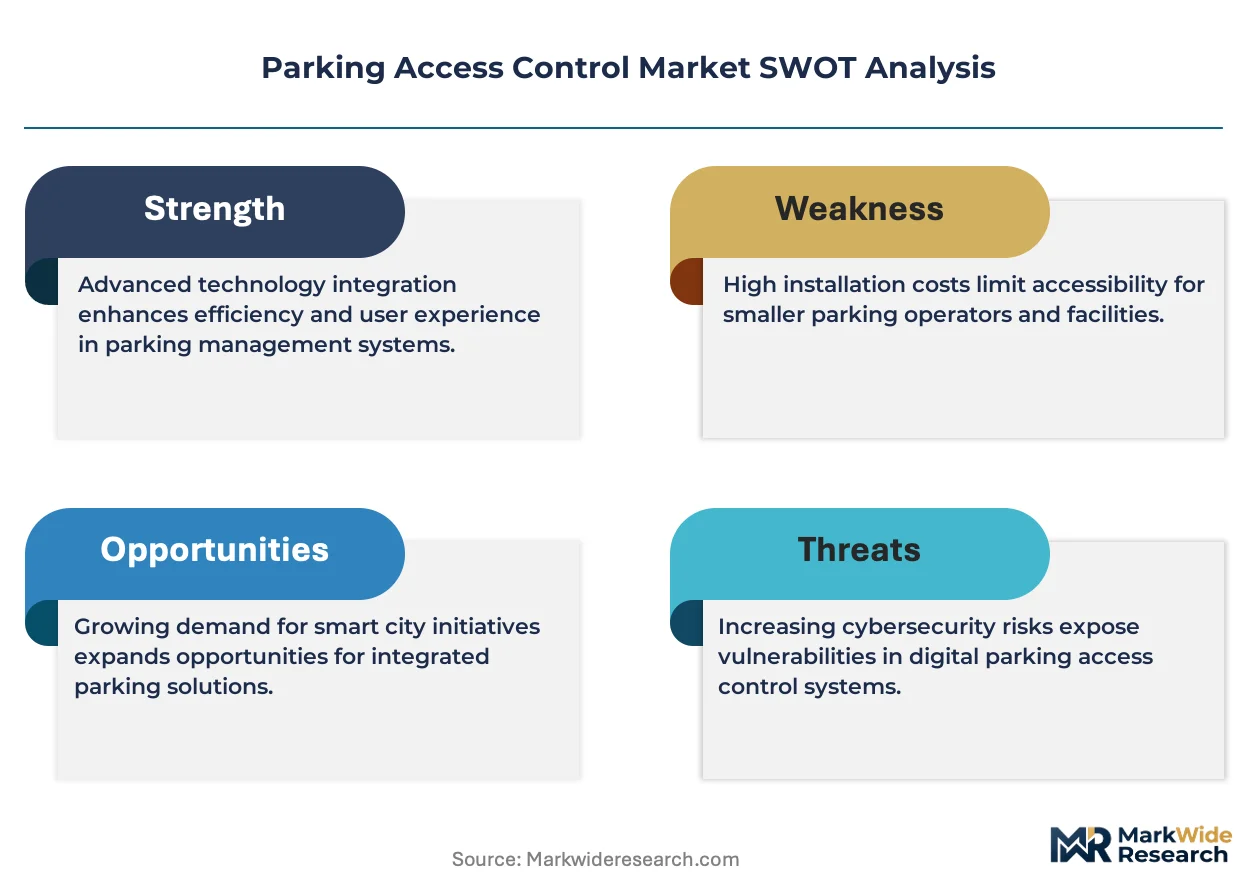
Cloud-native credentialing platforms are compressing deployment timelines from months to weeks, forcing incumbent hardware vendors to restructure pricing models around software-as-a-service recurring revenue rather than perpetual license sales.
Growth Catalysts
- License plate recognition systems:Airports and commercial real estate operators in the United States deploy camera-based authentication to eliminate physical credential distribution costs and reduce entry friction during peak traffic periods.
- FCC Part 15 regulations:Wireless credential transmission standards enable interoperable mobile access platforms across multi-tenant properties without proprietary hardware lock-in.
- Smart city infrastructure mandates:Municipal parking operators in Germany integrate access control with urban mobility platforms as federal funding prioritizes digitized traffic management systems.
Market Restraints
- Semiconductor supply concentration:Barrier controller chipsets depend on fabrication capacity concentrated in Taiwan, creating lead time volatility for electromechanical entry systems.
- CE marking compliance costs:The EU Machinery Directive imposes extensive safety testing requirements on automated barrier installations, elevating certification expenses for European deployments.
- Legacy ticket system installed base:Existing magnetic stripe infrastructure in aging municipal garages creates switching cost resistance despite superior mobile credential alternatives.
Strategic Opportunities
- Robotic parking structures:Automated storage retrieval convergence with vehicle access control creates demand for synchronized credential validation in vertical parking towers.
- China GB standard alignment:Domestic MIIT network security regulations favor locally architected cloud platforms, opening procurement channels for compliant foreign joint ventures.
- Subscription-based service models:Property management software vendors embed parking access modules into building automation suites, creating indirect distribution channels.
Industry Challenges
- Cybersecurity certification timelines:NIST framework alignment for connected parking systems extends product launch schedules as penetration testing requirements expand.
- Legacy system integration complexity:Hybrid deployments combining RFID readers with mobile credential platforms demand specialized protocol translation engineering.
- Electromechanical maintenance skill gaps:Barrier mechanism repair expertise concentrates with aging technician cohorts as vocational training programs emphasize software over hardware competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Access Control Market |
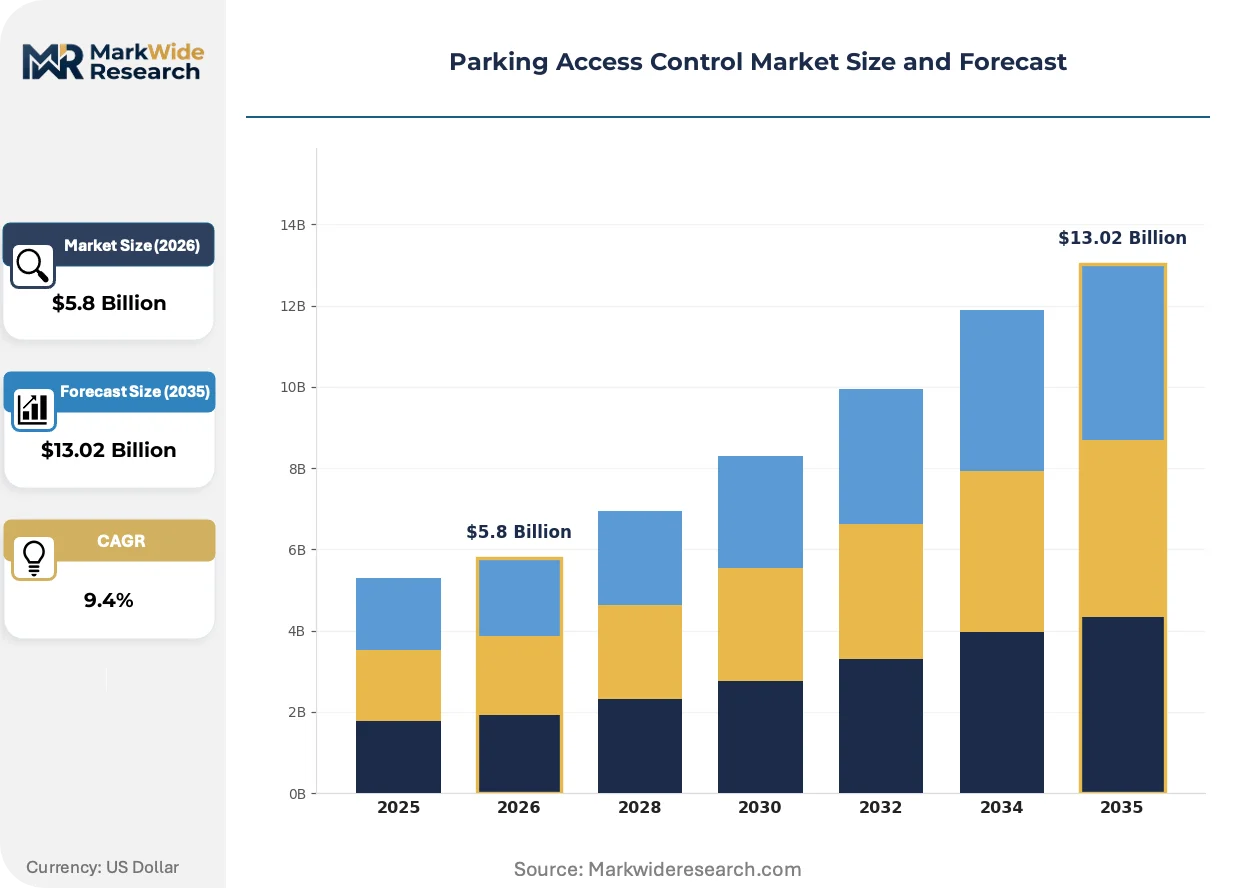
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, License Plate Recognition, Mobile App Integration, Biometric Access Application: Commercial Parking, Residential Parking, Airport Parking, Event Spaces End User: Property Management, Airports, Government Facilities, Educational Institutions Service Type: Installation, Maintenance, Consulting, Software Solutions |
| Companies Covered | SKIDATA, Amano Corp., Westfalia Technologies, TIBA Parking Systems, Group Indigo, Wohr Parking Systems, Robotic Parking Systems, KLAUS Multiparking, ASPS Access Security and Parking Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Access Control Market Trends and Innovations
Edge computing architectures are redistributing credential validation from centralized servers to local gate controllers, eliminating latency vulnerabilities during network outages while enabling real-time occupancy analytics.
Computer vision-based vehicle detection is virtualizing the physical loop sensor infrastructure that has dominated parking entry design for decades. Commercial real estate operators in the United States retrofit camera arrays to capture license plate, vehicle class, and occupancy data through unified optical systems. This consolidation is virtualizing separate hardware categories into single-device deployments, compressing capital expenditure and maintenance overhead.
The EU AI Act establishes risk classification frameworks for automated decision systems in physical access control, requiring transparency documentation for license plate recognition algorithms used in public parking facilities. Equipment vendors must now maintain algorithmic audit trails and human oversight protocols for high-traffic installations. German municipal operators have accelerated procurement of compliant platforms ahead of enforcement timelines, creating competitive differentiation for certified suppliers.
Building automation procurement increasingly bundles parking access with energy management and tenant experience platforms, unseating standalone system specifications. Facility managers in commercial office towers negotiate enterprise-wide software licenses that subsume parking credentialing into broader real estate technology stacks. This consolidation is most pronounced in the United States, where property technology budgets centralize under chief information officers rather than distributed facility directors.
Parking Access Control Market Segmentation
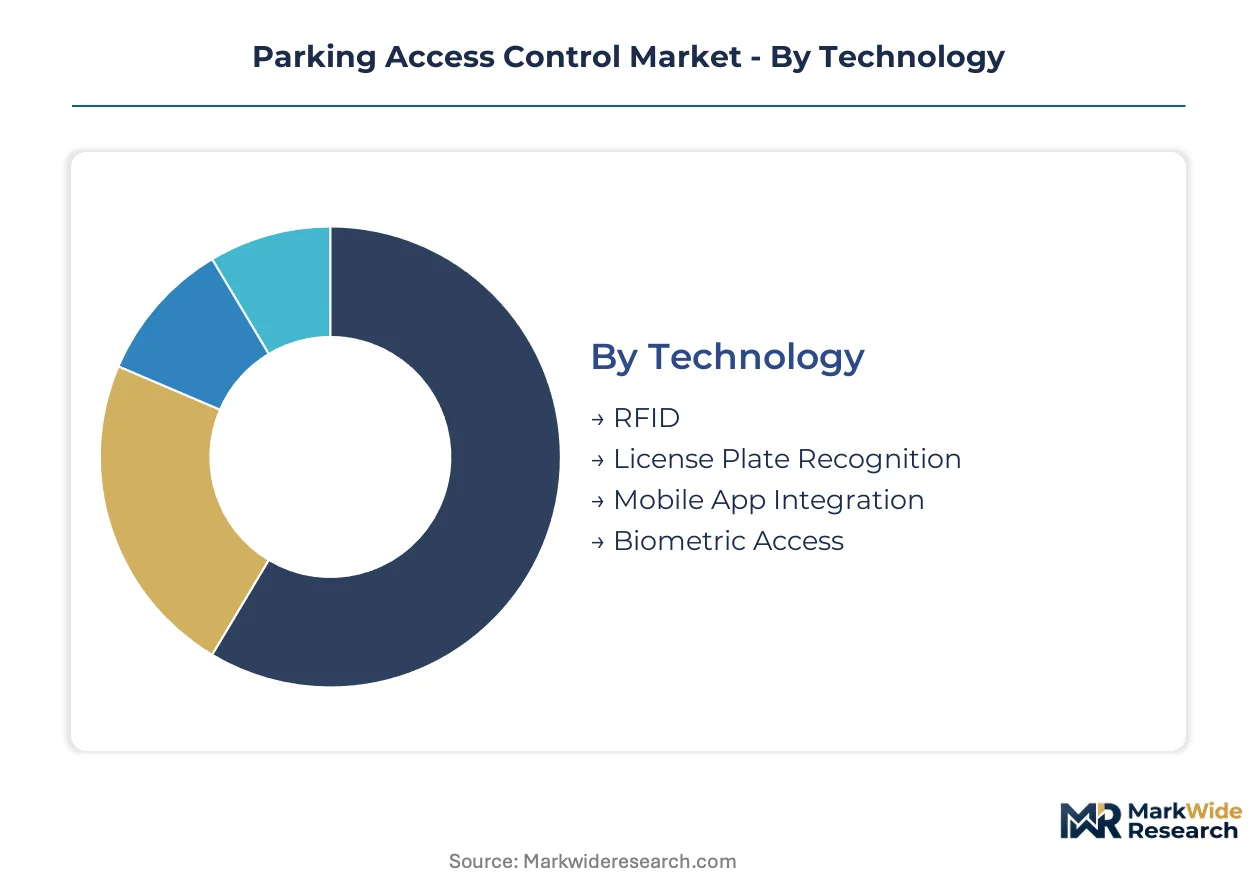
Segmentation reveals how parking access control procurement diverges across technology readiness, facility type, and buyer sophistication. Technology choices determine hardware-software bundling strategies, while application context dictates throughput requirements and integration complexity.
Technology:
After-sales service intensity varies sharply across credential technologies, with camera-based systems demanding continuous algorithm calibration while RFID infrastructure requires periodic reader recertification.
- RFID:Proximity and long-range radio frequency identification readers authenticate vehicles through windshield-mounted tags or card-based credentials. Educational institutions in the United States specify RFID for closed-loop campus environments where credential revocation protocols override convenience considerations.
- License Plate Recognition:Optical character recognition cameras capture and validate vehicle registration numbers without physical credential distribution. Airports in Germany deploy these systems to eliminate ticket handling labor and accelerate peak-hour throughput during flight bank operations.
- Mobile App Integration:Smartphone-based credentialing transmits encrypted tokens via Bluetooth or cellular connectivity. This segment expands most quickly as property managers eliminate plastic card inventory costs and enable remote credential provisioning.
- Biometric Access:Fingerprint and facial recognition systems authenticate drivers through unique biological identifiers. High-security government facilities specify these for facilities requiring multi-factor validation beyond vehicle-mounted credentials.
By volume, RFID leads due to legacy infrastructure persistence. By growth pace, mobile app integration is ahead.
Application:
Pricing stratifies across facility types based on peak-load variability and revenue per parking space, with commercial towers commanding premium integration while residential complexes prioritize capital efficiency.
- Commercial Parking:Multi-tenant office towers and retail complexes demand frictionless entry systems with tenant-branded mobile applications. United States commercial real estate operators specify sub-three-second transaction thresholds to prevent lobby congestion during morning arrival peaks.
- Airport Parking:High-volume facilities require redundant credential validation and revenue-grade audit trails for transient and long-term inventory management. German airport operators integrate access control with flight information systems to enable dynamic pricing based on terminal proximity and occupancy.
- Residential Parking:Condominium and apartment complexes prioritize low-maintenance electromechanical barriers with resident self-service credential management. These installations emphasize equipment durability over software extensibility given constrained capital improvement budgets.
- Event Spaces:Stadiums and convention centers require rapid deployment capabilities for temporary surge capacity during scheduled events. Operators favor modular barrier systems that reconfigure entry lanes based on anticipated attendance patterns.
Commercial parking generates highest absolute revenue. Airport parking shows steepest expansion trajectory as aviation recovery drives infrastructure investment.
End User:
Buyer sophistication determines procurement channel preferences, with centralized property technology budgets favoring platform vendors while decentralized facility managers rely on specialized systems integrators.
- Property Management:Real estate investment trusts and facility management conglomerates negotiate enterprise software licenses spanning distributed portfolios. These buyers prioritize API extensibility for integration with building automation and tenant experience platforms.
- Airports:Aviation authorities and concession operators mandate redundant systems with 99.9% uptime guarantees and real-time occupancy visibility. Procurement emphasizes interoperability with existing revenue management and flight information infrastructure.
- Government Facilities:Municipal parking authorities and federal installations specify closed-loop security protocols with audit-compliant credential revocation capabilities. FCC Part 15 certification governs wireless deployments in United States federal properties.
- Educational Institutions:Universities and school districts balance security requirements against limited operational technology budgets. These buyers favor RFID-based systems with multi-year equipment warranties and minimal software subscription obligations.
Property management commands largest contract values. Government facilities represent the most price-sensitive procurement segment.
Service Type:
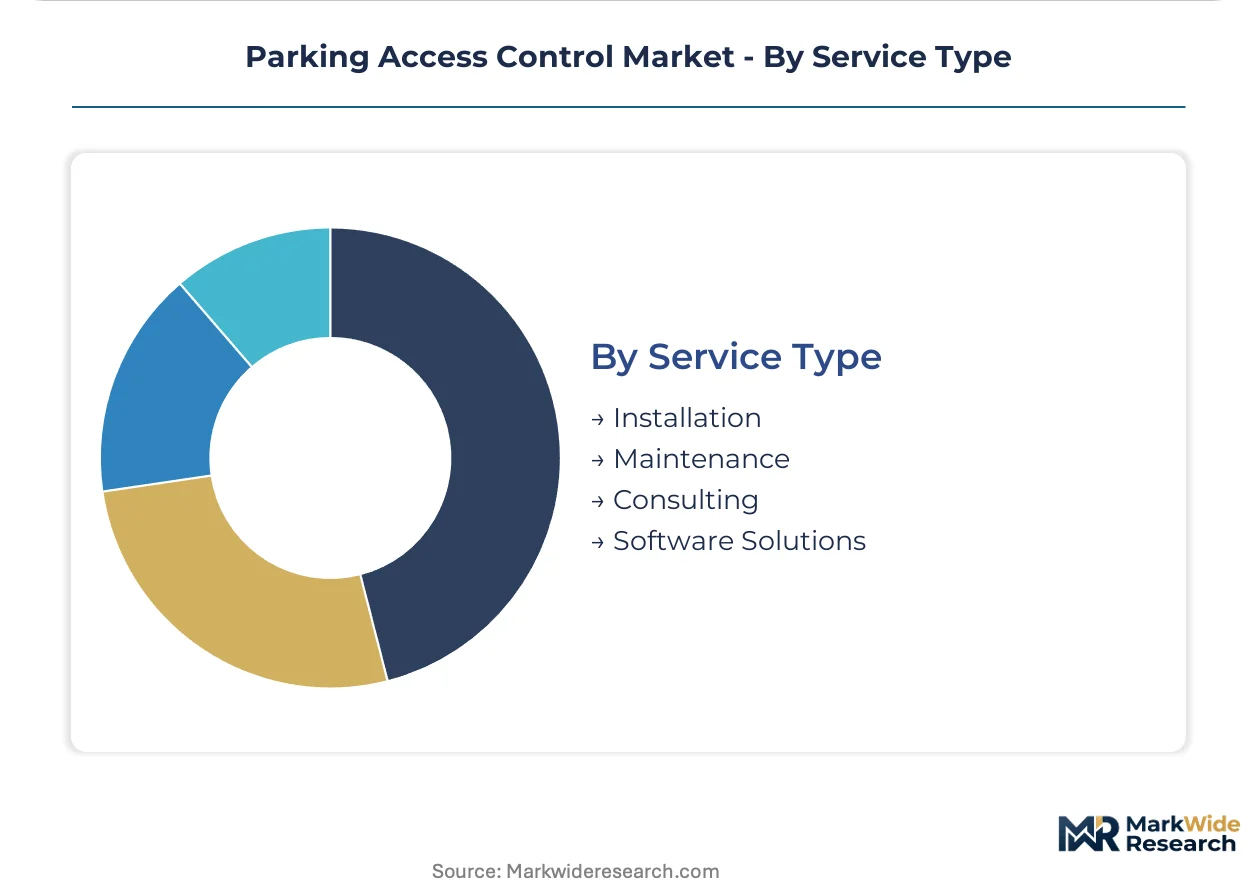
Margin structure inverts across the service lifecycle, with installation commanding upfront premiums while recurring maintenance generates predictable annuity streams.
- Installation:Electromechanical barrier deployment, conduit routing, and software commissioning for new construction or retrofit projects. German installations require CE marking compliance documentation and third-party safety validation extending project timelines.
- Software Solutions:Cloud-native credential management platforms with subscription-based access control administration. These offerings are gaining share fastest as property managers shift capital expenditure to operational expenditure models.
- Maintenance:Preventive service contracts covering barrier mechanism lubrication, sensor calibration, and firmware updates. Aging technician cohorts in the United States create supply constraints for electromechanical repair expertise.
- Consulting:System design, traffic flow optimization, and regulatory compliance advisory for complex multi-vendor deployments. Demand concentrates in airport and large commercial projects requiring specialized integration engineering.
Installation leads by current revenue contribution. Software solutions demonstrate strongest margin expansion as recurring revenue scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German parking access control manufacturers export integrated barrier and credentialing systems to airport operators across the United States and commercial real estate developers in China. Trade flows concentrate through specialized systems integrators rather than direct equipment sales.
United States
Commercial real estate investment trusts in Manhattan and Chicago mandate frictionless mobile credentialing for multi-tenant office towers. FCC Part 15 regulations govern wireless transmission standards for Bluetooth and cellular-based access platforms. Silicon Valley property technology budgets centralize parking access procurement under chief information officers rather than facility managers.
Germany
Municipal parking authorities in Munich and Frankfurt integrate access control with urban mobility platforms as federal funding prioritizes digitized traffic management. CE marking under the EU Machinery Directive imposes extensive safety testing requirements on automated barrier installations. The EU AI Act establishes risk classification frameworks for license plate recognition algorithms in public facilities.
China
Smart city investments in Beijing and Shenzhen accelerate procurement of cloud-native parking platforms for municipal garage networks. MIIT network security regulations and GB standards constrain how foreign platform providers architect cloud connectivity for domestic projects. Local joint ventures with compliant architecture gain preferential access to provincial procurement channels.
Japan
Dense urban parking in Tokyo and Osaka drives demand for automated mechanical parking structures with synchronized credential validation. METI industrial standards shape electromechanical safety specifications for vertical parking towers. Amano Corp. maintains channel relationships with municipal operators that create barriers for foreign equipment vendors.
United Kingdom
London commercial developers specify sub-three-second transaction thresholds to prevent lobby congestion during morning arrival peaks. GDPR compliance requirements govern biometric data collection for facial recognition access systems in public parking facilities. The Midlands manufacturing corridor hosts barrier mechanism fabrication for European export markets.
Parking Access Control Market Competitive Landscape
On the supply side, the industry is consolidating around platform vendors with cloud-native software capabilities while electromechanical hardware specialists face margin compression. Three strategic archetypes dominate: integrated parking technology conglomerates with software-hardware bundling, regional electromechanical barrier fabricators with dense service networks, and robotic parking structure specialists extending automated storage retrieval competencies. Competitive moves concentrate on strategic partnerships with property management software vendors and geographic expansion through certified systems integrator channels.
Within the integrated technology tier, SKIDATA leverages its Austrian heritage in high-throughput credential validation for peak-load environments. Amano Corp. anchors the Asia-Pacific regional fabricator position through municipal operator relationships. Westfalia Technologies exemplifies the robotic parking convergence archetype, extending automated storage retrieval competencies into vertical parking structures.
| Leading Market Players |
|---|
| SKIDATA |
| Amano Corp. |
| Westfalia Technologies |
| TIBA Parking Systems |
| Group Indigo |
| Wohr Parking Systems |
| Robotic Parking Systems |
| KLAUS Multiparking |
| ASPS Access Security and Parking Systems |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors linking Taiwanese semiconductor foundries to US barrier controller manufacturers transmit cost volatility directly into hardware pricing tiers, compressing margins for electromechanical vendors while amplifying differentiation premiums for cloud-native platform providers.
Pricing Analysis
Current-generation license plate recognition systems command substantial premiums over legacy RFID infrastructure and emerging mobile credentialing platforms. Three-tier pricing structure across premium, standard, and economy levels separates airport-grade optical systems with AI-powered analytics from municipal garage deployments and basic residential barrier installations. Pricing pressure stems from SaaS subscription models displacing perpetual license revenue as property managers shift capital expenditure to operational expenditure frameworks. Government facilities represent the most price-sensitive procurement segment, while commercial real estate investment trusts prioritize software extensibility over unit cost minimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for parking access control manufacturers sourcing electromechanical components. Barrier controller chipsets concentrate fabrication in Taiwan, South Korea, and mainland China, while precision optical sensors for license plate recognition draw from Japanese and German component suppliers. Single-source vulnerability in automotive-grade semiconductor supply creates lead time volatility for barrier mechanism controllers. Distribution runs through certified systems integrator networks rather than direct equipment sales, with regional service density determining competitive positioning in municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent parking access control vendors face sustained substitution pressure from building automation platforms embedding credential management into broader real estate technology stacks, requiring defensive repositioning around data sovereignty and edge computing architectures.
For Market Incumbents: Insulate core revenue streams by deepening software-hardware bundling through acquisition of cloud-native credentialing specialists, while accelerating CE marking and FCC Part 15 certification investments to create regulatory moats against unlicensed platform competitors. Channel control represents the critical defensive lever, as property management software vendors increasingly intermediate procurement decisions.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where legacy ticket system infrastructure creates switching cost resistance against established Western vendors but mobile-first deployment capabilities enable leapfrog positioning. Robotic parking structure integration engineering offers a specialized go-to-market angle with limited incumbent expertise concentration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform vendors with recurring revenue scaling potential over electromechanical hardware specialists facing margin compression. Long-term viability across the analysis window hinges on API extensibility and building automation ecosystem integration depth. The signal to watch is consolidation velocity among property management software vendors seeking embedded parking modules.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Recurring revenue scaling transforms hardware vendors into software enterprises with superior margin profiles. |
| Edge Computing Architecture Deployment | Local credential validation eliminates latency vulnerabilities during network outages for mission-critical installations. |
| Regulatory Certification Acceleration | EU AI Act compliance for license plate recognition algorithms creates procurement preference in German municipal channels. |
| Robotic Parking Integration Engineering | Automated storage retrieval convergence opens vertical parking tower opportunities beyond traditional barrier markets. |
| Property Technology Partnership Development | Building automation ecosystem integration embeds parking access into enterprise-wide real estate software procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with parking facility directors, property technology procurement officers, municipal transportation authority managers, and systems integration engineers; and secondary validation through FCC equipment authorization databases, CE marking registries, municipal procurement records, and commercial real estate technology budget disclosures. Bottom-up and top-down triangulation reconciled vendor shipment data with facility-level installation tracking.
Forecast inputs encompassed technology adoption curves across RFID, license plate recognition, and mobile credentialing platforms; facility type segmentation spanning commercial, airport, residential, and event space applications; and regional regulatory framework divergence affecting procurement timelines. CAGRs were derived from installed base growth modeling and replacement cycle analysis, with cloud-native deployment velocity and smart city infrastructure investment intensity serving as primary demand drivers.
Practitioners should monitor semiconductor supply availability, CE marking enforcement timelines, and property management software vendor consolidation for early signals of forecast revision. Material shifts in MIIT network security regulations or FCC Part 15 wireless transmission standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
China Access Control Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
RFID Locks Market