
 Smart Locker Locks Market | 2026-2036
Smart Locker Locks Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Locker Locks Market Insights
Embedded firmware engineering talent scarcity is redrawing competitive boundaries in smart locker lock manufacturing. ASSA ABLOY AB leverages its vertical integration across electromechanical components to sustain pricing power in premium installations. dormakaba Group anchors its position through specialized channel control in European commercial real estate. Samsung Electronics Co., Ltd. competes by extending semiconductor and IoT module capabilities into integrated lock platforms.
Smart locker locks are electromechanical access devices that authenticate users through credential verification—RFID, biometric, or keypad input—and communicate lock state via wireless protocols to centralized management systems, typically operating on low-voltage DC power with IP54 or higher ingress protection for public environments. Electronic locks currently occupy the largest product segment due to established cost structures and retrofit compatibility, while biometric locks are registering the fastest expansion as fingerprint and facial recognition modules decline in unit cost. Parcel delivery applications dominate volume demand driven by e-commerce locker networks, though hotels represent a concentrated margin pool where guest experience integration commands premium pricing.
FCC certification governs wireless transmission modules in the US market, while CE marking under the EU Radio Equipment Directive shapes product access across European member states. China's MIIT enforces GB standards for encryption modules in networked locks, creating compliance thresholds for cloud-connected platforms. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting connectivity architectures and credential technologies for multi-region deployments.
Market Dynamics
Parcel locker networks in urban logistics are consolidating purchasing power around cloud-connected access platforms, compressing supplier margins while elevating firmware security requirements.
Growth Catalysts
- Last-mile delivery infrastructure:E-commerce locker deployments in Shenzhen and Shanghai are scaling connected lock orders. Municipal smart city budgets in China prioritize parcel hub automation.
- CE marking under EU Radio Equipment Directive:Harmonized wireless certification reduces SKU fragmentation for European commercial real estate operators. Multi-country rollouts accelerate.
- Biometric module cost curves:Fingerprint sensor prices fell below electromechanical alternatives in high-volume contracts. Parcel networks in South Korea are piloting facial recognition integration.
Market Restraints
- Semiconductor supply concentration:MCU and wireless chipset fabrication concentrates in Taiwan and South Korea. Lock OEMs face allocation risk during capacity crunches.
- Lithium battery cost volatility:Cell price swings affect total cost of ownership for battery-powered outdoor installations. Solar-hybrid designs add engineering complexity.
- Substitution by smartphone-based access:Bluetooth credentialing via resident apps bypasses dedicated lock hardware in some hotel and office deployments.
Strategic Opportunities
- India's logistics modernization:National highway corridor development and e-commerce penetration create greenfield locker network potential. BIS certification pathways are stabilizing.
- Healthcare specimen chain custody:Temperature-controlled medical lockers with audit trails represent an emerging application. FDA 21 CFR Part 11 compliance requirements favor specialized vendors.
- ISO/IEC 27001 convergence:Cybersecurity management certification is becoming a procurement filter. Early alignment opens enterprise and government segments.
Industry Challenges
- Firmware engineering scarcity:Embedded security and low-power wireless protocol expertise commands premium compensation. Talent competition extends to automotive and medical device sectors.
- Multi-certification timelines:FCC, CE, and MIIT GB standard testing for a single SKU extends 14-18 months. Parallel filing strategies strain smaller engineering teams.
- Legacy system integration:Building management system protocols vary across installed bases. API standardization remains incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Locker Locks Market |
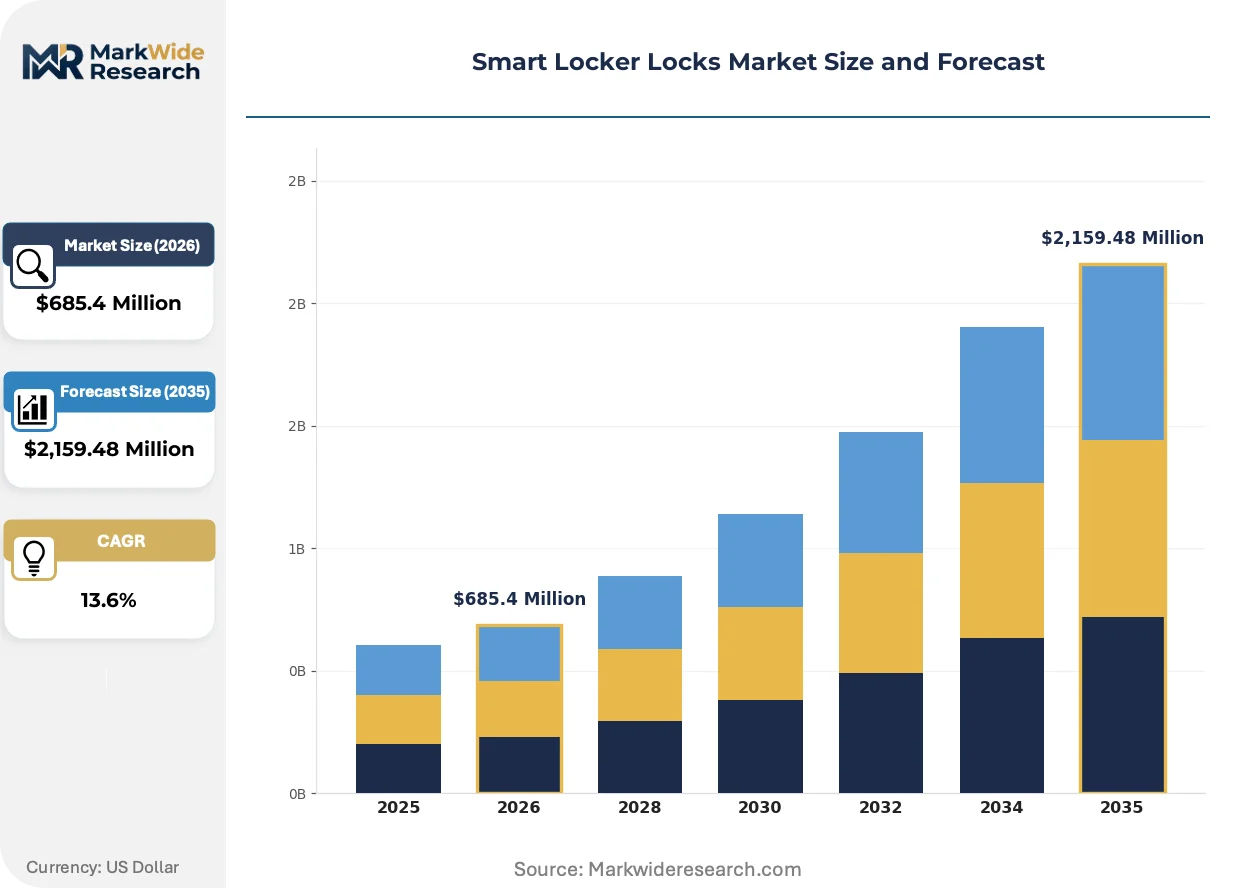
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,159.48 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Locks, Biometric Locks, Keypad Locks, RFID Locks Application: Parcel Delivery, Gym Facilities, Libraries, Hotels Technology: Wireless Connectivity, Facial Recognition, Mobile App Integration, Cloud-Based Management End User: Educational Institutions, Corporations, Residential Buildings, Transportation Hubs |
| Companies Covered | ASSA ABLOY AB, Allegion plc, dormakaba Group, Samsung Electronics Co., Ltd., August Home, Yale, Kwikset, Schlage, Onity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Locker Locks Market Trends and Innovations
Wireless credentialing architectures are diverging across regional standards, forcing suppliers to maintain parallel development tracks while cloud platforms consolidate backend management.
Ultra-wideband (UWB) positioning modules are fragmenting proximity-based access control. Logistics operators in Germany and Japan are deploying UWB-enabled locks for sub-meter location verification. The technology compresses Bluetooth-only solutions into commodity segments while opening premium positioning for spatial-aware security.
China's MIIT GB standards for encryption modules in networked locks are tightening data sovereignty requirements. Domestic cloud providers gain preferred vendor status. Foreign OEMs face mandatory joint venture structures or licensing fees for state-approved cryptographic implementations.
Facility managers are unbundling hardware procurement from software subscriptions. Lock vendors in North American commercial real estate face margin pressure as SaaS platforms capture recurring revenue. The shift concentrates buyer power among multi-property portfolio operators negotiating enterprise terms.
Smart Locker Locks Market Segmentation
Segmentation in smart locker locks reveals how credential technologies, deployment environments, and backend architectures create divergent margin structures. Suppliers must align R&D roadmaps with the specific compliance burdens and connectivity standards governing each slice.
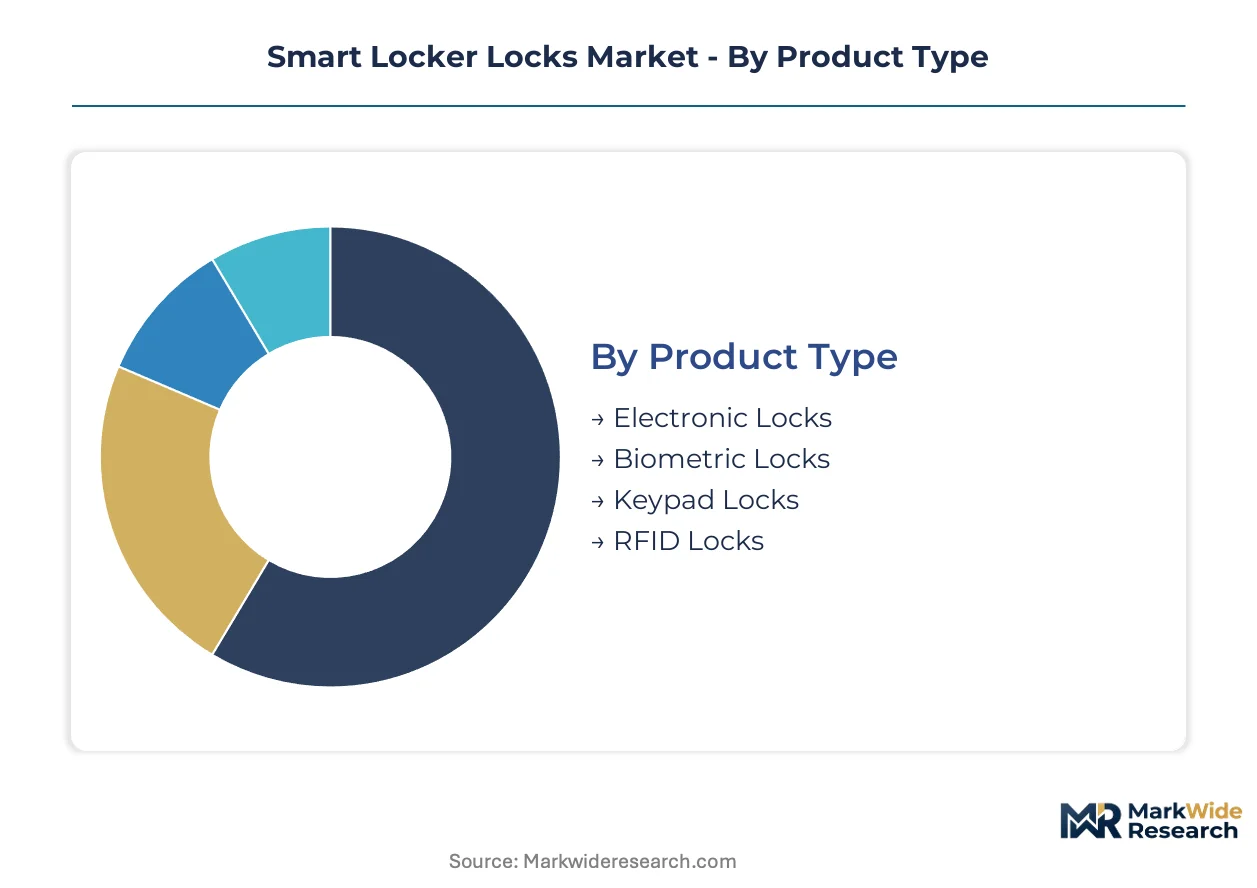
Product Type:
Margin pools concentrate in biometric modules where fingerprint and facial recognition sensors command premium positioning against commoditized electromechanical alternatives.
- Electronic Locks:Solenoid or motor-driven bolt mechanisms controlled by credential readers. Parcel delivery networks in Shenzhen and Shanghai source these at scale for outdoor locker installations where IP65 ingress protection and wide temperature tolerance prove essential.
- Biometric Locks:Fingerprint or facial recognition sensors authenticate users without physical credentials. South Korean logistics operators are piloting facial recognition integration as sensor module costs fall below electromechanical alternatives in high-volume contracts.
- Keypad Locks:PIN entry systems with membrane or capacitive touch interfaces. Budget hotel chains in India deploy these for guest locker access where smartphone penetration remains uneven.
- RFID Locks:Proximity or contactless card readers operating at 13.56 MHz or 125 kHz. European commercial real estate operators favor these for employee locker banks under unified access control systems.
Electronic locks hold installed capacity. Biometric locks are rotating up the share rankings.
Application:
Volume distribution tracks urban logistics infrastructure buildout, while margin extraction depends on guest experience integration and regulatory audit requirements.
- Parcel Delivery:Locker networks for e-commerce last-mile fulfillment. China's municipal smart city budgets prioritize parcel hub automation, with connected lock orders scaling across Shenzhen, Shanghai, and Hangzhou deployments.
- Hotels:Guest room safes and luggage storage with property management system integration. This segment captures concentrated margin pools where seamless mobile credentialing commands premium pricing from luxury chains.
- Gym Facilities:Member locker access with membership system synchronization. Budget operators in Germany favor keypad solutions while premium clubs in Japan deploy biometric readers.
- Libraries:Public locker systems for patron belongings. Municipal procurement in France and Italy drives demand for durable, low-maintenance electronic locks with centralized monitoring.
Parcel delivery dominates unit shipments. Hotels extract the highest margin per installation.
Technology:
Architecture choices determine compliance burden and recurring revenue potential, with cloud backends capturing subscription value that hardware margins cannot match.
- Wireless Connectivity:Bluetooth, Wi-Fi, or cellular modules enabling remote lock state monitoring. FCC certification governs these modules in the US market, while CE marking under the EU Radio Equipment Directive shapes European product access.
- Cloud-Based Management:Centralized platforms for credential provisioning, audit logging, and firmware updates. North American commercial real estate operators increasingly unbundle hardware procurement from SaaS subscriptions, compressing lock vendor margins.
- Mobile App Integration:Smartphone credentialing via proprietary or platform-agnostic applications. Some hotel deployments bypass dedicated lock hardware entirely through Bluetooth credentialing, threatening substitution.
- Facial Recognition:3D structured light or time-of-flight sensors for contactless authentication. China's MIIT enforces GB standards for encryption modules in networked locks, creating compliance thresholds for biometric data handling.
Wireless connectivity anchors current deployments. Cloud-based management is climbing the fastest as recurring revenue models take hold.
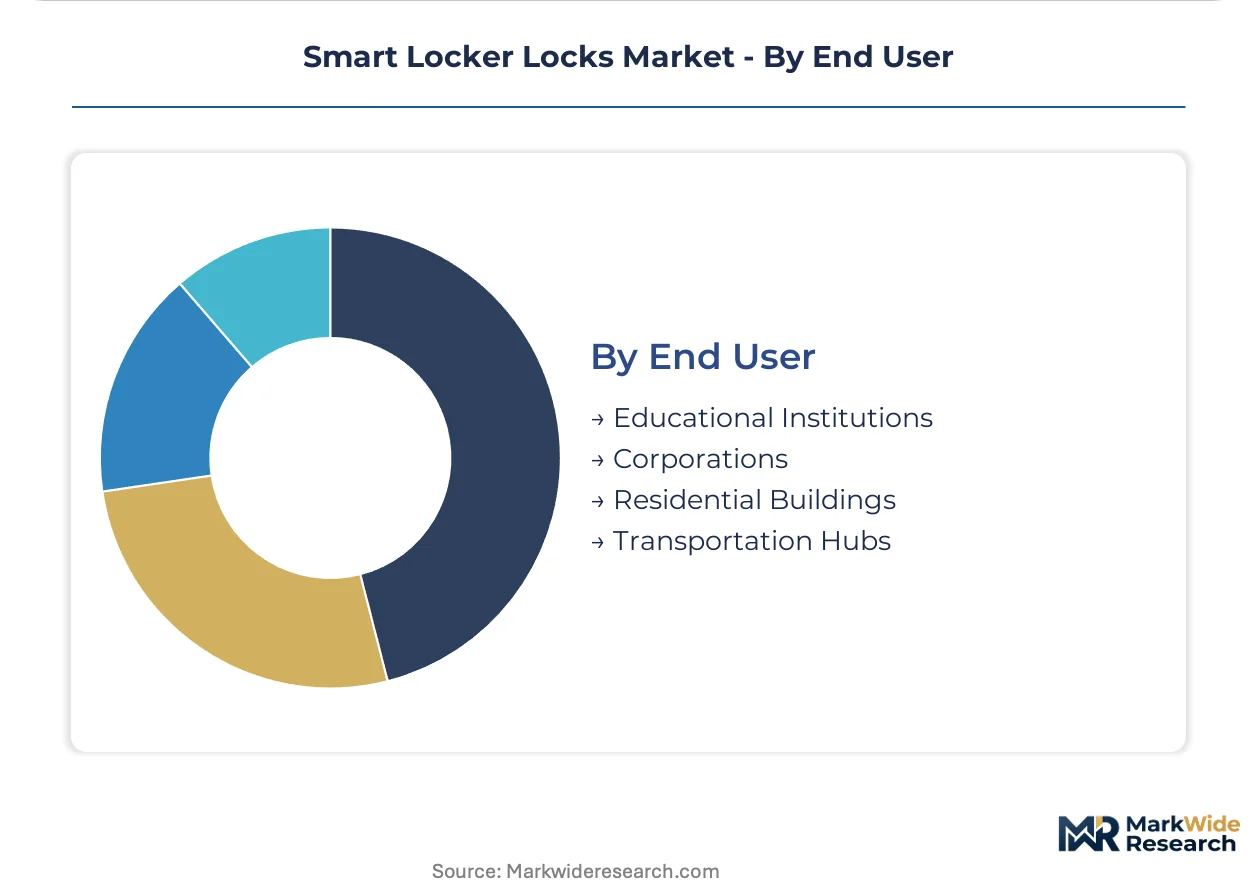
End User:
Procurement sophistication varies sharply across institutional buyers, with enterprise and government segments imposing cybersecurity certification requirements that filter vendor pools.
- Transportation Hubs:Airports, rail stations, and bus terminals with high-throughput, transient user populations. ISO/IEC 27001 certification is becoming a procurement filter for these security-sensitive installations.
- Corporations:Workplace locker systems integrated with human resource and access control platforms. Multi-property portfolio operators in North America negotiate enterprise terms that concentrate buyer power.
- Educational Institutions:Campus locker deployments for students and faculty. Budget constraints in public systems favor electronic locks over biometric alternatives.
- Residential Buildings:Apartment and condominium package lockers. India's logistics modernization creates greenfield potential as national highway corridor development accelerates e-commerce penetration.
Corporations drive standardization. Transportation hubs are gaining share fastest through security-hardened procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for encryption modules anchor China's regulatory framework for networked locks, creating compliance thresholds that reshape vendor access across Asia-Pacific smart city deployments.
China
Shenzhen and Shanghai municipal budgets prioritize parcel hub automation, scaling connected lock orders for last-mile delivery infrastructure. MIIT enforces GB standards for encryption modules in networked locks, tightening data sovereignty requirements. Domestic cloud providers gain preferred vendor status in Hangzhou deployments while foreign OEMs face mandatory joint venture structures.
United States
E-commerce locker networks in urban logistics consolidate purchasing power around cloud-connected access platforms. FCC certification governs wireless transmission modules, extending testing timelines for multi-protocol SKUs. Dallas-Fort Worth corridor logistics operators pilot UWB-enabled locks for sub-meter location verification in high-throughput terminals.
Germany
Commercial real estate operators favor RFID locks for employee locker banks under unified access control systems. CE marking under the EU Radio Equipment Directive reduces SKU fragmentation for multi-country rollouts. Bavaria-based logistics operators deploy UWB-enabled locks for spatial-aware security in premium positioning segments.
India
National highway corridor development and e-commerce penetration create greenfield locker network potential across logistics modernization programs. BIS certification pathways are stabilizing for electromechanical access devices. Maharashtra logistics hubs in Mumbai-Pune corridor attract pilot deployments of keypad-based systems for uneven smartphone penetration environments.
South Korea
Parcel networks pilot facial recognition integration as biometric sensor module costs fall below electromechanical alternatives in high-volume contracts. MFDS-equivalent standards shape medical device adjacent applications. Seoul metropolitan logistics operators test temperature-controlled medical lockers with audit trails for healthcare specimen chain custody.
Smart Locker Locks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration across electromechanical components sustaining pricing power in premium installations. The specialist tier concentrates on firmware security and low-power wireless protocol expertise, competing for talent against automotive and medical device sectors. Three archetypes dominate: diversified industrial conglomerates with semiconductor capabilities, electromechanical specialists with channel control in commercial real estate, and cloud-native entrants capturing SaaS subscription revenue. Consolidation pressures favor M&A activity around firmware engineering teams and parallel filing strategies for multi-certification timelines.
Among diversified industrial conglomerates, ASSA ABLOY AB and Samsung Electronics Co., Ltd. exemplify contrasting integration strategies. ASSA ABLOY AB represents the electromechanical specialist archetype with European commercial real estate channel control. Samsung Electronics Co., Ltd. occupies a position leveraging semiconductor and IoT module capabilities into integrated lock platforms. Dormakaba Group sits within the mid-tier specialist segment, anchoring geographic positioning through regional certification expertise rather than scale-driven cost structures.
| Leading Market Players |
|---|
| ASSA ABLOY AB |
| Allegion plc |
| dormakaba Group |
| Samsung Electronics Co., Ltd. |
| August Home |
| Yale |
| Kwikset |
| Schlage |
| Onity |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan-based MCU foundries lock in semiconductor supply access while capping unit cost escalation for tier-one lock OEMs. These arrangements tether pricing visibility to wafer allocation security across FCC, CE, and MIIT certification pipelines.
Pricing Analysis
China-to-Germany price spreads for equivalent electronic lock SKUs reach three-to-one multiples driven by MIIT GB compliance overhead and domestic cloud integration requirements. Three-tier pricing structure across premium biometric, standard electronic, and economy keypad levels stratifies by certification grade and firmware security tier. Pricing pressure stems from North American commercial real estate operators unbundling hardware from SaaS subscriptions. Parcel delivery networks exhibit highest price sensitivity; luxury hotel chains show lowest.
Supply Chain Analysis
Taiwan and South Korea anchor MCU and wireless chipset fabrication for smart locker lock modules. Battery cell supply draws from China and South Korea; electromechanical components source from Germany and China. Single-source vulnerability concentrates in 40nm MCU wafer supply. Distribution runs through direct OEM relationships with parcel network operators and commercial real estate portfolio managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware engineering talent scarcity constrains vendor scaling across cloud-connected access platforms, with low-power wireless protocol expertise commanding premium compensation in cross-sector competition.
For Market Incumbents: Secure captive semiconductor allocation through foundry partnerships or backward integration into module design. Deepen channel control in European commercial real estate to resist SaaS platform margin capture. Invest in parallel FCC-CE-MIIT certification filing infrastructure to compress 14-18 month timelines. For New Entrants and Emerging Players: Differentiate on healthcare specimen chain custody applications where FDA 21 CFR Part 11 compliance filters incumbent pools. Target India's greenfield logistics corridors where BIS certification pathways are stabilizing. Pursue temperature-controlled medical locker pilots with audit trail capabilities as beachhead entry. For Investors and Strategic Acquirers: Capital is best deployed toward firmware engineering specialists with ISO/IEC 27001 alignment and multi-certification filing capabilities. Long-term viability favors vendors with cloud-backend recurring revenue models over pure hardware plays. Watch UWB module cost curves as inflection signal for spatial-aware security premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Security Certification | ISO/IEC 27001 alignment opens enterprise and government procurement filters. |
| Multi-Region Certification Filing | Parallel FCC, CE, and MIIT GB testing compresses SKU fragmentation for global rollouts. |
| Healthcare Application Development | FDA 21 CFR Part 11 compliance creates defensible positioning in specimen chain custody. |
| UWB Module Integration | Sub-meter positioning verification commands premium over Bluetooth-only commodity tiers. |
| Cloud Platform Partnership | SaaS backend capture redirects recurring revenue from hardware margin compression. |
Research Methodology
A spread of perspectives from lock OEM product managers, parcel network procurement leads, commercial real estate facility directors, and embedded firmware engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from FCC equipment authorization databases, MIIT GB standard filings, EU Radio Equipment Directive notifications, and SEC 10-K disclosures of diversified industrial conglomerates. Bottom-up unit shipment estimates triangulated against top-down smart city budget allocations.
Segmentation dimensions modeled span product type, application, technology architecture, and end-user procurement sophistication across the projection horizon. Credential technology cost curves, wireless protocol adoption rates, and municipal automation budget trajectories fed CAGR derivation. Regional regulatory cluster variations shaped geographic demand allocation.
Decision-makers should treat outputs as directional under sustained e-commerce penetration and semiconductor supply normalization assumptions; material deviation would warrant model refresh. Firmware engineering labor market tightness and lithium battery cost volatility represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
US Access Control Market
Access Control Systems
Access Control Readers Market
Access Control Systems
Latin America Card-Based Access Control Market