
 Global Voice Biometrics Market | 2026-2036
Global Voice Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Voice Biometrics Market Foresight
Deep learning is expanding as the dominant computational substrate for voice biometric engines, displacing earlier Gaussian mixture model architectures and cutting error rates by orders of magnitude. Nuance Communications Inc. leverages its decades-long speech recognition heritage to anchor enterprise relationships across healthcare and financial services. Pindrop Security Inc. specializes in anti-fraud voiceprinting for telephone channels, while NICE Ltd. dominates contact-center deployments with integrated analytics-recording-biometric stacks.
Voice biometrics encompasses the automated identification or verification of individuals through distinctive vocal tract physiology, speaking behavior, and phonetic patterns, typically extracting mel-frequency cepstral coefficients and embedding vectors from audio samples for pattern matching against enrolled templates. The technology serves primarily to authenticate claimed identities in remote channels where passwords or tokens prove vulnerable to theft, replay, or social engineering. Text-independent verification leads in deployment flexibility because users need not recite fixed passphrases, though text-dependent methods retain traction in high-security access control where constrained vocabularies reduce spoofing surface area. Speaker identification segments are accelerating fastest in forensic analysis and large-scale call monitoring, where law enforcement and intelligence agencies process audio archives against watchlists without cooperative subject participation.
The Federal Trade Commission enforces Section 5 unfairness standards against deceptive biometric data practices in the United States, while the EU AI Act classifies remote biometric identification as high-risk and mandates conformity assessments, human oversight, and fundamental rights impact evaluations. India's Digital Personal Data Protection Act imposes purpose limitation and storage constraints on voiceprint processing by banks and telecom operators, shaping how vendors architect consent workflows and data residency. Stakeholders must monitor whether emerging national AI safety institutes will extend biometric-specific testing regimes beyond current voluntary frameworks.
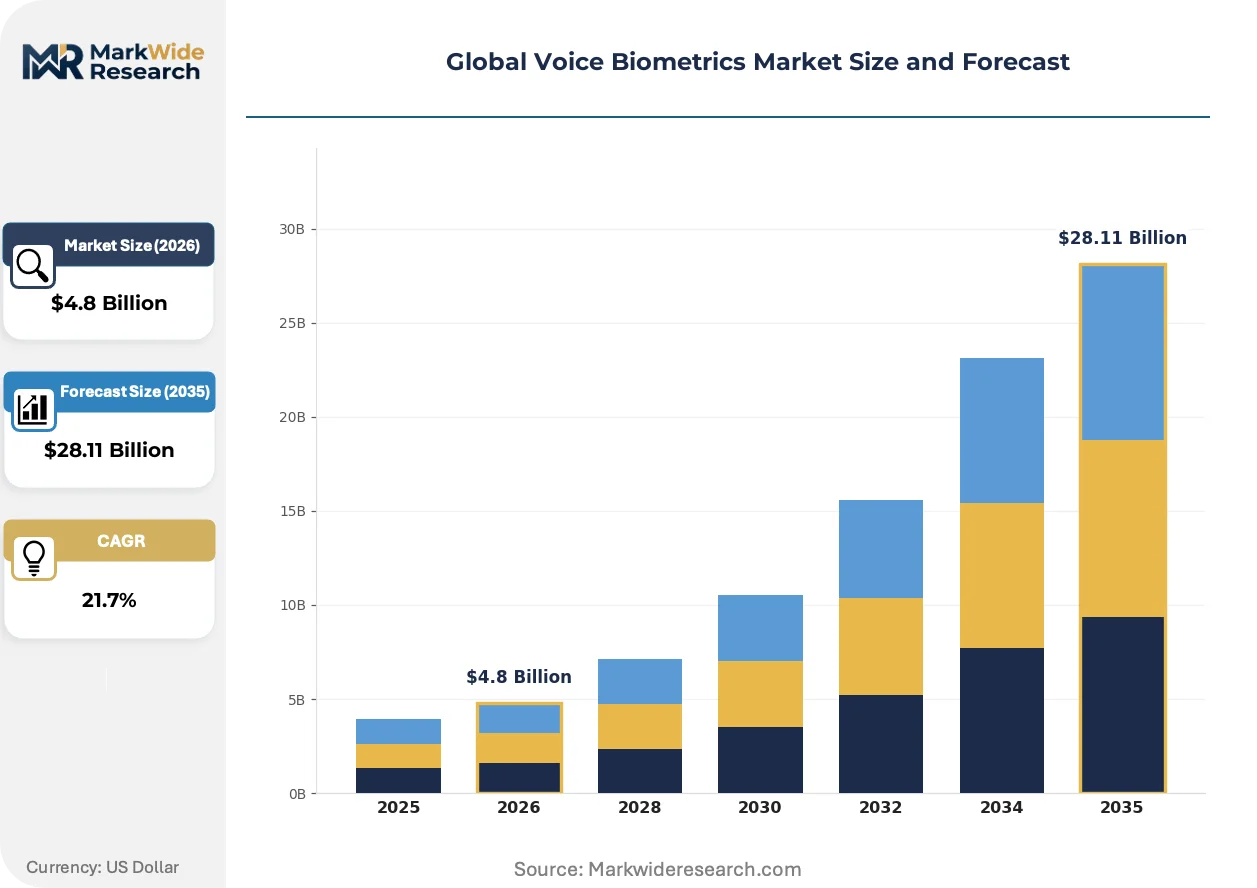
Market Dynamics
Deep learning architectures are compressing error rates in voice biometric engines while banking fraud losses and the EU AI Act's high-risk classification requirements simultaneously accelerate deployment urgency and compliance overhead.
Growth Catalysts
- EU AI Act high-risk mandates:The classification of remote biometric identification as high-risk under EU AI Act Article 6 is forcing conformity assessments and human oversight protocols, creating procurement pull for certified enterprise-grade systems.
- Telephone channel fraud:Financial services firms face escalating synthetic voice attacks against call center authentication, driving replacement of knowledge-based verification with voiceprint matching.
- Text-independent verification:Mel-frequency cepstral coefficient extraction paired with neural embedding vectors eliminates passphrase constraints, expanding deployment across asynchronous digital channels.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for deep neural speaker recognition engines depend on NVIDIA and AMD accelerator availability, with cloud rental rates fluctuating based on semiconductor fab output constraints.
- Enrollment friction:Voiceprint template creation requires multiple clean audio samples, creating abandonment in consumer onboarding flows compared to single-step fingerprint or face capture.
- Presentation attack vulnerability:Replay recordings and synthetic speech generation from text-to-speech models threaten system integrity, requiring liveness detection overlays that add latency and cost.
Strategic Opportunities
- India Digital Personal Data Protection Act:Purpose limitation and storage constraints on voiceprint processing by banks and telecom operators create demand for consent workflow automation and domestic data residency architectures.
- Forensic speaker identification:Law enforcement agencies require batch processing of audio archives against watchlists without cooperative subject participation, opening non-authentication revenue streams.
- Healthcare dictation convergence:Integration of speaker verification with clinical documentation workflows prevents unauthorized access to patient records while streamlining physician authentication.
Industry Challenges
- Phonetic data scientist scarcity:Expertise spanning acoustic signal processing, neural network architecture tuning, and adversarial robustness testing concentrates in a handful of academic labs and incumbent vendors.
- Cross-jurisdiction template portability:Voiceprint storage under India's data localization requirements conflicts with multinational banks' centralized identity architectures, forcing fragmented system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Voice Biometrics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $28.11 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Text-Dependent, Text-Independent, Speaker Identification, Speaker Verification Application: Fraud Detection, Customer Authentication, Access Control, Forensic Analysis, Call Monitoring End User: Banks, Telecom Operators, Government Agencies, Healthcare Providers, E-Commerce Platforms Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Pindrop Security Inc., ID R&D Inc., Nuance Communications Inc., Aculab Ltd., Auraya Systems Pty Ltd., NICE Ltd., LumenVox LLC, Phonexia s.r.o., Verint Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Voice Biometrics Market Shifts & Advancements
Architectural shifts in neural speaker recognition, tightening algorithmic transparency mandates, and evolving procurement criteria for fraud prevention systems are restructuring competitive positioning across authentication markets.
Neural embedding extraction is expanding into the dominant computational substrate for voice biometric engines, replacing Gaussian mixture model architectures that dominated prior decades. Healthcare and financial services procurement teams now mandate deep learning-based systems for new deployments. This compression of legacy technology viability is expanding into adjacent markets including smart home devices and automotive voice assistants.
The EU AI Act's fundamental rights impact evaluation requirement is reshaping vendor go-to-market strategies for biometric identification systems. Conformity assessment body involvement and documented human oversight protocols now precede procurement approvals in European banking and border control. Contact-center solution providers are responding by pre-certifying integrated analytics-recording-biometric stacks to compress sales cycles.
Outcome-based contracting is displacing perpetual license models in enterprise voice biometric procurement. Financial services buyers now demand fraud reduction guarantees tied to authentication performance, shifting vendor revenue toward usage-based or risk-shared structures. This reconfiguration is most visible in United States banking, where procurement teams bundle voice biometrics into broader identity platform RFPs rather than standalone speaker verification purchases.
Global Voice Biometrics Market Segmentation
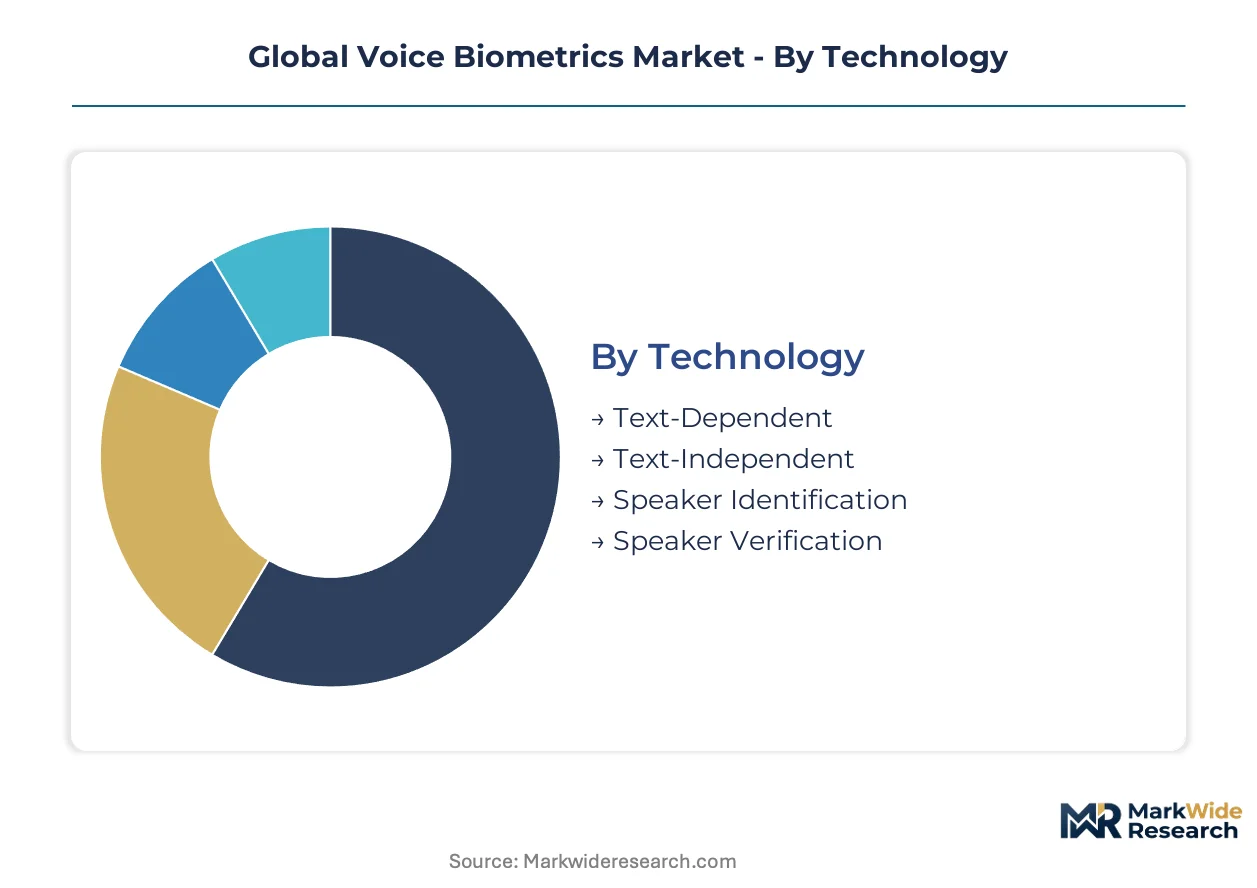
Voice biometrics procurement teams evaluate solutions across four critical dimensions: authentication flexibility, fraud prevention use case, organizational risk profile, and infrastructure sovereignty requirements. Each segmentation axis carries distinct technical specifications and compliance obligations that reshape vendor selection criteria.
Technology:
Banks prioritize authentication friction against security hardening when selecting underlying algorithmic approaches.
- Text-Dependent:Fixed passphrase constraints reduce spoofing surface area through controlled vocabulary exposure. High-security access control in government facilities and classified environments drives demand, though user memorization burdens limit consumer deployment scalability.
- Text-Independent:Neural embedding extraction from spontaneous speech eliminates enrollment friction across asynchronous digital channels. Financial services firms in the United States deploy this for telephone banking authentication where synthetic voice attacks have escalated fraud losses.
- Speaker Identification:Batch processing of audio archives without cooperative subject participation serves law enforcement watchlist matching and forensic analysis workloads.
- Speaker Verification:One-to-one template matching anchors enterprise authentication workflows in contact centers and remote workforce access scenarios.
Volume sits with Text-Independent verification; growth tilts toward Speaker Identification for forensic and intelligence applications.
Application:
Regulatory pressure from the EU AI Act and FTC enforcement reshapes which use cases attract enterprise investment.
- Fraud Detection:Real-time voiceprinting against synthetic speech and replay attacks dominates telephone channel security spending. United States banks face escalating liability from generative AI-enabled social engineering, accelerating replacement of knowledge-based authentication.
- Customer Authentication:Passwordless verification for account access and transaction authorization concentrates in retail banking and telecom subscriber management. India's Digital Personal Data Protection Act imposes purpose limitation requirements that reshape consent workflow design.
- Access Control:Physical and logical entry systems for secure facilities leverage voiceprint matching as a secondary biometric factor.
- Forensic Analysis:Law enforcement agencies across Germany, France, and the United Kingdom process historical audio evidence against enrolled databases without subject cooperation.
- Call Monitoring:Contact-center quality assurance and regulatory compliance recording integrate speaker diarization for agent-customer interaction analysis.
Revenue concentrates in Fraud Detection; steepest expansion trajectory belongs to Forensic Analysis as criminal justice digitization accelerates.
End User:
Data residency mandates and sector-specific breach liability calibrate procurement sophistication across organizational types.
- Banks:Basel operational risk frameworks and PSD2 strong customer authentication requirements in the European Union drive certified enterprise-grade system adoption. India's RBI mandates voiceprint storage localization for payment system operators.
- Telecom Operators:Subscriber identity verification for SIM registration and account recovery concentrates demand in emerging markets with mandatory biometric enrollment regulations.
- Government Agencies:Border control, prison communications monitoring, and intelligence processing require sovereign infrastructure with domestic data residency.
- Healthcare Providers:HIPAA compliance and clinical documentation workflow integration shape speaker verification deployment for physician authentication and patient record access.
- E-Commerce Platforms:Transaction verification and seller identity confirmation represent emerging demand as marketplace fraud sophistication escalates.
Procurement maturity peaks with Banks; Healthcare Providers are gaining share fastest through clinical workflow convergence.
Deployment:
Infrastructure architecture selection hinges on latency requirements, data sovereignty constraints, and GPU compute cost volatility.
- Cloud-Based:Elastic inference scaling for variable contact-center volumes dominates mid-market financial services adoption. EU AI Act high-risk classification mandates human oversight protocols that cloud vendors pre-certify to compress procurement cycles.
- On-Premises:Air-gapped installations serve intelligence agencies and defense contractors with classified processing requirements.
- Hybrid:Template storage on-premises with cloud-based neural network inference balances sovereignty and computational efficiency for multinational banks.
- Edge Computing:Embedded voice biometric engines in automotive voice assistants and smart home devices enable offline authentication with minimal latency.
Cloud-Based deployments hold current volume leadership; Edge Computing climbs fastest as IoT device authentication requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States banking institutions anchor demand concentration as synthetic voice attacks drive replacement of knowledge-based authentication with voiceprint matching systems. Financial services procurement teams bundle speaker verification into broader identity platform investments. The EU AI Act's high-risk classification mandates reshape European deployment timelines and vendor selection criteria.
United States
Telephone channel fraud losses at major banks accelerate voice biometric deployment across retail and commercial banking operations. FTC Section 5 enforcement against deceptive biometric data practices shapes vendor compliance architectures. New York and San Francisco financial services clusters drive enterprise-grade system procurement for contact-center authentication.
Germany
Industrial automation and automotive voice assistant integration create dual demand streams for embedded speaker recognition. KBA and federal data protection authorities enforce strict algorithmic transparency for biometric systems deployed in financial services. Munich and Stuttgart technology corridors concentrate R&D investment for automotive OEM voice authentication programs.
India
RBI mandates for voiceprint storage localization reshape bank and telecom operator procurement specifications. The Digital Personal Data Protection Act imposes purpose limitation requirements that drive consent workflow automation demand. Mumbai and Bangalore financial technology clusters lead domestic vendor development for Aadhaar-linked authentication services.
United Kingdom
Contact-center outsourcing hubs drive cloud-based voice biometric adoption for multinational financial services clients. Information Commissioner's Office guidance on biometric data processing shapes enterprise deployment architectures. London's financial services district concentrates procurement for anti-fraud telephone channel security.
Japan
Aging demographics and labor shortages accelerate voice authentication deployment in healthcare and elderly care facility access control. METI standards for AI system reliability influence vendor certification requirements for banking applications. Tokyo and Osaka metropolitan areas concentrate enterprise procurement for integrated biometric security systems.
Global Voice Biometrics Market Competitive Landscape
Technology licensing and strategic partnership formation dominate the current landscape as vendors accelerate certification for EU AI Act compliance requirements. The vendor base organizes around three strategic archetypes: speech recognition heritage incumbents with enterprise healthcare and financial services relationships, telephone channel anti-fraud specialists with carrier-grade deployment experience, and contact-center solution providers with integrated analytics-recording-biometric stacks. Portfolio diversification into adjacent authentication modalities and geographic expansion into data-residency-constrained markets represent the dominant competitive moves reshaping market structure.
Within the speech recognition heritage tier, Nuance Communications Inc. and NICE Ltd. exemplify vendors leveraging decades-long enterprise relationships to anchor healthcare and financial services procurement decisions. Pindrop Security Inc. occupies a specialized position among telephone channel anti-fraud providers, representing the archetype of vendors engineered specifically for carrier-grade call center deployment against synthetic voice threats.
| Leading Market Players |
|---|
| Pindrop Security Inc. |
| ID R&D Inc. |
| Nuance Communications Inc. |
| Aculab Ltd. |
| Auraya Systems Pty Ltd. |
| NICE Ltd. |
| LumenVox LLC |
| Phonexia s.r.o. |
| Verint Systems Inc. |
| Others |
Supply & Pricing Matrix
United States banking procurement teams concentrate voice biometric purchasing into broader identity platform RFPs, compressing standalone speaker verification margins while elevating outcome-based contracting with fraud reduction guarantees. This buyer consolidation reshapes vendor revenue structures toward usage-based and risk-shared arrangements.
Pricing Analysis
Volume concentrates in cloud-based SaaS tiers while margins accrue to on-premises and hybrid deployments with sovereign infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified enterprise stacks from mid-market contact-center bundles and basic API access. Cost compression in cloud inference is intensifying because GPU rental rate volatility forces vendors to absorb compute spikes. Tier 1 banks demonstrate lowest price sensitivity given fraud liability exposure, while mid-market financial services buyers drive hardest bargain terms.
Supply Chain Analysis
Freight costs for edge computing hardware shipments to automotive and smart home OEMs add margin pressure distinct from cloud software distribution. GPU and AI accelerator supply concentrates in Taiwan, South Korea, and the United States, with NVIDIA and AMD anchoring neural network training and inference. Voice biometric engines draw from cloud hyperscaler infrastructure, proprietary neural embedding models, and mel-frequency cepstral coefficient processing libraries. Single-source vulnerability in advanced semiconductor fabrication threatens delivery timelines for on-premises deployments. Distribution runs through direct enterprise sales for banking and government, with channel partners handling mid-market contact-center integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance overhead and GPU compute cost volatility are forcing weaker voice biometric vendors toward exit or acquisition, consolidating procurement decisions around certified enterprise-grade providers. Incumbents with speech recognition heritage and carrier-grade deployment experience capture disproportionate share.
For Market Incumbents: To counter synthetic voice attack sophistication eroding customer trust, Nuance Communications Inc. and NICE Ltd. should deepen backward integration into liveness detection R&D and pre-certify integrated analytics-recording-biometric stacks for EU conformity assessment bodies. Channel control through exclusive contact-center partnerships compresses sales cycles against telephone channel anti-fraud specialists.
For New Entrants and Emerging Players: India's Digital Personal Data Protection Act opens a window for domestic vendors architecting consent workflow automation and data residency-compliant architectures for Mumbai and Bangalore financial technology clusters. Forensic speaker identification for law enforcement watchlist matching represents the most penetrable white-space segment. Go-to-market through national AI safety institute certification programs builds credibility faster than direct bank procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor telephone channel anti-fraud specialists with carrier-grade deployment experience in the United States, where synthetic voice fraud losses have accelerated replacement timelines. Long-term viability hinges on neural embedding extraction capabilities and EU AI Act certification readiness. Monitor RBI voiceprint localization mandates as inflection indicator for India-focused acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Conformity assessment body involvement compresses European banking and border control sales cycles. |
| Outcome-Based Contracting | Fraud reduction guarantees shift vendor revenue toward usage-based structures with United States banks. |
| Data Residency Architecture | Domestic template storage aligns with India's RBI mandates and Digital Personal Data Protection Act constraints. |
| Forensic Speaker Identification | Batch processing capabilities open non-authentication revenue streams with law enforcement agencies. |
| Healthcare Workflow Integration | Clinical documentation convergence prevents unauthorized patient record access while streamlining physician authentication. |
Research Methodology
SEC filings, EU AI Act regulatory documentation, and cloud hyperscaler capex disclosures formed the secondary backbone, supplemented by customs records tracking GPU and AI accelerator trade flows. Primary interviews with bank fraud prevention executives, contact-center procurement officers, biometric system integration specialists, and regulatory compliance directors at financial services firms validated deployment timelines and certification requirements. Bottom-up triangulation across vendor revenue disclosures and top-down modeling against telephone channel fraud loss estimates anchored market sizing.
Historical trendline analysis of speaker verification deployment in United States banking and European contact-center outsourcing established baseline adoption curves across the projection horizon. The analytical framework modeled technology segmentation by text-dependent, text-independent, speaker identification, and speaker verification approaches; application segmentation by fraud detection, customer authentication, access control, forensic analysis, and call monitoring; and deployment segmentation by cloud-based, on-premises, hybrid, and edge computing architectures. CAGRs derived from neural embedding extraction penetration curves and EU AI Act procurement acceleration assumptions.
The model assumes a particular technology adoption path; alternative pathways for Gaussian mixture model retention in legacy installations would alter the outlook. Forecasts reflect assumptions about synthetic voice attack sophistication, GPU supply normalization, and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market