
 Global Mucosal Atomization Devices Market | 2026-2036
Global Mucosal Atomization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mucosal Atomization Devices Market Foresight
Miniaturization of piezoelectric transducers is reshaping how mucosal atomization devices achieve consistent particle size distribution across portable platforms. Mercury Medical leverages vertical integration to control nozzle manufacturing tolerances. Kurve Therapeutics anchors its position through R&D intensity in intranasal drug-device combinations. Teleflex Incorporated dominates distribution channels across North American hospital systems.
Mucosal atomization devices generate fine aerosolized droplets, typically within the 20-50 micron range, for deposition onto nasal, oral, or tracheal mucosal surfaces to enable rapid systemic absorption or localized therapeutic effect. The primary commercial purpose centers on bypassing gastrointestinal degradation and first-pass hepatic metabolism for faster onset of clinical action. Disposable devices command the largest revenue pool due to infection control protocols, while electronic atomizers represent the fastest-expanding segment as battery efficiency improves. Pressure-driven atomization technology maintains mature market presence in emergency settings, whereas ultrasonic nebulization captures margin concentration in specialized anesthesia applications.
FDA 510(k) premarket notification requirements shape product development timelines and clinical evidence standards for U.S. market entry. The EU Medical Device Regulation (MDR) and CE marking obligations impose stricter post-market surveillance and quality management system demands across European jurisdictions. ISO 13485 certification serves as the baseline quality framework for manufacturers seeking multi-regional commercialization. Stakeholders must monitor evolving pharmacovigilance requirements for combination products as regulatory convergence between drug and device oversight intensifies.
Market Dynamics
Pressure-driven atomization technology faces displacement from ultrasonic nebulization as battery efficiency improvements enable portable electronic platforms. Mercury Medical's vertical integration into nozzle manufacturing tightens supply control while Kurve Therapeutics intensifies R&D in intranasal drug-device combinations.
Growth Catalysts
- Emergency medical services expansion:Prehospital care infrastructure investments in the United States, Germany, and Japan accelerate device procurement for rapid drug delivery scenarios.
- FDA 510(k) clearance pathway:The streamlined premarket notification process reduces commercialization timelines for nasal delivery systems entering U.S. distribution.
- Infection control protocols:Hospital systems mandate single-use disposable devices, creating structural demand pull across acute care settings.
Market Restraints
- Piezoelectric material cost volatility:Supply concentration for specialized ceramics strains electronic atomizer production economics.
- EU MDR compliance burden:Stricter post-market surveillance and quality management obligations extend European market entry timelines.
- First-pass metabolism bypass limitations:Certain drug classes remain incompatible with mucosal absorption, constraining addressable therapeutic categories.
Strategic Opportunities
- Japan's aging demographic:Home healthcare infrastructure expansion creates demand for patient-administered intranasal delivery systems.
- Pediatric anesthesia applications:Needle-free drug delivery addresses compliance challenges in specialized surgical settings.
- ISO 13485 certification leverage:Baseline quality framework enables multi-regional commercialization from unified manufacturing footprints.
Industry Challenges
- Combination product regulatory convergence:Intensifying oversight integration between drug and device authorities complicates submission strategies.
- Particle size distribution consistency:Miniaturized transducer manufacturing demands precision engineering talent scarce in contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mucosal Atomization Devices Market |
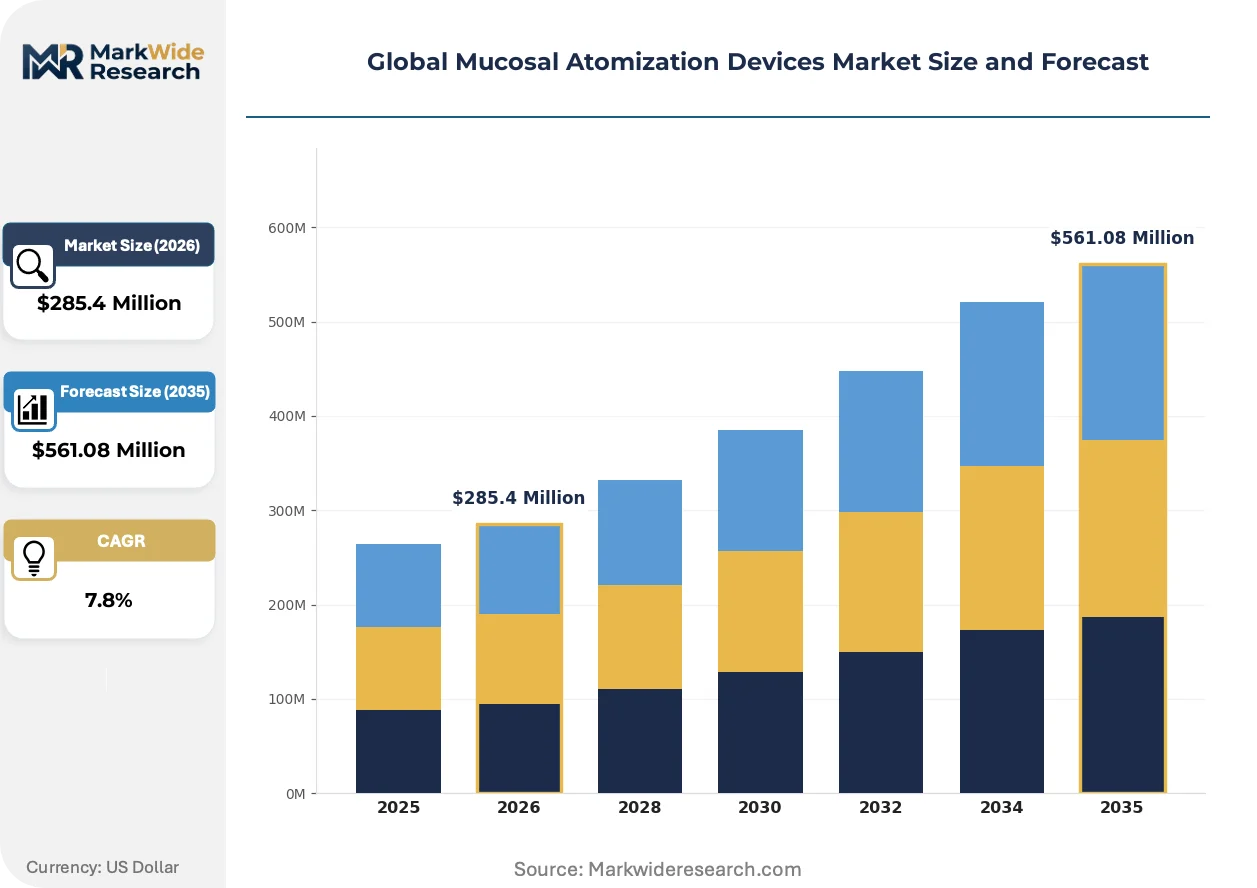
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Atomizers, Electronic Atomizers, Disposable Devices, Reusable Devices Application: Anesthesia Delivery, Pain Management, Vaccine Administration, Respiratory Therapy, Diagnostic Procedures Technology: Ultrasonic Nebulization, Pressure-Driven Atomization, Piezoelectric Technology, Electrostatic Spraying End User: Hospitals, Ambulatory Surgical Centers, Veterinary Clinics, Emergency Medical Services |
| Companies Covered | Life-Assist Inc., Mercury Medical, Teleflex Incorporated, Becton Dickinson and Company, DeVilbiss Healthcare LLC, Cook Medical LLC, Vyaire Medical Inc., Kurve Therapeutics, Pulmodyne Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mucosal Atomization Devices Market Shifts & Advancements
Ultrasonic nebulization is virtualizing traditional pressure-driven platforms across emergency and anesthesia settings. Three developments dominate competitive positioning.
Battery-integrated piezoelectric transducers enable consistent 20-50 micron droplet generation without compressed gas infrastructure. Emergency medical services in North American hospital systems adopt these platforms for field portability. Electronic atomization is virtualizing the installed base of mechanical squeeze-bulb devices.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic clinical follow-up for Class IIa and above nasal delivery systems. Manufacturers must maintain vigilance systems capturing adverse events across distributed care settings. German notified bodies apply heightened scrutiny to drug-device combination submissions.
Prehospital care procurement committees now specify battery lifecycle performance alongside particle size metrics in competitive tenders. United States emergency services consortiums consolidate purchasing through group purchasing organizations. Teleflex Incorporated and Kurve Therapeutics compete on total cost-of-ownership documentation rather than device price alone.
Global Mucosal Atomization Devices Market Segmentation
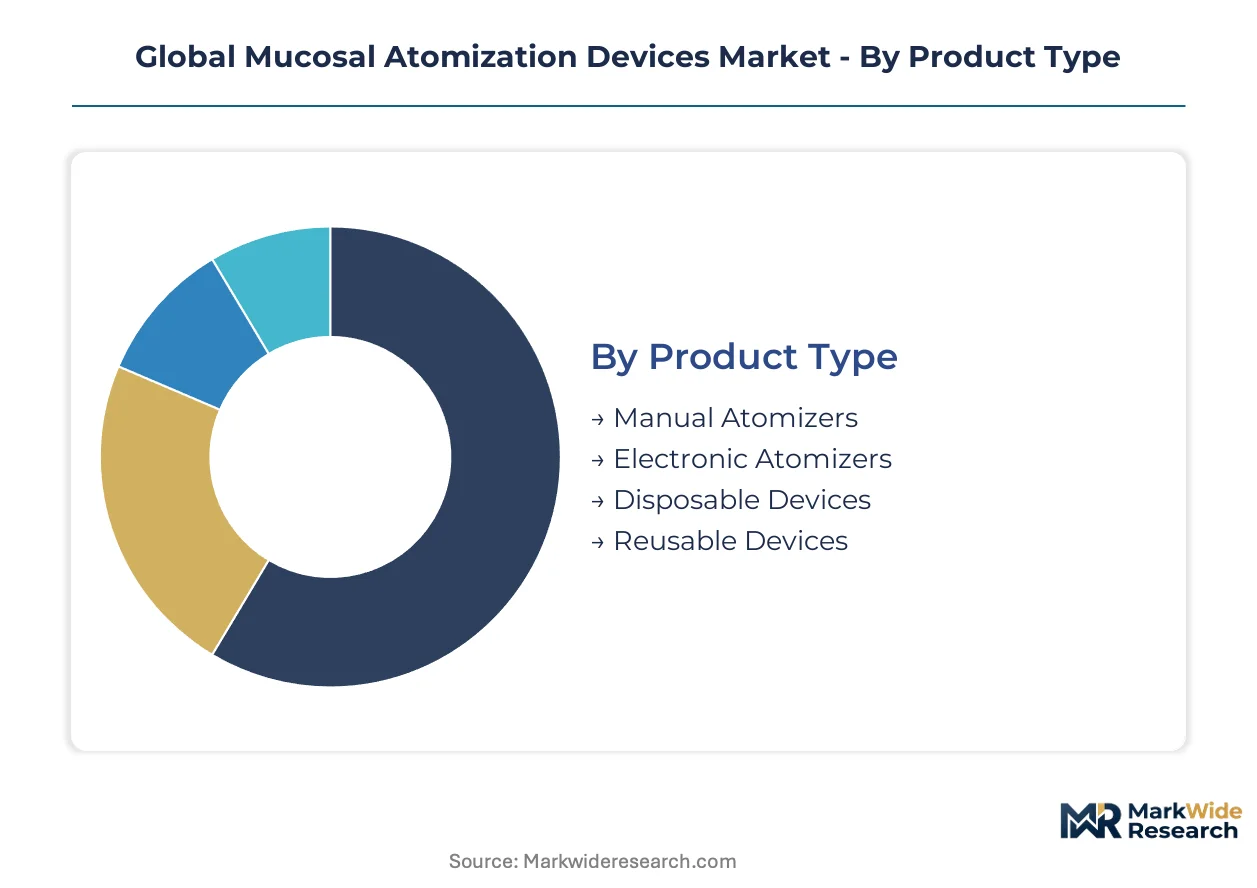
Segmentation in mucosal atomization devices reveals how clinical use-case diversity drives hardware specialization. Emergency settings demand disposable, pressure-driven platforms while anesthesia suites prioritize electronic precision. Each dimension carries distinct regulatory pathways and procurement economics.
Product Type:
Use-case spectrum spans field-portable manual squeeze-bulb devices to programmable electronic systems with integrated battery management.
- Manual Atomizers:Mechanical squeeze-bulb mechanisms generate aerosol through hand-actuated pressure pulses. Demand concentrates in United States emergency medical services where prehospital protocols mandate immediate deployment without power dependency. Procurement committees prioritize unit cost and shelf stability over precision metrics.
- Electronic Atomizers:Battery-integrated piezoelectric transducers deliver consistent 20-50 micron droplet distributions. German hospital systems and Japanese home healthcare infrastructure are expanding procurement as lithium-ion efficiency improves and device miniaturization advances.
- Disposable Devices:Single-use polymer construction eliminates cross-contamination risks in acute care settings.
- Reusable Devices:Autoclavable stainless steel and medical-grade silicone assemblies serve veterinary and research applications with lower patient throughput.
The dominant share belongs to Disposable Devices, while Electronic Atomizers are climbing the fastest as battery chemistry and transducer manufacturing mature.
Application:
Clinical indication shapes particle size targets and delivery site specifications across the therapeutic portfolio.
- Anesthesia Delivery:Intranasal midazolam and ketamine administration requires 30-50 micron droplets for rapid mucosal absorption preceding pediatric procedures. United States ambulatory surgical centers are standardizing needle-free protocols to address pediatric compliance challenges.
- Pain Management:Fentanyl and naloxone delivery for breakthrough cancer pain and opioid overdose reversal demands sub-30 micron particle distributions for deep nasal cavity deposition. Emergency medical services in Japan and Germany specify these platforms for field deployment.
- Vaccine Administration:Mucosal immunization routes bypass cold chain constraints for certain vector-based formulations.
- Respiratory Therapy:Corticosteroid and bronchodilator deposition onto tracheal mucosa serves intensive care ventilation weaning protocols.
- Diagnostic Procedures:Topical anesthetic atomization precedes nasendoscopy and laryngoscopy across otolaryngology practices.
Pain Management commands the largest procurement volume, while Vaccine Administration is gaining share fastest as intranasal platform technologies advance through clinical pipelines.
Technology:
Platform physics determines portability, power requirements, and particle engineering precision.
- Ultrasonic Nebulization:High-frequency piezoelectric vibration at 1-3 MHz generates monodisperse aerosols without compressed gas. Anesthesia departments in United States academic medical centers specify these systems for controlled sedation induction.
- Pressure-Driven Atomization:Compressed gas or mechanical force shears liquid into droplets through fixed-orifice nozzles. Emergency medical services maintain installed base dominance due to reliability and field maintenance simplicity.
- Piezoelectric Technology:Solid-state transducer arrays enable programmable droplet size modulation through frequency adjustment.
- Electrostatic Spraying:Charged particle generation enhances deposition efficiency onto mucosal surfaces through electrostatic attraction.
Pressure-Driven Atomization retains the dominant installed base, though Piezoelectric Technology is expanding most quickly as semiconductor manufacturing scales reduce transducer costs.
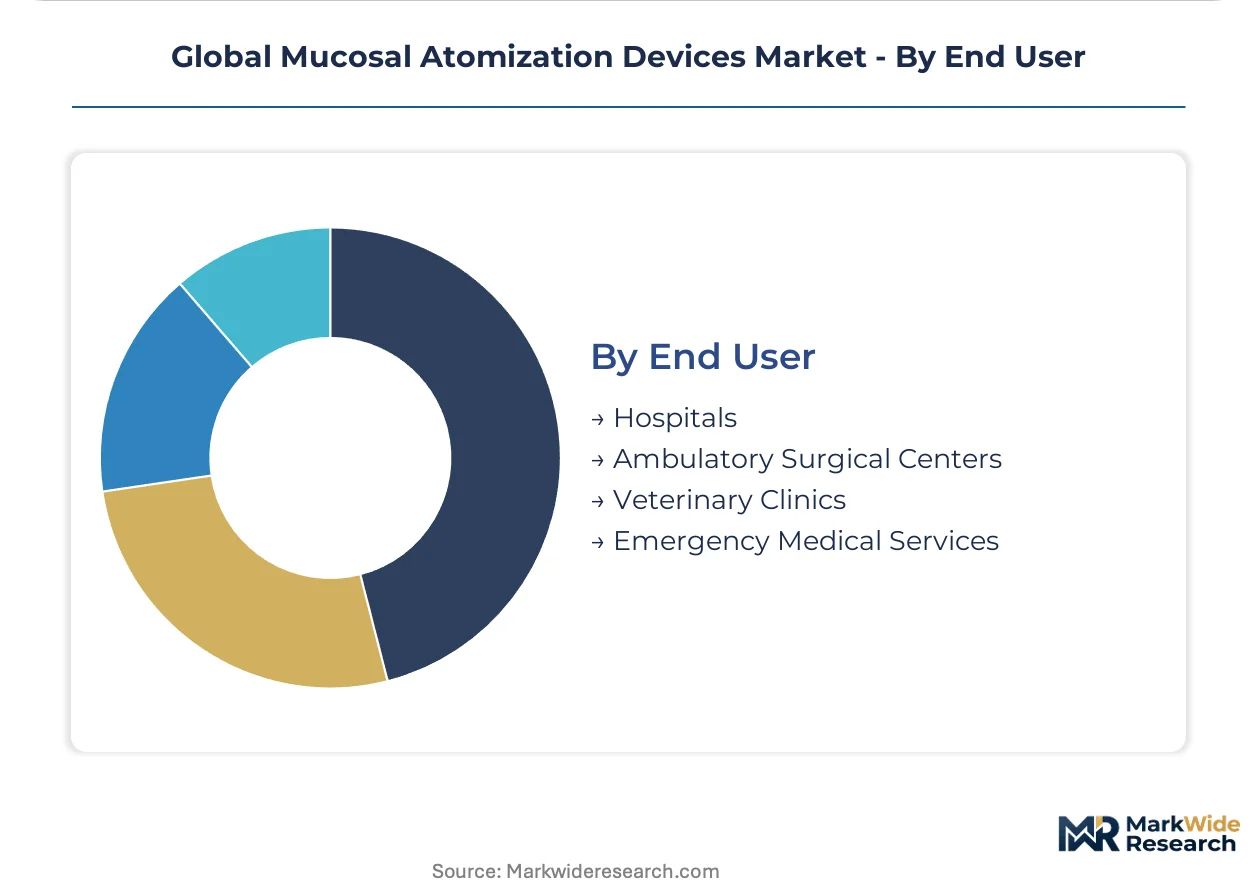
End User:
Procurement authority and reimbursement pathways segment demand across institutional settings.
- Hospitals:Infection control committees mandate disposable platforms for emergency departments while anesthesia divisions invest in electronic precision systems. United States health systems consolidate purchasing through group purchasing organizations with total cost-of-ownership evaluation criteria.
- Emergency Medical Services:Prehospital care infrastructure investments in Germany and Japan specify battery-integrated platforms with validated lifecycle performance under temperature extremes.
- Ambulatory Surgical Centers:Lower patient volumes favor reusable device economics with sterilization protocol compliance.
- Veterinary Clinics:Companion animal anesthesia and large-animal respiratory therapy applications adapt human-device platforms with modified nozzle geometries.
Hospitals capture the dominant procurement value, while Emergency Medical Services is closing the gap fastest as municipal prehospital budgets expand in developed economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered electronic atomizers to United States hospital systems, while Japanese suppliers ship miniaturized piezoelectric components to European anesthesia equipment integrators.
United States
Emergency medical services procurement drives volume, with municipal prehospital budgets expanding across metropolitan networks. FDA 510(k) premarket notification streamlines commercialization timelines for nasal delivery systems. Boston and Minneapolis medical device clusters concentrate R&D activity for intranasal drug-device combinations.
Germany
Hospital infection control committees mandate single-use disposable platforms for emergency departments. EU Medical Device Regulation imposes stricter post-market surveillance and quality management obligations on manufacturers. Baden-Württemberg and Bavaria host precision nozzle fabrication facilities supplying continental anesthesia equipment producers.
Japan
Aging demographics expand home healthcare infrastructure demand for patient-administered intranasal delivery systems. PMDA oversees pharmaceutical and medical device combination product approvals with intensifying oversight integration. Tokyo and Osaka metropolitan areas concentrate battery-integrated platform assembly for domestic and export markets.
United Kingdom
Ambulatory surgical centers standardize needle-free protocols to address pediatric compliance challenges in anesthesia delivery. MHRA enforces post-Brexit regulatory alignment with EU MDR standards for market entry. London and Southeast England clusters specialize in diagnostic procedure applications for otolaryngology practices.
India
Domestic manufacturing scales for cost-optimized manual atomizers serving veterinary and emerging market applications. CDSCO regulates medical device imports while PLI scheme incentives expand local production capacity. Maharashtra and Gujarat industrial corridors develop polymer molding capabilities for disposable device platforms.
Global Mucosal Atomization Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mercury Medical and Teleflex Incorporated anchor distribution networks through group purchasing organization relationships, while Kurve Therapeutics occupies the R&D-intensive drug-device combination niche. Tiered competitive dynamics separate scale-driven manufacturers from precision-engineering specialists. Dominant moves include backward integration into nozzle manufacturing and strategic partnerships for combination product regulatory navigation.
Among United States-based diversified medical technology corporations, Teleflex Incorporated and Becton Dickinson and Company exemplify channel-controlling archetypes through consolidated hospital system procurement relationships. Mercury Medical represents the vertically integrated specialist tier with captive supply of critical nozzle components. Kurve Therapeutics occupies the innovation-driven position focused on intranasal drug-device combination development.
| Leading Market Players |
|---|
| Life-Assist Inc. |
| Mercury Medical |
| Teleflex Incorporated |
| Becton Dickinson and Company |
| DeVilbiss Healthcare LLC |
| Cook Medical LLC |
| Vyaire Medical Inc. |
| Kurve Therapeutics |
| Pulmodyne Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese polymer molding facilities is compressing unit economics for disposable device manufacturers while simultaneously granting procurement committees in United States hospital systems enhanced negotiating leverage on volume contracts.
Pricing Analysis
Current-generation electronic atomizers command substantial premiums over prior-generation mechanical squeeze-bulb devices, while next-generation battery-integrated platforms with programmable droplet modulation are entering at premium-mid-economy pricing differentiation. Cost compression in the manual atomizer tier is intensifying because Chinese contract manufacturers are absorbing margin erosion to maintain utilization rates. United States emergency medical services procurement committees exhibit highest price sensitivity due to municipal budget constraints, whereas German anesthesia departments demonstrate lowest sensitivity given reimbursement structures that prioritize precision metrics over capital expenditure.
Supply Chain Analysis
Export control regimes targeting advanced piezoelectric ceramics and high-frequency transducer arrays are constraining technology flows from Japanese component suppliers to European device integrators. Manufacturing concentrates in China for polymer device housings, Germany for precision nozzle fabrication, and Japan for piezoelectric transducer arrays. The supply chain draws from specialized ceramic substrates, medical-grade lithium-ion cells, and autoclavable stainless steel alloys. Single-source vulnerability in Japanese transducer supply creates structural risk for electronic atomizer producers. Distribution runs through group purchasing organizations in North American hospital systems and direct hospital contracting in European jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of precision engineering talent capable of manufacturing miniaturized transducers at consistent tolerances is constraining capacity expansion for electronic atomizer platforms and reshaping competitive entry economics.
For Market Incumbents: Harden supply security through backward integration into piezoelectric ceramic sourcing or captive nozzle manufacturing capabilities. Incumbents must simultaneously defend against ultrasonic nebulization substitution by investing in battery lifecycle performance documentation that satisfies prehospital procurement specifications. Channel control through group purchasing organization relationships represents the critical defensive lever.
For New Entrants and Emerging Players: Pediatric anesthesia applications in ambulatory surgical centers represent the most penetrable entry point given compliance-driven demand for needle-free protocols and lower incumbent saturation. Japanese home healthcare infrastructure expansion offers secondary white-space opportunity as aging demographics expand patient-administered delivery system demand. A go-to-market strategy anchored through reimbursement strategy development with regional health technology assessment bodies enables pricing capture.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic atomizer manufacturing as cleanroom fabrication requirements and precision metrology equipment demands escalate. Long-term viability favors targets with established ISO 13485 quality frameworks and demonstrated regulatory navigation through FDA 510(k) or EU MDR pathways. The signal to watch is PMDA combination product approval velocity for intranasal drug-device platforms targeting Japan's expanding home healthcare segment.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates commercialization timelines for nasal delivery systems entering United States distribution. |
| CE Marking Pathway | EU MDR compliance enables market access across German hospital systems with stringent post-market surveillance obligations. |
| Hospital System Partnership | Group purchasing organization relationships anchor volume procurement through consolidated United States health system networks. |
| Backward Integration | Captive nozzle manufacturing tightens supply control and protects margin position against piezoelectric material cost volatility. |
| Reimbursement Strategy | Coding and coverage alignment with Medicare and commercial payors determines adoption velocity in outpatient settings. |
Research Methodology
A standing panel of emergency medical services procurement directors, anesthesia department chiefs, biomedical engineers, and group purchasing organization contract managers provided ongoing calibration throughout the study period. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and GPO contract repositories. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored volume estimates.
Scenario-bracketing around battery efficiency improvement curves and regulatory approval velocity variations framed the projection horizon. Segmentation dimensions modeled include product type, application indication, technology platform, and end-user setting across the analysis window. CAGRs derived from fitted growth curves incorporating emergency medical services infrastructure investment schedules and intranasal drug pipeline advancement rates. Forecast inputs included municipal prehospital budget trajectories and piezoelectric transducer cost decline assumptions.
Practitioners should monitor FDA combination product guidance evolution and Japanese PMDA drug-device oversight integration for early signals of regulatory friction. Forecasts reflect assumptions regarding lithium-ion battery chemistry advancement and infection control protocol persistence in acute care settings. Material shifts in export control regime stringency for piezoelectric ceramics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Steerable Needles Market
Medical Devices
Rapid Infuser Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Global Casting Devices Market
Medical Devices
Capsule Endoscope and Workstations Market