
 Global Syringe Pumps Market | 2026-2036
Global Syringe Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Syringe Pumps Market Foresight
Hospital procurement consortiums is reshaping how syringe pump manufacturers secure volume contracts across integrated delivery networks. Becton, Dickinson and Company leverages its broad infusion portfolio to anchor long-term supply agreements with major health systems. Fresenius Kabi AG specializes in critical care applications where precision dosing commands premium positioning. Terumo Corporation competes through manufacturing scale that sustains cost leadership in standard mechanical pump segments.
A syringe pump is a motor-driven precision fluid delivery device that displaces plunger-driven syringes at controlled flow rates, typically achieving accuracy within plus or minus two percent for volumes ranging from microliters to hundreds of milliliters. Its primary commercial purpose is to administer medications, nutrients, or diagnostic agents at programmed intervals in clinical and research settings where manual dosing risks therapeutic failure or patient harm. Volumetric pumps occupy the mature core of the product mix, while smart pumps with dose-error reduction software capture expanding margin pools as liability concerns intensify. Electronic technology leads unit shipments, though wireless controlled systems represent the fastest-growing configuration as hospitals prioritize centralized monitoring and interoperability with electronic health records.
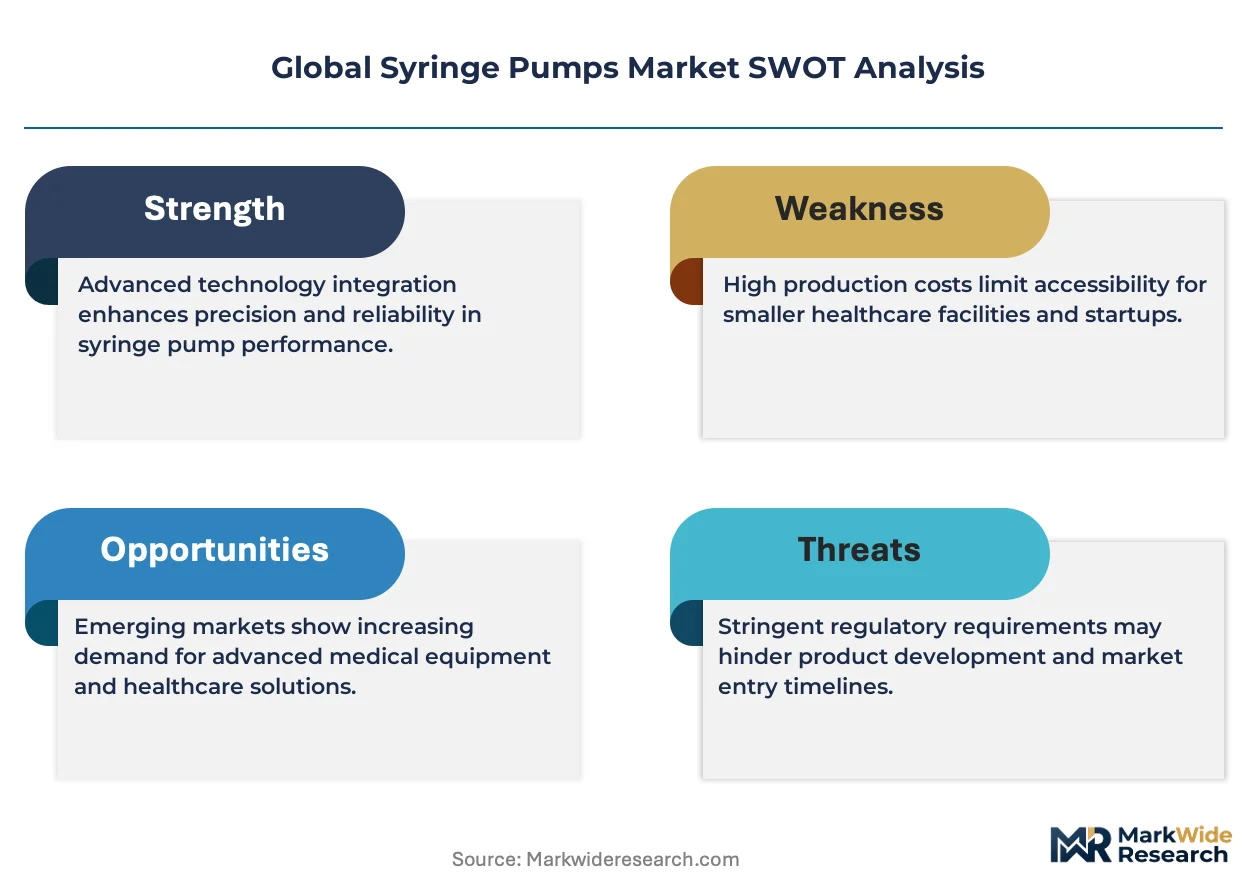
The FDA regulates syringe pumps as Class II medical devices under 21 CFR 880.5725, requiring substantial equivalence demonstrations for premarket clearance that shape product development timelines and design architectures. The EU Medical Device Regulation mandates enhanced clinical evidence and post-market surveillance through EUDAMED, elevating compliance costs for manufacturers seeking CE marking access. ISO 80369-6 small-bore connector standards for neuraxial applications further constrain design flexibility and force hardware revisions. Stakeholders must monitor how converging cybersecurity guidance from FDA and IEC 81001-5-1 reshapes validation requirements for connected pump ecosystems.
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across integrated delivery networks, forcing manufacturers to restructure pricing architectures and service commitments around multi-year enterprise agreements rather than transactional equipment sales.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical evidence requirements for CE marking create competitive moats for established manufacturers with robust quality systems, squeezing marginal competitors from the European market.
- Neuraxial drug delivery:Expanding applications in pain management and anesthesia drive demand for ISO 80369-6 compliant small-bore connector systems with dedicated safety profiles.
- Japan's metropolitan hospital networks:Concentrated investment in smart infusion infrastructure across Tokyo, Osaka, and Nagoya accelerates replacement cycles for connected pump ecosystems.
Market Restraints
- Semiconductor supply concentration:Dependence on specialized microcontrollers from concentrated Asian foundries exposes pump manufacturers to lead-time volatility and allocation constraints.
- Polymer cost sensitivity:Medical-grade polycarbonate and ABS resin prices fluctuate with petrochemical feedstock markets, compressing margins on standard mechanical pump segments.
- Interoperability fragmentation:Proprietary communication protocols between pump systems and electronic health records create integration friction that delays hospital adoption decisions.
Strategic Opportunities
- Germany's Klinikum modernization wave:Federal hospital infrastructure programs fund smart infusion system upgrades across university medical centers and municipal hospital networks.
- Wearable ambulatory pumps:Convergence of miniaturized motor technology with flexible battery chemistry enables subcutaneous drug delivery outside traditional bedside settings.
- Cybersecurity validation services:FDA and IEC 81001-5-1 guidance creates ancillary revenue streams for manufacturers offering penetration testing and software update infrastructure.
Industry Challenges
- Biomedical engineering talent scarcity:Shortage of professionals cross-trained in fluid mechanics, embedded systems, and clinical workflow design extends product development timelines.
- 510(k) clearance compression:FDA substantial equivalence demonstrations for software-enabled pumps require extensive predicate device analysis that consumes regulatory resources.
- Legacy pump fleet interoperability:Hospital demand for backward compatibility with installed base hardware constrains architectural innovation in next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Syringe Pumps Market |
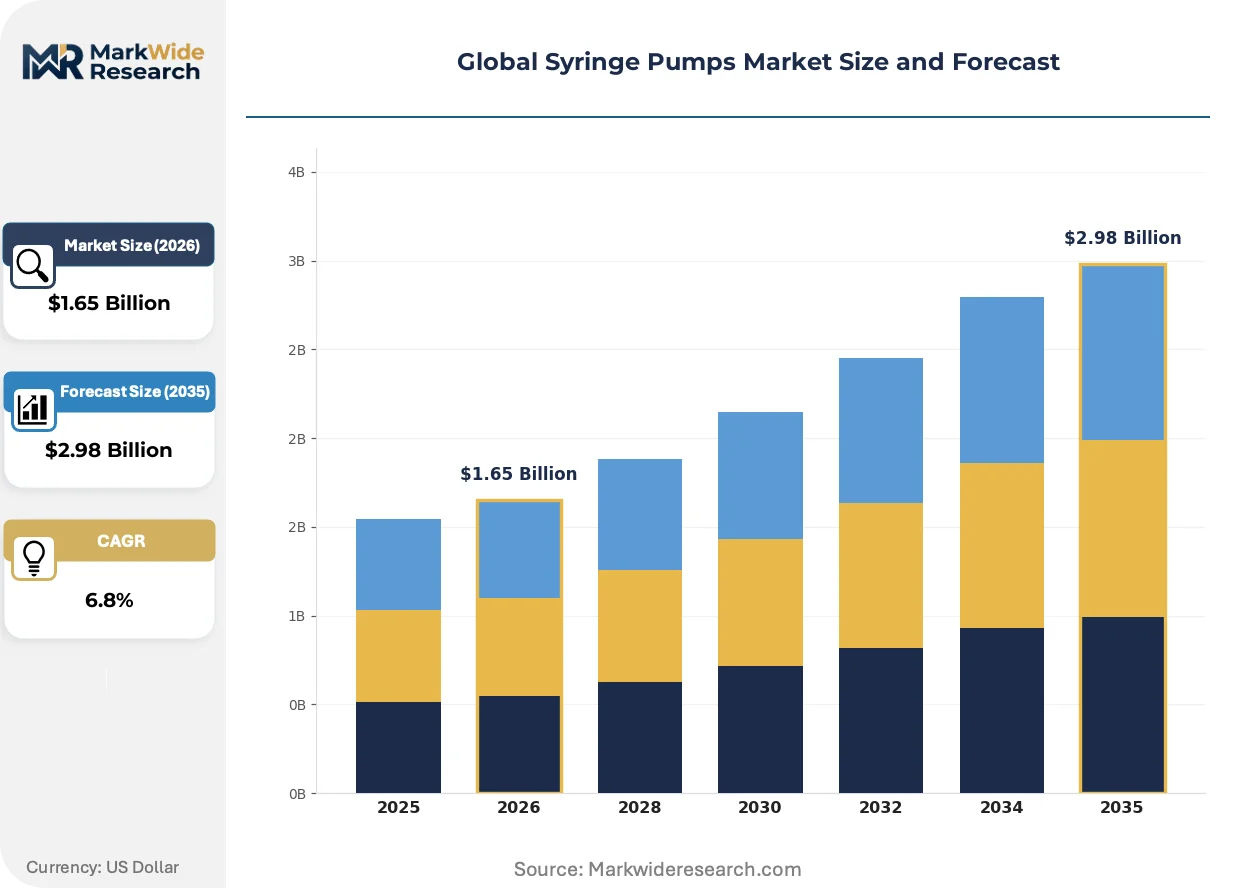
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
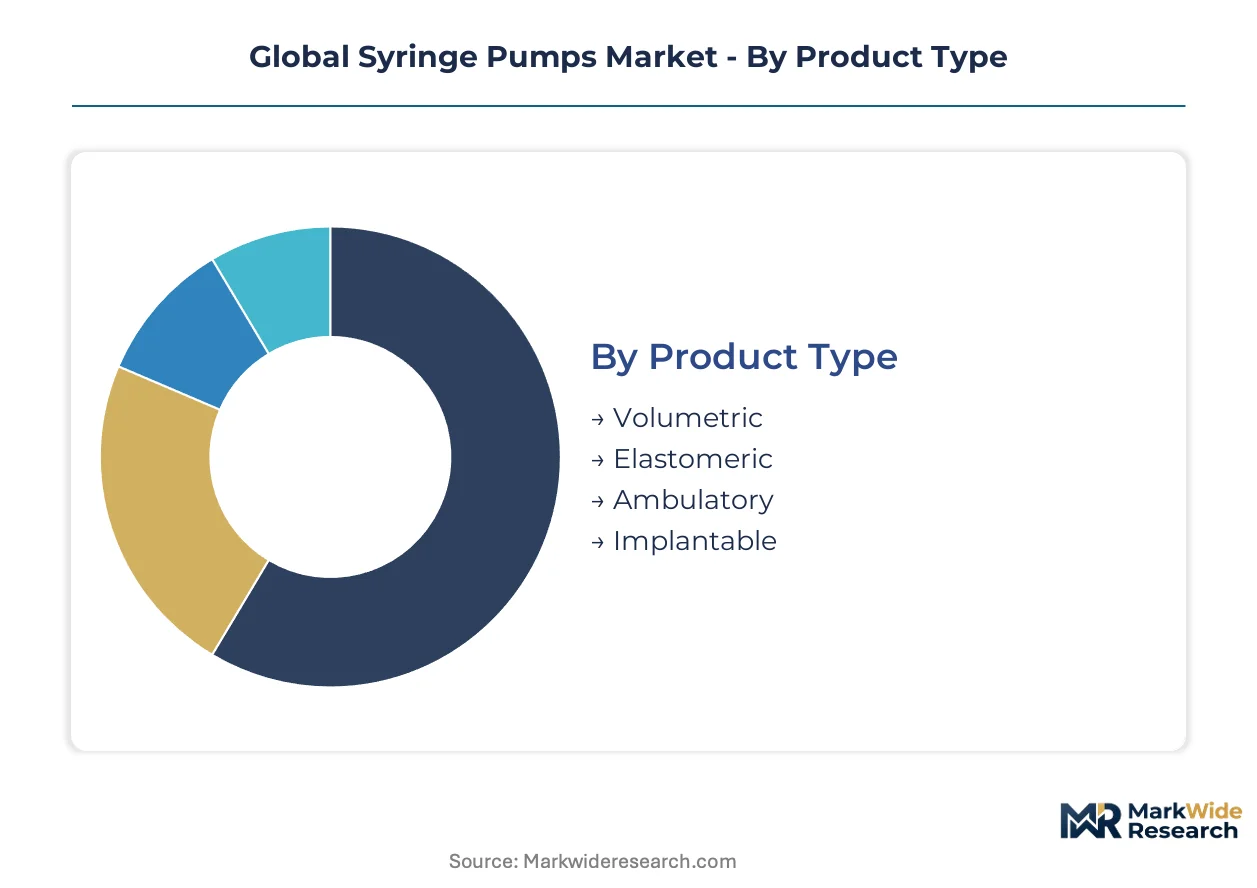
| Segmentation | Product Type: Volumetric, Elastomeric, Ambulatory, Implantable Application: Anesthesia, Critical Care, Oncology, Neonatal Care, Pain Management End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare, Specialty Clinics Technology: Mechanical, Electronic, Smart Pumps, Wireless Controlled |
| Companies Covered | ICU Medical, Inc., Terumo Corporation, Becton, Dickinson and Company, Smiths Medical, Medtronic plc, B. Braun Medical, Baxter International Inc., Boston Scientific Corporation, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Syringe Pumps Market Shifts & Advancements
Smart infusion technology is redefining competitive differentiation as dose-error reduction software and wireless connectivity migrate from premium tier to baseline expectation across hospital purchasing specifications.
Closed-loop infusion control is hybridizing pharmacokinetic modeling with real-time patient monitoring data streams. Academic medical centers in the United States and Germany are piloting these systems for insulin and anesthesia delivery. The technology is compressing the window between physiological change and therapeutic adjustment, shifting liability frameworks toward shared algorithm accountability.
The EU Medical Device Regulation's post-market surveillance mandates through EUDAMED are elevating clinical evidence requirements for pump manufacturers seeking CE marking renewal. This regulatory pressure is forcing portfolio rationalization as smaller product lines fail to justify ongoing clinical follow-up costs. High-risk therapeutic segments including neonatal and oncology infusion face the steepest compliance burden.
Consolidated purchasing by hospital procurement consortiums is replacing decentralized department-level acquisition. Integrated delivery networks in the United States and national health service trusts in the United Kingdom now negotiate enterprise-wide pump contracts spanning multiple facilities. This concentration is visible most acutely in standard volumetric pump categories where interchangeability and service standardization dominate selection criteria over device-specific features.
Global Syringe Pumps Market Segmentation
Syringe pump manufacturers structure service contracts and spare parts logistics around how each segment wears, fails, and requires recalibration. Segmentation thus determines aftermarket revenue depth and customer lifetime value calculations.
Product Type:
After-sales service intensity varies sharply across pump architectures, with electronic and implantable systems demanding specialized technician networks that mechanical devices do not.
- Volumetric:These gravity-assisted or pressure-driven systems deliver preset fluid volumes through calibrated chambers. Demand concentrates in India's municipal hospital networks where procurement budgets favor proven mechanical reliability over connectivity features. The segment generates recurring revenue through disposable administration sets rather than device servicing.
- Smart Pumps:Dose-error reduction software and drug libraries define these electronically controlled units. Germany's university medical centers drive replacement demand as EU MDR compliance deadlines force hardware refreshes. Service contracts bundle cybersecurity patch management with preventive maintenance.
- Elastomeric:Balloon-powered disposable pumps for post-operative pain management require minimal technical support beyond patient training.
- Ambulatory:Wearable battery-powered devices for home chemotherapy rely on regional distributor networks for patient education and troubleshooting.
- Implantable:Intrathecal drug delivery systems demand surgical specialist partnerships and long-term monitoring protocols.
Volumetric pumps hold the largest share; momentum sits with smart pumps as liability concerns intensify.
Application:
Margin structures diverge across clinical settings based on dosing precision requirements and regulatory scrutiny intensity.
- Critical Care:Multi-channel infusion with hemodynamic monitoring integration characterizes ICU deployments. Japan's metropolitan emergency centers prioritize these systems for sepsis and shock management where micro-rate accuracy prevents therapeutic failure.
- Oncology:Chemotherapy protocols require vesicant drug libraries and flow-rate verification algorithms. Outpatient infusion centers in the United States negotiate enterprise contracts bundling pump rental with hazardous drug handling compliance.
- Anesthesia:Operating room workflows favor rapid syringe exchange and TCI (target-controlled infusion) compatibility.
- Neonatal Care:Micro-volume accuracy down to 0.1 mL/hour distinguishes NICU-specific designs with air-in-line detection.
- Pain Management:PCA (patient-controlled analgesia) functionality dominates post-surgical and chronic pain applications.
Critical care commands the highest installed base; oncology applications are climbing the fastest as ambulatory infusion expands.
End User:
Purchasing authority concentration shapes how manufacturers structure pricing tiers and field service coverage.
- Hospitals:Integrated delivery networks consolidate enterprise agreements spanning multiple facilities. Procurement consortiums in the United Kingdom's NHS trusts negotiate five-year contracts with standardized training and interoperability mandates.
- Home Healthcare:Durable medical equipment suppliers manage patient onboarding and 24-hour technical hotlines. Japan's aging population drives demand for portable infusion allowing palliative care outside institutional settings.
- Ambulatory Surgical Centers:Same-day discharge protocols favor single-use elastomeric pumps over capital equipment.
- Specialty Clinics:Dialysis and fertility centers require procedure-specific flow profiles and limited multi-channel capability.
Hospitals retain the dominant share; home healthcare represents the steepest expansion trajectory as reimbursement shifts toward site-neutral payment.
Technology:
Component complexity and software validation burden determine which technology tiers attract new market entrants versus incumbent defense.
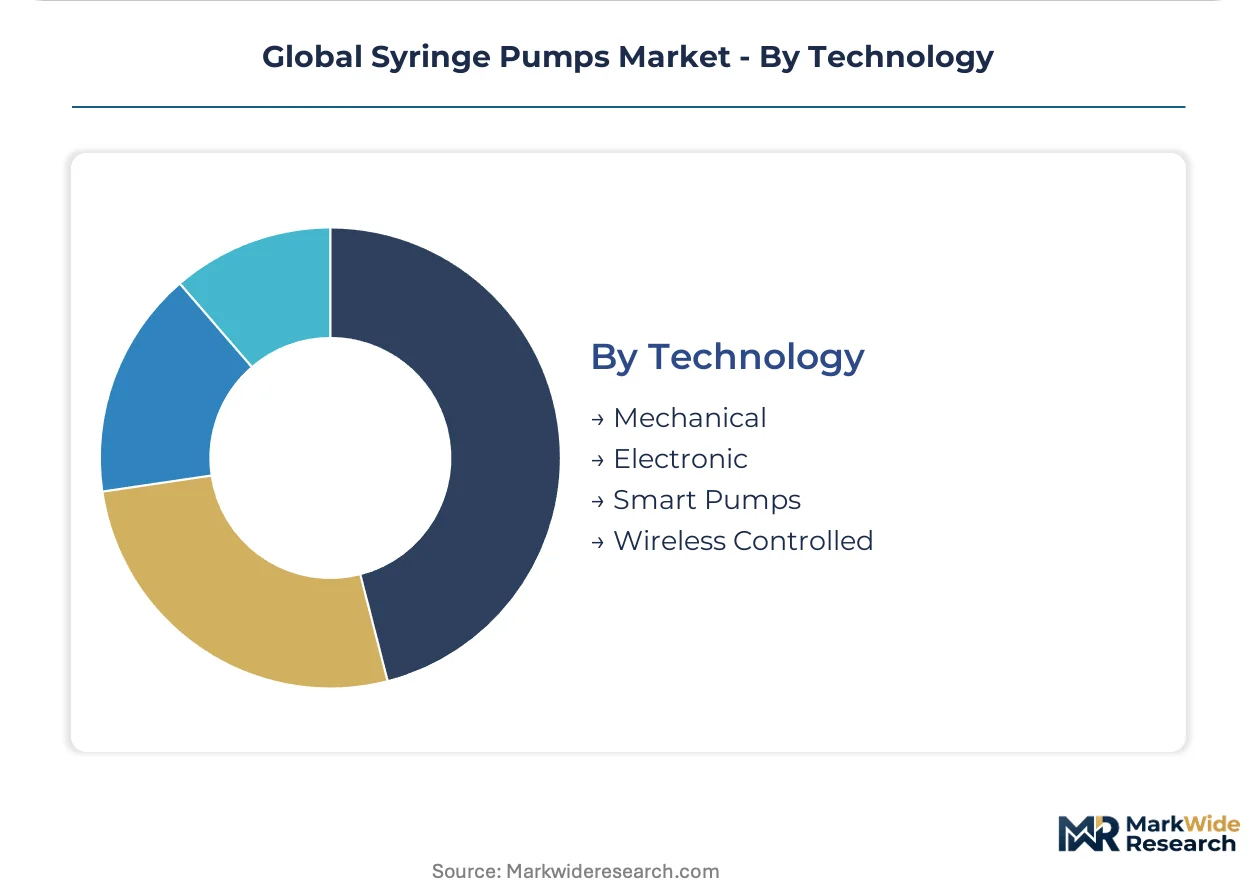
- Wireless Controlled:Centralized pump fleet management through WiFi or proprietary RF protocols enables remote alarm surveillance and dose modification. Germany's Klinikum modernization programs specify these systems for nurse station oversight of multiple wards.
- Electronic:Stepper motor precision with basic programming interfaces occupies the volume tier where manufacturing scale sustains cost leadership.
- Mechanical:Spring or screw-driven legacy designs persist in resource-constrained settings with minimal technical infrastructure.
- Smart Pumps:Dose-error reduction software with barcode medication administration integration commands premium positioning in liability-sensitive accounts.
Electronic technology anchors current shipments; wireless controlled systems are gaining share fastest as interoperability mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's university medical centers runs 40% above India's municipal procurement floors, creating a bifurcated revenue architecture that manufacturers navigate through tiered product positioning.
United States
Integrated delivery networks in Texas and Florida consolidate enterprise pump contracts spanning 20-plus facilities each. FDA 510(k) clearance timelines for software-enabled devices extend development cycles by 8-14 months. The Greater Boston cluster anchors closed-loop insulin infusion pilots bridging academic medical centers with algorithm developers.
Germany
Federal Klinikum modernization programs allocate €2.3 billion through 2028 for smart infusion infrastructure across university hospitals. EU MDR post-market surveillance through EUDAMED forces biannual clinical evidence submissions for CE marking renewal. Bavaria's Munich-Stuttgart corridor concentrates precision dosing R&D partnerships between device manufacturers and anesthesia societies.
Japan
Metropolitan hospital networks in Tokyo, Osaka, and Nagoya drive 70% of national smart pump demand through centralized prefectural procurement. PMDA software-as-medical-device guidance issued in 2023 tightens validation requirements for wireless pump fleets. The Kanto region's emergency medical centers prioritize multi-channel sepsis management systems with hemodynamic integration.
India
Municipal hospital networks in Maharashtra and Gujarat favor volumetric pumps with disposable set economics over capital-intensive smart platforms. CDSCO import licensing delays for electronic components stretch lead times to 16-22 weeks. Tamil Nadu's medical device cluster near Chennai assembles mechanical pump variants for Southeast Asian export markets.
United Kingdom
NHS trust procurement consortiums negotiate five-year pump contracts with standardized interoperability mandates across England's integrated care systems. MHRA post-Brexit recognition agreements with FDA streamline dual-market clearance pathways. The Oxford-Cambridge-London triangle hosts pilot programs for wearable ambulatory chemotherapy delivery in outpatient oncology networks.
Global Syringe Pumps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying motors, sensors, and disposable administration sets to finished device manufacturers. The market structures around three tiers: multinational infusion platform houses with enterprise service networks, regional mechanical pump fabricators competing on procurement price, and emerging connectivity software vendors licensing dose-error reduction algorithms. Consolidation pressure intensifies as hospital procurement consortiums demand single-source accountability across pump fleets and consumables.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Baxter International Inc. exemplify platform integrators anchoring long-term supply agreements through broad infusion portfolios. Fresenius Kabi AG occupies a specialized position within critical care and oncology segments where precision dosing commands premium positioning. Terumo Corporation represents manufacturing-scale leadership in standard mechanical pump categories serving cost-sensitive procurement environments.
| Leading Market Players |
|---|
| ICU Medical, Inc. |
| Terumo Corporation |
| Becton, Dickinson and Company |
| Smiths Medical |
| Medtronic plc |
| B. Braun Medical |
| Baxter International Inc. |
| Boston Scientific Corporation |
| Fresenius Kabi AG |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam maritime freight corridors transmit semiconductor and polymer cost volatility directly into syringe pump landed costs, concentrating margin pressure on manufacturers without captive component supply while enabling premium pricing for ISO 80369-6 certified systems in German university hospitals.
Pricing Analysis
The customization-premium spread separates configured-to-order smart pumps with dose-error reduction software from standard volumetric units, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. Price differentiation stems from FDA 510(k) clearance tier and geographic delivery cost, with margins tightening in India's municipal procurement due to disposable-set economics. Hospital procurement consortiums in the United States exhibit lowest price sensitivity, while Southeast Asian distributors drive hardest volume negotiations.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk planning for microcontroller-dependent pump manufacturers. Component sourcing draws from Taiwan, South Korea, and Japan for specialized stepper motors and sensors, with medical-grade polycarbonate and ABS resin feeding from petrochemical feedstock markets. Single-source vulnerability concentrates in Asian foundry capacity for infusion pump microcontrollers. Distribution runs through hospital procurement consortiums and GPO contracts in developed markets, with regional distributor networks covering ambulatory and home healthcare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The syringe pump market operates as a service-attach opportunity where cybersecurity validation contracts and preventive maintenance subscriptions expand faster than hardware unit sales, particularly around EU MDR-mandated EUDAMED compliance and FDA IEC 81001-5-1 guidance implementation.
For Market Incumbents: Entrench enterprise pump fleet contracts through backward integration into disposable administration set manufacturing, eliminating third-party supplier margin leakage. Deepen software companion development for dose-error reduction algorithms to defend against emerging connectivity vendors licensing standalone drug library platforms. Prioritize CE marking renewal investment ahead of EU MDR clinical evidence deadlines to squeeze marginal competitors from European procurement.
For New Entrants and Emerging Players: Establish a beachhead in Japan's home healthcare segment where PMDA software-as-medical-device guidance creates validation barriers incumbents navigate slowly. Target wearable ambulatory pump white space where miniaturized motor technology convergence enables subcutaneous delivery outside institutional settings. Pursue cybersecurity validation services as the go-to-market angle, offering penetration testing and software update infrastructure to hospital systems lacking in-house biomedical engineering depth.
For Investors and Strategic Acquirers: Component specialists with captive sensor and motor technology command acquisition priority as platform integrators seek supply security. Long-term viability centers on manufacturers with demonstrated EU MDR quality system maturity and recurring revenue depth from service contracts. Watch FDA 510(k) clearance compression timelines as the signal indicating which software-enabled pump developers possess regulatory navigation capabilities worth premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements through EUDAMED force portfolio rationalization and compliance investment concentration. |
| Hospital System Partnership | Integrated delivery network enterprise contracts spanning multiple facilities replace transactional equipment sales. |
| Software Companion Development | Dose-error reduction algorithms with barcode medication administration integration capture premium positioning in liability-sensitive accounts. |
| Backward Integration | In-house production of disposable administration sets eliminates supplier margin leakage and secures consumable revenue streams. |
| Reimbursement Strategy | Site-neutral payment shifts in the United States accelerate home healthcare pump adoption outside institutional settings. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR EUDAMED submissions, hospital procurement databases, and GPO contracts preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and infusion therapy clinicians. Secondary validation drew from SEC 10-K disclosures, CDSCO import licensing records, and PMDA software guidance documents. Bottom-up unit shipment estimates across product type, application, end user, and technology segments were triangulated against top-down market sizing from integrated delivery network capital expenditure disclosures.
Assumptions around EU MDR compliance timeline adherence, semiconductor supply normalization, and hospital procurement consortium consolidation velocity were held fixed across baseline scenarios while tariff exposure and polymer feedstock volatility were stress-tested. Segmentation dimensions modeled include product architecture, clinical application intensity, end-user purchasing authority concentration, and connectivity technology tier. CAGRs were derived from replacement cycle analysis and installed base expansion patterns, with wireless pump adoption curves and closed-loop infusion pilot conversion rates serving as industry-specific forecast inputs.
Stress conditions across semiconductor allocation constraints, EU MDR clinical evidence cost escalation, and Japan PMDA software validation timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers including cybersecurity guidance convergence between FDA and IEC, neuraxial connector standard enforcement intensity, and hospital procurement consortium geographic expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implant Handpiece Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
PPG Biosensors Market
Medical Devices
Depression Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Veterinary Anesthesia Equipment Market