
 Clinical Hand Hygiene Products Market | 2026-2036
Clinical Hand Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Hand Hygiene Products Market Outlook
Long-term care facilities are collapsing as the dominant buyer archetype as hospital systems reclaim volume leadership through centralized infection control budgets. GOJO Industries leverages its captive supply of dispenser hardware to lock in recurring gel and foam refills across integrated delivery networks. Ecolab sustains dominance in surgical suites through proprietary antimicrobial formulations that exceed FDA tentative final monograph standards. Medline Industries competes aggressively on institutional contracts by bundling hand hygiene products with broader personal protective equipment portfolios.
Clinical hand hygiene products encompass alcohol-based and non-alcohol-based formulations engineered for pathogen reduction on healthcare workers' hands between patient contacts, with alcohol-based gels typically containing 60-95% ethanol or isopropanol as active ingredients per WHO formulation guidelines. Their primary commercial purpose centers on breaking nosocomial transmission chains in acute and ambulatory settings. Alcohol-based gels lead volume share due to speed of use and residual efficacy, while foam formats capture premium positioning through controlled dosing mechanisms that reduce per-use waste. Wipes represent the fastest-expanding category in isolation rooms and pre-operative prepping where mechanical removal of bioburden matters alongside chemical kill.
The FDA governs over-the-counter antiseptic monographs that dictate active ingredient concentrations and efficacy labeling claims for hand sanitizers sold into clinical channels. EPA registration requirements apply to disinfectant wipes making residual surface claims, creating dual regulatory pathways that fragment vendor compliance costs. The Joint Commission survey process enforces CDC hand hygiene compliance metrics that directly shape hospital purchasing specifications and staff training investments. Stakeholders must monitor evolving FDA rulemaking on benzalkonium chloride and other alternative actives, as monograph revisions could force formulation reformulations and supply disruptions across installed dispenser bases.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins as integrated delivery networks centralize infection control spending under single-source contracts. Automated dispenser hardware now functions as a lock-in mechanism for recurring consumable revenue across multi-facility systems.
Growth Catalysts
- Joint Commission audit intensity:US acute care facilities face escalating surveyor scrutiny on CDC hand hygiene compliance metrics. Non-compliance triggers conditional accreditation status that compels capital investment in monitoring technology and staff training programs.
- Ethanol supply chain maturation:Corn-based and synthetic ethanol production capacity in the US Midwest has stabilized input costs for alcohol-based gel formulations. Regional biorefinery expansion supports just-in-time manufacturing for clinical channel distributors.
- Wipes in isolation protocols:Mechanical bioburden removal combined with chemical kill is displacing gel-only regimens in pre-operative prepping and contact precaution rooms. CDC guideline updates explicitly endorse wipe-based protocols for C. difficile containment.
Market Restraints
- Active ingredient concentration floors:FDA tentative final monographs mandate 60-95% ethanol or isopropanol thresholds that exclude lower-alcohol alternatives. Formulators seeking benzalkonium chloride pathways face unresolved efficacy data requirements and timeline uncertainty.
- Dispenser hardware fragmentation:Proprietary cartridge geometries from GOJO, Ecolab, and 3M create incompatible refill ecosystems. Hospital systems cannot switch suppliers without full infrastructure replacement, entrenching incumbent positions.
- Moisturizer additive restrictions:ECHA scrutiny of skin-conditioning agents under REACH candidate list protocols limits European formulation flexibility. Suppliers must reformulate to exclude flagged emollients, raising R&D overhead.
Strategic Opportunities
- Long-term care underpenetration:Skilled nursing facilities in the US Southeast operate with lower dispenser density per bed than acute care benchmarks. CMS quality metrics expansion creates procurement urgency for automated monitoring systems.
- Sustainability certification premiums:EPA Safer Choice and EU Ecolabel pathways enable pricing stratification for biodegradable wipe substrates and plant-derived alcohol feedstocks. German hospital procurement coalitions now mandate environmental labeling.
- AI-enabled compliance monitoring:Computer vision systems from emerging technology vendors are converging with existing dispenser networks to deliver real-time adherence dashboards. Early adoption concentrates in California health systems facing state-level HAI reduction mandates.
Industry Challenges
- Biocompatibility testing timelines:New antimicrobial actives require 18-24 month FDA pre-market notification cycles. Formulators face capital lockup during efficacy validation without revenue offset.
- Legacy dispenser base integration:RFID and Bluetooth-enabled "smart" dispensers must interface with hospital IT infrastructure running mixed-generation enterprise resource planning systems. Interoperability failures delay pilot-to-scale transitions.
- Workforce dermatitis management:Nursing staff turnover correlates with cumulative irritant contact dermatitis from high-frequency sanitizer exposure. Facilities must balance efficacy protocols with occupational health liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Hand Hygiene Products Market |
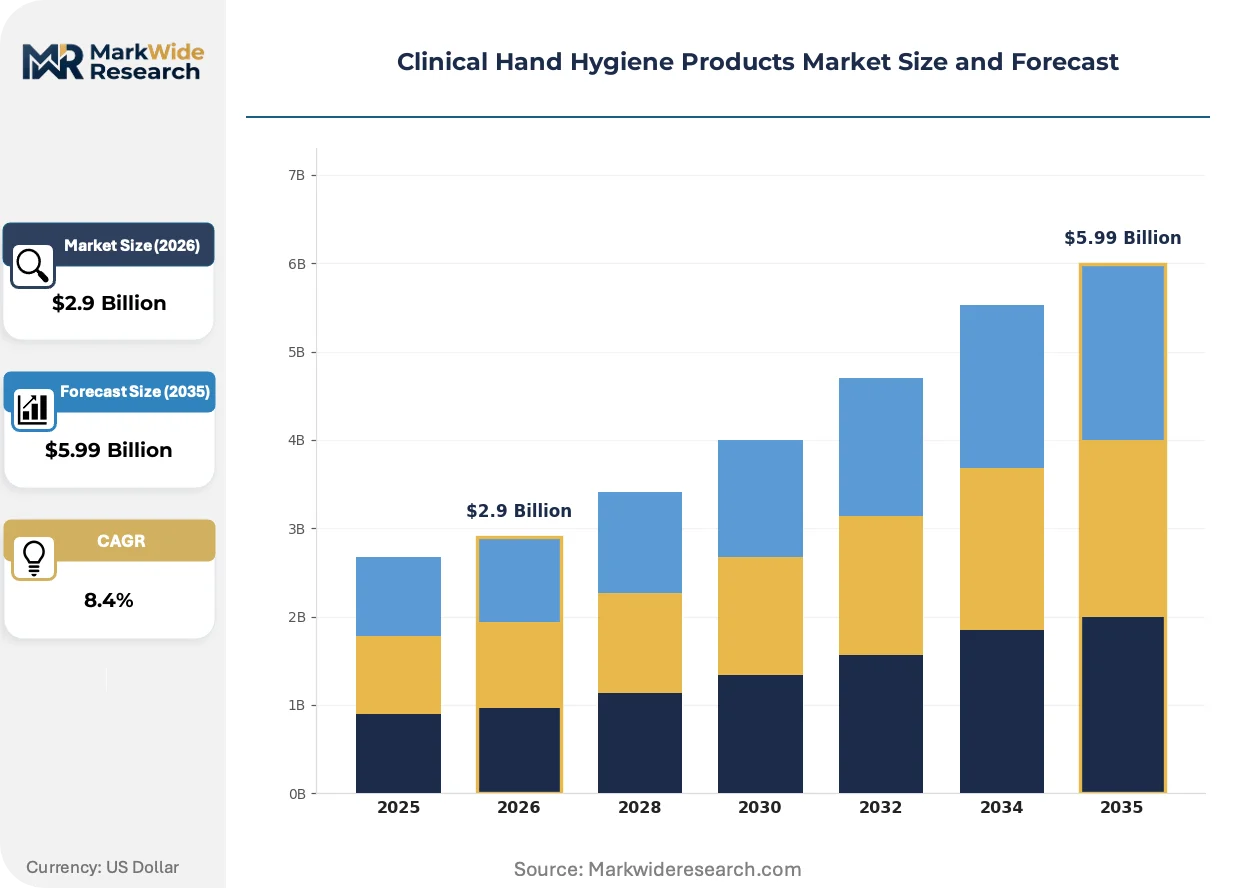
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Foams, Wipes, Sprays Application: Hospitals, Clinics, Laboratories, Home Care Formulation: Alcohol-Based, Non-Alcohol-Based, Antimicrobial, Herbal Distribution Channel: Retail, Online, Direct Sales, Institutional |
| Companies Covered | GOJO Industries, Ecolab, 3M Company, Reckitt Benckiser Group plc, Kimberly-Clark, B. Braun Melsungen AG, Procter & Gamble, Medline Industries, Diversey Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Hand Hygiene Products Market Strategic Shifts
Formulation chemistry and hardware intelligence are converging to redefine how compliance is measured, enforced, and monetized across healthcare delivery networks. Three developments dominate this transformation.
Foam-based controlled dosing is displacing traditional gel dispensers in surgical suites and intensive care units. The format delivers calibrated volumes that reduce per-use waste by 30-40% compared to gravity-fed gel systems. Hospital systems in Texas and Florida are standardizing foam infrastructure to align with value-based purchasing cost targets.
EPA registration requirements for disinfectant wipes with residual surface claims are tightening documentation burdens on manufacturers making 24-hour or 7-day pathogen suppression assertions. The agency's 2023 data call-in for quaternary ammonium compound safety profiles forced reformulation of several legacy products. Wipe suppliers serving ambulatory surgery centers face compressed timelines to submit amended master labels.
Group purchasing organizations are consolidating contract vehicles for hand hygiene products with broader infection prevention portfolios. Premier and Vizient in the US now bundle dispenser hardware, consumables, and compliance analytics under multi-year agreements. This behavior is most visible in the Midwest, where Catholic health systems leverage scale to extract performance guarantees from vendor partners.
Clinical Hand Hygiene Products Market Segmentation
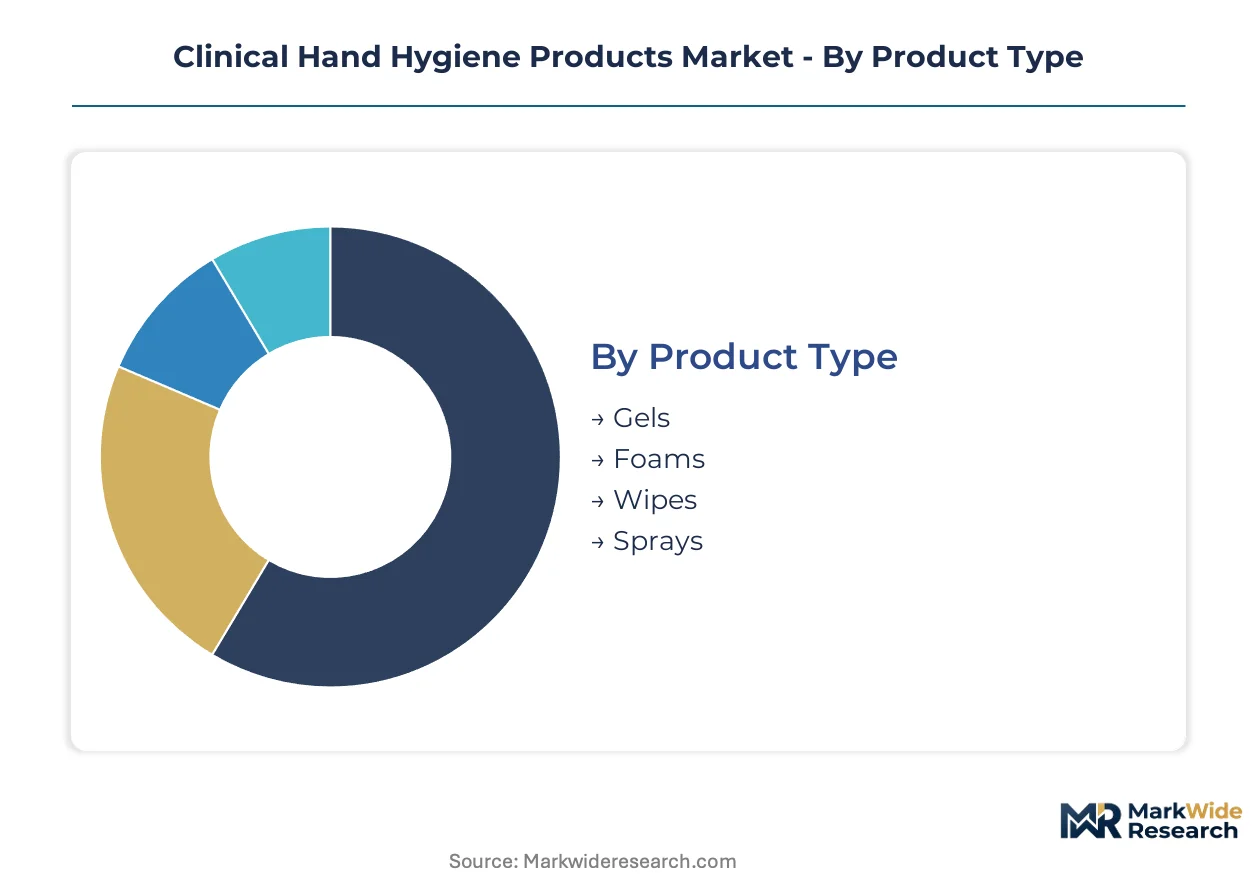
Segmentation reveals how procurement specifications fragment across care settings and how formulation chemistry drives regulatory compliance costs. Understanding these divides exposes where vendor switching costs concentrate and where new entrants can bypass entrenched dispenser networks.
Product Type:
Margin pools sit deepest in formats that bundle proprietary hardware with recurring consumable revenue.
- Gels:Gravity-fed dispensers deliver 60-95% ethanol or isopropanol formulations in viscous carriers optimized for rapid skin penetration. Demand concentrates in US acute care corridors where Joint Commission auditors measure compliance via dispenser actuation counts. Procurement departments favor gel infrastructure for its lowest per-unit consumable cost and established staff training protocols.
- Foams:Controlled-dosing pump mechanisms calibrate 0.8-1.2mL volumes per actuation, cutting waste by one-third against gel equivalents while extending refill intervals. Texas and Florida health systems are standardizing foam infrastructure to align with value-based purchasing cost targets, with surgical suites and intensive care units leading conversion.
- Wipes:Saturated nonwoven substrates combine mechanical bioburden removal with chemical kill for C. difficile protocols.
- Sprays:Aerosolized delivery suits rapid surface disinfection in ambulatory settings with limited sink access.
The dominant share belongs to Gels, while Foams is closing the gap fastest.
Application:
Volume concentration tracks infection control budget centralization and audit intensity.
- Hospitals:Integrated delivery networks command 500-2,000 bed systems under single-source contracts, with automated dispenser hardware functioning as lock-in mechanisms for recurring refill revenue. US acute care facilities face the strictest Joint Commission survey protocols, driving capital investment in compliance monitoring technology.
- Clinics:Outpatient surgery centers and specialty practices operate with lower dispenser density but higher per-staff usage rates due to rapid patient turnover.
- Laboratories:Biosafety level protocols mandate hand hygiene at containment boundaries, with research institutions prioritizing residue-free formulations that avoid PCR interference.
- Home Care:Discharge planning and hospice services represent emerging demand as post-acute infection liability shifts to community settings.
Hospitals capture the largest procurement volume, though Home Care is expanding most quickly as reimbursement models push care outside facility walls.
Formulation:
Regulatory pathway complexity determines which chemistries attract R&D investment versus commodity sourcing.
- Alcohol-Based:Ethanol and isopropanol formulations at 60-95% concentration dominate clinical procurement under WHO guidelines and FDA tentative final monographs. Corn-based and synthetic ethanol supply chains in the US Midwest have stabilized input costs, supporting just-in-time manufacturing for distributor networks.
- Non-Alcohol-Based:Benzalkonium chloride and alternative actives face unresolved FDA efficacy data requirements, creating timeline uncertainty for formulators seeking monograph compliance.
- Antimicrobial:Persistent-action chemistries target surgical hand scrubs with extended residual protection.
- Herbal:Plant-derived extracts serve niche demand in sustainability-focused European procurement coalitions.
Alcohol-Based formulations hold entrenched clinical preference, while Non-Alcohol-Based alternatives are gaining regulatory attention as resistance concerns mount.
Distribution Channel:
Channel selection reflects contract scale and technical service requirements.
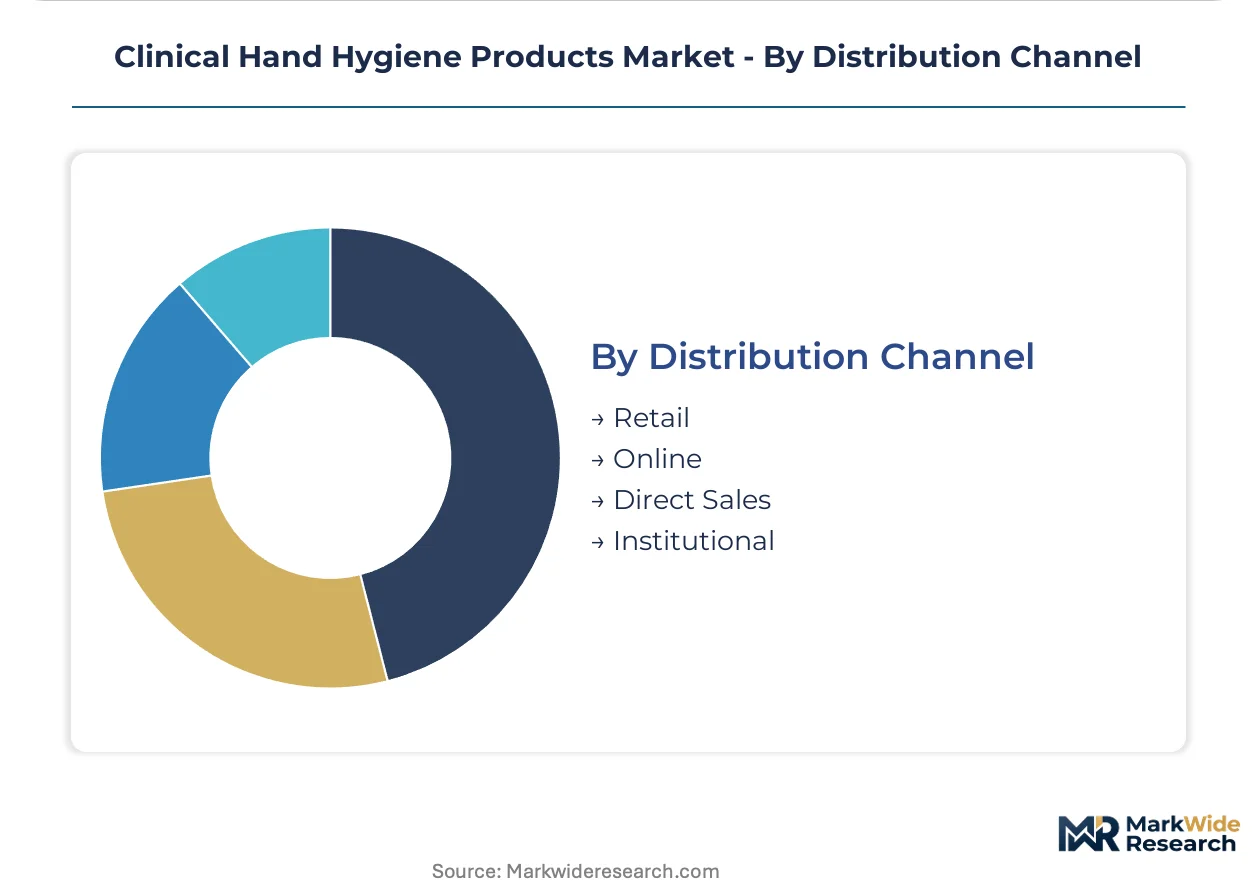
- Direct Sales:Manufacturer field representatives negotiate multi-year agreements with integrated delivery networks, bundling dispenser hardware installation with compliance analytics and staff training. Premier and Vizient in the US consolidate these contracts with performance guarantees.
- Institutional:Group purchasing organizations aggregate demand across Catholic health systems and regional cooperatives, extracting volume discounts through standardized specifications.
- Retail:Pharmacy and medical supply stores serve small-practice and home care segments with limited procurement sophistication.
- Online:E-commerce platforms capture ambulatory surgery center replenishment and emergency stockpiling demand.
Direct Sales commands the highest contract value, yet Institutional channels are scaling fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-based manufacturers export clinical hand hygiene formulations to health systems across Canada, Mexico, and Latin America, with distribution networks anchored in Midwest ethanol production corridors and coastal logistics hubs.
United States
Joint Commission audit intensity drives procurement centralization across integrated delivery networks spanning 500-2,000 beds. FDA tentative final monographs govern alcohol concentration thresholds for clinical channel sales. Texas and Florida health systems are standardizing foam infrastructure to align with value-based purchasing cost targets.
Germany
Hospital procurement coalitions mandate EPA Safer Choice and EU Ecolabel certification for biodegradable wipe substrates. ECHA scrutiny of skin-conditioning agents under REACH candidate list protocols limits formulation flexibility. The Rhine-Ruhr industrial cluster hosts concentrated manufacturing of dispenser hardware and controlled-dosing pump mechanisms.
China
Domestic biorefinery expansion supports synthetic ethanol production for alcohol-based gel formulations serving Asia-Pacific clinical channels. NMPA registration requirements align with WHO formulation guidelines for pathogen reduction claims. The Yangtze River Delta region concentrates contract manufacturing for nonwoven wipe substrates used in isolation protocols.
Japan
Acute care facilities prioritize residue-free formulations that avoid PCR interference in laboratory-adjacent clinical settings. METI standards for medical device adjacent products shape dispenser hardware specifications. The Kansai region around Osaka hosts specialized production of antimicrobial surgical hand scrubs with extended residual protection.
United Kingdom
NHS procurement frameworks consolidate infection control spending under single-source contracts with performance guarantees. MHRA guidance on biocidal product authorization creates compliance timelines for alternative active ingredients. The Southeast England corridor around London anchors demand for automated dispenser programs with compliance analytics integration.
Clinical Hand Hygiene Products Market Competitive Environment
Player mix skews toward diversified hygiene conglomerates with captive dispenser hardware ecosystems. Market structure exhibits tiered consolidation, with three to five vendors commanding integrated delivery network contracts and a long tail of regional formulators serving ambulatory and long-term care segments. Strategic archetypes include hardware-locked consumable suppliers, compliance analytics bundlers, and private-label contract manufacturers. Dominant competitive moves involve backward integration into ethanol production and strategic partnerships with group purchasing organizations.
Within the hardware-locked tier, GOJO Industries and Ecolab exemplify the captive dispenser ecosystem model, with proprietary cartridge geometries creating incompatible refill networks that entrench incumbent positions. 3M Company occupies a position bridging industrial and clinical channels, leveraging scale advantages across multiple healthcare verticals. These three anchors represent distinct strategic postures: dispenser hardware lock-in, surgical suite formulation dominance, and diversified healthcare portfolio breadth.
| Leading Market Players |
|---|
| GOJO Industries |
| Ecolab |
| 3M Company |
| Reckitt Benckiser Group plc |
| Kimberly-Clark |
| B. Braun Melsungen AG |
| Procter & Gamble |
| Medline Industries |
| Diversey Holdings |
| Others |
Value Chain & Pricing Dynamics
Multi-year group purchasing organization contracts lock in ethanol supply commitments and dispenser hardware pricing for integrated delivery networks across the United States. These arrangements secure volume visibility for corn-based and synthetic ethanol producers while insulating hospital procurement departments from spot market volatility in Midwest biorefinery corridors.
Pricing Analysis
Current-generation foam dispensers with controlled-dosing mechanisms command 15-25% premiums over prior-generation gravity-fed gel systems due to waste reduction guarantees and extended refill intervals. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA Safer Choice certification status and bundled compliance analytics. Cost compression in standard-tier gel refills is intensifying because group purchasing organization consolidation extracts volume discounts from regional formulators. Ambulatory surgery centers exhibit highest price sensitivity due to limited infection control budgets, while integrated delivery networks prioritize total cost-of-ownership metrics over per-unit pricing.
Supply Chain Analysis
Strategic stockpiling of nonwoven wipe substrates and pump dispenser components dominates procurement strategy following pandemic-era supply disruptions. Manufacturing concentration centers on the United States for ethanol formulations, Germany for controlled-dosing pump mechanisms, and China for saturated wipe substrates. Raw material dependencies include corn-derived ethanol, synthetic isopropanol, and quaternary ammonium compounds for residual-claim wipes. Single-source vulnerability in proprietary cartridge geometries from entrenched hardware vendors creates switching cost barriers. Distribution runs through Midwest ethanol production corridors to coastal logistics hubs serving acute care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as integrated delivery networks consolidate infection control spending under single-source contracts spanning 500-2,000 bed systems. This procurement centralization fragments vendor access and compresses margins for suppliers lacking captive dispenser ecosystems.
For Market Incumbents: Compound dispenser hardware lock-in with predictive refill logistics to defend recurring revenue streams against emerging private-label contract manufacturers. Backward integration into ethanol production secures input cost stability as Midwest biorefinery capacity expands. Prioritize AI-enabled compliance monitoring partnerships to differentiate beyond commodity formulation supply.
For New Entrants and Emerging Players: Compliance analytics service-layer gaps in long-term care facilities present white-space targets where automated dispenser density lags acute care benchmarks. Skilled nursing facilities in the US Southeast operate with minimal monitoring infrastructure and rising CMS quality metrics pressure. Pursue direct sales relationships with regional cooperatives outside Premier and Vizient contract umbrellas.
For Investors and Strategic Acquirers: Capital is best deployed toward private-label contract manufacturers with FDA-registered formulation capabilities and flexible packaging lines serving ambulatory surgery center demand. Long-term viability hinges on regulatory pathway diversification beyond alcohol-based monographs. Watch FDA rulemaking timelines on benzalkonium chloride efficacy data requirements as inflection indicator for alternative active ingredient commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Production | Captive supply from Midwest biorefineries stabilizes input costs against commodity volatility. |
| AI-Enabled Compliance Monitoring Partnership | Computer vision integration with dispenser networks addresses California HAI reduction mandates. |
| EPA Safer Choice Certification Pathway | German hospital procurement coalitions now mandate environmental labeling for wipe substrates. |
| Long-Term Care Facility Expansion | Skilled nursing underpenetration creates urgency as CMS quality metrics broaden scope. |
| Non-Alcohol Formulation R&D Investment | Alternative active development hedges against FDA monograph concentration floor restrictions. |
Study Parameters
Initial hypotheses were tested against primary input from hospital procurement directors, infection prevention specialists, GPO contracts managers, and dispenser hardware engineers and refined through secondary validation. Hospital procurement databases, FDA tentative final monograph dockets, EPA registration filings, and group purchasing organization contract disclosures supplied quantitative anchors. Bottom-up demand modeling across care settings triangulated with top-down ethanol production capacity analysis.
Variance in projected outcomes decomposes across formulation chemistry segments, dispenser hardware generations, and regional regulatory clusters. Segmentation dimensions modeled include product format, care setting, active ingredient pathway, and distribution channel structure. CAGRs derive from installed base expansion rates and per-bed consumption intensity trajectories. Ethanol supply chain maturation and Joint Commission audit protocol evolution serve as key forecast sensitivity inputs.
Underlying assumptions cover sustained Joint Commission enforcement intensity, stable Midwest ethanol production economics, and unresolved FDA timelines for alternative active monographs, with deviation risk concentrated in regulatory pathway disruptions and biorefinery capacity constraints. Revision becomes warranted when benzalkonium chloride efficacy data requirements receive definitive FDA resolution or when group purchasing organization consolidation accelerates beyond current contract restructuring patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Surgical Site Infections Market
Infection Control
Air Sanitizer Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Sterilization Technologies Market
Infection Control
Infection Control Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Perianal Infection Treatment Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Denture Disinfectants Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Sterilization Tunnel Market