
 Europe Open System MRI Market | 2026-2036
Europe Open System MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Open System MRI Market Foresight
The capital-intensity divergence between superconducting coil manufacturers and permanent-magnet assemblers is redrawing competitive boundaries across Europe. Siemens Healthineers leverages its cryogenics supply chain to dominate high-field open configurations, while Esaote anchors its position in extremity-dedicated systems through Italian manufacturing scale. Philips Healthcare navigates the reimbursement complexity of multi-country hospital procurement by sustaining a direct-service footprint in France, Germany, and the Netherlands.
Europe Open System MRI denotes diagnostic imaging equipment employing non-enclosed magnet architectures, typically operating at field strengths below 1.0 Tesla for permanent-magnet designs or up to 1.5 Tesla in superconducting variants, engineered to eliminate the cylindrical tunnel that induces patient claustrophobia. These systems serve orthopedic, neurological, and pediatric applications where patient comfort directly impacts scan completion rates and clinical throughput. Permanent Magnet Technology occupies the largest installed base across Southern European clinics constrained by infrastructure budgets, while Superconducting Technology leads margin pools in Northern European academic hospitals pursuing spectroscopic and functional imaging protocols. The Application dimension shows Orthopedic Imaging generating the highest procedure volume, though Neurological Imaging commands premium pricing where open systems enable intraoperative guidance.
The EU Medical Device Regulation (MDR) and CE marking framework administered by notified bodies in Germany, the Netherlands, and Ireland are extending clinical evaluation requirements for open-system modifications, compressing time-to-market for incremental hardware upgrades. EMA guidance on diagnostic quality benchmarks indirectly shapes national procurement specifications, particularly in France where ANSM enforces post-market surveillance obligations. Stakeholders must monitor how the EU AI Act intersects with emerging embedded image-reconstruction algorithms, as compliance costs for algorithmic transparency could restructure vendor R&D priorities.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product lifecycles for open-architecture MRI manufacturers, forcing simultaneous compliance upgrades across electromagnetic safety protocols and clinical evaluation documentation while pediatric diagnostic networks accelerate scanner deployments.
Growth Catalysts
- Claustrophobia-tolerant patient flows:Bariatric and pediatric diagnostic centers in Germany, France, and the United Kingdom are prioritizing open-architecture installations to reduce scan abandonment rates and improve clinical throughput.
- EU MDR conformity harmonization:Streamlined CE marking pathways for open-system modifications are reducing regulatory friction for hardware upgrades across notified bodies in Germany, the Netherlands, and Ireland.
- Permanent-magnet cost accessibility:Southern European clinics constrained by infrastructure budgets are expanding installed bases of sub-1.0 Tesla systems for orthopedic extremity imaging.
Market Restraints
- Superconducting helium dependency:Cryogenic supply chain concentration in Northern European academic hospitals exposes procurement to helium price volatility and sourcing bottlenecks.
- Field-strength performance ceiling:Open-architecture designs face inherent signal-to-noise ratio limitations below 1.5 Tesla that constrain functional MRI and spectroscopic protocols.
- CE marking timeline elongation:Extended clinical evaluation requirements under EU MDR are delaying time-to-market for incremental hardware modifications by 12-18 months.
Strategic Opportunities
- Intraoperative neurological guidance:Open systems enabling real-time surgical navigation are penetrating neurosurgical suites in French and German academic medical centers at premium pricing tiers.
- EU AI Act algorithmic transparency:Embedded image-reconstruction software compliance requirements are creating first-mover advantages for vendors with pre-validated machine-learning pipelines.
- Direct-service procurement consolidation:Multi-country hospital networks in the Netherlands and Belgium are unbundelling equipment and service contracts to favor vendors with captive technical workforces.
Industry Challenges
- Cryogenics technician scarcity:Specialized superconducting coil maintenance expertise is concentrating among aging workforces in Germany and Switzerland, constraining service response times.
- Legacy PACS integration friction:Open-system MRI deployments face interoperability failures with proprietary radiology information systems prevalent in mid-sized French hospital networks.
- Post-market surveillance documentation:ANSM-mandated vigilance reporting for French installations is absorbing clinical engineering resources previously allocated to uptime optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Open System MRI Market |
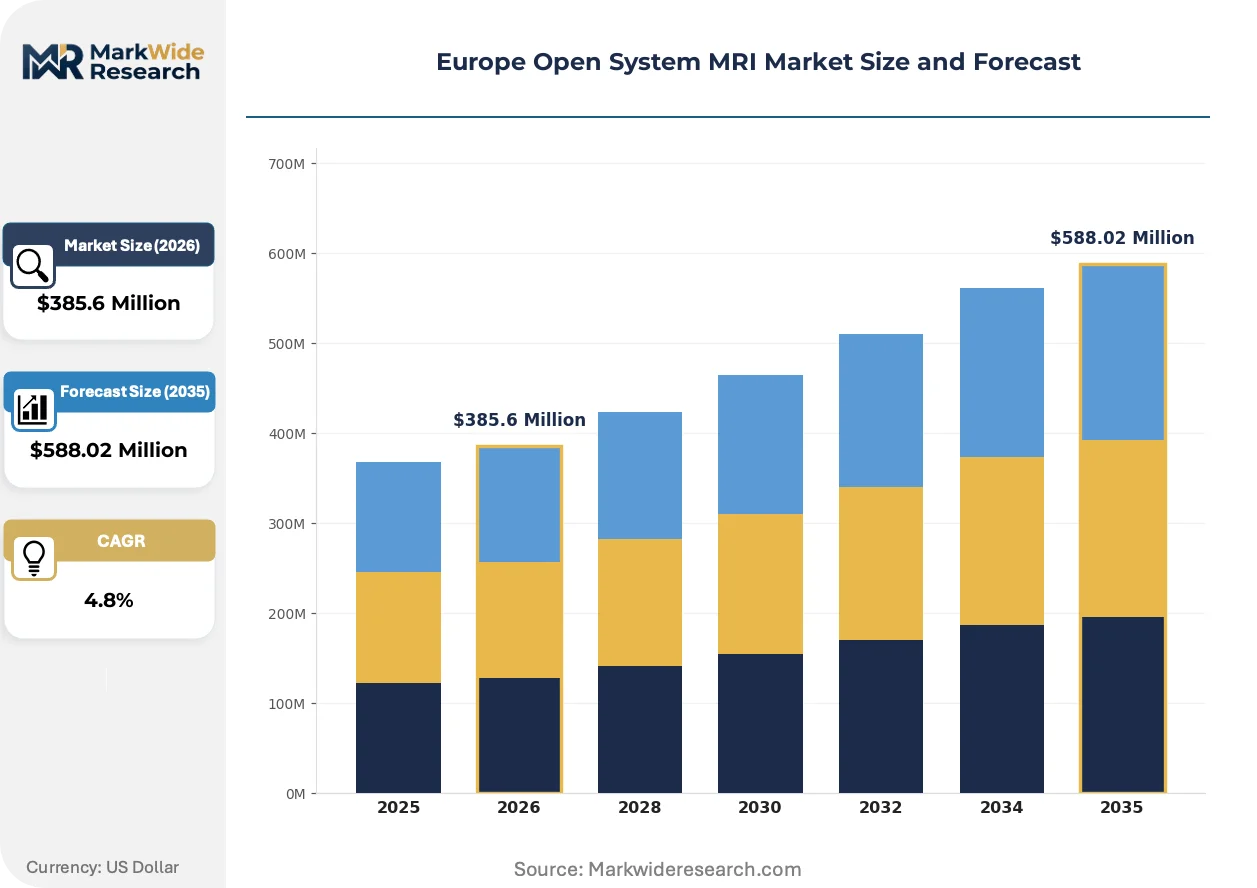
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Imaging Centers, Research Institutions, Clinics Technology: Superconducting Technology, Permanent Magnet Technology, Hybrid Systems, Electrical Systems Application: Orthopedic Imaging, Neurological Imaging, Cardiovascular Imaging, Oncology Imaging |
| Companies Covered | Siemens Healthineers, Philips Healthcare, GE Healthcare, Esaote, FUJIFILM, Canon Medical Systems, Hitachi Healthcare, Fonar Corporation, Koninklijke Philips, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Open System MRI Market Shifts & Advancements
Permanent-magnet assemblies are gaining ground across Southern European budget-constrained clinics while regulatory pressure on embedded software reshapes vendor development priorities and procurement patterns fragment along service-capability lines.
Permanent-magnet open MRI systems operating at 0.2-0.5 Tesla are supplanting refurbished high-field closed scanners in Italian and Spanish outpatient orthopedic networks. These systems sacrifice spectroscopic capability for operational simplicity and eliminated cryogen dependency. The shift is compressing addressable margins for superconducting vendors while expanding procedure volumes in price-sensitive segments.
The EU AI Act intersects with EMA diagnostic quality benchmarks to impose algorithmic transparency requirements on embedded image-reconstruction software. Vendors must now document training data provenance and decision-logic interpretability for CE-marked devices. French procurement specifications under ANSM guidance are already embedding these compliance thresholds into tender evaluations.
Hospital procurement departments are fragmenting equipment-acquisition decisions from long-term service commitments. Dutch and Belgian multi-site networks now unbundle these contracts to optimize total cost of ownership across 10-year lifecycles. This behavioral shift favors vendors with direct technical workforces over third-party service intermediaries in competitive evaluations.
Europe Open System MRI Market Segmentation
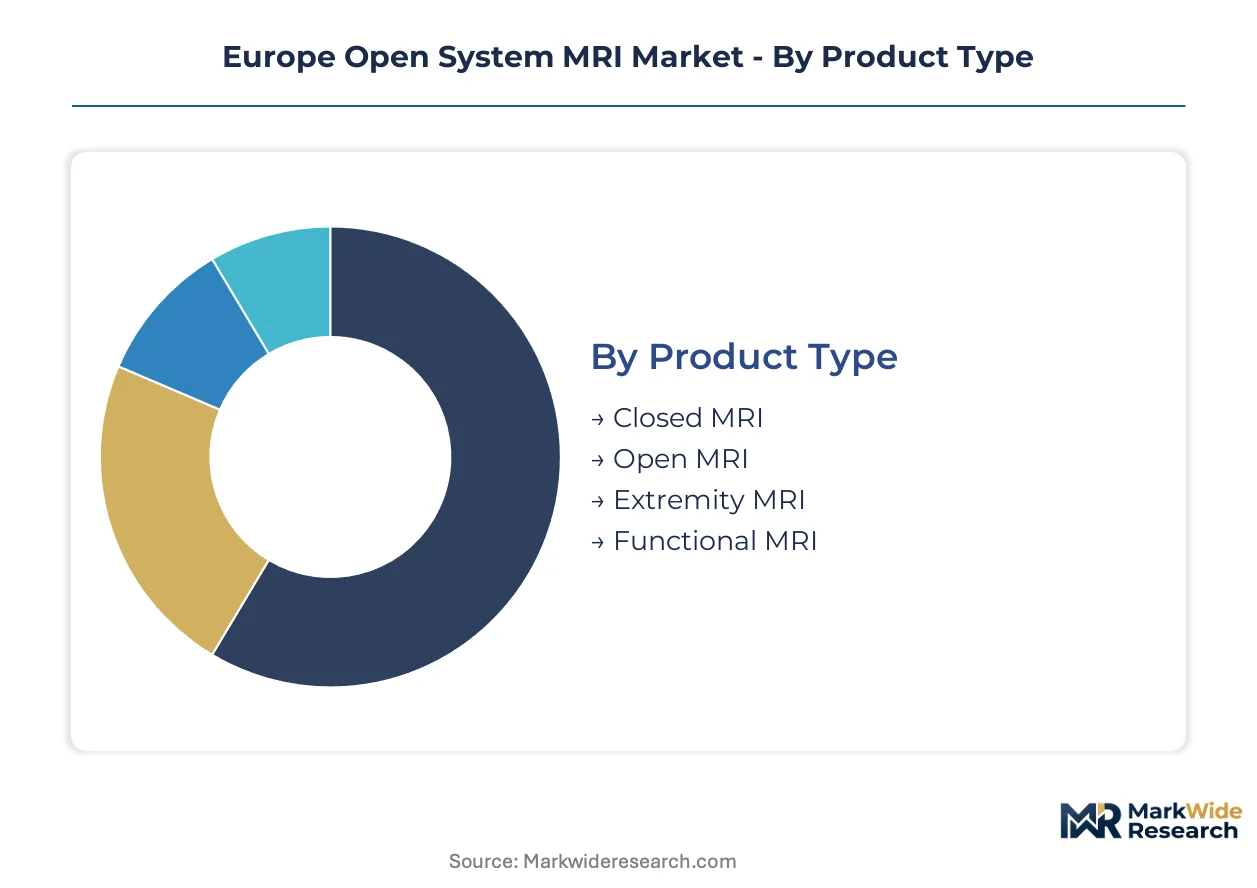
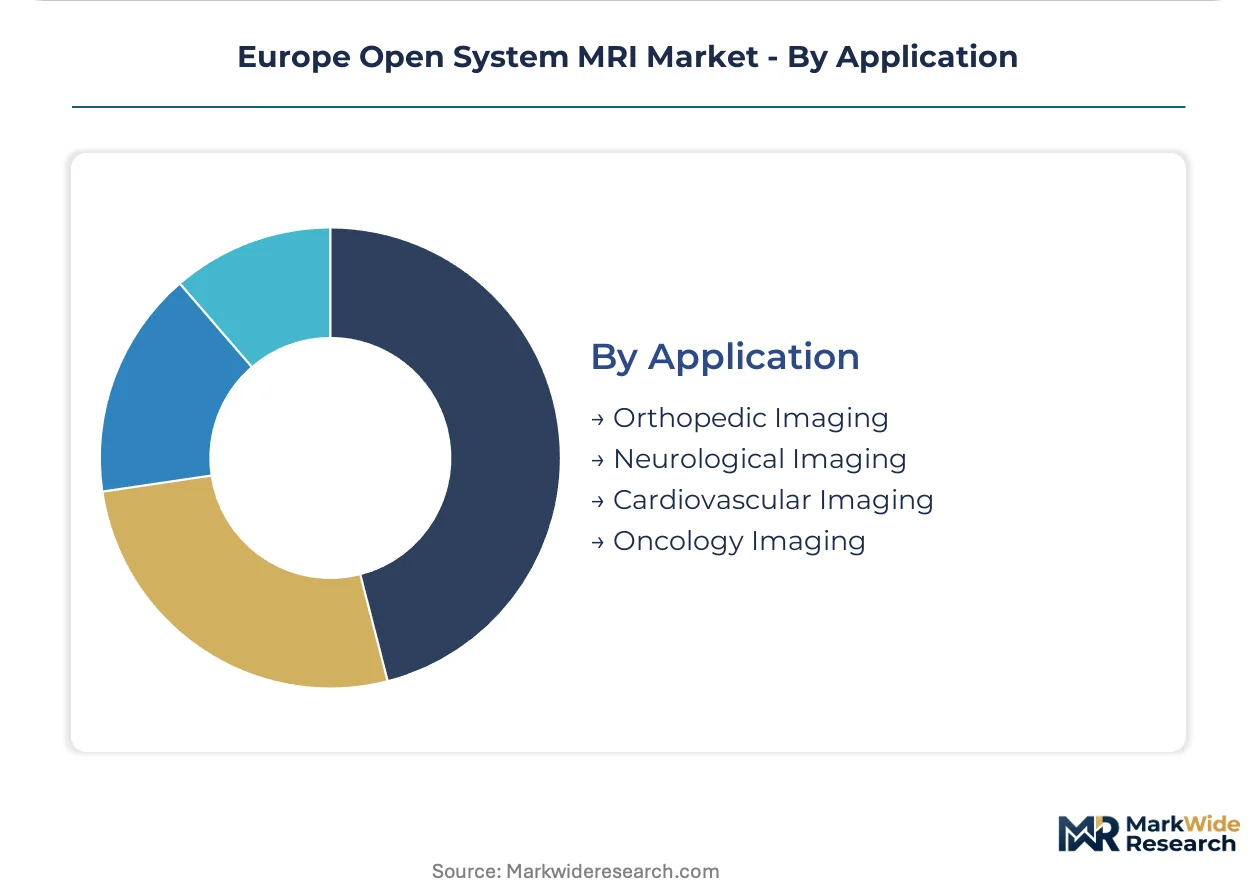
Segmentation reveals how procurement priorities diverge across European healthcare systems. Budget constraints, clinical specialization, and regulatory compliance requirements reshape competitive positioning differently across each dimension.
Product Type:
Margin pools concentrate in configurations that balance patient throughput with capital efficiency, with open-architecture designs commanding premium positioning in claustrophobia-sensitive workflows.
- Open MRI:Non-enclosed magnet architectures operate below 1.5 Tesla to eliminate cylindrical tunnel confinement. German, French, and UK pediatric diagnostic centers prioritize these installations to reduce scan abandonment rates among bariatric and anxious patient populations.
- Extremity MRI:Dedicated limb-imaging systems employ compact permanent-magnet designs for orthopedic extremity scans. Southern European outpatient clinics in Italy and Spain favor these for operational simplicity and eliminated cryogen dependency.
- Closed MRI:Traditional enclosed-bore superconducting systems deliver maximum field strength for spectroscopic protocols.
- Functional MRI:Specialized configurations enabling real-time brain activity mapping during cognitive tasks.
Open MRI holds installed capacity. Extremity MRI is rotating up the share rankings.
End User:
Procurement authority fragments across institutional types with diverging capital cycles and clinical mission priorities.
- Hospitals:Acute-care networks with multi-modality imaging departments drive volume concentration. Northern European academic medical centers in Germany and France prioritize superconducting open systems for intraoperative neurological guidance at premium pricing tiers.
- Imaging Centers:Outpatient-focused facilities optimize throughput per square meter. Dutch and Belgian multi-site networks unbundle equipment and service contracts to favor vendors with captive technical workforces across 10-year lifecycles.
- Research Institutions:University-affiliated facilities pursuing spectroscopic and functional imaging protocols.
- Clinics:Smaller facilities constrained by infrastructure budgets and space limitations.
Hospitals anchor procurement volume. Imaging centers are expanding fastest in the Netherlands and Belgium.
Technology:
Cost-tier differentiation separates cryogen-dependent superconducting architectures from maintenance-light permanent-magnet alternatives.
- Superconducting Technology:High-field designs up to 1.5 Tesla require liquid helium cooling and specialized technician expertise. German and Swiss academic hospitals concentrate procurement here despite helium price volatility and aging cryogenics workforces constraining service response times.
- Permanent Magnet Technology:Sub-1.0 Tesla assemblies eliminate cryogen dependency entirely. Italian and Spanish orthopedic networks expand these installations where infrastructure budgets limit capital deployment and operational simplicity outweighs spectroscopic capability sacrifice.
- Hybrid Systems:Configurations combining superconducting and permanent-magnet elements for specialized workflows.
- Electrical Systems:Emerging architectures employing advanced electromagnetic coil designs without permanent magnets.
Permanent Magnet Technology leads Southern European installed base. Superconducting Technology retains Northern European margin concentration.
Application:
Procedure volume and pricing power diverge sharply between high-frequency orthopedic workflows and premium neurological interventions.
- Neurological Imaging:Brain and spinal cord diagnostics command premium pricing where open systems enable intraoperative surgical navigation. French and German academic medical centers deploy these configurations in neurosurgical suites for real-time guidance during tumor resections.
- Orthopedic Imaging:Musculoskeletal diagnostics generate highest procedure volumes across European healthcare systems. Extremity-dedicated open systems in Italian and Spanish outpatient networks capture this demand with permanent-magnet simplicity.
- Cardiovascular Imaging:Cardiac structure and function assessment requiring specialized coil configurations.
- Oncology Imaging:Tumor detection and staging applications across body regions.
Orthopedic Imaging dominates procedure counts. Neurological Imaging commands steepest expansion trajectory in academic settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German academic medical centers while Italian outpatient networks compete on permanent-magnet cost efficiency. This asymmetry shapes procurement fragmentation across Northern and Southern European healthcare systems.
Germany
Academic hospitals in Berlin and Munich drive demand for superconducting open systems enabling intraoperative neurological guidance. The EU Medical Device Regulation tightens conformity assessment through notified bodies in Germany, extending clinical evaluation timelines. Bavaria's medical technology cluster around Erlangen anchors Siemens Healthineers' cryogenics supply chain dominance.
France
Pediatric diagnostic centers in Paris and Lyon prioritize claustrophobia-tolerant open-architecture scanners to reduce scan abandonment rates. ANSM enforces post-market surveillance obligations that absorb clinical engineering resources. The Île-de-France region concentrates neurosurgical suites deploying premium-priced open systems for real-time tumor resection guidance.
United Kingdom
Bariatric patient populations in London and Manchester diagnostic networks accelerate open-system installations. NHS procurement frameworks emphasize patient-centric imaging workflows with unbundled equipment and service contracts. The Greater Manchester health innovation cluster tests embedded AI reconstruction algorithms under emerging EU AI Act transparency requirements.
Italy
Orthopedic outpatient clinics in Milan and Rome expand permanent-magnet installations constrained by infrastructure budgets. CE marking pathways for sub-1.0 Tesla systems streamline regulatory access compared to superconducting variants. Lombardy's manufacturing base supports Esaote's extremity-dedicated system production for Southern European price-sensitive segments.
Netherlands
Multi-site hospital networks in Amsterdam and Rotterdam unbundle procurement to optimize total cost of ownership across 10-year lifecycles. Dutch regulators align with EMA diagnostic quality benchmarks shaping tender evaluations. The Randstad medical technology corridor favors vendors with captive technical workforces over third-party service intermediaries.
Europe Open System MRI Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European open system MRI market. The vendor base concentrates around superconducting specialists leveraging cryogenics expertise and permanent-magnet assemblers competing on operational simplicity. Two strategic archetypes dominate: integrated healthcare conglomerates with captive supply chains and specialized imaging equipment manufacturers with regional manufacturing scale. Competitive moves center on direct-service footprint expansion and algorithmic transparency pre-validation for EU AI Act compliance.
Among Germany-based healthcare conglomerates, Siemens Healthineers anchors the superconducting technology tier through cryogenics supply chain control. Philips Healthcare occupies a position spanning both premium and mid-market segments through its direct-service presence across France, Germany, and the Netherlands. Esaote exemplifies the specialized manufacturer archetype, leveraging Italian manufacturing scale to dominate extremity-dedicated permanent-magnet systems across Southern European budget-constrained clinics.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Philips Healthcare |
| GE Healthcare |
| Esaote |
| FUJIFILM |
| Canon Medical Systems |
| Hitachi Healthcare |
| Fonar Corporation |
| Koninklijke Philips |
| Others |
Supply & Pricing Matrix
CE marking pathways administered by German and Dutch notified bodies gate both vendor qualification and price differentiation simultaneously, compressing margins for non-compliant hardware modifications while rewarding pre-certified configurations with procurement preference in multi-country hospital networks.
Pricing Analysis
Configured-to-order pricing for superconducting open systems commands a 40-60% premium over standard permanent-magnet configurations across Northern European academic hospitals. Price differentiation hinges on field-strength tier and bundled after-sales service contracts, with Dutch multi-site networks unbundling these elements to optimize total cost of ownership. Pricing pressure stems from helium cost volatility constraining superconducting margins, while Southern European outpatient clinics exhibit highest price sensitivity due to infrastructure budget constraints.
Supply Chain Analysis
Inventory lead times for superconducting coil assemblies extend 18-24 months due to cryogenic component scarcity concentrated in Germany and Switzerland. Manufacturing draws from rare-earth magnet suppliers in China, precision coil winders in Japan, and helium sourcing networks anchored in Qatar and Algeria. Single-source vulnerability in liquid helium logistics exposes procurement to commodity price spikes. Distribution runs through direct-service footprints favored in Dutch and Belgian hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Open System MRI Market is entering a cyclical recovery phase driven by pediatric diagnostic network expansion and EU MDR compliance-driven replacement cycles across Western European hospital systems.
For Market Incumbents: Secure cryogenics technician pipelines through apprenticeship partnerships with Bavarian and Swiss technical institutes to counter aging workforce attrition. Deepen backward integration into permanent-magnet assemblies to defend margin position against Esaote's Italian manufacturing scale in Southern European price-sensitive segments.
For New Entrants and Emerging Players: CE marking fast-tracks for sub-1.0 Tesla extremity-dedicated systems offer the most penetrable entry vector into Italian and Spanish orthopedic outpatient networks. Target permanent-magnet simplicity as the go-to-market angle, emphasizing eliminated helium dependency and reduced clinical engineering overhead in procurement evaluations.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by elevating algorithmic transparency capabilities to strategic priority status. Long-term viability favors targets with pre-validated machine-learning pipelines for embedded image reconstruction. Watch ANSM-mandated post-market surveillance documentation burdens as the signal indicating which vendors possess compliant clinical engineering infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Streamlined conformity assessment through German notified bodies accelerates hardware upgrade deployment timelines. |
| Hospital System Partnership | Direct-service footprint expansion in Netherlands and Belgium captures unbundled procurement contract preferences. |
| Software Companion Development | Embedded AI reconstruction algorithms compliant with EU AI Act transparency requirements command tender evaluation premiums. |
| Backward Integration | In-house permanent-magnet assembly production defends margin position against Southern European cost competitors. |
| Reimbursement Strategy | Alignment with EMA diagnostic quality benchmarks shapes French ANSM procurement specification compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU MDR notified body filings, EMA diagnostic quality guidance, and hospital procurement database records across Germany, France, and the Netherlands. Primary interviews engaged biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at superconducting and permanent-magnet manufacturers. Secondary sources included CE marking registries, ANSM vigilance reports, and CMS-equivalent European reimbursement filings. Bottom-up installed base estimates triangulated against top-down capital expenditure forecasts from acute-care network disclosures.
Segmentation dimensions modeled span product architecture, technology type, application specialty, and end-user institutional category across the projection horizon. CAGRs derive from procedure volume trajectories weighted by field-strength tier pricing and service contract attach rates. Forecast inputs incorporated helium price elasticity coefficients and EU AI Act compliance cost assumptions for embedded software modules.
Decision-makers should treat outputs as directional under sustained EU MDR timeline compression and pediatric diagnostic center capital allocation continuity; material deviation in regulatory enforcement intensity or helium supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
South America CT Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Digital Pathology Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
PACS and RIS Market