
 Motorized Prosthesis Market | 2026-2036
Motorized Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Motorized Prosthesis Market Analysis
Germany's industrial corridor for precision mechatronics is fragmenting as multiple competitors establish localized assembly for motorized prosthetic components. Ottobock anchors European distribution through its long-standing rehabilitation clinic partnerships. Össur hf. competes in North America with carbon-fiber composite expertise for athletic-performance limbs. Faulhaber Group leverages miniature motor manufacturing to supply drive systems across multiple device OEMs.
A motorized prosthesis integrates servo motors, sensor arrays, and microprocessor-controlled joints to replicate or augment natural human limb movement with programmable gait patterns and grip force modulation. These devices restore mobility and dexterity for amputees across medical rehabilitation and daily living contexts. Lower-limb bionic systems dominate current volume due to higher incidence of dysvascular and trauma-related amputations, while neural-interface technology represents the fastest-expanding margin pool as signal-processing algorithms improve. Rehabilitation centers remain the primary channel for initial fitting and calibration, though home-care delivery models are gaining traction for maintenance and software updates.
The FDA's breakthrough device program compresses timelines for novel neural-control systems, while the EU Medical Device Regulation imposes stricter clinical-evidence requirements on electromechanical limb manufacturers seeking CE marking. Japan's Ministry of Economy, Trade and Industry (METI) coordinates national insurance reimbursement tiers that directly shape patient access to microprocessor-enabled knees versus passive mechanical alternatives. Stakeholders must monitor how reimbursement harmonization across Germany, Japan, and the United States affects pricing power for premium bionic systems versus standard electromechanical configurations.
Market Dynamics
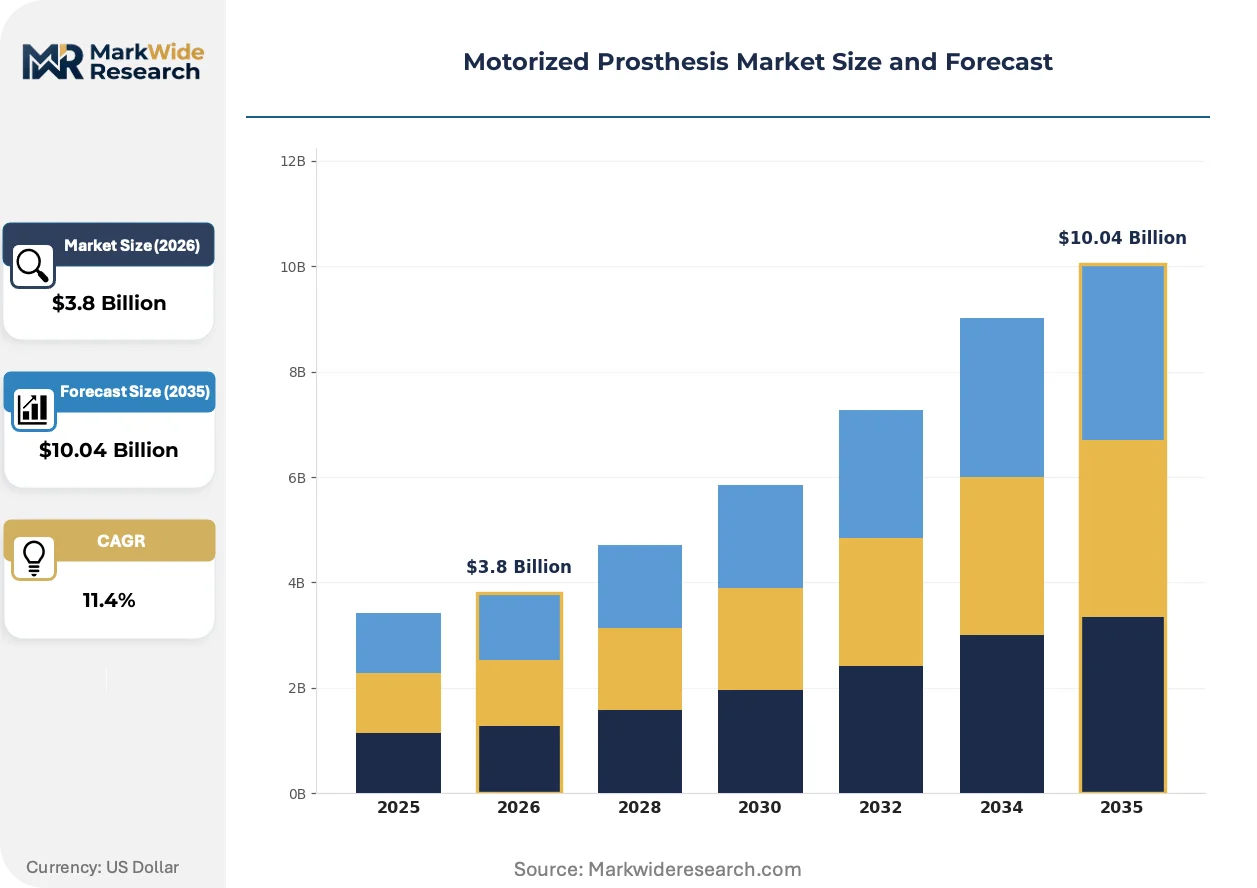
The motorized prosthesis market is experiencing intensifying pressure from reimbursement policy divergence across major healthcare systems, as payers in Japan, Germany, and the United States apply divergent evidentiary standards for microprocessor-enabled limb coverage.
Growth Catalysts
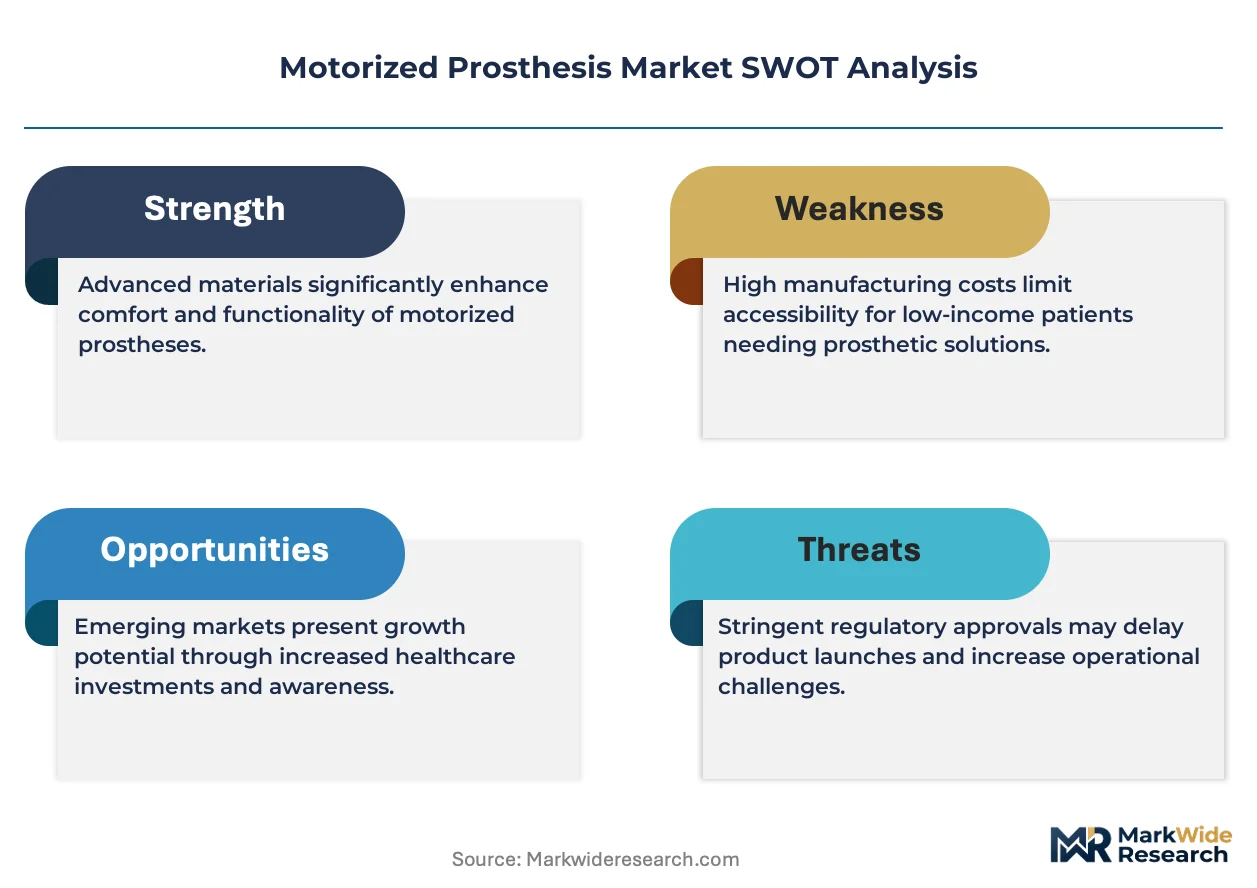
- Neural-interface breakthrough designation:The FDA's accelerated pathway for brain-controlled prosthetic systems compresses commercialization timelines for signal-decoding algorithms. This regulatory mechanism rewards manufacturers investing in invasive electrode arrays.
- Aging-related amputation incidence:Japan's demographic transition toward super-aged society status concentrates demand for lower-limb replacement among dysvascular patients. METI's reimbursement tiers explicitly favor electromechanical knees over passive alternatives.
- Miniaturized servo motor availability:Precision mechatronics clusters in southern Germany now supply brushless DC drives with torque density sufficient for ankle-foot prosthesis integration. Component standardization reduces OEM development cycles.
Market Restraints
- Raw material concentration:Neodymium and dysprosium supply chains for high-performance permanent magnets concentrate in Chinese processing facilities. Price volatility for rare-earth elements compresses gross margins on motorized joint assemblies.
- Clinical evidence burden:The EU Medical Device Regulation mandates extended follow-up data for Class IIb active implantable prosthetics. Smaller manufacturers lack capital reserves to sustain multi-year PMCF studies.
- Passive prosthetic substitution:Carbon-fiber energy-storage feet from Icelandic and German suppliers satisfy athletic-performance demands at one-third the service cost. Competitive runners increasingly select non-powered alternatives.
Strategic Opportunities
- Pediatric bionic expansion:Underpenetrated demand exists for scalable motorized limbs accommodating growth-adjustable socket systems. Regulatory frameworks in Germany and Japan lack pediatric-specific reimbursement codes.
- Home-care calibration channels:Remote software update infrastructure enables direct manufacturer-patient relationships bypassing traditional rehabilitation clinic intermediaries. Telehealth integration reduces fitting appointment frequency.
- Cross-modal sensory feedback:Convergence of haptic actuator arrays with peripheral nerve stimulation creates proprioception restoration previously unavailable in myoelectric systems. Surgical implantation protocols are standardizing.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for real-time gait-phase detection requires specialized expertise in sensor fusion and control theory. Rehabilitation technology firms compete with automotive and robotics sectors for identical skill profiles.
- CE marking timeline compression:Notified body backlogs under MDR implementation delay market entry for novel electromechanical knee mechanisms. Manufacturers face working capital strain during extended conformity assessment periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorized Prosthesis Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lower Limb, Upper Limb, Robotic Hand, Bionic Leg Technology: Electromechanical, Pneumatic, Hydraulic, Neural Interface End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Application: Athletic Performance, Daily Living, Medical Rehabilitation, Cosmetic |
| Companies Covered | Össur hf., Ottobock, Advanced Arm Dynamics, Faulhaber Group, Mobius Bionics, BionX Medical Technologies, Blatchford Group, Fillauer LLC, Hanger, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorized Prosthesis Market Emerging Trajectories
Signal processing architectures are migrating from centralized microprocessor units toward distributed edge-computing nodes embedded directly at joint actuators. This hardware decentralization enables faster loop closure for balance correction.
Machine learning-based pattern recognition is migrating from laboratory-trained models toward patient-specific adaptive algorithms that recalibrate during daily use. Veterans Affairs healthcare systems in the United States deploy these systems for transfemoral amputees with variable terrain exposure. The technology is migrating from research-grade equipment toward clinically validated commercial platforms with FDA 510(k) clearance.
The EU Medical Device Regulation's software-as-a-medical-device classification captures AI-enabled gait optimization code as independently regulated components. Manufacturers must maintain version-controlled algorithm documentation across over-the-air update cycles. Lower-limb bionic OEMs with German manufacturing footprints face the steepest compliance cost increases.
Rehabilitation center procurement patterns are fragmenting as hospital networks consolidate orthopedic device purchasing through centralized value analysis committees. Independent prosthetic clinics respond by forming regional buying cooperatives to maintain negotiating leverage against multinational suppliers. This concentration dynamic is most visible in the United States, where private insurance prior authorization requirements increasingly specify microprocessor knee brands by name.
Motorized Prosthesis Market Segmentation
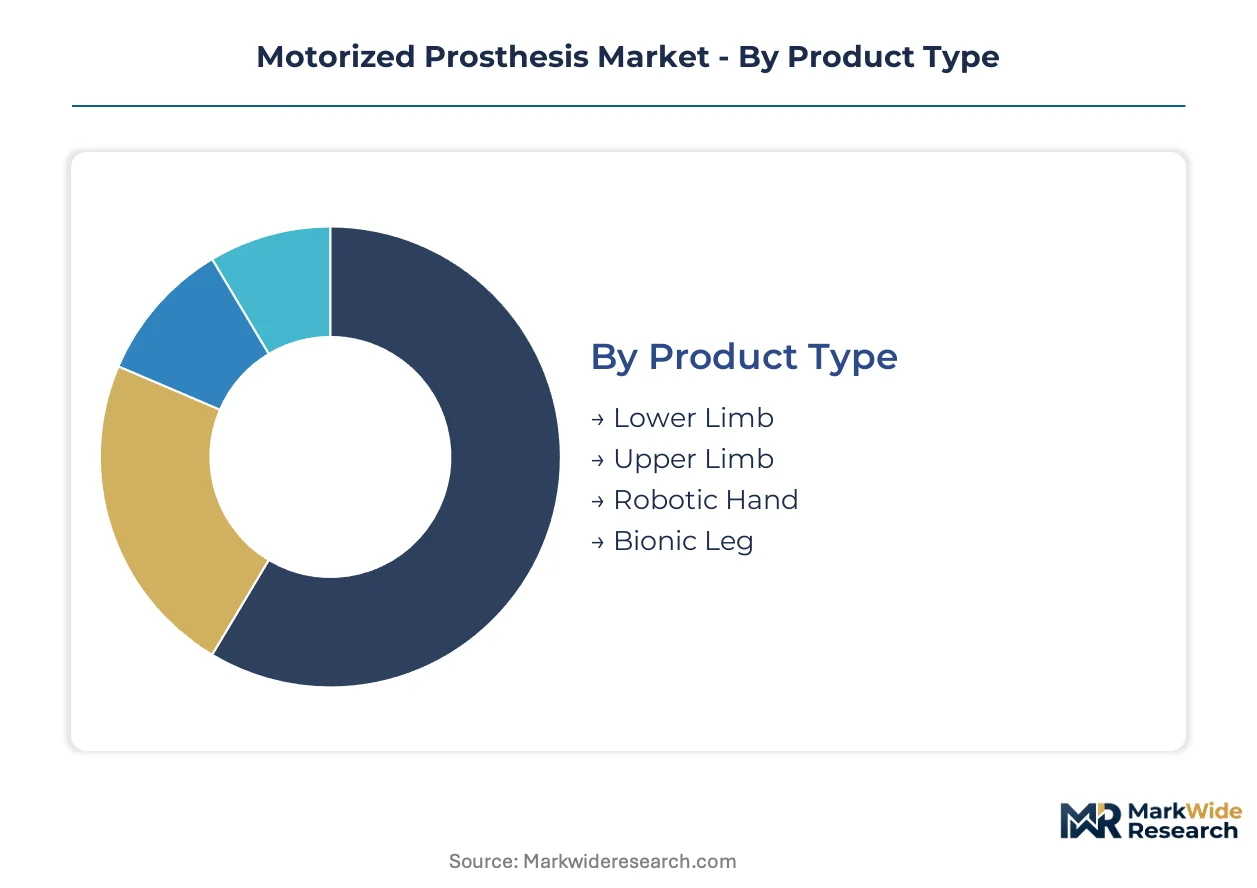
Motorized prosthesis manufacturers engineer distinct product architectures for limb position, actuation method, care setting, and functional objective. Each segmentation dimension carries reimbursement implications and technical validation requirements that shape commercial strategy.
Product Type:
Mature socket-and-limb systems anchor current revenue while emerging bionic configurations capture development investment.
- Lower Limb:Transfemoral and transtibial configurations integrate microprocessor knees with carbon-fiber pylons. Demand concentrates in Japan's aging population centers where METI reimbursement tiers explicitly favor electromechanical knees over passive alternatives for dysvascular amputees.
- Upper Limb:Myoelectric elbow-wrist-hand systems decode residual muscle signals for grasp patterns. German rehabilitation clinic networks drive fitting volume for transhumeral configurations, though reimbursement authorization requires documented functional necessity assessments.
- Robotic Hand:Multi-articulating digit systems with independent finger control.
- Bionic Leg:Full-limb replacement with powered ankle and knee articulation.
Lower Limb handles the majority of throughput; Bionic Leg is the fastest mover on share.
Technology:
Cost tiers separate established electromechanical platforms from premium neural-interface systems requiring invasive surgical protocols.
- Electromechanical:Brushless DC servo motors with encoder feedback dominate current manufacturing. Southern Germany's precision mechatronics clusters supply standardized drive modules that reduce OEM development cycles for ankle-foot and knee mechanisms.
- Neural Interface:Invasive electrode arrays decode cortical or peripheral nerve signals for intuitive control. FDA breakthrough device designation accelerates approval timelines for signal-decoding algorithms, rewarding manufacturers with capital reserves for clinical trial investment.
- Pneumatic:Compressed gas actuation for lightweight power assistance.
- Hydraulic:Fluid-based resistance modulation for stance-phase stability.
Electromechanical configurations handle the majority of throughput; Neural Interface is expanding most quickly on share.
End User:
Volume concentrates in institutional channels while margin pools shift toward direct-to-patient delivery models.
- Rehabilitation Centers:Specialized prosthetic facilities conduct initial fitting, gait training, and device calibration. Ottobock's long-standing clinic partnerships across Germany anchor European distribution for premium bionic systems requiring multi-session adjustment protocols.
- Home Care:Remote software update infrastructure and telehealth integration enable manufacturer-patient relationships bypassing traditional intermediaries. Veterans Affairs healthcare systems deploy adaptive algorithms for transfemoral amputees with variable terrain exposure.
- Hospitals:Acute care settings for immediate post-amputation consultation.
- Clinics:Independent prosthetic practices forming regional buying cooperatives.
Rehabilitation Centers handle the majority of throughput; Home Care is climbing the fastest on share.
Application:
Medical necessity drives reimbursement authorization while athletic and cosmetic applications rely on private payment.
- Medical Rehabilitation:Functional restoration for amputees across dysvascular, trauma, and congenital indications. Insurance prior authorization requirements increasingly specify microprocessor knee brands by name in the United States, concentrating procurement through hospital network value analysis committees.
- Athletic Performance:Carbon-fiber energy-storage feet from Icelandic and German suppliers satisfy competitive demands at lower service cost, displacing motorized alternatives for running and sprinting disciplines.
- Daily Living:General mobility and self-care task assistance.
- Cosmetic:Aesthetic prosthesis with limited functional articulation.
Medical Rehabilitation handles the majority of throughput; Daily Living is gaining share fastest as home-care channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's precision engineering logistics corridor underwrites Germany's dominance in electromechanical component supply for motorized prosthesis manufacturing.
United States
Veterans Affairs healthcare systems drive demand for adaptive gait algorithms among transfemoral amputees. FDA breakthrough device designation accelerates neural-interface system approvals, compressing commercialization timelines. Minneapolis-St. Paul anchors upper-limb fitting volume through specialized rehabilitation clinic networks.
Germany
Dysvascular amputation incidence among aging populations concentrates demand for microprocessor-enabled knees. EU Medical Device Regulation imposes extended clinical-evidence requirements for Class IIb active implantable prosthetics. Bavaria's precision mechatronics clusters supply standardized brushless DC drive modules to multiple device OEMs.
Japan
Super-aged society status concentrates lower-limb replacement demand in metropolitan centers. METI coordinates national insurance reimbursement tiers that explicitly favor electromechanical knees over passive mechanical alternatives. Tokyo-Osaka corridor rehabilitation facilities anchor fitting volume for bionic systems.
United Kingdom
NHS procurement consolidation through specialized prosthetic centers shapes access to premium motorized systems. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways. London and Manchester rehabilitation hubs drive initial fitting protocols for microprocessor-controlled limbs.
Motorized Prosthesis Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying standardized drive modules and sensor arrays. Market structure consolidates around rehabilitation clinic partnerships and distribution networks rather than manufacturing scale alone. Three archetypes dominate: full-system OEMs with clinic integration capabilities, precision motor suppliers with multi-OEM relationships, and regional fabricators serving national reimbursement systems. Competitive moves concentrate on M&A for clinic network access and capacity expansion in southern Germany's mechatronics corridor.
Among Nordic-European system integrators, Össur hf. and Ottobock occupy positions anchoring distinct geographic footprints. Össur hf. exemplifies the athletic-performance limb archetype with carbon-fiber composite expertise, while Ottobock represents clinic-integrated distribution dominance. Faulhaber Group sits within the component-specialist tier, supplying miniature motor systems across multiple device manufacturers without direct patient-facing operations.
| Leading Market Players |
|---|
| Össur hf. |
| Ottobock |
| Advanced Arm Dynamics |
| Faulhaber Group |
| Mobius Bionics |
| BionX Medical Technologies |
| Blatchford Group |
| Fillauer LLC |
| Hanger, Inc. |
| Others |
Supply Flow & Price Mechanics
The Port of Hamburg's precision engineering logistics corridor shapes cost dynamics across motorized prosthesis supply chains, concentrating premium-tier pricing power with German mechatronics OEMs while compressing margins for assemblers dependent on rare-earth magnet imports. Freight cost differentials between Hamburg and Asian component hubs directly separate premium bionic system pricing from standard electromechanical configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with neural-interface systems commanding premium positioning against brushless DC-based alternatives. FDA breakthrough device certification and CE marking under MDR create price differentiation between validated and pending-approval configurations. Cost compression in standard electromechanical knees is intensifying because carbon-fiber passive substitutes satisfy athletic-performance demands at lower service cost. Rehabilitation centers exhibit highest price sensitivity due to consolidated hospital network purchasing, while Veterans Affairs systems demonstrate lowest sensitivity for adaptive gait algorithms.
Supply Chain Analysis
Tariff exposure between China and processing facilities in Germany and Japan dominates supply chain risk assessment for rare-earth magnet procurement. Neodymium and dysprosium supply chains concentrate in Chinese processing facilities, with brushless DC servo motors and encoder feedback systems sourcing from Bavarian precision mechatronics clusters. Single-source vulnerability in permanent magnet refining compresses gross margins on motorized joint assemblies. Distribution runs through rehabilitation clinic networks for initial fitting, with remote software update infrastructure emerging for maintenance and calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering expertise for real-time gait-phase detection represents the critical capability gap, with rehabilitation technology firms competing against automotive and robotics sectors for identical embedded systems talent pools. This scarcity shapes strategic positioning across all market participants.
For Market Incumbents: Entrench clinic network partnerships through multi-session calibration protocols that lock in switching costs for premium bionic systems. Deepen backward integration into brushless DC drive module production within Bavaria's mechatronics corridor to offset rare-earth price volatility. Neural-interface patent portfolios provide defensive moats against emerging algorithm-centric competitors. For New Entrants and Emerging Players: Pursue pediatric bionic expansion where regulatory frameworks in Germany and Japan lack age-specific reimbursement codes, creating first-mover advantage in scalable growth-adjustable socket systems. Home-care calibration channels offer penetrable white space through telehealth-integrated remote software update infrastructure. Direct manufacturer-patient relationships bypass entrenched rehabilitation clinic intermediaries. For Investors and Strategic Acquirers: Component-specialist suppliers with multi-OEM motor relationships present acquisition targets, particularly those with established Faulhaber-style miniature drive system expertise. Long-term viability hinges on reimbursement harmonization across German, Japanese, and United States healthcare systems. Signal to watch: FDA breakthrough device designation velocity for invasive electrode array systems as inflection indicator for neural-interface margin pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance costs concentrate in German manufacturing footprints with extended PMCF study requirements. |
| Hospital System Partnership | Ottobock's rehabilitation clinic networks anchor European distribution against consolidated purchasing committees. |
| Software Companion Development | EU MDR software-as-medical-device classification captures AI-enabled gait optimization for version-controlled documentation. |
| Reimbursement Strategy | METI insurance tiers in Japan explicitly favor electromechanical knees over passive mechanical alternatives. |
| Backward Integration | Bavarian precision mechatronics clusters supply standardized drive modules reducing OEM development cycles. |
Methodological Framework
Operator-level perspectives from prosthetists, rehabilitation clinic directors, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA 510(k) clearance databases, EMA MDR submission records, METI reimbursement tier documentation, and CMS Medicare prosthetic claims data. Bottom-up demand modeling across limb position and technology segments triangulated with top-down healthcare expenditure tracking.
Scenario-bracketing framed sensitivity analysis across regulatory approval velocity, reimbursement policy divergence, and rare-earth commodity price trajectories over the projection horizon. Segmentation dimensions modeled include limb position, actuation technology, care setting, functional application, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating aging-related amputation incidence patterns, neural-interface clinical trial advancement rates, and miniaturized servo motor cost reduction curves.
Sensitivities concentrate around MDR notified body backlog resolution timelines, METI reimbursement tier adjustments for pediatric indications, and Chinese rare-earth export quota modifications. Forecasts reflect documented assumptions regarding regulatory pathway compression and component standardization adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Digital Phoropter Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Breathing Exercise Devices Market