
 Bone Conduction Hearing Aids Market | 2026-2036
Bone Conduction Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Conduction Hearing Aids Market Outlook
ISO 13485 certification for medical device quality management is reorganizing competitive entry in bone conduction hearing aids, forcing smaller manufacturers to invest heavily in audit-ready quality systems before commercialization. Cochlear leverages its decades of implantable device expertise to sustain premium positioning across hospital procurement channels. WS Audiology anchors broad retail audiology networks, while MED-EL specializes in advanced vibration transfer architectures for complex conductive hearing loss cases.
Bone conduction hearing aids transmit sound vibrations directly through the skull bone to the cochlea, bypassing damaged outer or middle ear structures, with typical frequency responses spanning 250-8000 Hz and power outputs calibrated to bone-conduction thresholds. These devices serve patients with conductive, mixed, or single-sided deafness who cannot benefit from conventional air-conduction amplification. Implantable devices command the deepest margin pools due to surgical placement requirements and long-term service revenue, while wireless options integrating Bluetooth protocols represent the fastest-growing technology dimension as smartphone-native users age into hearing loss. The seniors end-user segment remains the largest volume base, though pediatrics generates disproportionate clinical attention and reimbursement advocacy.
FDA oversight through 21 CFR 874 medical device classification shapes product registration pathways and clinical evidence requirements for US market entry, while the EU Medical Device Regulation imposes stricter post-market surveillance and notified body scrutiny on European distribution. The FDA's 2022 over-the-counter hearing aid final rule is fragmenting traditional audiologist gatekeeping, creating parallel commercial channels that bypass professional fitting. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and Australia reconcile prescriptive clinical models with consumer-direct purchasing trends.
Market Dynamics
The FDA's 2022 over-the-counter hearing aid final rule is fragmenting traditional audiologist gatekeeping, creating parallel commercial channels that bypass professional fitting and compress margin structures across established distribution networks.
Growth Catalysts
- Pediatric ENT clinic expansion:Parents increasingly seek non-surgical alternatives for congenital hearing loss, driving volume through specialized pediatric audiology centers.
- Bluetooth protocol integration:Wireless options connecting directly to smartphones attract aging users accustomed to seamless device pairing.
- Reimbursement pathway maturation:United States bone-anchored system coverage has stabilized, reducing patient out-of-pocket uncertainty.
Market Restraints
- ISO 13485 audit costs:Smaller manufacturers face heavy investment requirements for quality management certification before commercialization.
- Surgical placement dependency:Implantable devices require otolaryngologist involvement, limiting addressable population and geographic reach.
- Air-conduction substitute threat:Conventional hearing aids retain cost advantage and broader clinical familiarity among general audiologists.
Strategic Opportunities
- Direct-to-consumer channel development:Online platforms and retail pharmacy chains create access points outside traditional audiology networks.
- Japan's aging demographic:METI initiatives supporting assistive technology adoption open reimbursement discussions for bone conduction alternatives.
- Pediatric school screening mandates:Early detection programs in Australia and Germany expand identification of conductive hearing loss candidates.
Industry Challenges
- Otolaryngologist training bottlenecks:Surgical placement requires specialized ENT expertise that concentrates in urban academic medical centers.
- Post-market surveillance compliance:EU Medical Device Regulation imposes ongoing clinical follow-up obligations that strain smaller manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Conduction Hearing Aids Market |
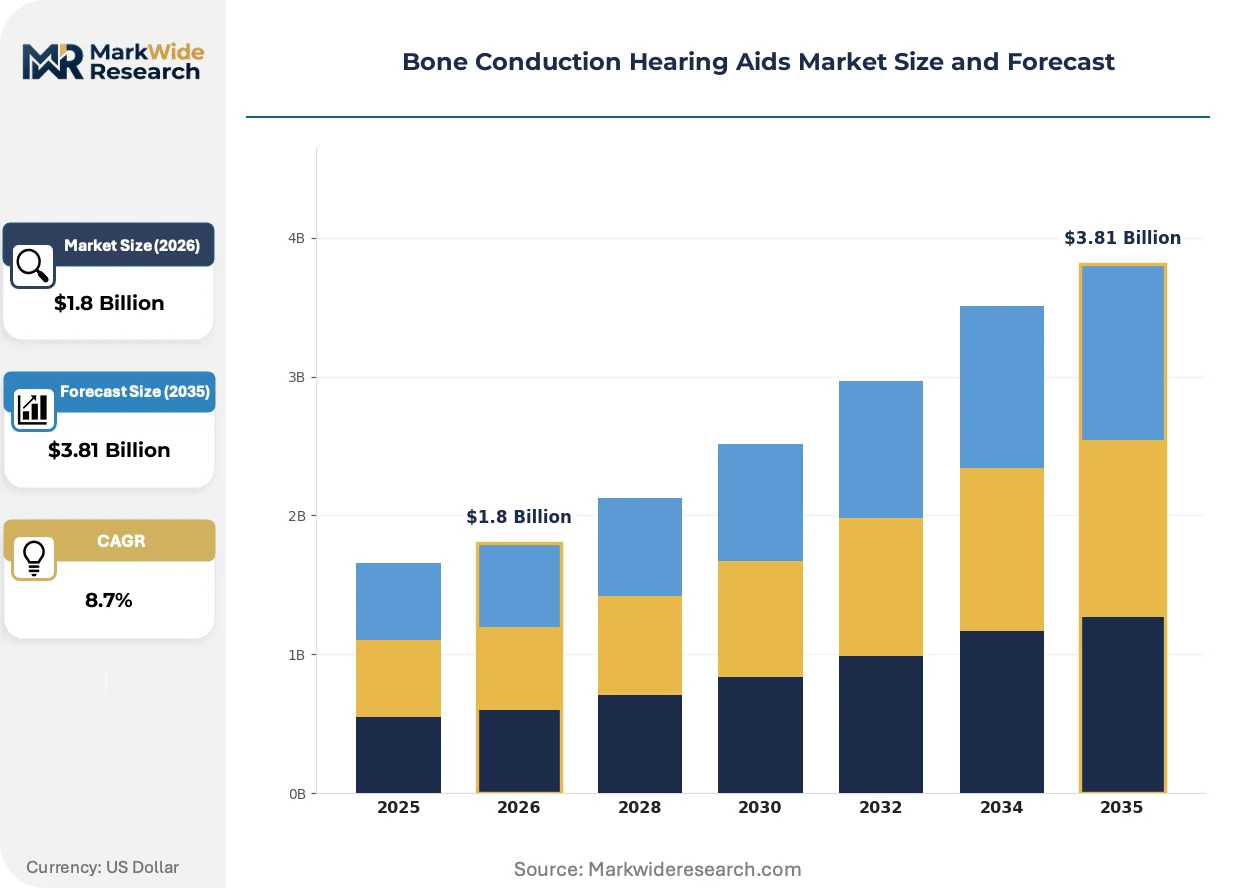
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Conventional Aids, Wireless Options, Custom Solutions Technology: Vibration Transfer, Signal Processing, Bluetooth Integration, Noise Cancellation Application: Sound Transmission, Audio Processing, Assistive Listening, Hearing Restoration End User: Adults, Pediatrics, Seniors, Hearing Impaired Individuals |
| Companies Covered | Medtronic, Aurica Hearing Aids, Cochlear, WS Audiology, GN Hearing, Oticon Medical, BHM-Tech Produktionsgesellschaft, HearNU, MED-EL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Conduction Hearing Aids Market Strategic Shifts
Wireless connectivity protocols and direct-to-consumer distribution models are compressing traditional value chains. Regulatory fragmentation between prescriptive clinical models and consumer-direct access creates competitive uncertainty.
Titanium abutment systems with percutaneous placement is supplanting older soft-tissue preservation techniques in bone-anchored applications. Otolaryngology departments in tertiary hospitals are adopting these architectures for reduced skin complication rates. The shift is supplanting transcutaneous magnetic coupling as the default surgical recommendation for mixed hearing loss cases.
EU Medical Device Regulation post-market surveillance requirements are extending clinical evidence obligations across product lifecycles. Manufacturers must maintain active implant registries and periodic safety reporting beyond initial CE marking. Implantable device portfolios face the steepest compliance burden, with notified body scrutiny intensifying for Class III bone conduction systems.
Smartphone-native users aging into presbycusis are rejecting clinic-dependent fitting workflows. Direct-to-consumer platforms with self-administered hearing tests capture trial users before traditional audiology encounters. This behavioral pivot concentrates in United States metropolitan markets where OTC regulatory clarity has enabled retail pharmacy distribution.
Bone Conduction Hearing Aids Market Segmentation
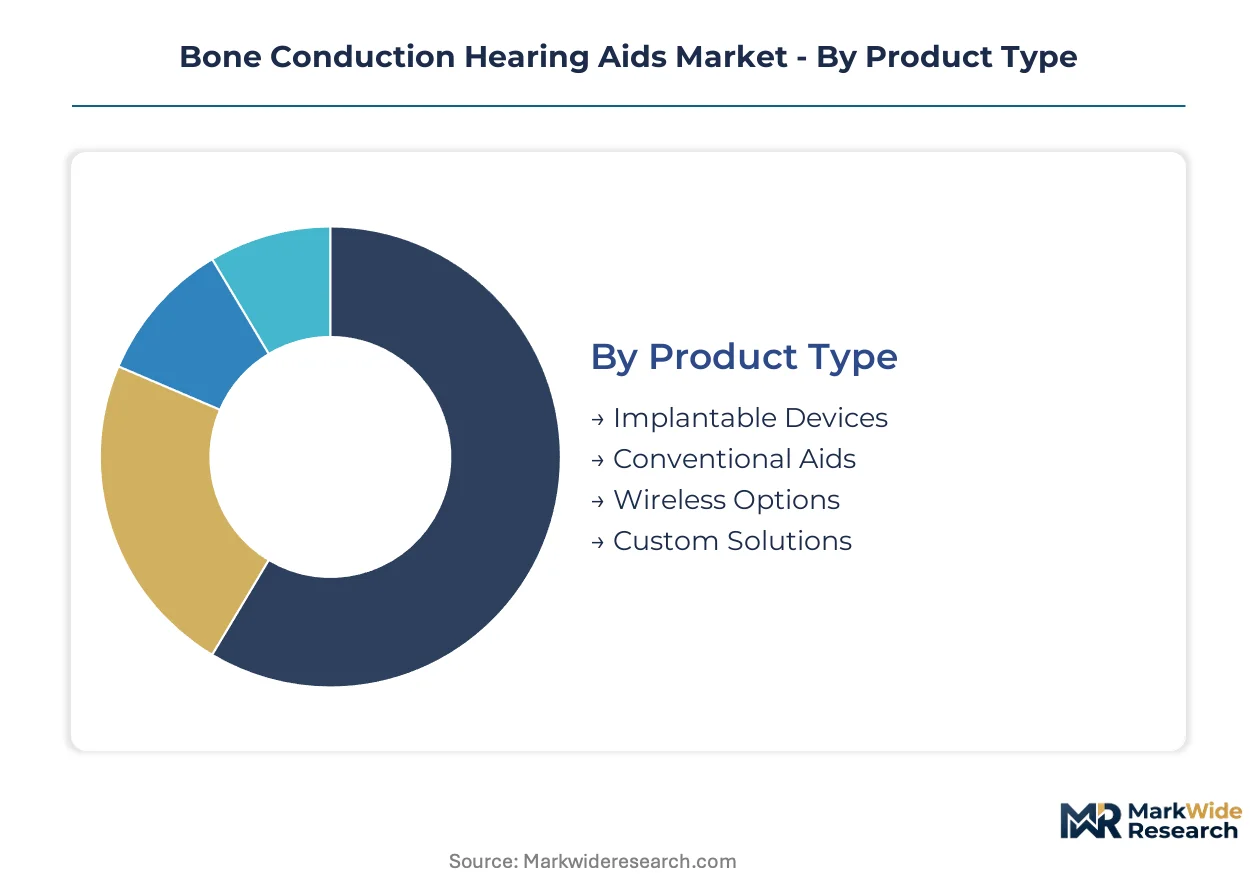
Segmentation in bone conduction hearing aids reveals how surgical complexity, connectivity protocols, and patient age reshape procurement channels. Manufacturers calibrate R&D investment and distribution partnerships against these divides.
Product Type:
Implantable devices capture the deepest margin pools due to surgical service revenue and long-term maintenance contracts.
- Implantable Devices:Titanium abutment systems with percutaneous placement bypass damaged outer ear structures entirely. Demand concentrates in United States tertiary hospitals where otolaryngology departments favor reduced skin complication rates over transcutaneous magnetic alternatives.
- Wireless Options:Bluetooth-enabled units pair directly with smartphones for streaming and remote adjustment. Aging users in United States metropolitan markets favor these for self-administered fitting workflows that bypass traditional audiology gatekeeping.
- Conventional Aids:Non-surgical bone conduction headsets serve conductive hearing loss patients who decline implantation.
- Custom Solutions:Patient-specific fittings address complex anatomical variations in pediatric craniofacial cases.
Implantable devices hold installed capacity. Wireless options are rotating up the share rankings.
Technology:
Signal processing architectures differentiate premium tiers from economy offerings through real-time environmental adaptation.
- Signal Processing:Digital algorithms adjust frequency response dynamically to bone-conduction thresholds. Pediatric clinics in Germany prioritize these systems for congenital conductive loss where environmental variability demands automatic gain control.
- Bluetooth Integration:Direct smartphone pairing enables remote programming and audio streaming. United States direct-to-consumer channels exploit this capability to attract smartphone-native users aging into presbycusis.
- Vibration Transfer:Electromechanical transducers convert electrical signals to skull vibrations with calibrated power outputs.
- Noise Cancellation:Directional microphone arrays suppress background interference in multi-talker environments.
Signal processing dominates premium positioning. Bluetooth integration is climbing the fastest as OTC distribution expands.
Application:
Volume concentrates in hearing restoration where surgical candidacy creates patient selection bottlenecks.
- Hearing Restoration:Surgical and non-surgical interventions aim to recover functional hearing thresholds. United States reimbursement pathways for bone-anchored systems have matured, reducing patient out-of-pocket uncertainty and stabilizing demand.
- Assistive Listening:Classroom and workplace amplification systems support communication access. Australian pediatric school screening mandates expand identification of conductive hearing loss candidates for these interventions.
- Sound Transmission:Basic vibration conduction without processing for single-sided deafness cases.
- Audio Processing:Real-time signal modification for frequency-specific amplification needs.
Hearing restoration commands procedural revenue. Assistive listening is gaining share fastest through early detection programs.
End User:
Pediatrics generates disproportionate clinical attention despite smaller volume, driven by parental advocacy for non-surgical alternatives.
- Seniors:Presbycusis patients with conductive components or single-sided deafness form the largest addressable population. Japan's METI initiatives supporting assistive technology adoption open reimbursement discussions for bone conduction alternatives in this cohort.
- Pediatrics:Parents seek non-surgical alternatives for congenital hearing loss, accelerating volume through specialized pediatric audiology centers in Germany and Australia.
- Adults:Working-age patients with traumatic or acquired conductive loss pursue discreet solutions.
- Hearing Impaired Individuals:Broad category encompassing all severity levels and etiologies.
Seniors hold installed capacity. Pediatrics is rotating up the share rankings through early intervention advocacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bone conduction hearing aids market traverses specialized logistics corridors linking medical device manufacturing clusters with tertiary hospital networks across major economies.
United States
Pediatric ENT clinic expansion and direct-to-consumer channel maturation drive volume growth in metropolitan markets. The FDA's 2022 over-the-counter hearing aid final rule fragments traditional audiologist gatekeeping, enabling retail pharmacy distribution. Boston and Minneapolis anchor academic medical center concentration where otolaryngology departments favor titanium abutment surgical placements.
Germany
Early detection school screening mandates and pediatric audiology center specialization expand candidate identification for conductive hearing loss interventions. The EU Medical Device Regulation imposes stringent post-market surveillance obligations on implantable device portfolios. Bavaria's medical technology corridor around Erlangen concentrates vibration transfer engineering expertise for complex craniofacial cases.
Japan
METI initiatives supporting assistive technology adoption open reimbursement discussions for aging presbycusis patients seeking bone conduction alternatives. The Pharmaceuticals and Medical Devices Agency maintains rigorous clinical evidence standards for Class III device approvals. Tokyo and Osaka metropolitan clusters concentrate hearing aid retail networks integrating Bluetooth-enabled wireless options.
Australia
Pediatric school screening programs and early intervention advocacy accelerate identification of congenital conductive hearing loss candidates. The Therapeutic Goods Administration oversees medical device registration with emphasis on post-market safety monitoring. Sydney and Melbourne anchor specialized pediatric audiology centers driving non-surgical alternative demand.
United Kingdom
National Health Service procurement frameworks and specialized audiology referral pathways shape hospital-based bone-anchored system adoption. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for post-market surveillance. London's tertiary hospital network concentrates otolaryngology expertise for complex implantable device placements.
Bone Conduction Hearing Aids Market Competitive Environment
Listed leaders compete with private specialists across regulatory certification and distribution channel dimensions, producing a tiered market structure where scale advantages concentrate in publicly traded entities while private manufacturers occupy niche surgical and pediatric segments. Strategic archetypes include implantable device specialists leveraging decades of surgical service relationships, retail audiology network operators capturing direct-to-consumer volume, and vibration transfer engineering firms serving complex conductive loss cases. Competitive moves center on ISO 13485 quality system investments for market entry clearance and strategic partnerships with tertiary hospital procurement channels.
Within the implantable device tier, Cochlear and MED-EL represent archetypes of surgical expertise translation into premium positioning, while WS Audiology occupies a position bridging professional fitting networks with emerging direct-to-consumer access points. These three entities exemplify how decades of clinical relationship accumulation creates defensive positioning against OTC channel fragmentation.
| Leading Market Players |
|---|
| Medtronic |
| Aurica Hearing Aids |
| Cochlear |
| WS Audiology |
| GN Hearing |
| Oticon Medical |
| BHM-Tech Produktionsgesellschaft |
| HearNU |
| MED-EL |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at titanium abutment foundries in the United States and Germany shapes both component scarcity and implantable device price floors, concentrating margin power with vertically integrated manufacturers who control surgical service bundling.
Pricing Analysis
Certification level creates the primary spread between premium implantable systems and economy non-surgical alternatives. Three-tier pricing structure across premium, standard, and economy levels segments the market, with FDA 510(k) clearance and EU MDR Class III certification commanding substantial premiums over uncertified direct-to-consumer units. Cost compression in wireless Bluetooth-enabled segments is intensifying because OTC channel expansion eliminates professional fitting fees. Pediatric clinics exhibit lowest price sensitivity due to parental advocacy and established reimbursement pathways, while aging presbycusis patients in direct-to-consumer channels demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for titanium abutment components currently stretch 14-22 weeks due to orthopedic device foundry capacity competition. Manufacturing concentrates in the United States, Germany, and Switzerland for precision-machined implantable components, with final assembly distributed across Ireland and Singapore for regional regulatory compliance. Raw material dependencies include surgical-grade titanium, neodymium magnets for transcutaneous coupling, and Bluetooth SoC chipsets. Single-source vulnerability sits with European notified bodies for EU MDR certification. Distribution runs through hospital procurement committees for implantables and retail pharmacy chains for OTC wireless units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bone conduction hearing aids occupy an early-cycle expansion phase, with FDA OTC rulemaking and pediatric non-surgical demand constituting durable adoption tailwinds through the projection horizon.
For Market Incumbents: Secure otolaryngology department partnerships in United States academic medical centers before titanium abutment surgical placement becomes commoditized. Deepen backward integration into vibration transfer transducer manufacturing to defend margin position against Bluetooth-enabled wireless substitutes. ISO 13485 certification investment remains the priority lever for European market retention. For New Entrants and Emerging Players: Anchor in Japan's aging demographic segment where METI assistive technology initiatives are opening reimbursement discussions ahead of established competitor presence. Target Australian pediatric school screening programs for conductive hearing loss identification partnerships. Pursue direct-to-consumer online platforms with self-administered hearing test integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wireless connectivity specialists over legacy implantable device pure-plays. Five-to-ten year viability hinges on software-defined hearing aid architectures and remote programming capabilities. Acquisition target archetype: Bluetooth protocol engineering firms with FDA quality system documentation. Watch FDA enforcement discretion on OTC marketing claims as the inflection indicator for channel profitability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates United States market entry for implantable titanium abutment systems. |
| EU MDR Class III Certification | Unlocks European hospital procurement channels with post-market surveillance compliance. |
| Hospital System Partnership | Secures preferred vendor status in tertiary otolaryngology departments for surgical placements. |
| Software Companion Development | Enables smartphone-native users to self-administer fitting workflows bypassing audiology gatekeeping. |
| Reimbursement Strategy | Stabilizes patient out-of-pocket costs through CMS Medicare coverage for bone-anchored systems. |
Study Parameters
Desk research of FDA 510(k) device filings, EU MDR notified body guidance documents, and hospital procurement database records preceded structured interviews with otolaryngology department heads, biomedical engineering directors, pediatric audiology clinic managers, and GPO contracts administrators. Secondary validation drew from CMS Medicare reimbursement schedules, Japanese METI assistive technology white papers, and Australian Therapeutic Goods Administration safety monitoring reports. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Variance decomposition across product type, technology architecture, application setting, and end-user age cohort informed the analytical framework throughout the forecast period. CAGRs derived from surgical placement volume trajectories, wireless unit adoption curves, and reimbursement pathway maturation timelines. Industry-specific forecast inputs included FDA OTC rule implementation pace and pediatric early detection program expansion rates.
Material uncertainties — regulatory enforcement discretion shifts, reimbursement policy reversals, and Bluetooth protocol standard changes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding adoption elasticity and channel migration patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Cryoablation Devices Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Active Wheelchair Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Global Veress Needle Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market