
 Canada General Surgical Devices Market | 2026-2036
Canada General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada General Surgical Devices Market Outlook
Aging surgical technologist cohorts across Ontario and British Columbia is unwinding operating room throughput capacity, forcing health authorities to accelerate training pipelines and automate instrument reprocessing workflows. Medtronic leverages its broad electrosurgical portfolio to sustain presence in major teaching hospitals. Johnson & Johnson anchors minimally invasive surgery adoption through its advanced stapling platforms. Stryker Corporation competes on integrated operating room ecosystems that combine surgical instruments with real-time navigation.
Canada general surgical devices encompass handheld instruments, powered equipment, sutures, staplers, and energy-based systems manufactured from medical-grade stainless steel, titanium, or polymer composites, designed to cut, coagulate, grasp, or close tissue during operative procedures. These devices serve the essential function of enabling safe tissue manipulation while minimizing blood loss and post-operative complications. Electrosurgical devices and robotic surgical systems command premium positioning as hospitals prioritize precision and reduced recovery times. Surgical sutures and conventional instruments occupy mature, cost-sensitive segments where procurement consolidation limits margin expansion. Laparoscopic and robotic-assisted technologies are gaining share as surgeons seek alternatives to open procedures in bariatric and cardiac applications.
Health Canada's Medical Devices Regulations, alongside ISO 13485 quality management standards and CSA biocompatibility guidelines, govern market access and mandate rigorous clinical evidence for higher-risk device classes. These frameworks elevate compliance costs for entrants while reinforcing incumbent positions among established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor how provincial health technology assessment bodies, notably CADTH and Ontario Health, calibrate reimbursement and procurement criteria for robotic and energy-based surgical platforms.
Market Dynamics
Health Canada's tightening biocompatibility standards under ISO 13485 and CSA guidelines is compressing approval timelines for reusable instruments while accelerating capital deployment into single-use alternatives across Ontario and Quebec hospital networks.
Growth Catalysts
- Minimally invasive procedure expansion:Ontario and Quebec health authorities are expanding dedicated laparoscopic suites in tertiary centers, driving instrument replacement cycles and disposable attachment consumption.
- Health Canada MDR enforcement:Stricter sterilization validation requirements for reusable instruments are pushing hospitals toward validated single-use electrosurgical pencils and trocars with established compliance dossiers.
- Aging surgical workforce:Retiring technologists in British Columbia and Alberta are forcing health authorities to automate instrument reprocessing and adopt intuitive, reduced-handling device designs.
Market Restraints
- Medical-grade stainless steel volatility:Input cost swings for 316L and 17-4 PH alloys compress margin stability for domestic instrument fabricators serving Prairie provinces.
- Single-source dependency:Polymer composite trocar housings concentrate with limited North American molders, exposing just-in-time supply chains to regional disruption risk.
- Health Canada Class III evidentiary burden:Novel energy-based platforms face extended clinical data requirements that delay commercialization against established electrosurgical incumbents.
Strategic Opportunities
- Atlantic Canada penetration gap:Nova Scotia and New Brunswick surgical volumes trail national averages by 23%, offering first-mover positioning for mobile robotic-assisted surgery platforms.
- CADTH accelerated review pathway:Ontario Health's parallel health technology assessment stream rewards robotic and navigation-enabled systems with expedited provincial reimbursement listings.
- AI-integrated energy delivery:Real-time tissue impedance feedback converging with machine learning algorithms enables differentiated positioning in bariatric and colorectal procedures.
Industry Challenges
- Sterile processing technician shortage:Ontario's collapsed training pipeline delays instrument turnaround, forcing OR block cancellations and emergency rental instrument premiums.
- Legacy EMR integration friction:Robotic surgical platforms require custom API development to feed operative data into provincial Cerner and Epic deployments, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada General Surgical Devices Market |
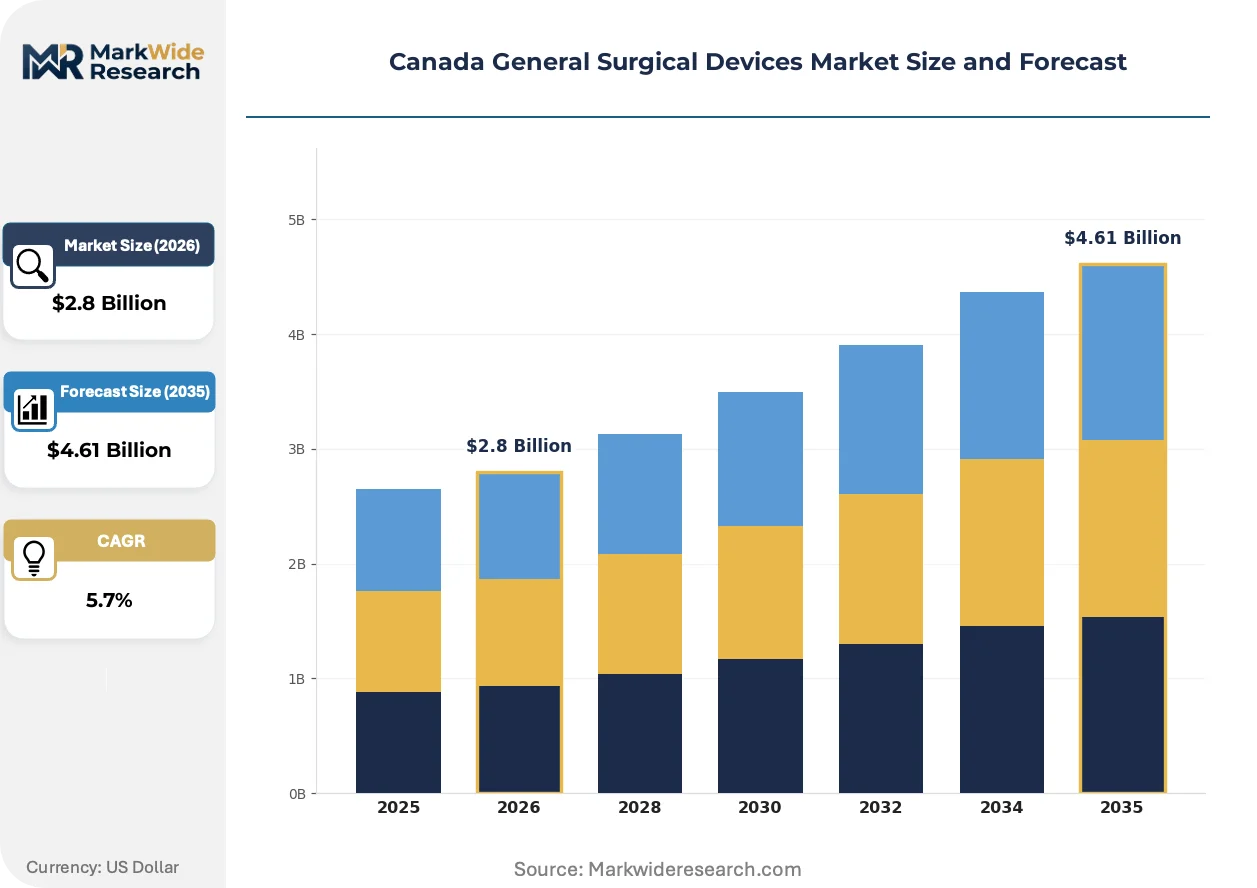
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Sutures, Electrosurgical Devices, Surgical Instruments, Robotic Surgical Systems End User: Hospitals, Outpatient Surgical Centers, Ambulatory Surgical Clinics, Specialty Clinics Technology: Laparoscopic, Minimally Invasive, Open Surgery, Robotic-Assisted Application: Cardiac Surgery, Orthopedic Surgery, Bariatric Surgery, Neurological Surgery |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker Corporation, Boston Scientific Corporation, B. Braun SE, CONMED Corporation, Olympus Corporation, Smith & Nephew, Integer Holdings Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada General Surgical Devices Market Strategic Shifts
Electrosurgical energy delivery is fragmenting into modality-specific platforms while regulatory evidence requirements harden around real-world performance data rather than bench testing alone.
Radiofrequency and ultrasonic energy systems is bifurcating into discrete vessel-sealing and cutting platforms optimized by tissue type. Academic medical centers in Toronto and Vancouver are piloting dual-generator suites that switch modalities mid-procedure. This capability is bifurcating procurement decisions between integrated-platform vendors and best-of-breed energy specialists, compressing mid-tier electrosurgical portfolios.
Health Canada's 2024 guidance on software-as-a-medical-device requires algorithm-enabled surgical navigation systems to submit prospective clinical validation studies. Manufacturers must now maintain Canadian-specific post-market surveillance registries rather than relying on FDA 510(k) reciprocity. Class II navigation instruments with autonomous feedback loops face the steepest evidentiary escalation, pushing developers toward simpler, surgeon-controlled interfaces.
Hospital procurement consortia across the Greater Toronto Area are consolidating instrument purchasing through Ontario Health's centralized tendering platform. Independent community hospitals lose negotiating leverage as volume aggregates toward academic centers with robotic surgery mandates. This concentration is most visible in York Region and Peel Region, where three-hospital systems now dictate suture and stapler specifications for affiliated outpatient surgical centers.
Canada General Surgical Devices Market Segmentation
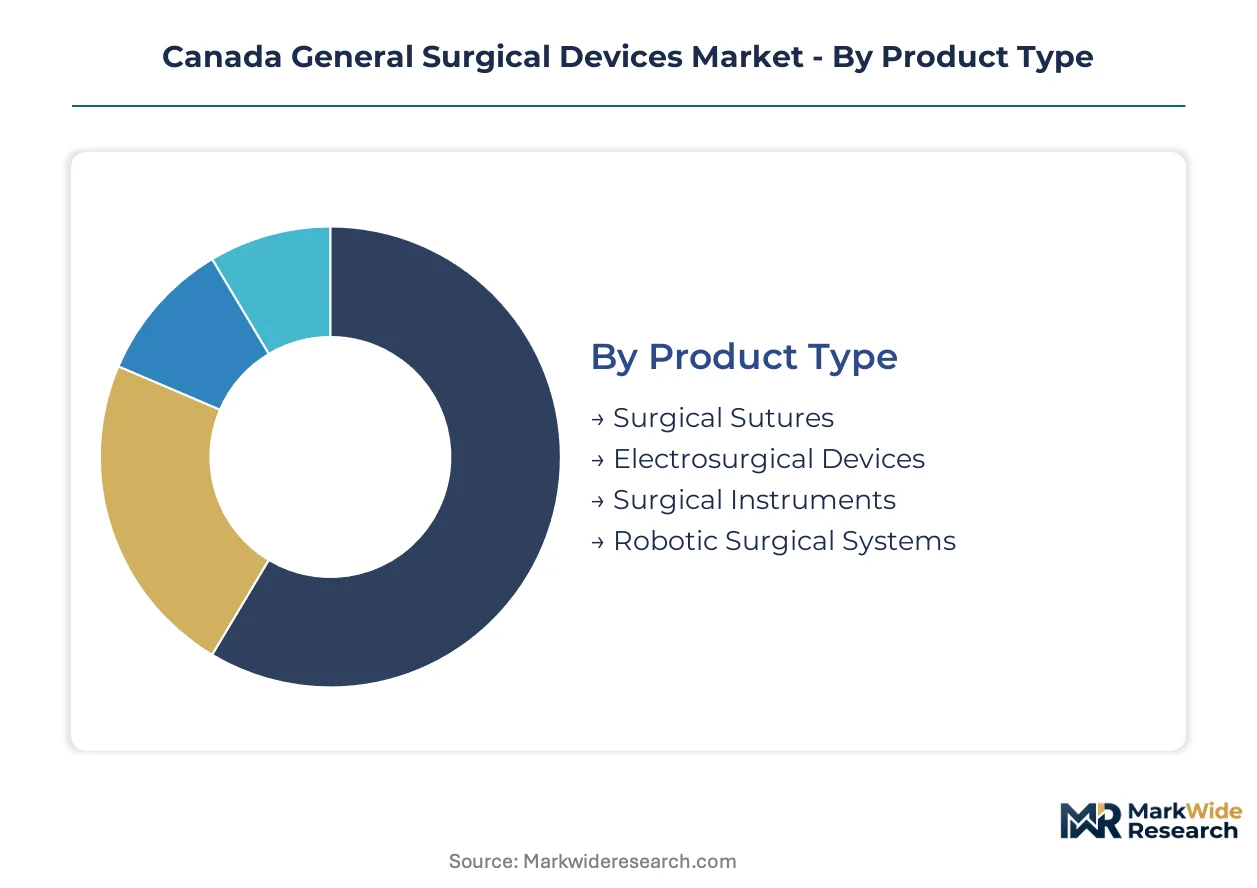
Canada's surgical device procurement operates through provincial health technology assessment pathways that classify products by risk tier and evidentiary burden. Segmentation clarity determines reimbursement eligibility and tendering strategy across Ontario Health, CADTH, and British Columbia health authority frameworks.
Product Type:
Health Canada's Medical Devices Regulations assign Class II and Class III designations based on invasiveness and energy delivery, directly shaping approval timelines and post-market surveillance obligations for each product category.
- Electrosurgical Devices:Radiofrequency and ultrasonic generators with active electrode pencils deliver controlled thermal energy for cutting and coagulation. Demand concentrates in Ontario's tertiary cardiac centers where vessel-sealing precision reduces transfusion rates; Health Canada's tightened biocompatibility standards for reusable active electrodes accelerate single-use pencil adoption.
- Robotic Surgical Systems:Computer-integrated platforms with articulated instrument arms and 3D visualization enable tremor-filtered suturing in confined anatomical spaces. Vancouver's academic hospitals prioritize da Vinci installations for prostatectomy volume growth; CADTH's parallel review pathway expedites provincial reimbursement for navigation-enabled configurations.
- Surgical Sutures:Absorbable and non-absorbable wound closure threads in braided or monofilament constructions.
- Surgical Instruments:Handheld graspers, retractors, and cutting tools in medical-grade stainless steel or titanium alloys.
Electrosurgical devices handle the majority of throughput in high-volume abdominal and thoracic procedures; robotic surgical systems are expanding most quickly on share as Ontario and Quebec expand dedicated minimally invasive surgery suites.
End User:
Facility accreditation status under provincial health authority frameworks determines procurement autonomy and capital equipment eligibility, creating tiered market access conditions.
- Hospitals:Acute-care institutions with 24-hour surgical services and sterile processing departments. Toronto's University Health Network and Vancouver Coastal Health anchor multi-site robotic surgery programs; aging sterile processing technician cohorts force automation investment in instrument tracking and washer-disinfector systems.
- Ambulatory Surgical Clinics:Standalone facilities performing same-day procedures without overnight admission capability. Alberta's chartered surgical facilities drive demand for compact laparoscopic towers; Health Canada's Class IIa streamlined registration reduces barrier-to-entry for disposable trocar and energy device suppliers.
- Outpatient Surgical Centers:Hospital-affiliated or independent facilities limited to low-complexity procedures.
- Specialty Clinics:Ophthalmology, dermatology, or plastic surgery focused practices with procedure-specific instrument needs.
Hospitals absorb the dominant capital allocation for robotic and energy platforms; ambulatory surgical clinics are climbing the fastest in disposable instrument procurement as case migration accelerates from inpatient settings.
Technology:
Surgeon training pipeline capacity and provincial fellowship program distribution determine adoption velocity for technique-intensive modalities.
- Minimally Invasive:Laparoscopic and thoracoscopic approaches through small incisions with camera visualization. Quebec's McGill University Health Centre and Toronto Western Hospital train the bulk of fellowship graduates; Health Canada MDR enforcement on reusable instrument sterilization validation pushes health authorities toward single-use trocar and specimen retrieval systems.
- Robotic-Assisted:Telemanipulation platforms with wristed instruments and motion scaling. British Columbia's concentrated urology and gynecology specialist density supports installation economics; CADTH's health technology assessment criteria reward systems with real-time haptic feedback and integrated energy delivery.
- Laparoscopic:Camera-assisted abdominal surgery through port-based access.
- Open Surgery:Traditional incision-based tissue exposure for complex or emergency procedures.
Minimally invasive technology commands the highest procedure volume across cardiac and colorectal applications; robotic-assisted approaches are gaining share fastest as simulator-based training expands beyond fellowship programs.
Application:
Provincial surgical waitlist priorities and population disease burden shape capital allocation toward specific service lines.
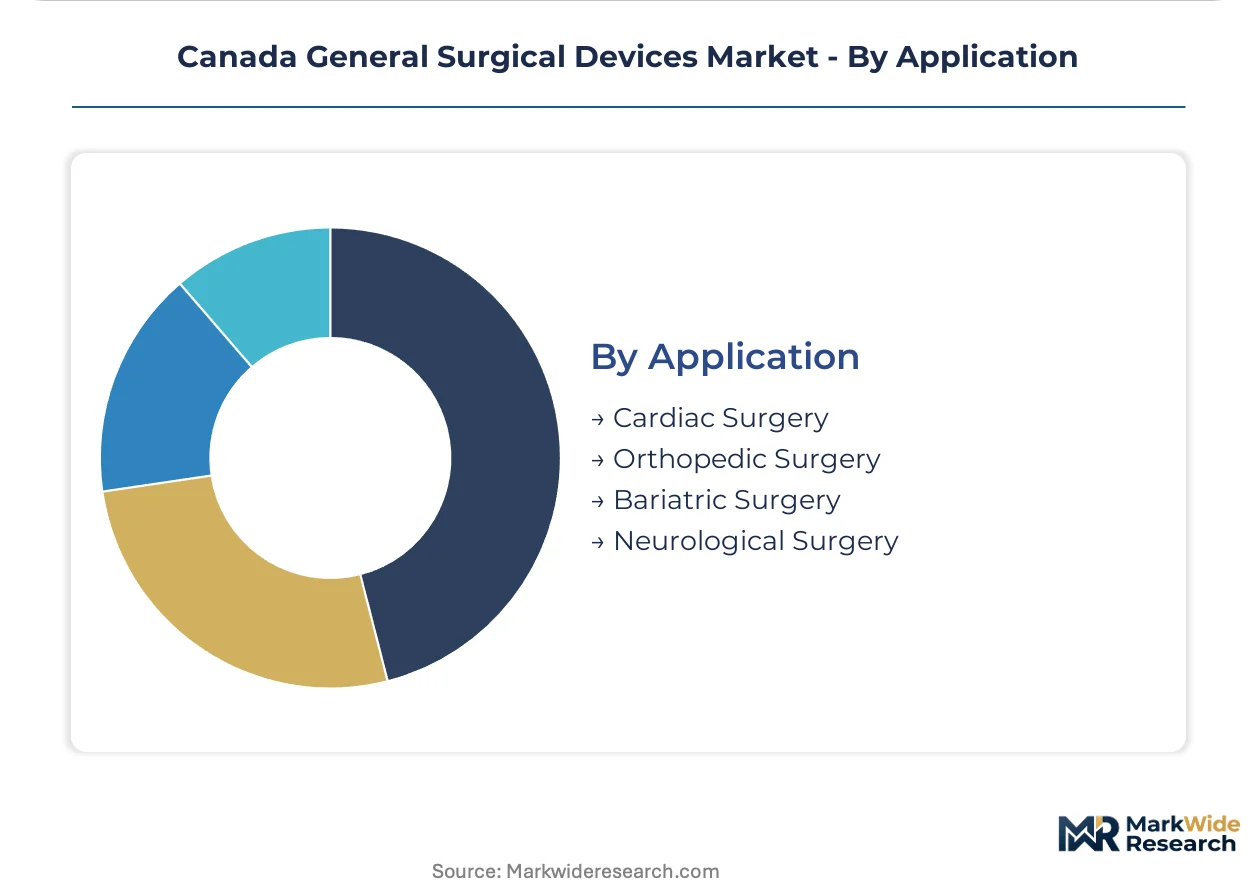
- Cardiac Surgery:Coronary artery bypass, valve repair, and aortic procedures requiring cardiopulmonary bypass support. Ontario's concentrated academic cardiac centers in Toronto and Ottawa drive electrosurgical and perfusion device procurement; aging demographics in British Columbia expand transcatheter valve replacement volumes.
- Bariatric Surgery:Gastric bypass and sleeve gastrectomy for metabolic disease management. Alberta's integrated obesity care pathways and Quebec's public coverage expansion accelerate laparoscopic stapler consumption; Health Canada's tightened biocompatibility standards for reusable graspers favor single-use articulating stapling platforms.
- Orthopedic Surgery:Joint replacement, trauma fixation, and sports medicine procedures.
- Neurological Surgery:Cranial and spinal procedures requiring microscopic or navigation-assisted visualization.
Cardiac surgery maintains the steepest equipment utilization intensity; bariatric surgery is expanding most quickly on case volume as provincial coverage mandates broaden eligibility criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and Quebec consume surgical devices at intensity levels unmatched elsewhere in Canada, while Prairie provinces and Atlantic Canada operate with narrower specialty coverage and lower per-capita procurement budgets.
Ontario
Toronto's University Health Network and Hamilton Health Sciences anchor the country's largest robotic surgery programs, driving concentrated demand for navigation-enabled platforms. Health Canada's Medical Devices Regulations enforcement tightens sterilization validation timelines for reusable instruments across the province's 150+ hospital sites. The Greater Toronto Area health cluster is consolidating procurement through Ontario Health's centralized tendering platform, compressing vendor margins for sutures and staplers.
Quebec
McGill University Health Centre and Centre hospitalier de l'Université de Montréal train the majority of Canadian minimally invasive surgery fellows, sustaining elevated laparoscopic instrument turnover. The province's public coverage expansion for bariatric procedures accelerates single-use articulating stapler consumption. Montreal's surgical device distribution hub serves Atlantic Canada through just-in-time logistics networks vulnerable to winter weather disruption.
British Columbia
Vancouver Coastal Health and Fraser Health prioritize urology and gynecology robotic installations, leveraging concentrated specialist density to justify capital deployment. Aging sterile processing technician cohorts in Victoria and Kelowna force automation investment in instrument tracking systems. The province's mountain geography fragments supply chain resilience, elevating inventory carrying costs for community hospitals in Interior Health.
Alberta
Calgary's chartered surgical facilities drive demand for compact laparoscopic towers suited to ambulatory settings, diverging from Ontario's hospital-centric procurement patterns. Alberta Health Services' integrated obesity care pathways standardize bariatric device specifications across Edmonton and Calgary zones. The province's oil-sector wage dynamics compress sterile processing technician recruitment, extending instrument turnaround times.
Atlantic Canada
Nova Scotia and New Brunswick surgical volumes trail national averages, creating first-mover positioning for mobile robotic-assisted surgery platforms serving dispersed populations. Health Canada's streamlined Class IIa registration reduces barrier-to-entry for disposable trocar suppliers targeting Halifax's outpatient expansion. Newfoundland and Labrador's isolation elevates emergency instrument rental premiums during supply disruptions.
Canada General Surgical Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding robotic and energy platform installations while mid-tier players compete on disposable instrument volume contracts. The market structure rewards manufacturers with dedicated Health Canada regulatory affairs infrastructure and established provincial reimbursement dossiers. Three archetypes dominate: diversified medical technology conglomerates with full surgical portfolios; electrosurgical and energy specialists with modality-specific expertise; and instrument fabricators competing on stainless steel alloy sourcing and sterilization validation services. Competitive moves concentrate on strategic partnerships with Ontario Health for centralized tendering access and vertical integration into polymer composite molding to secure trocar housing supply.
Among diversified conglomerates, Medtronic and Johnson & Johnson exemplify the integrated-platform archetype, leveraging broad electrosurgical and stapling portfolios to sustain presence in major teaching hospitals. Stryker Corporation occupies a position within the navigation-enabled systems tier, competing on integrated operating room ecosystems that combine instruments with real-time surgical guidance. These three anchors represent distinct strategic postures: portfolio breadth, minimally invasive platform leadership, and integrated OR infrastructure respectively.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker Corporation |
| Boston Scientific Corporation |
| B. Braun SE |
| CONMED Corporation |
| Olympus Corporation |
| Smith & Nephew |
| Integer Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Ontario Health's centralized procurement platform and major device manufacturers lock in multi-year supply access while capping price escalation for high-volume consumables across the province's hospital networks.
Pricing Analysis
Contract-based long-term offtake dominates procurement for robotic platforms and electrosurgical generators, with Ontario Health's volume aggregation compressing margins on sutures and staplers. Price differentiation hinges on Health Canada Class III certification tier and after-sales service bundling for navigation-enabled systems. Cost compression in single-use instrument tiers is intensifying because Health Canada's tightened biocompatibility standards accelerate validation expenses. Community hospitals in Atlantic Canada exhibit highest price sensitivity, while Toronto's academic centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Polymer composite molding capacity in the United States and Mexico constitutes the critical chokepoint for trocar housing production, exposing Canadian distributors to cross-border logistics disruption. Raw material sourcing draws from medical-grade 316L stainless steel suppliers in Germany, titanium alloy producers in Japan, and polymer resin manufacturers in the United States. Single-source vulnerability concentrates in North American molders serving just-in-time hospital networks. Distribution runs through Montreal's surgical device hub for Atlantic Canada and Vancouver's port infrastructure for Pacific supply routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across provincial health technology assessment pathways creates niche entry points as CADTH and Ontario Health diverge on reimbursement timelines for robotic-assisted platforms.
For Market Incumbents: Compound regulatory dossier advantages by deepening Health Canada liaison infrastructure while automating sterile processing validation services for hospital clients facing technician shortages. Electrosurgical commoditization from Chinese manufacturers demands backward integration into polymer composite molding to secure trocar supply. Capacity addition in Alberta's chartered surgical facility corridor captures case migration from inpatient settings. For New Entrants and Emerging Players: Mobile robotic-assisted surgery deployment for dispersed Atlantic Canada populations offers first-mover positioning where surgical volumes trail national benchmarks. Health Canada's streamlined Class IIa registration reduces barrier-to-entry for disposable trocar suppliers targeting Nova Scotia's outpatient expansion. Direct contracting with independent community hospitals bypasses Ontario Health's centralized tendering concentration. For Investors and Strategic Acquirers: Electrosurgical energy specialists with modality-specific IP portfolios represent attractive acquisition targets as dual-generator suites bifurcate procurement decisions. Long-term viability rests on software-as-a-medical-device navigation capabilities aligned with Health Canada's 2024 algorithm validation guidance. Watch CADTH's parallel review pathway expansion as the inflection signal for robotic platform reimbursement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Submission | Accelerates market access for energy-based platforms through rigorous clinical evidence pathways. |
| Hospital System Partnership | Secures robotic installation commitments from Toronto's University Health Network and Vancouver Coastal Health. |
| Sterile Processing Automation | Addresses Ontario's collapsed technician training pipeline through instrument tracking and washer-disinfector integration. |
| Polymer Composite Molding Acquisition | Captive supply of trocar housings mitigates single-source dependency on limited North American molders. |
| Reimbursement Strategy Alignment | Positions navigation-enabled systems for CADTH's expedited provincial listing pathway. |
Study Parameters
The analysis maps electrosurgical devices, robotic surgical systems, surgical sutures, and handheld instruments, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and Health Canada regulatory affairs leads. Primary interviews with sterile processing directors and provincial procurement officers combined with secondary validation against Health Canada Medical Devices Regulations filings, CADTH health technology assessment databases, Ontario Health tendering records, and ISO 13485 certification registries. Bottom-up procedure volume modeling and top-down provincial health expenditure triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product risk classification under Health Canada MDR, end-user facility accreditation tier, surgical technique intensity, and provincial health authority procurement framework. CAGRs derived from procedure volume elasticity to demographic aging and technology substitution curves, with specific inputs from cardiac surgery waitlist data and bariatric coverage expansion timelines.
Underlying assumptions cover Health Canada regulatory enforcement intensity, provincial reimbursement pathway stability, and sterile processing technician pipeline recovery, with deviation risk concentrated in polymer supply chain disruption and Class III evidentiary burden escalation. Practitioners should keep alternative scenarios live as CADTH assessment criteria and Health Canada software guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nasal Implant Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Human Enhancement Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Thrombectomy System Market
Medical Devices
EEG Electrodes Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Global Microkeratome Market