
 Body Repair Tools Market | 2026-2036
Body Repair Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Body Repair Tools Market Analytics
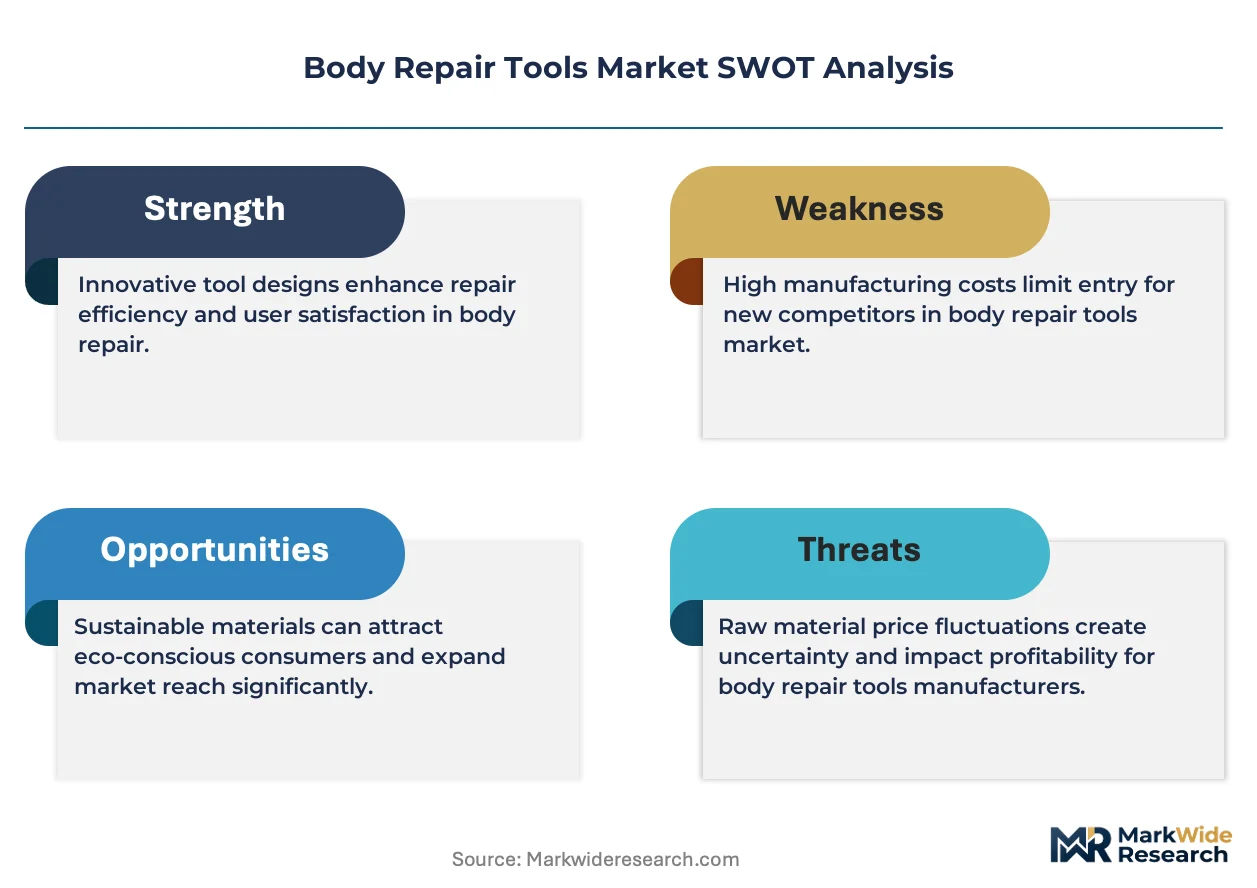
The EU Green Deal is realigning procurement priorities across European collision repair networks, compelling shops to replace energy-intensive frame racks and welding systems with lower-consumption alternatives. Robert Bosch GmbH leverages its industrial automation heritage to supply digitally integrated measuring and straightening equipment. Car-O-Liner anchors the premium frame correction segment through proprietary alignment software and certified training ecosystems. Chief Automotive Technologies specializes in aluminum repair workstations, a category gaining traction as OEM body-in-white designs shift toward lightweight materials.
Body repair tools encompass hand implements, power equipment, and diagnostic systems engineered to restore vehicle structural integrity, surface finish, and dimensional accuracy following collision damage or corrosion. Frame straightening benches typically achieve pulling forces exceeding ten tons while maintaining millimeter-level measurement precision through laser or ultrasonic reference systems. The Tool Type dimension shows wrenches and sockets commanding stable replacement demand from independent garages, while ratchet systems incorporating torque-limiting mechanisms capture premium positioning. The Material segment reveals aluminum and composite variants growing fastest as OEM repair procedures mandate substrate-specific tooling to prevent galvanic corrosion or fiber delamination.
The US Environmental Protection Agency shapes equipment standards through emissions controls on spray booths and solvent recovery systems, while OSHA governs worker exposure limits during abrasive blasting and welding operations. The EU's F-Gas Regulation restricts refrigerant handling equipment specifications, directly affecting climate control repair tool configurations. REACH compliance adds material disclosure requirements for coatings and adhesives applied with manufacturer-specified applicators. Stakeholders must evaluate how evolving OEM certification programs and right-to-repair legislation will redistribute tool purchasing authority between dealer networks and independent repair shops.
Market Dynamics
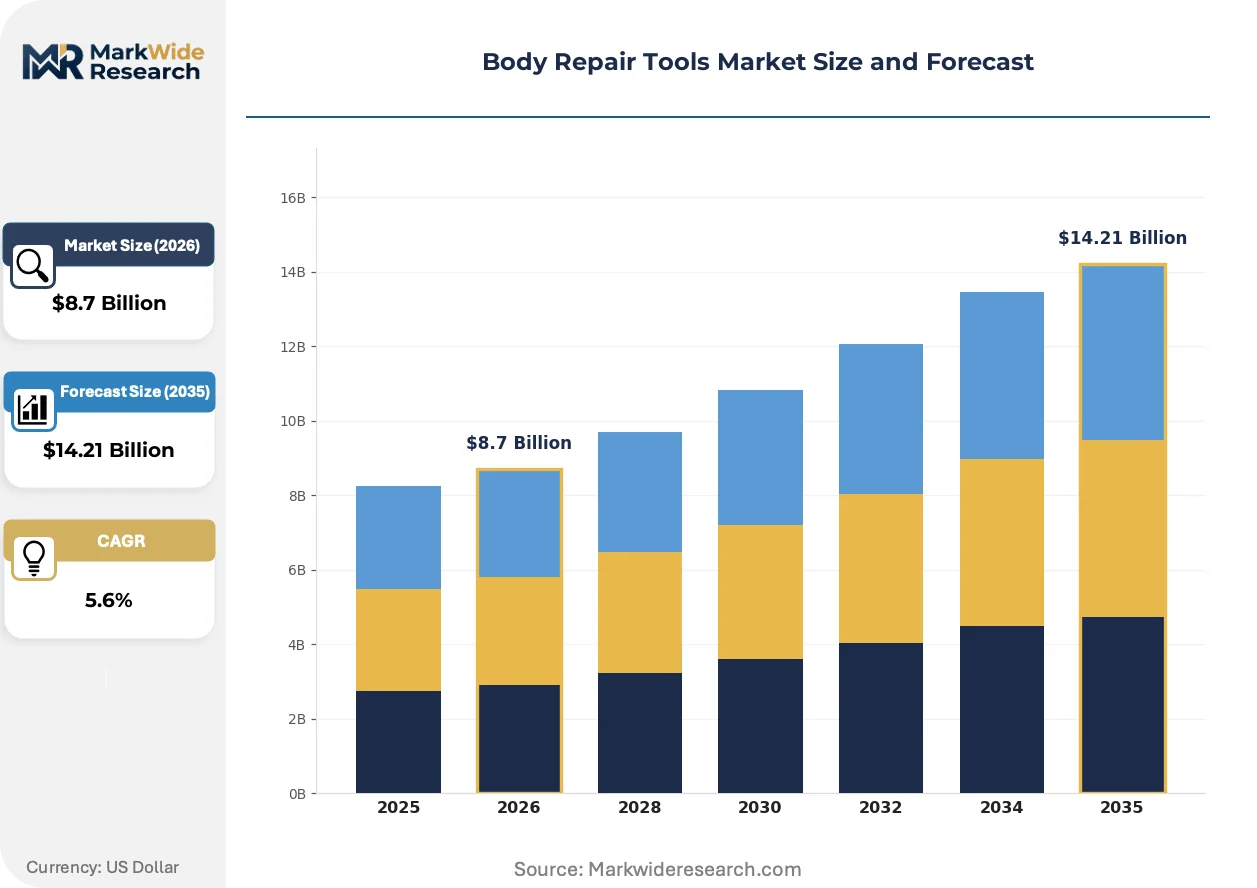
Collision repair shops face a structural inflection point as OEM certification programs tighten tool specifications and the EU Green Deal mandates energy-efficient equipment retrofits, compressing procurement cycles and elevating capital requirements.
Growth Catalysts
- EU Green Deal compliance deadlines:European collision networks must replace energy-intensive frame racks and welding systems with lower-consumption alternatives, accelerating replacement demand.
- Lightweight material proliferation:OEM body-in-white designs shift toward aluminum and carbon fiber composites, mandating substrate-specific tooling to prevent galvanic corrosion.
- Germany's automotive service corridor:Dense concentration of premium vehicle manufacturers and authorized repair networks concentrates procurement volume in specialized equipment.
Market Restraints
- High-grade steel input volatility:Frame straightening benches and pulling towers require specialized alloy compositions, exposing manufacturers to commodity price swings.
- REACH material disclosure complexity:Coatings and adhesives applied with manufacturer-specified applicators face escalating compliance documentation burdens.
- Manual tool substitution pressure:Basic hand implements face displacement from integrated power systems, narrowing addressable market for standalone wrench and socket producers.
Strategic Opportunities
- Right-to-repair legislative tailwinds:Proposed EU and US frameworks would redistribute tool purchasing authority from dealer networks toward independent shops, expanding addressable customer base.
- Diagnostic-straightening convergence:Laser measurement systems fused with automated frame correction software create premium service bundles commanding higher margins.
- Central and Eastern Europe penetration gaps:Poland and Czech Republic collision networks operate with dated equipment, presenting upgrade cycles as vehicle parc sophistication rises.
Industry Challenges
- Aluminum repair technician scarcity:OEM certification programs require specialized welding and substrate handling competencies that training infrastructure has not matched.
- Legacy frame rack integration friction:Shops with sunk capital in hydraulic systems face stranded asset risk when upgrading to digitally integrated measuring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Repair Tools Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Wrenches, Hammers, Sockets, Ratchets Material: Steel, Aluminum, Plastic, Composite Application: Automotive Repairs, Hardware Maintenance, Furniture Restoration, Appliance Repair End User: Professionals, DIY Enthusiasts, Repair Shops, Manufacturers |
| Companies Covered | Robert Bosch GmbH, Star-A-Liner, Roberlo, Car-O-Liner, Chief Automotive Technologies, SATA, Spies Hecker, ProSpot, Spiram, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Repair Tools Market Evolving Landscape
Tool manufacturers are embedding connectivity and automation into traditionally mechanical equipment, while regulatory pressure on energy consumption and chemical handling reshapes product roadmaps and shop investment priorities.
Battery-powered pulling and fastening systems are electrifying collision repair workflows, eliminating pneumatic line infrastructure and enabling mobile repair units. Independent garages in urban Germany and the Netherlands adopt these systems fastest due to space constraints. This shift is electrifying competitive positioning as cordless torque precision rivals shop-floor stationary equipment.
The EU F-Gas Regulation restricts refrigerant handling equipment specifications, forcing climate control repair tool reconfigurations across European service networks. Manufacturers must redesign recovery and charging stations to meet lower global warming potential thresholds. Aluminum repair workstations face the steepest compliance adjustments given their integration with HVAC systems in electric vehicle architectures.
Collision shops now bundle diagnostic scanning with structural repair quoting, unbundling the traditional separation between damage assessment and frame correction. This compresses the traditional three-visit customer journey into single-appointment resolution. Germany's insurer-certified repair networks demonstrate this pattern most visibly, pressuring independent shops to match throughput speed.
Body Repair Tools Market Segmentation
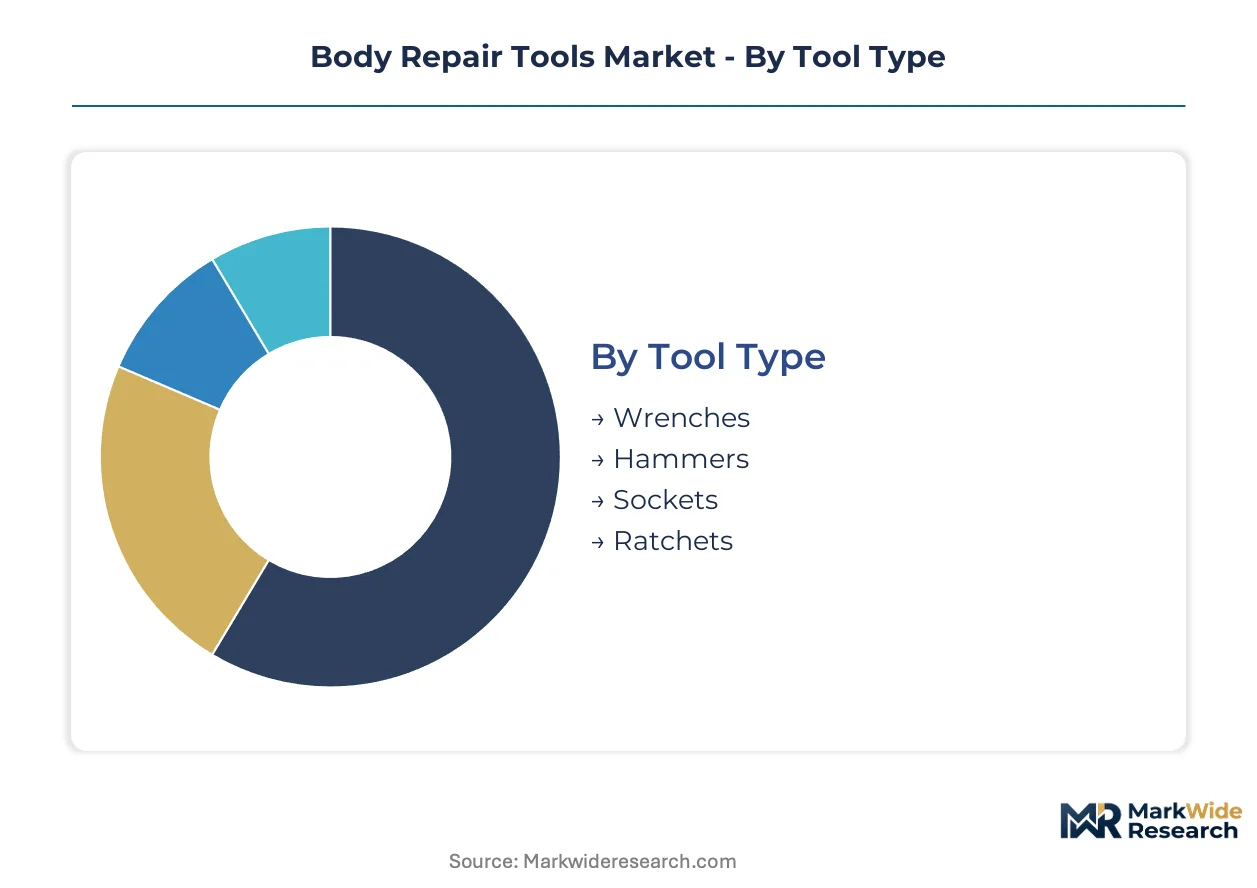
Tool selection in collision repair networks hinges on substrate compatibility, precision requirements, and certification mandates from vehicle manufacturers. Procurement patterns diverge sharply between high-investment frame correction systems and consumable hand implements, creating distinct margin profiles across the value chain.
Tool Type:
Capital intensity peaks with electronically controlled frame straightening benches, while manual implements require minimal upfront outlay yet generate recurring replacement cycles.
- Wrenches:Open-end and combination configurations dominate independent garage inventories across Germany's automotive service corridor. Torque-limiting variants capture premium positioning as OEM repair procedures mandate precise fastener tensioning to prevent structural compromise.
- Ratchets:Fine-tooth mechanisms with 72-tooth gear systems enable restricted-access work in modern engine bays where space constraints limit swing arc. Battery-powered cordless ratchets are displacing pneumatic alternatives in Dutch urban shops facing compressed footprints and noise restrictions.
- Hammers:Soft-face and dead-blow variants prevent surface marring during aluminum panel reshaping, a category gaining traction as lightweight material adoption accelerates.
- Sockets:Impact-rated and thin-wall configurations address high-torque fastening and confined-space access, with six-point designs reducing fastener rounding in high-volume shop environments.
Ratchets absorb the bulk of installed capacity; battery-powered variants are expanding most quickly.
Material:
Substrate selection determines corrosion resistance, weight handling, and OEM warranty compliance, with premium alloys commanding three-to-five-fold price multiples over standard grades.
- Steel:Chrome-vanadium and chrome-molybdenum alloys deliver tensile strength exceeding 600 MPa for frame pulling towers and structural repair fixtures. German OEM-certified shops specify these grades exclusively to maintain warranty indemnification.
- Aluminum:Non-ferrous implements prevent galvanic corrosion when contacting aluminum body panels, a requirement proliferating as OEM body-in-white designs shift toward lightweight architectures. Specialized welding and dent removal tools in this category face the steepest compliance adjustments under REACH material disclosure mandates.
- Composite:Carbon fiber-reinforced polymer handles reduce technician fatigue during extended repair cycles while maintaining dielectric properties for electric vehicle servicing.
- Plastic:Glass-filled nylon components insulate against thermal transfer and electrical conductivity in battery-electric vehicle repair environments.
Steel retains dominant share in heavy-duty applications; aluminum variants are climbing the fastest as substrate-specific mandates proliferate.
Application:
Volume concentration tracks collision frequency and fleet density, with automotive work commanding precision tolerances that other verticals rarely require.
- Automotive Repairs:Frame straightening, panel replacement, and structural realignment demand millimeter-level dimensional accuracy verified through laser or ultrasonic measurement systems. Germany's insurer-certified repair networks concentrate procurement volume in this vertical.
- Hardware Maintenance:Industrial facility upkeep utilizes overlapping tool categories with lower precision requirements, sourcing primarily through distributor networks rather than OEM-direct channels.
- Furniture Restoration:Woodworking-adapted variants prioritize surface protection and aesthetic preservation over structural load-bearing specifications.
- Appliance Repair:Compact form factors address domestic equipment disassembly, with insulated grips addressing consumer safety regulations.
Automotive Repairs commands the deepest tool investment per technician; Appliance Repair is gaining share fastest as service networks expand into white-goods maintenance.
End User:
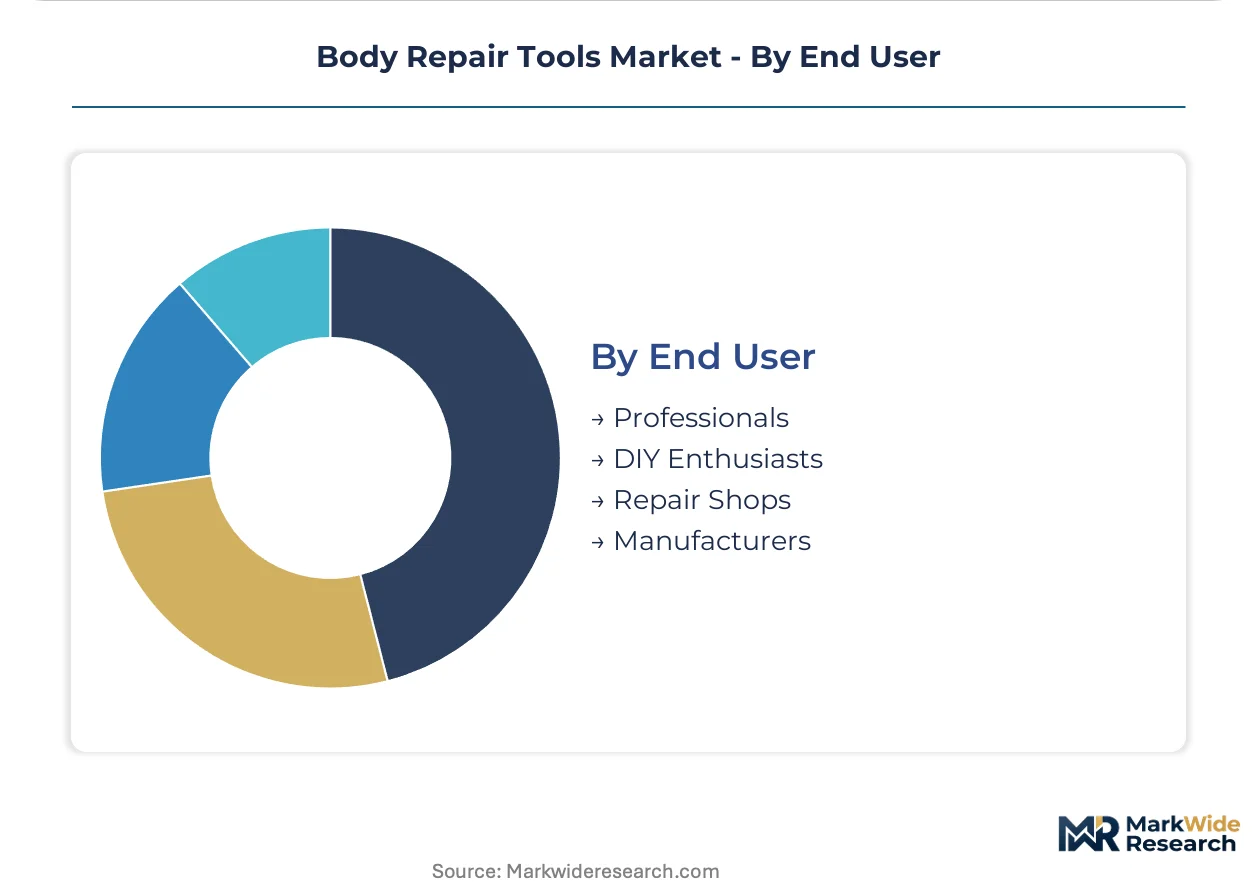
Purchasing authority and technical sophistication create four distinct customer archetypes with diverging price sensitivity and specification rigor.
- Repair Shops:Collision centers and mechanical garages drive procurement of integrated diagnostic-straightening systems, with EU Green Deal compliance deadlines accelerating equipment refresh cycles. These entities face the steepest capital requirements for frame racks and welding infrastructure.
- Professionals:Mobile technicians and dealership service personnel prioritize portability and OEM certification compatibility, favoring tool configurations that satisfy manufacturer training program requirements.
- DIY Enthusiasts:Consumer-grade socket sets and basic hand implements populate home garage inventories, with purchasing decisions driven by retail availability and brand recognition rather than technical specifications.
- Manufacturers:Assembly line tooling and warranty service provisioning operate through direct procurement relationships with volume pricing structures distinct from aftermarket channels.
Repair Shops account for the largest capital deployment; Professionals are expanding their tool expenditure fastest as mobile service models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tool manufacturing concentrates in Germany's industrial belt while consumption spreads across collision repair networks in North America and Western Europe. The production-consumption gap widens as Asian fabrication scales up standard hand implements for export markets.
United States
Collision repair volume drives procurement of frame straightening systems and aluminum-specific workstations across the Rust Belt and Sun Belt corridors. The EPA mandates emissions controls on spray booths and solvent recovery systems, reshaping equipment specifications for climate control repair tools. Detroit's automotive service ecosystem anchors premium tool demand as OEM certification programs tighten procurement standards for dealer-affiliated shops.
Germany
Precision manufacturing heritage supports domestic production of electronically controlled measuring benches and laser alignment systems for export markets. The EU Green Deal compels collision networks to replace energy-intensive hydraulic frame racks with lower-consumption alternatives, compressing replacement cycles. Bavaria's automotive service corridor concentrates procurement volume from insurer-certified repair networks serving premium vehicle parcs.
China
Domestic vehicle fleet expansion generates collision repair tool demand across tier-one and tier-two cities, with state-backed infrastructure investment supporting workshop modernization. GB standards and MIIT technical regulations govern equipment safety certifications for imported frame correction systems. The Yangtze River Delta manufacturing cluster produces cost-optimized hand implements and power tools for regional distribution and re-export.
Japan
Lightweight material adoption in domestic OEM body-in-white designs accelerates substrate-specific tooling procurement from specialized suppliers. METI industrial policy and JIS standards establish quality benchmarks for collision repair equipment entering the aftermarket. The Nagoya-Toyota industrial corridor maintains dense concentrations of OEM-certified repair facilities with stringent tool specification requirements.
United Kingdom
Independent garage networks drive replacement demand for torque-limiting ratchets and impact-rated sockets as vehicle complexity rises. REACH compliance and CSRD disclosure mandates add documentation burdens for coatings and adhesives applied with manufacturer-specified applicators. The Midlands automotive manufacturing belt supports specialized tool distribution channels serving both OEM warranty operations and aftermarket collision repair.
Body Repair Tools Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with automotive heritage alongside specialized frame correction specialists. Market concentration remains moderate, with premium segments showing tighter vendor consolidation than commodity hand implement categories. Two archetypes dominate: integrated measurement-straightening system providers and substrate-specific workstation specialists. Capacity expansion and strategic technology licensing represent the primary competitive vectors as shops seek digitally integrated platforms.
Among German-based industrial conglomerates, Robert Bosch GmbH exemplifies the diversified archetype leveraging automation heritage across collision repair equipment categories. Car-O-Liner and Chief Automotive Technologies occupy positions within the specialized tier, representing contrasting approaches to frame correction and substrate-specific repair ecosystems. These three anchors illustrate how competitive positioning splits between broad industrial capability and focused technical specialization.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Star-A-Liner |
| Roberlo |
| Car-O-Liner |
| Chief Automotive Technologies |
| SATA |
| Spies Hecker |
| ProSpot |
| Spiram |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists across Germany's industrial belt maintain disciplined pricing through captive production of high-grade alloy components, insulating frame correction equipment from commodity volatility while passing selective premiums to OEM-certified repair networks.
Pricing Analysis
Margin tightening in electronically controlled frame benches reflects alloy input volatility and REACH compliance documentation burdens. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression accelerates in manual hand implements as battery-powered systems displace pneumatic alternatives. Independent garages in compressed urban footprints show highest price sensitivity; insurer-certified networks absorb premium positioning for warranty indemnification.
Supply Chain Analysis
OEM certification programs and EU Green Deal mandates gate supplier qualification through energy-efficiency benchmarks and material disclosure protocols. Manufacturing concentrates in Germany, China, and the United States, with the Yangtze River Delta producing cost-optimized power tools and the Rust Belt anchoring heavy-duty frame system fabrication. Specialized alloy compositions for pulling towers draw from chrome-vanadium and chrome-molybdenum supply chains. Single-source vulnerability concentrates in laser measurement system optics. Distribution runs through OEM-direct channels for certified equipment and distributor networks for consumable implements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding competency scarcity props pricing for aluminum repair workstations, constraining supply expansion as OEM lightweight material mandates accelerate.
For Market Incumbents: Acquire distressed aluminum repair training infrastructure to lock technician certification pipelines before right-to-repair legislation redistributes purchasing authority. Deepen backward integration into high-grade alloy forging to neutralize commodity volatility threatening frame bench margins. Battery-powered system substitution and emerging Polish collision network upgrades represent priority threat surfaces. For New Entrants and Emerging Players: Launch via mobile repair unit equipment bundles targeting Dutch urban shops facing footprint compression and noise restrictions. Central and Eastern European collision networks in Poland and Czech Republic offer the most penetrable white-space, with dated hydraulic frame racks stranding incumbent capital. Position through cordless torque precision rivaling stationary shop-floor specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor substrate-specific workstation specialists in Germany's automotive service corridor, where EU Green Deal retrofit deadlines compress replacement cycles. Five-to-ten year viability hinges on diagnostic-straightening convergence capabilities. Monitor right-to-repair legislative progression as inflection signal for independent shop purchasing authority expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Training Ecosystem Acquisition | Locks technician pipelines as OEM aluminum repair mandates outpace training infrastructure. |
| Battery-Powered System Portfolio Expansion | Captures Dutch and German urban shops eliminating pneumatic infrastructure. |
| Central and Eastern European Distribution Buildout | Accesses Poland and Czech Republic upgrade cycles as vehicle parc sophistication rises. |
| Diagnostic-Straightening Software Integration | Commands premium bundling margins through laser measurement and automated correction fusion. |
| REACH-Compliant Material Disclosure Investment | Preempts regulatory friction on coatings and adhesives applicator specifications. |
Research Methodology
Document review covered equipment manufacturer technical specifications, EU regulatory filings, and collision repair network procurement records, complemented by interviews with collision center operations directors, OEM certification program managers, aftermarket distribution channel heads, and alloy component procurement leads. Secondary sources included EPA emissions control documentation, ECHA REACH substance databases, and customs trade flow records. Bottom-up technician tool expenditure estimates triangulated against top-down equipment manufacturer shipment data.
Cross-referencing historical replacement cycle patterns with panel input from equipment procurement committees established the analytical framework across the projection horizon. Segmentation dimensions modeled include tool type, substrate material, application vertical, and end-user archetype. CAGRs derived from equipment refresh cycle compression under EU Green Deal mandates and lightweight material adoption curves. Industry-specific inputs incorporated OEM body-in-white design roadmaps and insurer-certified network expansion rates.
Aluminum repair technician training capacity shortfalls, right-to-repair legislative timing, and alloy commodity price spikes are the dominant revision risks to modeled equipment demand. Forecasts reflect documented assumptions on certification program proliferation and energy-efficiency retrofit compliance rates. A model refresh is warranted upon material change in EU Green Deal enforcement timelines or OEM lightweight material commitment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market