
 Body in White (BIW) Market | 2026-2036
Body in White (BIW) Market Size, Share, and Industry Trends Forecast 2026-2036
Body in White (BIW) Market Outlook
Aftermarket service revenue is narrowing as OEMs extend platform lifecycles and consolidate supplier bases. Magna International Inc. leverages its stamping and assembly integration to capture recurring tooling contracts. Gestamp Automoción anchors European electric vehicle programs through hot-forming capacity in Spain and Germany. Thyssenkrupp AG competes on high-strength steel grades that balance crash performance with weight reduction targets.
Body in White denotes the welded sheet-metal shell of a vehicle before painting, comprising closures, underbody, side panels, and roof structures typically formed from cold-rolled steel or 6xxx-series aluminum alloys through progressive die stamping and robotic resistance welding. Its primary purpose is to provide structural integrity, occupant protection, and dimensional precision for downstream assembly operations. Steel retains dominance in mass-market passenger vehicles where stamping throughput and repair infrastructure remain mature, while aluminum represents the fastest-expanding material type as electric vehicle platforms prioritize range-extending weight reduction. Composite segments occupy niche positions in low-volume performance applications where tooling amortization constraints limit broader adoption.
The U.S. NHTSA and EPA jointly enforce fuel economy and emissions standards that directly shape BIW material selection and lightweighting investment cycles. Europe's REACH regulation and CE marking requirements for automotive components restrict certain coating chemistries and mandate traceable supply chain documentation for structural materials. China's MIIT administers GB standards for vehicle safety and energy consumption that push domestic OEMs toward advanced high-strength steel and aluminum hybrid architectures. Stakeholders must monitor how evolving crash-test protocols and battery protection requirements for electric vehicle platforms reshape load-path engineering and joining technology roadmaps.
Market Dynamics
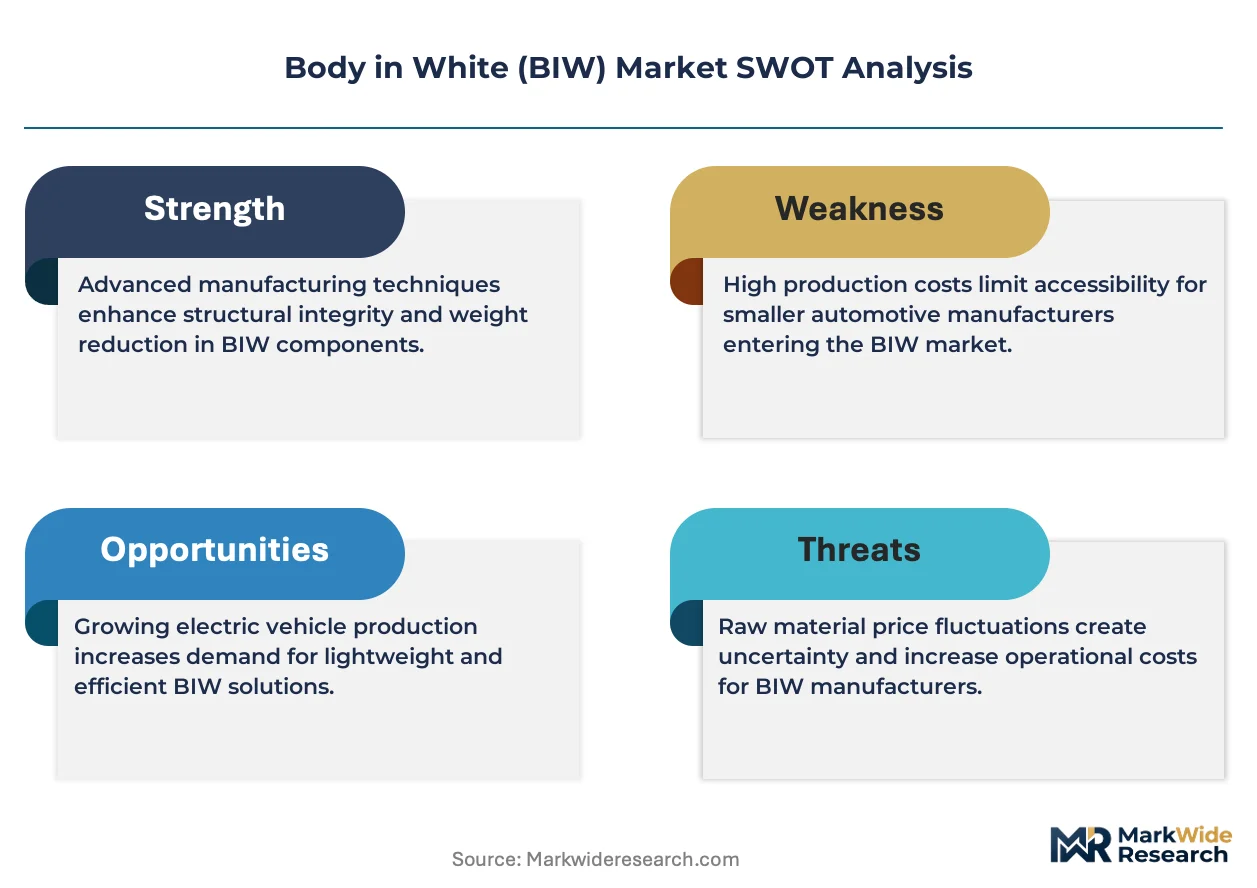
The Body in White market faces a structural pivot where electric vehicle platform architectures are forcing material substitution at scale, compressing the traditional steel-aluminum cost gap while rewiring supplier relationships around battery protection engineering.
Growth Catalysts
- Europe's F-Gas Regulation:The phasedown of hydrofluorocarbon-based forming lubricants accelerates dry stamping and hot-forming process adoption across German and Spanish production corridors.
- Crash-performance mandates:NHTSA's updated side-pole impact protocols drive OEM specification of third-generation advanced high-strength steel grades in side-impact beams and roof rails.
- Aluminum 6xxx-series expansion:Extrusion-hybrid architectures for battery enclosures concentrate new capacity investment around Shanghai and Detroit metropolitan clusters.
Market Restraints
- Scrap aluminum price volatility:Secondary aluminum ingot costs swing with LME primary pricing, squeezing margin stability for closed-loop recycling-dependent suppliers.
- Hot-forming press concentration:Capable equipment suppliers cluster in Germany and Japan, creating single-source risk for OEMs scaling electric vehicle body production.
- Multi-material joining complexity:Dissimilar metal galvanic corrosion limits steel-aluminum hybrid joint durability, constraining architecture flexibility.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic OEMs receive production-linked incentives for localizing advanced stamping capacity, opening supplier establishment windows in Pune and Chennai.
- Battery tray structural integration:Cast aluminum battery enclosures merge with floor pan assemblies, eliminating separate subframe welding stages.
- Digital twin deployment:Real-time springback prediction during progressive die forming reduces tooling iteration cycles from months to weeks.
Industry Challenges
- Simulation engineer scarcity:Finite element analysis talent for multi-stage forming simulation commands premium wages in Stuttgart and Wolfsburg labor markets.
- Tooling amortization compression:Shortened electric vehicle platform lifecycles strain die investment recovery, forcing modular die design adoption.
- Cross-certification friction:Divergent GB standards and EPA crash-test protocols require parallel validation programs for export-bound architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body in White (BIW) Market |
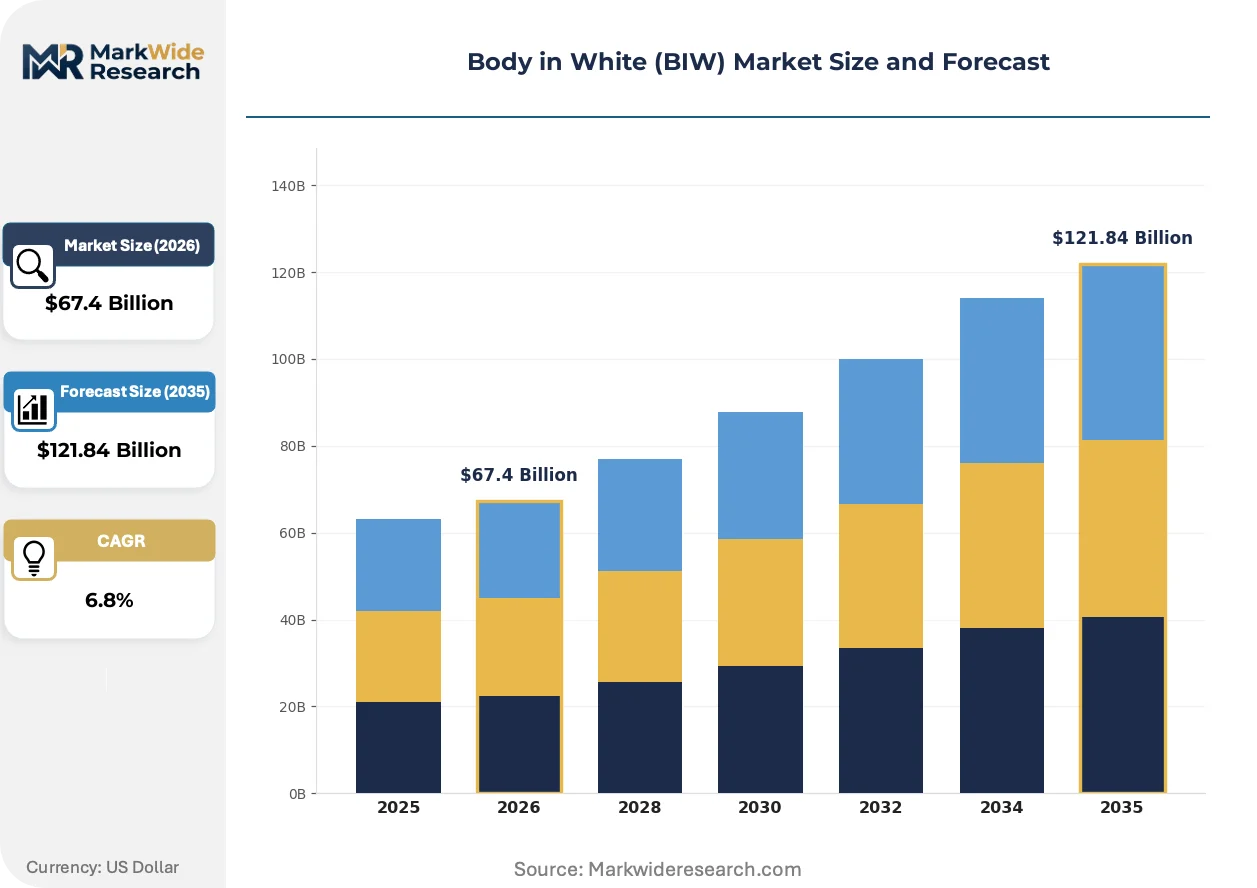
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $121.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Magnesium, Composite Manufacturing Process: Stamping, Welding, Casting, 3D Printing Application Type: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, SUVs End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Benteler International AG, Aisin Seiki Co., Ltd., Magna International Inc., ArcelorMittal, Thyssenkrupp AG, Gestamp Automoción, Kirchhoff Automotive, Martinrea International, Tower International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body in White (BIW) Market Strategic Shifts
Process innovation is compressing the traditional stamping-welding sequence while regulatory chemistry restrictions and buyer consolidation reshape competitive requirements for structural component suppliers.
Tailored blank laser welding is collapsing the distinction between structural and closure panel material grades. OEMs specify patchwork blanks with strength gradients across a single stamped component, eliminating reinforcement brackets and downstream spot welds. Tier-1 stampers in Bavaria and Michigan deploy this capability to capture integrated assembly contracts previously held by welding specialists.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings force OEMs to validate trivalent chrome and zirconium-based pretreatments for aluminum-intensive architectures. The regulation compresses qualification timelines for new coating chemistries. Suppliers serving Swedish and Dutch electric vehicle programs face accelerated corrosion-testing protocols.
Buyer consolidation among electric vehicle pure-plays concentrates stamping contract volumes with fewer Tier-1 suppliers possessing full-process integration. Legacy multi-tier supply structures fragment as OEMs direct-source hot-formed B-pillars and battery tray extrusions. This pattern concentrates procurement leverage in Shanghai and Austin metropolitan manufacturing zones.
Body in White (BIW) Market Segmentation
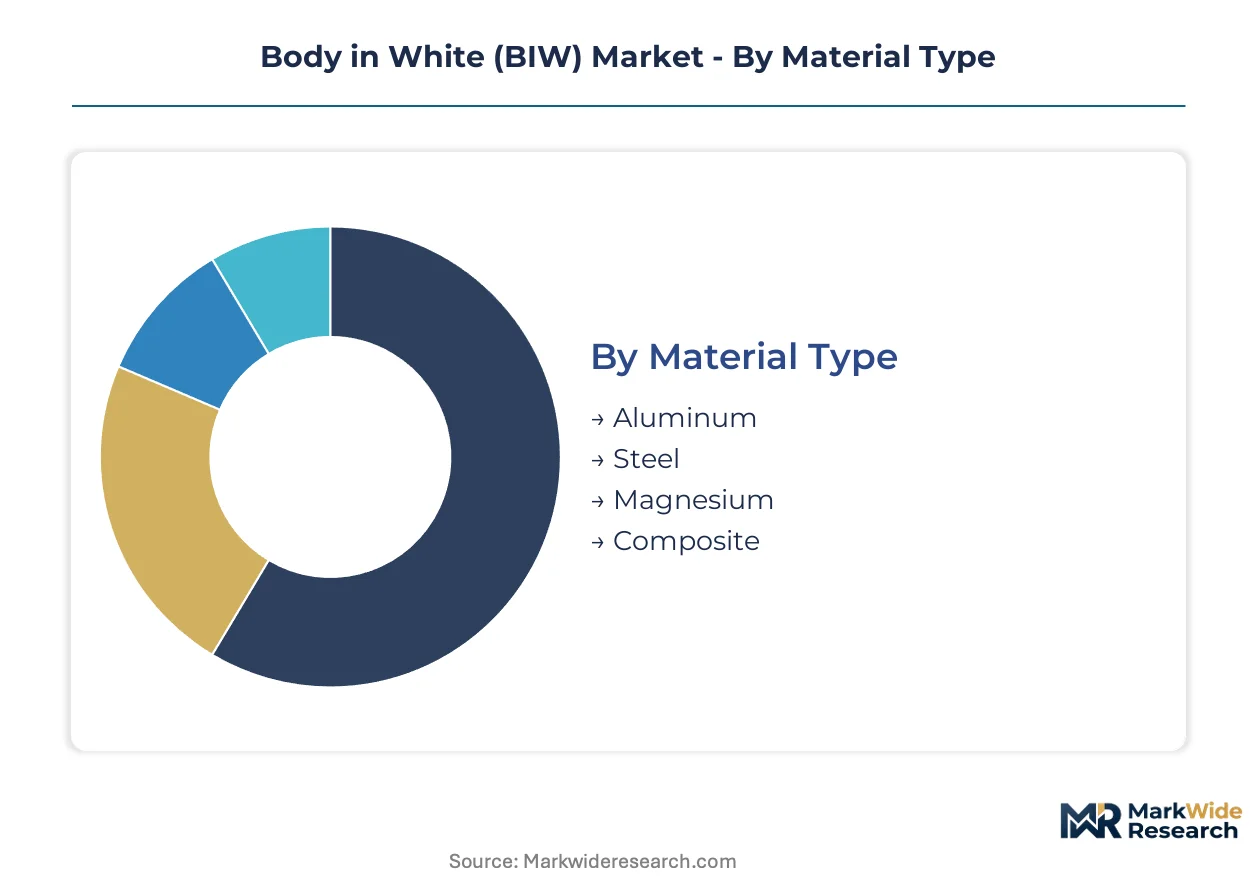
Material selection and manufacturing process choices in Body in White structures cascade through tooling investment, cycle times, and platform flexibility. Segmentation reveals where electric vehicle architectures are compressing traditional material hierarchies and forcing process consolidation among suppliers.
Material Type:
Cold-rolled steel cycles through stamping lines in under six seconds per hit, while aluminum and composite panels demand extended forming windows and specialized lubrication systems. Magnesium occupies the slowest throughput tier due to corrosion protection requirements and temperature-controlled handling protocols.
- Aluminum:6xxx-series alloys dominate extrusion-hybrid battery enclosures and closure panels where weight reduction extends electric vehicle range. Demand concentrates in Detroit and Shanghai metropolitan clusters where OEMs operate integrated aluminum stamping and hemming lines for electric vehicle platforms.
- Steel:Third-generation advanced high-strength grades (980 MPa tensile plus) form side-impact beams and roof rails under NHTSA's updated side-pole protocols. German and Japanese OEMs specify these grades for mass-market passenger vehicles where repair infrastructure and stamping throughput remain decisive.
- Magnesium:AZ91D and AM60B alloys serve instrument panel cross-car beams and steering wheel armatures in premium European nameplates where gram-level weight savings justify material cost premiums and specialized corrosion coatings.
- Composite:Carbon fiber reinforced polymer (CFRP) and sheet molding compound (SMC) occupy low-volume performance applications including roof panels and hood assemblies where tooling amortization constraints limit broader adoption.
Steel dominates installed base across legacy platforms. Aluminum is where expansion concentrates as electric vehicle production scales.
Manufacturing Process:
Process selection tracks material compatibility and joint durability requirements, with capital intensity varying by an order of magnitude between conventional stamping and emerging additive approaches.
- Stamping:Progressive die and transfer press operations form the throughput backbone of high-volume body production, with tailored blank laser welding collapsing multi-part assemblies into single stampings. Bavarian and Michigan Tier-1 suppliers deploy this capability to capture integrated contracts.
- Welding:Robotic resistance spot welding retains dominance in steel-intensive architectures, while friction stir and laser welding expand for aluminum joint integrity. Spanish and German production corridors concentrate hot-forming press capacity for hardened steel B-pillars.
- Casting:High-pressure die casting merges battery tray structures with floor pan assemblies, eliminating separate subframe welding stages in electric vehicle platforms.
- 3D Printing:Directed energy deposition and binder jetting produce low-volume structural prototypes and repair tooling, with limited production penetration due to surface finish and build speed constraints.
Welding commands the largest installed equipment base. Casting is climbing the fastest as structural integration eliminates assembly stages.
Application Type:
Application segmentation reflects divergent crash-performance targets, production volumes, and material substitution timelines across vehicle categories.
- Passenger Vehicles:Steel-intensive unibody architectures prioritize repair economics and stamping throughput in mass-market segments, with selective aluminum adoption in hood and decklid closures.
- Commercial Vehicles:Ladder-frame and cab structures emphasize durability under cyclic loading, with high-strength steel grades specified for chassis rails and crossmembers.
- Electric Vehicles:Extrusion-hybrid floor pans and cast aluminum battery enclosures prioritize range-extending weight reduction, with crash-load paths engineered around battery protection requirements.
- SUVs:Higher beltlines and roof structures drive advanced high-strength steel specification for rollover protection, with aluminum closure panels offsetting powertrain mass in electrified variants.
Passenger vehicles anchor legacy demand volumes. Electric vehicles represent the steepest expansion trajectory as platform architectures proliferate.
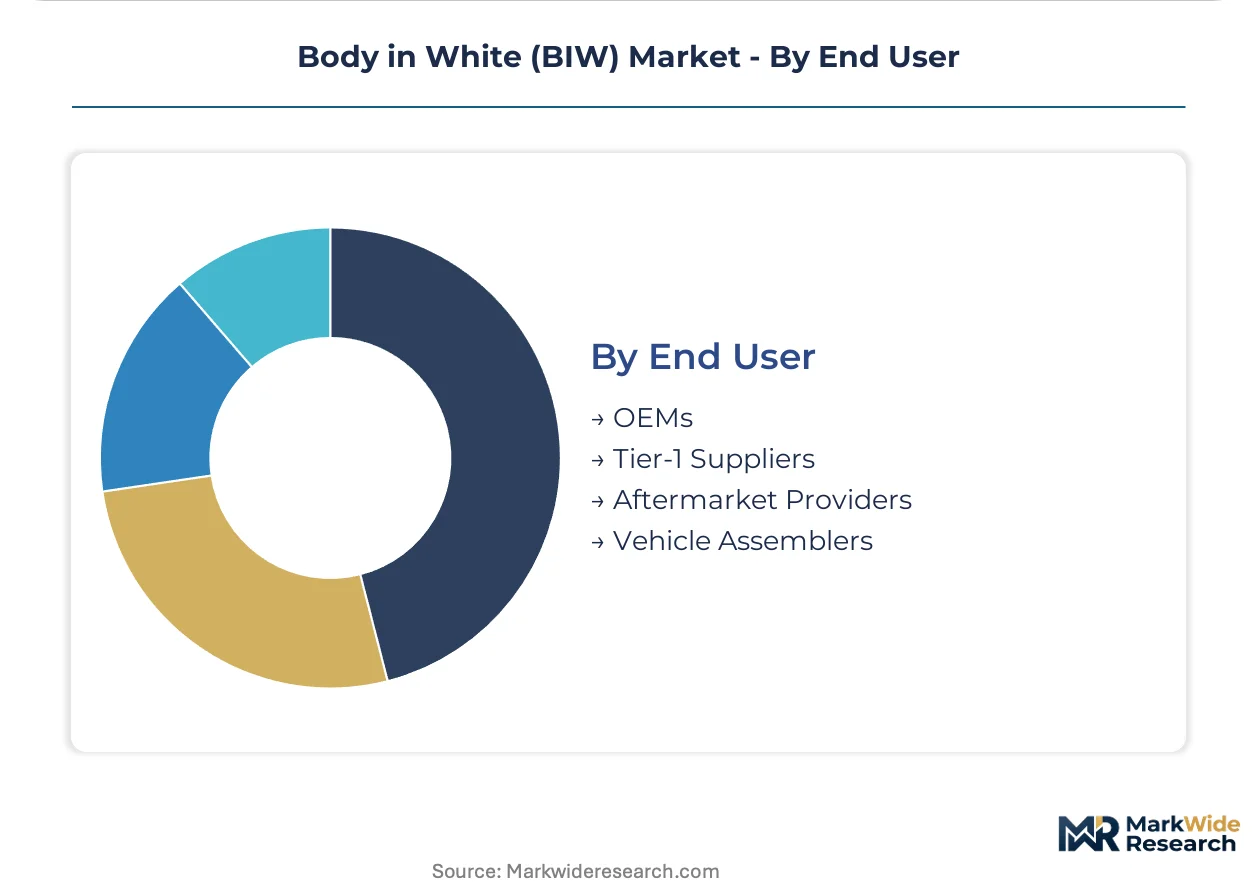
End User:
End user segmentation tracks procurement consolidation as OEMs direct-source critical structural components and compress supplier tiers.
- OEMs:Integrated stamping and welding facilities in Germany, China, and the United States retain strategic control over body architecture and platform flexibility, with selective outsourcing of closure panels.
- Tier-1 Suppliers:Full-process integrators capture hot-formed structural assemblies and aluminum extrusion contracts as OEMs consolidate procurement leverage.
- Aftermarket Providers:Service revenue narrows as extended platform lifecycles and consolidated supplier bases reduce replacement part turnover.
- Vehicle Assemblers:Contract manufacturers and electric vehicle pure-plays source complete body-in-white modules from system suppliers to minimize capital deployment.
OEMs dominate strategic component sourcing. Tier-1 suppliers are gaining share fastest as integration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity for advanced high-strength steel grades, while OEMs in India and Mexico prioritize stamping throughput economics over material substitution premiums. This demand-elasticity gradient shapes where capital deploys across the value chain.
Germany
OEM procurement of hot-formed B-pillars and aluminum closure panels concentrates around Wolfsburg and Stuttgart production corridors. The F-Gas Regulation accelerates dry stamping process adoption across Bavarian stamping facilities. Gestamp Automoción anchors European electric vehicle programs through dedicated hot-forming capacity in Spain and Germany.
China
Domestic electric vehicle OEMs specify 6xxx-series aluminum extrusion-hybrid architectures for battery enclosures at scale. MIIT-administered GB standards for vehicle safety push manufacturers toward advanced high-strength steel and aluminum hybrid designs. Shanghai and Detroit metropolitan clusters concentrate new aluminum stamping and hemming line investments.
United States
Integrated stamping and welding facilities in Michigan and Ohio retain strategic control over body architecture for mass-market passenger vehicles. NHTSA's updated side-pole impact protocols drive specification of third-generation advanced high-strength steel grades in side-impact beams. Detroit-area Tier-1 suppliers deploy tailored blank laser welding to capture integrated assembly contracts.
India
Domestic OEMs receive production-linked incentives under the PLI scheme for automotive for localizing advanced stamping capacity. BIS standards for vehicle safety and energy consumption push gradual adoption of high-strength steel architectures. Pune and Chennai manufacturing zones attract supplier establishment as platform localization accelerates.
Japan
OEMs specify third-generation advanced high-strength steel grades for mass-market unibody platforms where repair infrastructure maturity remains decisive. METI industrial policy supports lightweighting R&D consortiums targeting next-generation forming technologies. Toyota City and Nagoya production corridors concentrate robotic resistance welding capacity for steel-intensive architectures.
Body in White (BIW) Market Competitive Environment
Capability concentration sits with Tier-1 integrators possessing full-process stamping, hot-forming, and aluminum joining expertise; scale advantage sits with diversified automotive suppliers operating across multiple OEM platforms. The vendor base organizes around three strategic archetypes: full-process integrators capturing structural assembly contracts, steel-centric specialists defending high-throughput stamping positions, and aluminum-focused entrants scaling battery enclosure capabilities. Dominant competitive moves include backward integration into tooling design and geographic expansion toward electric vehicle production clusters.
Within the full-process integrator tier, Magna International Inc. and Gestamp Automoción exemplify suppliers capturing recurring tooling contracts through stamping and assembly integration. Among steel-centric specialists, ArcelorMittal and Thyssenkrupp AG occupy positions balancing crash performance with weight reduction targets for mass-market platforms. Aisin Seiki Co., Ltd. represents the diversified industrial conglomerate archetype leveraging captive component demand across Toyota Group platforms.
| Leading Market Players |
|---|
| Benteler International AG |
| Aisin Seiki Co., Ltd. |
| Magna International Inc. |
| ArcelorMittal |
| Thyssenkrupp AG |
| Gestamp Automoción |
| Kirchhoff Automotive |
| Martinrea International |
| Tower International |
| Others |
Value Chain & Pricing Dynamics
Wolfsburg and Stuttgart production corridors concentrate hot-forming press capacity for advanced high-strength steel grades, concentrating pricing leverage among German Tier-1 suppliers serving OEM platform engineering teams. This geographic clustering of specialized equipment creates asymmetric bargaining power where tooling amortization cycles and material grade certification costs flow downstream into long-term contract structures.
Pricing Analysis
Long-term offtake agreements dominate structural component procurement, with OEMs locking in multi-year pricing for hot-formed B-pillars and aluminum closure panels to secure capacity amid equipment scarcity. Price differentiation rests on material certification tiers and volume scale, with GB-standard qualified suppliers commanding premiums over uncertified competitors in Chinese electric vehicle programs. Cost compression in steel-intensive segments is intensifying because shortened platform lifecycles compress die investment recovery windows. Fleet procurement teams at electric vehicle pure-plays demonstrate lowest price sensitivity, prioritizing crash-performance validation speed over per-unit cost.
Supply Chain Analysis
Export-control regimes on friction stir welding equipment and hot-forming press technology limit capacity expansion outside Germany and Japan, constraining supply elasticity for aluminum-intensive architectures. Raw material flows draw from primary aluminum smelters in China, high-strength steel mills in Germany, and secondary aluminum recyclers in the United States. Single-source vulnerability concentrates around Japanese equipment suppliers for hardened steel B-pillar production lines. Distribution runs through OEM-integrated stamping facilities in Michigan, Bavaria, and Shanghai metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform proliferation fragments procurement volumes across multiple battery enclosure architectures, creating specialist niches for suppliers possessing aluminum extrusion and cast structural integration capabilities.
For Market Incumbents: Pre-empt margin erosion from pure-play electric vehicle OEMs by backward integration into tooling design software and modular die systems that compress iteration cycles. Anchor capacity expansion in Detroit and Shanghai clusters where battery tray structural integration demand concentrates. Defend against aluminum-focused entrants by accelerating trivalent chrome pretreatment qualification under REACH Annex XVII timelines. For New Entrants and Emerging Players: India's PLI scheme automotive corridors around Pune and Chennai offer white-space penetration for advanced stamping capacity localization. Target battery tray casting integration as the most penetrable segment, where OEMs seek to eliminate separate subframe welding stages. Pursue joint development agreements with domestic electric vehicle platforms requiring GB-standard crash validation. For Investors and Strategic Acquirers: Long-term, this sits as a process-technology consolidation play because electric vehicle architectures are collapsing traditional stamping-welding sequences into fewer integrated production stages. Acquire full-process integrators possessing hot-forming, aluminum joining, and digital twin simulation capabilities. Watch for inflection when NHTSA announces updated battery protection protocols that reshape load-path engineering requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Forming Capacity Expansion | Captures recurring tooling contracts from OEMs scaling electric vehicle B-pillar production in Germany. |
| Aluminum Extrusion Integration | Merges battery enclosure structures with floor pan assemblies for Shanghai-based electric vehicle platforms. |
| Digital Twin Deployment | Compresses springback prediction cycles from months to weeks for Michigan stamping operations. |
| REACH-Compliant Coating Qualification | Validates trivalent chrome pretreatments for Swedish electric vehicle aluminum architectures. |
| Modular Die Design Adoption | Addresses tooling amortization compression from shortened electric vehicle platform lifecycles. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement directors, hot-forming equipment operators, and aftermarket service managers anchored the qualitative base for this analysis. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and NHTSA crash-test protocol documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the analytical approach, with segmentation dimensions spanning material type, manufacturing process, vehicle propulsion architecture, and regional production cluster. CAGRs derived from installed capacity trajectories, platform lifecycle assumptions, and material substitution elasticity curves. Forecast inputs incorporated electric vehicle production ramp schedules and regulatory compliance timelines for F-Gas Regulation phasedown.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery enclosure pure-plays or aluminum casting specialists would shift outcomes beyond modeled ranges. Material shifts in NHTSA battery protection protocols or REACH coating chemistry restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Steering Rack Market