
 Car Detailing Products Market | 2026-2036
Car Detailing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Car Detailing Products Market Analytics
The capital-intensity divergence between automated production lines and hand-batch compounders is redrawing competitive tiers in car detailing products. Meguiar's leverages its vertically integrated California manufacturing campus to control raw material costs across wax and polish lines. 3M anchors its position through captive resin synthesis that feeds sealant formulations. Griot's Garage competes on a narrower SKU base but sustains premium pricing through direct-to-consumer channel control.
Car detailing products encompass surface preparation, protection, and finishing compounds formulated with silicones, abrasives, solvents, and polymeric resins to restore or enhance vehicle appearance. Sealants typically incorporate synthetic cross-linked polymers that bond at the molecular level to paint clear coats, delivering durability measured in months rather than weeks. Wax commands the largest revenue share among product types due to entrenched consumer familiarity and lower per-unit price points, though sealants generate superior margins as professional detail shops shift toward longer-interval protection cycles. Interior application segments now outpace exterior growth in certain channels as fleet owners prioritize cabin sanitization protocols alongside aesthetic maintenance.
The EPA governs volatile organic compound limits under 40 CFR Part 59, forcing reformulation of solvent-heavy cleaners and degreasers toward waterborne alternatives. REACH restrictions on microplastics and specific petrochemical feedstocks compel European suppliers to recertify abrasive compounds and synthetic wax carriers. California's Air Resources Board maintains the most stringent VOC thresholds in the United States, effectively setting the compliance ceiling for products distributed nationally. Stakeholders must monitor whether emerging state-level PFAS prohibitions extend into automotive surface treatments, as this would trigger another wave of raw material substitution and testing expenditure.
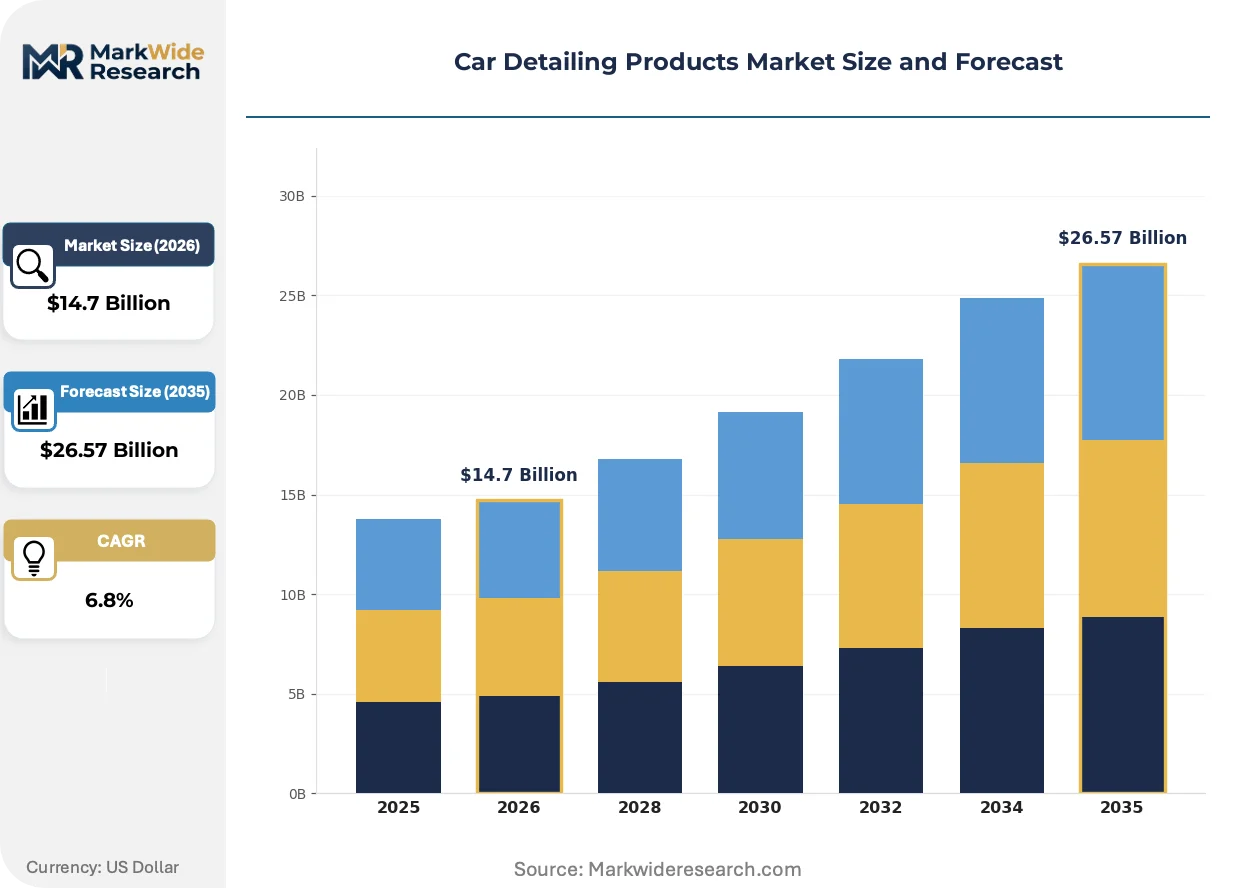
Market Dynamics
Professional detail shops now dominate procurement volumes, forcing suppliers to reformulate water-based chemistries that satisfy California Air Resources Board VOC ceilings while maintaining performance parity with solvent-heavy legacy compounds.
Growth Catalysts
- REACH-compliant chemistry mandates:European ECHA restrictions on petrochemical feedstocks accelerate supplier R&D investment in bio-based synthetic wax carriers and abrasive binders.
- Fleet cabin sanitization protocols:Commercial vehicle operators now specify interior application products alongside exterior maintenance, expanding addressable SKU counts per contract.
- Cross-linked polymer sealants:Molecular-level bonding technologies extend protection intervals from weeks to months, justifying premium pricing acceptance among high-volume detail operations.
Market Restraints
- Silicone resin cost volatility:Petrochemical feedstock fluctuations compress margins on sealant formulations where synthetic polymers constitute 40-60% of material cost.
- California ARB threshold stringency:The state's VOC limits function as de facto national compliance ceilings, forcing reformulation expenditure on products distributed beyond state borders.
- Waterborne performance gaps:Solvent substitution in heavy-duty degreasers yields reduced efficacy on baked-on contaminants, limiting complete category conversion.
Strategic Opportunities
- China's professional detail sector:Underpenetrated independent shop networks in tier-two cities present channel development potential for mid-premium formulation suppliers.
- PFAS prohibition anticipation:Emerging state-level fluorochemical bans in automotive surface treatments would create first-mover advantage for PFAS-free coating developers.
- Direct-to-consumer subscription models:Enthusiast-grade maintenance kits delivered on protection-interval schedules capture lifetime value from hobbyist segments bypassing retail markup.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silicone-polymer compatibility and abrasive particle dispersion commands premium compensation, constraining mid-tier supplier expansion.
- Multi-jurisdiction certification timelines:Parallel EPA 40 CFR Part 59, REACH, and GB standard testing extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Detailing Products Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax, Polish, Sealant, Shampoo Application: Exterior, Interior, Windows, Tires Distribution Channel: Online, Retail Stores, Distributors, Wholesale Customer Type: Individuals, Fleet Owners, Detail Shops, Car Washes |
| Companies Covered | Chemical Guys, Sonax, Meguiar's, Mothers, Autoglym, 3M, Armor All, Griot's Garage, Turtle Wax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Detailing Products Market Evolving Landscape
Ceramic coating chemistry, waterborne regulatory compliance, and professional-shop procurement consolidation are restructuring how surface protection compounds reach end-users.
Nano-ceramic silica formulations is fragmenting the traditional wax-sealant hierarchy by delivering hardness ratings exceeding 9H on the pencil scale. High-end detail studios in Germany and the United Arab Emirates now specify these coatings as standard for luxury vehicle clientele. The technology is fragmenting supplier R&D budgets away from incremental polymer improvements toward inorganic matrix development.
REACH microplastic restrictions compel European suppliers to recertify abrasive compounds and synthetic wax carriers ahead of 2027 enforcement deadlines. Abrasive manufacturers must reformulate cutting compounds with biodegradable alternatives or face market withdrawal across EU member states. German KBA vehicle inspection protocols now reference coating durability as a resale value factor, indirectly pressuring detailers toward compliant, longer-lasting protection systems.
Fleet procurement teams now negotiate consolidated supply agreements spanning exterior protection, interior sanitization, and windshield treatment under single-vendor contracts. Independent detail shops in the United States face margin compression as national fleet management companies centralize purchasing through approved supplier lists. This concentration is most visible in rental car fleet operations across Florida, Texas, and California, where standardized product specifications override local supplier relationships.
Car Detailing Products Market Segmentation
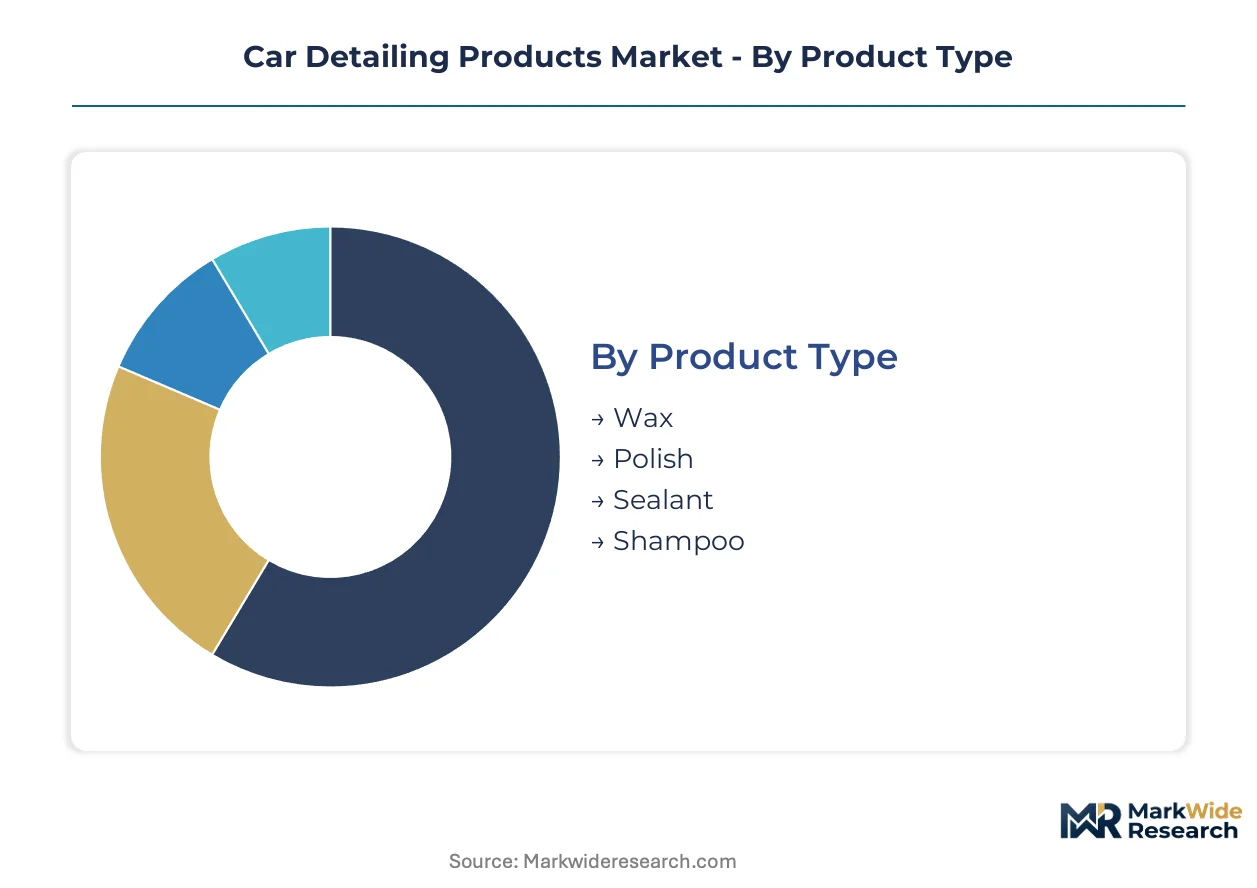
Product formulation chemistry and procurement channel economics create divergent margin profiles across car detailing segments. Professional detail shops now concentrate purchasing power in ways that reshape which formulations suppliers prioritize for development investment.
Product Type:
Wax faces the strongest substitution pressure as nano-ceramic silica coatings fragment traditional protection hierarchies with hardness ratings exceeding 9H on the pencil scale.
- Wax:Natural carnauba and synthetic polymer blends deliver familiar application characteristics and lower per-unit price points. Consumer familiarity sustains volume in retail channels across the United States and Germany, though professional shops increasingly specify longer-interval alternatives.
- Sealant:Synthetic cross-linked polymers bond at the molecular level to paint clear coats, delivering protection measured in months rather than weeks. Detail shops in California and the United Arab Emirates now specify these as standard for luxury vehicle clientele, justifying premium pricing through reduced reapplication frequency.
- Polish:Abrasive compounds formulated with diminishing abrasives restore optical clarity to oxidized paint surfaces.
- Shampoo:pH-neutral surfactant formulations remove contaminants without stripping existing protection layers.
Wax retains volume leadership; sealant holds the steepest expansion curve.
Application:
Cost tier stratification separates exterior protection commanded by fleet procurement teams from interior sanitization protocols now bundled under consolidated supply agreements.
- Exterior:Surface preparation, paint correction, and protective coating applications dominate material consumption volumes. German KBA vehicle inspection protocols now reference coating durability as a resale value factor, pressuring detailers toward longer-lasting protection systems.
- Interior:Cabin sanitization and surface conditioning products now outpace exterior growth in fleet channels as commercial operators prioritize hygiene protocols alongside aesthetic maintenance. Rental car operations across Florida, Texas, and California specify standardized interior treatment specifications.
- Windows:Hydrophobic coating and streak-free cleaning formulations address visibility and safety requirements.
- Tires:Dressing compounds restore sidewall appearance with solvent-based and waterborne formulation options.
Exterior commands the largest revenue base; interior applications gain share fastest in fleet procurement channels.
Distribution Channel:
Customer type concentration is shifting procurement patterns toward direct vendor relationships that bypass traditional retail markup structures.
- Online:Direct-to-consumer subscription models capture lifetime value from enthusiast segments through protection-interval delivery schedules. Griot's Garage maintains premium positioning through channel control that eliminates retail margin extraction.
- Retail Stores:Mass-market wax and shampoo SKUs sustain volume through consumer familiarity and impulse purchase accessibility.
- Distributors:Independent detail shops source professional-grade compounds through regional supply networks with technical support services.
- Wholesale:Fleet management companies and national car wash chains negotiate consolidated supply agreements spanning multiple product categories.
Online channels expand most quickly in enthusiast segments; wholesale concentrates volume in fleet and commercial accounts.
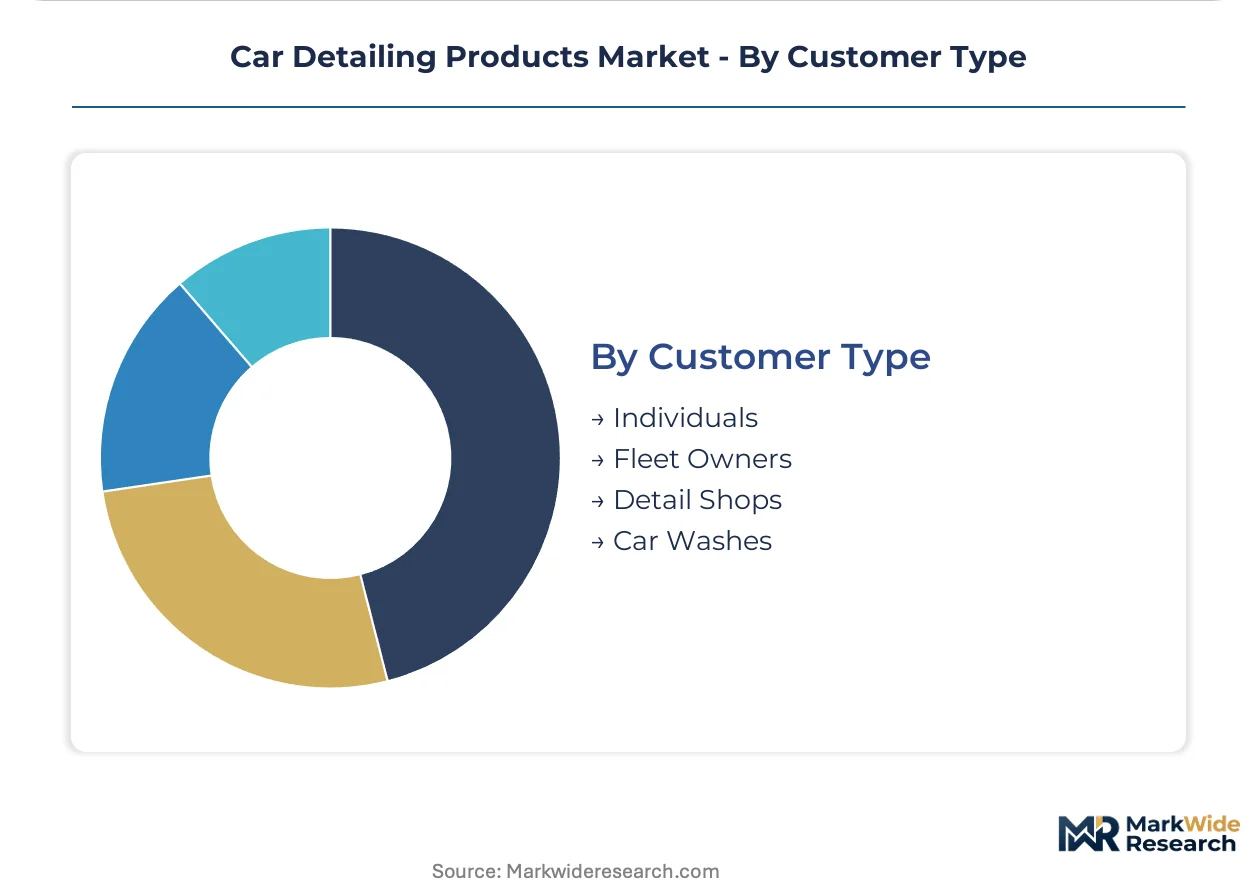
Customer Type:
Supply concentration among professional detail shops is redrawing competitive tiers and forcing formulation investments in water-based chemistries that satisfy California Air Resources Board VOC ceilings.
- Detail Shops:High-volume professional operations now dominate procurement volumes and drive supplier R&D priorities. These customers specify REACH-compliant chemistries and demand performance parity with solvent-heavy legacy compounds despite regulatory constraints.
- Fleet Owners:Rental car, commercial vehicle, and corporate fleet operators negotiate consolidated supply agreements spanning exterior protection, interior sanitization, and windshield treatment under single-vendor contracts.
- Individuals:Hobbyist enthusiasts sustain premium pricing acceptance through direct-to-consumer channels and subscription maintenance kits.
- Car Washes:Automated and tunnel wash operations consume bulk-formulated detergents and drying agents optimized for high-throughput equipment.
Detail shops anchor volume procurement; fleet owners drive the fastest contract value expansion through category consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional detail shops in Germany command 40-50% pricing premiums over comparable services in tier-two Chinese cities, reflecting divergent labor costs and regulatory compliance burdens that reshape supplier profit margins across geographies.
United States
California's Air Resources Board VOC thresholds function as de facto national compliance ceilings, forcing reformulation expenditure on products distributed beyond state borders. Fleet procurement teams in Florida, Texas, and California negotiate consolidated supply agreements spanning exterior protection, interior sanitization, and windshield treatment. Meguiar's leverages its vertically integrated California manufacturing campus to control raw material costs across wax and polish lines.
Germany
German KBA vehicle inspection protocols now reference coating durability as a resale value factor, indirectly pressuring detailers toward compliant, longer-lasting protection systems. REACH restrictions on microplastics and specific petrochemical feedstocks compel European suppliers to recertify abrasive compounds and synthetic wax carriers. High-end detail studios in Munich and Stuttgart specify nano-ceramic silica coatings as standard for luxury vehicle clientele.
China
Underpenetrated independent shop networks in tier-two cities present channel development potential for mid-premium formulation suppliers. GB standard testing extends product launch cycles by 18-24 months alongside parallel EPA and REACH certification timelines. The Yangtze River Delta and Pearl River Delta concentrate manufacturing capacity for water-based surfactant formulations serving domestic professional detail chains.
United Arab Emirates
Luxury vehicle density in Dubai and Abu Dhabi drives specification of molecular-level bonding sealants with hardness ratings exceeding 9H on the pencil scale. MOHAP registration requirements for automotive surface treatments add regulatory layering distinct from EU or US frameworks. High-end detail studios in Dubai now specify ceramic coatings as standard, fragmenting traditional wax-sealant hierarchies.
Japan
METI guidelines on chemical substance management influence supplier R&D priorities for bio-based synthetic wax carriers. JIS standards for automotive surface treatments create technical barriers for imported formulations lacking domestic certification. The Kanto region around Tokyo concentrates enthusiast-grade maintenance kit demand through direct-to-consumer subscription models.
Car Detailing Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the car detailing products market. Vertically integrated manufacturers with captive resin synthesis capabilities anchor premium-tier positioning, while regional compounders compete on formulation agility and channel responsiveness. Three strategic archetypes dominate: integrated chemical producers controlling upstream polymer supply, specialist formulators with direct-to-consumer channel control, and mass-market brands leveraging retail distribution scale. Competitive moves concentrate on regulatory pre-certification investments and professional-shop procurement consolidation through approved supplier lists.
Among North American specialists, Meguiar's and Griot's Garage occupy distinct positioning vectors—Meguiar's exemplifies vertical manufacturing integration with in-house California production, while Griot's Garage represents channel-controlled premium positioning through direct-to-consumer reach. 3M anchors the integrated chemical producer archetype through captive resin synthesis feeding sealant formulations. German formulator Sonax sits within the European regulatory compliance tier, reflecting REACH-mandated chemistry investments.
| Leading Market Players |
|---|
| Chemical Guys |
| Sonax |
| Meguiar's |
| Mothers |
| Autoglym |
| 3M |
| Armor All |
| Griot's Garage |
| Turtle Wax |
| Others |
Value Network & Pricing Analysis
Consolidated fleet supply agreements lock in multi-year supply access and price visibility for professional detail shops across California, Florida, and Texas, compressing margins for suppliers unable to match REACH-compliant chemistry investments or California ARB VOC thresholds. These contract structures concentrate procurement power among national fleet operators while fragmenting independent shop networks into price-takers without volume leverage.
Pricing Analysis
The customization-premium spread between configured-to-order ceramic coating systems and standard wax-sealant SKUs now exceeds three-to-one in professional channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with California ARB-compliant formulations commanding tier-one positioning. Price differentiation stems from silicone-polymer compatibility expertise and captive resin synthesis capabilities. Cost compression in mid-tier waterborne degreasers is intensifying because performance gaps against solvent-heavy alternatives limit complete category conversion. Fleet procurement teams exhibit lowest price sensitivity due to consolidated contract values, while independent detail shops face acute margin pressure from standardized product specifications.
Supply Chain Analysis
Inbound logistics costs through Los Angeles-Long Beach port congestion and trans-Pacific container availability constraints now constitute twelve to fifteen percent of landed formulation costs for European suppliers serving United States distribution. Raw material sourcing draws from Germany for specialty silicone resins, China for water-based surfactant precursors, and United Arab Emirates for nano-ceramic silica feedstocks. Petrochemical feedstock volatility constitutes the dominant supply chain risk, with synthetic polymer costs fluctuating forty to sixty percent of sealant formulation material expense. Distribution runs through approved supplier lists controlled by national fleet management companies, bypassing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
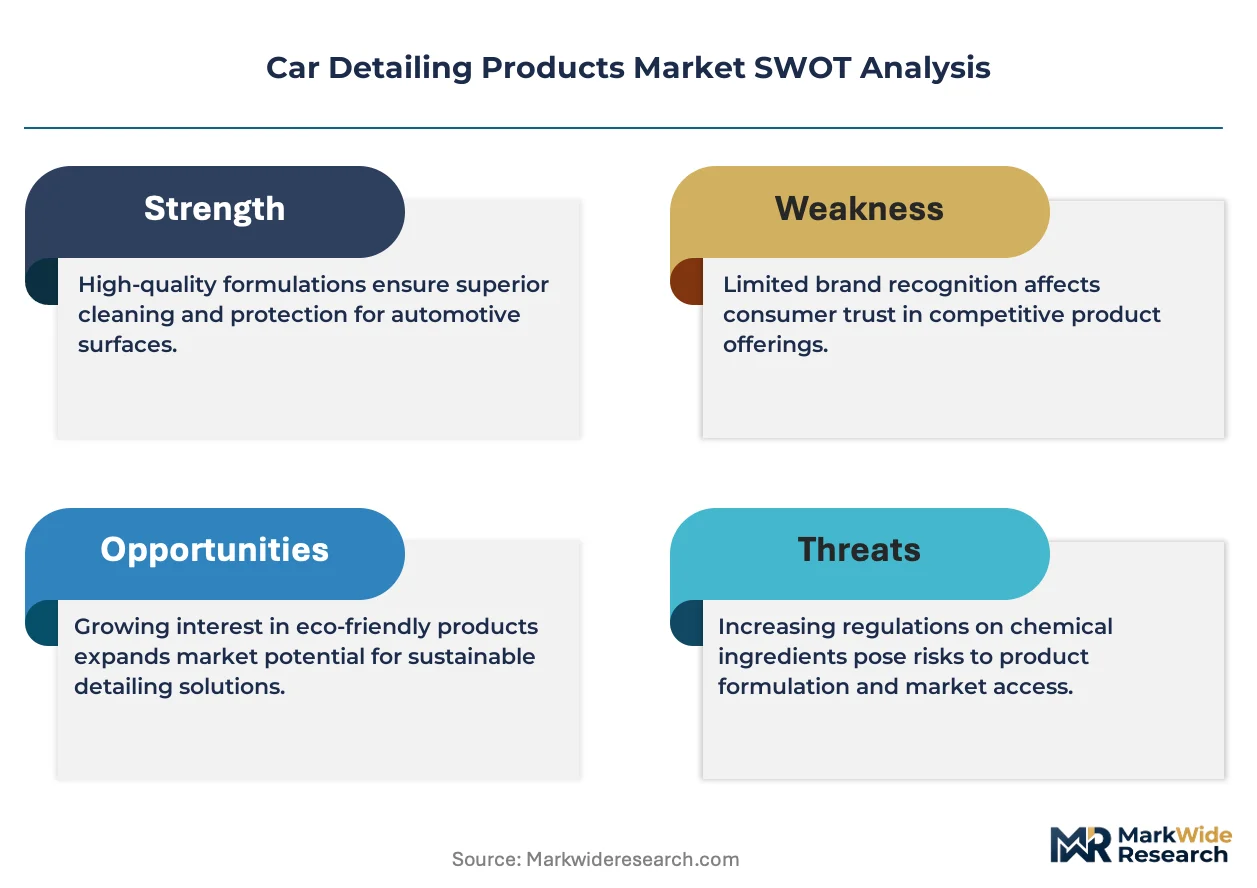
Fragmentation across professional detail shop tiers creates niche formation opportunities as fleet procurement consolidation and enthusiast direct-to-consumer channels diverge in specification requirements. The demand-side shift toward interior sanitization protocols alongside exterior protection bundles SKU counts per contract while opening formulation specialization gaps.
For Market Incumbents: Shield margin position through captive resin synthesis investments that lock in sealant formulation cost structures against silicone price volatility. Accelerate California ARB pre-certification for waterborne heavy-duty degreasers to capture fleet contract renewals before performance-gap limitations trigger supplier switching. Prioritize backward integration into abrasive compound manufacturing to offset REACH microplastic restriction compliance costs.
For New Entrants and Emerging Players: California ARB fast-track certification programs offer entry acceleration for PFAS-free coating developers anticipating state-level fluorochemical prohibitions. White-space concentration sits in tier-two Chinese city independent shop networks, where GB standard navigation capabilities separate viable entrants from specification-compliant suppliers. Direct-to-consumer subscription maintenance kits targeting Japanese enthusiast segments in the Kanto region bypass retail margin extraction entirely.
For Investors and Strategic Acquirers: The market sits at a regulatory-compliance phase that favors integrated chemical producers with captive polymer supply and multi-jurisdiction certification infrastructure. Long-term viability centers on five-to-ten year raw material substitution trajectories as bio-based synthetic wax carriers displace petrochemical feedstocks. Acquisition target archetypes include regional compounders with REACH-compliant chemistry portfolios and established professional shop relationships. The signal to watch is emerging state-level PFAS prohibition scope expansion into automotive surface treatments.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Investment | Bio-based synthetic wax carrier development secures EU market access ahead of 2027 microplastic enforcement deadlines. |
| California ARB Pre-Certification | Early VOC threshold compliance creates approved supplier list positioning for national fleet procurement consolidation. |
| Ceramic Coating Formulation Launch | Nano-ceramic silica systems with 9H+ hardness ratings fragment traditional wax-sealant hierarchies in German luxury studios. |
| Direct-to-Consumer Subscription Model | Protection-interval delivery schedules capture lifetime value from enthusiast segments bypassing retail markup structures. |
| Backward Integration into Resin Synthesis | Captive polymer supply anchors margin control against silicone feedstock volatility in sealant formulations. |
Research Methodology
The analysis maps wax-sealant-ceramic coating product tiers, interior-exterior application segments, and professional shop-fleet owner-individual customer channels, each validated through formulation chemists, fleet procurement directors, and independent detail shop operators. Primary interviews with plant managers at vertically integrated manufacturing campuses, distribution channel partners managing approved supplier lists, and technical R&D directors specializing in silicone-polymer compatibility combined with secondary validation from EPA 40 CFR Part 59 regulatory filings, ECHA REACH restriction updates, California ARB VOC threshold documentation, and customs trade data on silicone resin imports. Bottom-up SKU-level volume estimates and top-down market sizing triangulated through professional shop procurement concentration metrics.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation dimensions spanning formulation chemistry type, application surface, customer procurement scale, and regional regulatory cluster. CAGRs derived from professional shop volume growth trajectories, fleet contract value expansion rates, and ceramic coating adoption curves in German and United Arab Emirates luxury vehicle channels. Modeled inputs included silicone resin price indices, REACH compliance cost escalations, and California ARB threshold stringency projections.
Underlying assumptions cover sustained professional shop procurement consolidation, REACH microplastic restriction enforcement timelines, and California ARB threshold adoption as de facto national standards, with deviation risk concentrated in PFAS prohibition scope expansion and waterborne formulation performance gap closure rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market