
 Road Maintenance Service Market | 2026-2036
Road Maintenance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Road Maintenance Service Market Insights
The road maintenance service industry is pivoting on a widening split between data-driven predictive maintenance contracts and traditional reactive repair bidding. Vinci SA leverages its integrated concession-operate-maintain model to capture long-term revenue streams on European toll networks. Colas Group anchors its competitive position through specialized bitumen recycling technologies that reduce material costs on resurfacing programs. Downer Group dominates Australasian public infrastructure frameworks through embedded relationships with state road authorities.
Road maintenance service encompasses the systematic preservation, repair, and rehabilitation of paved and unpaved surfaces to sustain design load capacity, ride quality, and safety performance, typically involving asphalt overlays between 25-50mm thickness, crack infiltration sealing, and subgrade drainage restoration. Its primary purpose extends pavement service life while minimizing whole-life costs for public asset owners. Pothole repair and asphalt resurfacing command the largest share of contracted spend due to high frequency and visible public accountability, while bridge repair captures disproportionate margin pools given structural engineering complexity and regulatory inspection mandates. Municipal authorities represent the most fragmented yet volume-heavy client channel, whereas toll operators concentrate maintenance procurement among fewer integrated service providers.
The Federal Highway Administration shapes US demand through National Highway System condition standards and MAP-21 performance management requirements, while the EU Green Deal's sustainable mobility frameworks push member states toward lower-carbon resurfacing binders and recycled content thresholds. India's Ministry of Road Transport and Highways enforces IRC pavement condition indexing that dictates maintenance prioritization across national highway corridors. Stakeholders must monitor how climate resilience mandates are rewriting material specifications and contract tenors for surface infrastructure assets.
Market Dynamics
The Infrastructure Investment and Jobs Act is funneling unprecedented capital toward preventive maintenance frameworks, forcing asset owners to abandon reactive repair cycles in favor of lifecycle contracting models that lock in decade-long service provider relationships.
Growth Catalysts
- Performance-based contracting:State transportation departments are rewriting procurement rules to reward pavement condition outcomes rather than activity volumes, aligning contractor incentives with long-term asset health.
- India:The National Highways Authority is accelerating asset management outsourcing to private operators, creating dedicated maintenance corridors on national highway networks.
- Warm-mix asphalt technologies:Lower-temperature paving processes are reducing energy consumption and extending construction seasons in temperate climates.
Market Restraints
- Bitumen price volatility:Crude oil derivatives expose resurfacing program budgets to commodity swings that compress contractor margins on fixed-price contracts.
- Skilled operator shortages:Specialized pavement condition assessment technicians remain concentrated in legacy infrastructure markets, constraining expansion into emerging economies.
- EU Green Deal recycled content mandates:Binding thresholds for reclaimed asphalt pavement create technical compliance costs that smaller regional contractors struggle to absorb.
Strategic Opportunities
- Drone-based condition monitoring:Automated crack detection and rutting measurement systems are opening predictive maintenance contracts previously reserved for manual inspection regimes.
- Bridge rehabilitation specialization:Structural engineering complexity and mandatory inspection cycles create premium service niches with higher barriers to entry than surface maintenance.
- Carbon credit monetization:Lower-emission resurfacing binders qualify for EU emissions trading scheme offsets, creating ancillary revenue streams for early technology adopters.
Industry Challenges
- Legacy equipment integration:Automated paving control systems must interface with decades-old fleet assets, creating interoperability failures that delay smart machinery deployment.
- Certification timeline compression:IRC pavement condition indexing requirements in India demand rapid assessor qualification that outpaces available training infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Maintenance Service Market |
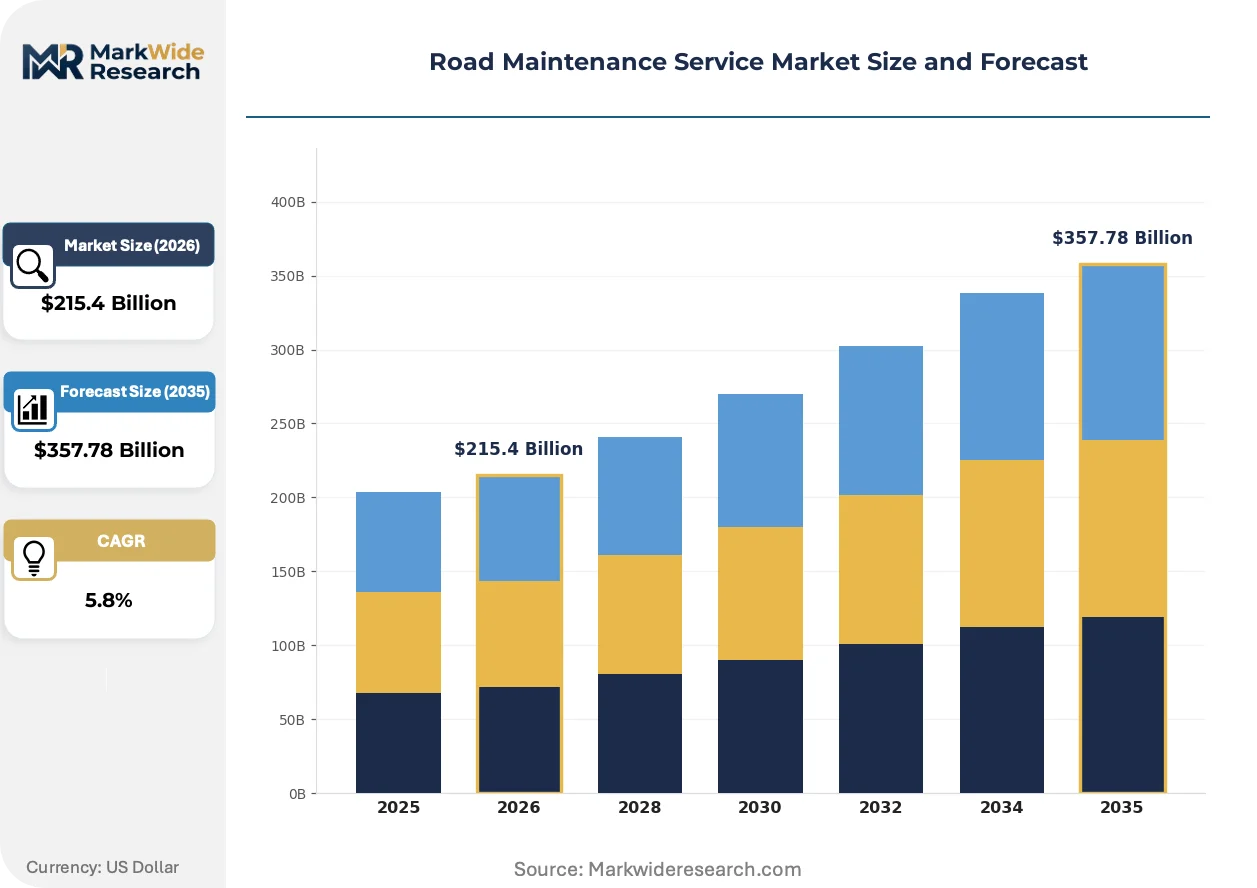
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $357.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pothole Repair, Asphalt Resurfacing, Road Marking, Crack Sealing, Drainage Maintenance, Bridge Repair Equipment Used: Asphalt Pavers, Road Rollers, Graders, Milling Machines, Crack Sealers, Concrete Mixers Client Type: Municipal Authorities, Highway Contractors, Toll Operators, Roadway Agencies, Private Developers, Construction Firms Application: Urban Roads, Rural Highways, Industrial Roads, Airport Runways, Port Access Roads, Event Venues |
| Companies Covered | Vinci SA, Balfour Beatty, ACS Group, Bechtel Corporation, Colas Group, Downer Group, Hochtief, Kiewit Corporation, AECOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Maintenance Service Market Trends and Innovations
Digital condition assessment tools and lower-carbon material specifications are compressing traditional maintenance planning horizons while elevating technical performance requirements for service providers.
Geospatial pavement management systems are consolidating fragmented asset data into unified platforms that integrate traffic load modeling, climate exposure mapping, and deterioration forecasting. State road authorities in the United States are adopting these systems fastest, driven by MAP-21 performance reporting mandates. The technology is consolidating previously siloed engineering, finance, and operations functions into single-source decision frameworks that reduce procurement cycle times.
The EU Green Deal's sustainable mobility frameworks are mandating lower-carbon resurfacing binders and recycled content thresholds that reshape material supply chains. Member states must demonstrate compliance through certified life-cycle assessment documentation. Road maintenance contracts in Germany, France, and the Netherlands now embed carbon intensity scoring that determines bidder qualification.
Toll operators are consolidating maintenance procurement among integrated concession holders, displacing fragmented spot-contracting for discrete repair activities. This bundling compresses vendor rosters and extends contract tenors from annual renewals toward 15-20 year concession terms. The shift is most visible on European toll networks where Vinci SA and similar operators control both revenue collection and preservation obligations.
Road Maintenance Service Market Segmentation
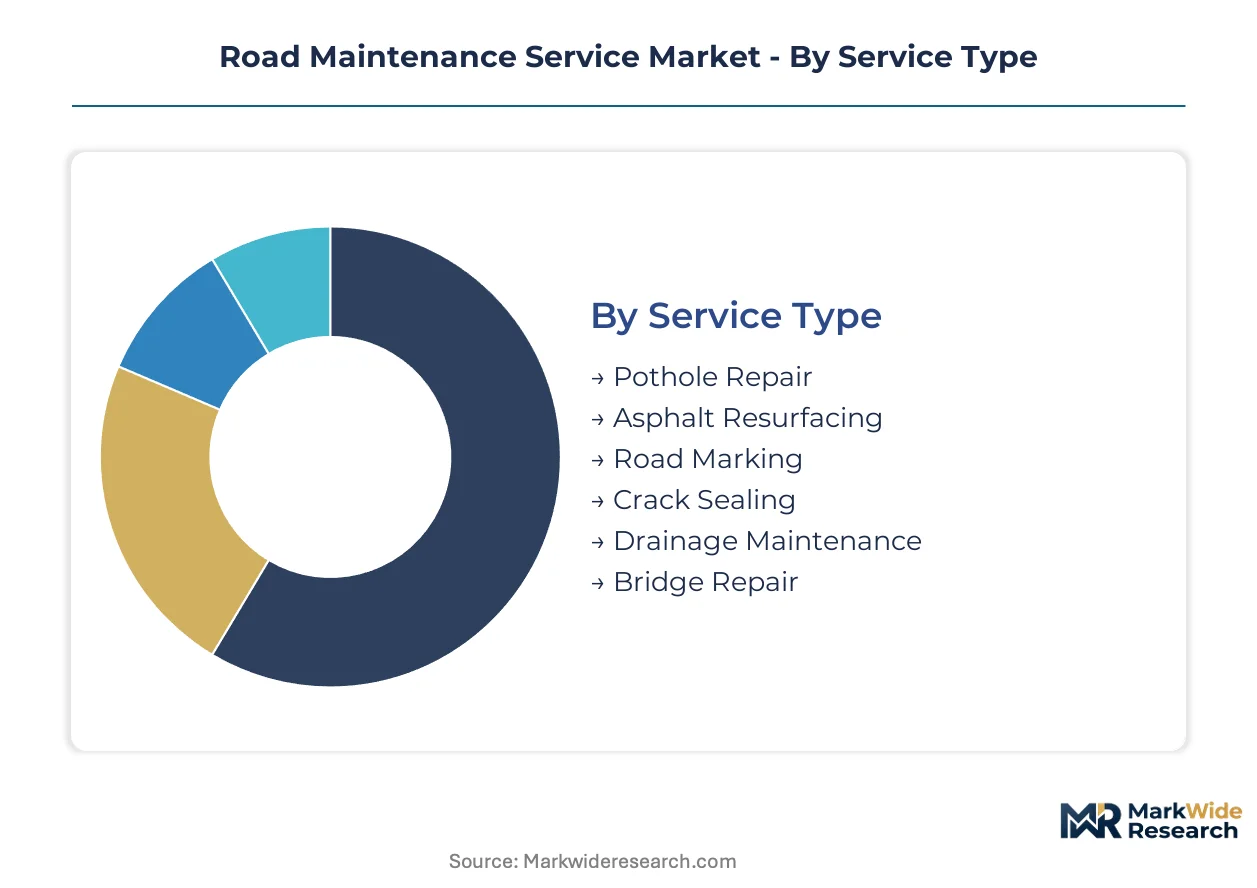
Service differentiation in road maintenance creates distinct margin profiles and contract tenures across technical specializations. Equipment intensity and client procurement sophistication further stratify competitive positioning within each segment category.
Service Type:
Asphalt resurfacing commands the heaviest contract volumes while bridge repair extracts premium pricing through engineering complexity.
- Pothole Repair:Reactive patching of localized pavement failures using hot-mix or cold-patch asphalt compounds. Municipal authorities in India concentrate demand here, driven by IRC pavement condition indexing mandates that penalize visible surface defects.
- Asphalt Resurfacing:Mill-and-overlay operations applying 25-50mm asphalt lifts to restore ride quality and structural capacity. State transportation departments across the United States are expanding preventive maintenance contracts for this service, locking in decade-long contractor relationships through lifecycle performance frameworks.
- Road Marking:Thermoplastic and water-based paint applications for lane delineation and safety signage.
- Crack Sealing:Polymer-modified sealant injection to prevent water infiltration and subgrade deterioration.
- Drainage Maintenance:Culvert clearing, ditch grading, and stormwater system rehabilitation to preserve pavement structural support.
- Bridge Repair:Structural concrete rehabilitation, joint replacement, and load-bearing element restoration subject to mandatory inspection cycles.
Today's leader: Asphalt Resurfacing. Tomorrow's challenger: Bridge Repair.
Equipment Used:
Mechanization intensity separates high-volume surface treatment providers from specialized structural contractors.
- Asphalt Pavers:Tracked and wheeled machines distributing hot-mix asphalt at specified depths and compaction rates. Highway contractors in Germany and France are prioritizing warm-mix compatible pavers to meet EU Green Deal carbon intensity scoring requirements.
- Road Rollers:Steel drum and pneumatic-tired compactors achieving specified density targets through intelligent compaction systems. The technology is expanding most quickly in the United States where MAP-21 performance reporting demands precise quality documentation.
- Graders:Motorized blades for subgrade preparation and surface finishing on unpaved or reclaimed sections.
- Milling Machines:Cold planers removing deteriorated asphalt layers for recycling and overlay preparation.
- Crack Sealers:Specialized applicators delivering heated sealant under pressure into pavement fractures.
- Concrete Mixers:Mobile batching and transit equipment for bridge deck and structural repairs.
The installed base concentrates among asphalt pavers and road rollers; milling machines are gaining share fastest as recycling mandates intensify.
Client Type:
Procurement sophistication ranges from fragmented municipal spot-contracting to integrated concession frameworks.
- Municipal Authorities:City and county governments issuing annual or multi-year maintenance contracts through competitive bidding. These clients represent the most fragmented yet volume-heavy channel across the United States, driven by visible public accountability for road surface conditions.
- Highway Contractors:Prime construction firms subcontracting specialized preservation work or self-performing maintenance under design-build agreements.
- Toll Operators:Concession holders bundling maintenance with revenue collection obligations. European networks are concentrating procurement among integrated service providers, displacing fragmented spot-contracting for discrete repair activities.
- Roadway Agencies:State and national highway authorities with centralized asset management frameworks.
- Private Developers:Industrial park and residential community owners maintaining internal road networks.
- Construction Firms:General contractors seeking maintenance capabilities to extend project revenue streams.
Municipal authorities dominate current volumes; toll operators are restructuring procurement fastest toward long-term concession partnerships.
Application:
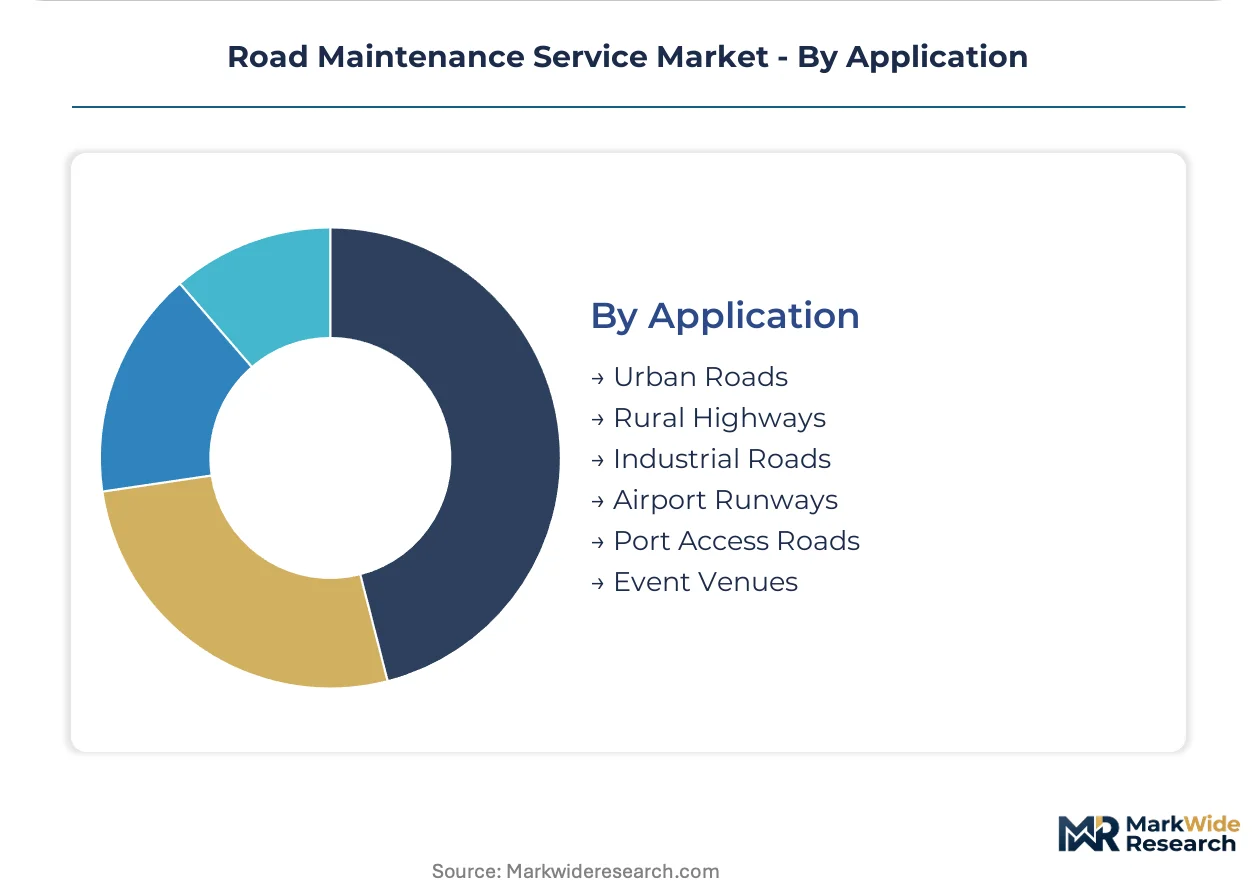
Traffic loading severity and climate exposure create divergent technical specifications across surface types.
- Urban Roads:High-density networks subject to frequent utility cuts, stormwater infiltration, and heavy commercial vehicle channelization. India's National Highways Authority is accelerating asset management outsourcing for these corridors, creating dedicated maintenance concessions on national highway networks passing through metropolitan areas.
- Rural Highways:Lower-traffic arterials with extended freeze-thaw cycles and limited alternative routing options.
- Industrial Roads:Heavy-haul surfaces serving mining, logistics, and manufacturing facilities with extreme axle loading.
- Airport Runways:Precision-grade pavements requiring friction restoration and foreign object damage prevention.
- Port Access Roads:Container terminal connectors with concentrated heavy truck traffic and salt exposure.
- Event Venues:Temporary or seasonal surfaces for racing circuits, exhibition grounds, and recreational facilities.
Urban roads absorb the largest maintenance budgets; industrial roads are climbing the fastest as freight volumes concentrate on dedicated heavy-haul corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled pavement engineering talent concentrates in Germany, the United States, and India, anchoring regional competitive advantages in automated surfacing technologies and lifecycle asset management frameworks.
United States
State transportation departments dominate procurement volumes through Infrastructure Investment and Jobs Act funding mechanisms. The Federal Highway Administration enforces MAP-21 performance management requirements that mandate condition-based maintenance prioritization. Texas and California anchor the heaviest contract concentrations, where preventive resurfacing programs are displacing reactive repair cycles.
Germany
Warm-mix asphalt adoption accelerates fastest among European highway authorities seeking construction season extension. The EU Green Deal mandates recycled content thresholds and carbon intensity scoring that reshape material specifications. Bavaria and North Rhine-Westphalia concentrate specialized milling machine fleets serving cross-border corridor maintenance.
India
The National Highways Authority accelerates asset management outsourcing to private operators across metropolitan corridor networks. IRC pavement condition indexing mandates dictate maintenance prioritization and penalize visible surface defects. Maharashtra and Gujarat host the densest concentrations of dedicated maintenance concessions on national highway routes.
Australia
State road authorities embed long-term service providers through framework agreements spanning decade-long tenors. State-level procurement rules emphasize pavement condition outcomes over activity volumes. New South Wales and Victoria dominate contract volumes through embedded relationships with integrated infrastructure operators.
France
Toll operators consolidate maintenance procurement among integrated concession holders controlling both revenue collection and preservation obligations. EU Green Deal sustainable mobility frameworks enforce lower-carbon resurfacing binder requirements. The Paris-Saclay corridor and Lyon-Grenoble axis concentrate automated paving control system deployments.
Road Maintenance Service Market Competitive Landscape
Capital-heavy integrated concession holders compete with asset-light specialized maintenance contractors for differentiated contract tenors and margin profiles. The vendor base stratifies across three tiers: global infrastructure conglomerates with concession-operate-maintain capabilities, regional surfacing specialists with recycling technology advantages, and municipal-scale reactive repair operators. Two dominant competitive moves reshape positioning: long-term concession bundling that compresses vendor rosters, and technology licensing partnerships that accelerate smart machinery deployment without full capital commitment.
Within the integrated concession tier, Vinci SA exemplifies the bundled revenue-collection-and-preservation model dominating European toll networks. Colas Group and Downer Group occupy positions as regional specialists with embedded relationships in France and Australasia respectively. These three anchors represent divergent strategic postures: transnational concession control, material recycling specialization, and public framework embeddedness.
| Leading Market Players |
|---|
| Vinci SA |
| Balfour Beatty |
| ACS Group |
| Bechtel Corporation |
| Colas Group |
| Downer Group |
| Hochtief |
| Kiewit Corporation |
| AECOM |
| Others |
Pricing and Supply Chain Analysis
Bitumen futures pricing on the Singapore Exchange cascades through road maintenance supply chains into three distinct contractor tiers: integrated concession holders absorbing commodity swings through long-term offtake agreements, regional resurfacing specialists exposed to spot-market volatility, and municipal repair operators bidding fixed-price pothole contracts with minimal margin buffers.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the road maintenance sector. Integrated concession contracts spanning 15-20 years command premium rates by packaging revenue collection with preservation obligations, while spot-contracted reactive repairs compete on thin margins in fragmented municipal bidding. Price differentiation hinges on warm-mix asphalt certification status and recycled content compliance thresholds under EU Green Deal frameworks. Cost compression in standard resurfacing tiers intensifies as state transportation departments consolidate vendor rosters through performance-based procurement. Municipal authorities exhibit the highest price sensitivity, whereas toll operators prioritize lifecycle cost outcomes over unit-rate competitiveness.
Supply Chain Analysis
Reclaimed asphalt pavement flows reverse through collection networks into hot-mix plant feedstocks, creating circular material loops that reshape traditional virgin-bitumen dependencies. Primary supply concentration rests in Germany, the United States, and India, where specialized milling machine fleets and warm-mix production capacity cluster near metropolitan highway corridors. Critical inputs include crude oil-derived bitumen, polymer-modified binders, and geosynthetic reinforcement fabrics. Single-source vulnerability in specialized paver control systems imported from German manufacturers exposes contractors to equipment delivery delays. Distribution runs through state road authority framework agreements and toll operator concession partnerships rather than spot-market procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Road maintenance service margins are expanding through carbon credit monetization on lower-emission resurfacing programs, where early warm-mix technology adopters capture ancillary revenue streams unavailable to conventional operators.
For Market Incumbents: Anticipate procurement consolidation by embedding drone-based condition monitoring capabilities before mandatory adoption deadlines compress competitive differentiation windows. Deepen backward integration into bitumen recycling infrastructure to offset commodity price volatility on fixed-price state contracts. Prioritize IRC assessor certification investments in India ahead of training infrastructure bottlenecks that will constrain qualified technician supply.
For New Entrants and Emerging Players: Digital procurement platforms for municipal spot-contracting offer the lowest barrier-to-entry channel for building operational track records without concession-scale capital commitments. Target bridge rehabilitation specialization where mandatory inspection cycles and structural engineering complexity sustain premium pricing power against commoditized surface maintenance. Pursue technology licensing partnerships with established paver manufacturers to deploy automated compaction controls without full fleet ownership burdens.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing embedded state road authority relationships and proven recycling technology portfolios that qualify for EU emissions trading scheme offsets. Long-term viability favors asset-light service providers capable of pivoting between public framework agreements and private concession opportunities as procurement models evolve. Monitor IRC pavement condition indexing enforcement intensity across Indian national highway corridors as an inflection signal for outsourced maintenance corridor expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Transition | Aligns contractor incentives with MAP-21 outcome requirements across US state transportation departments. |
| Warm-Mix Asphalt Capacity Buildout | Positions operators for EU Green Deal carbon intensity scoring mandates in Germany and France. |
| Drone-Based Condition Monitoring Deployment | Opens predictive maintenance contracts previously reserved for manual IRC inspection regimes in India. |
| Bridge Rehabilitation Specialization | Captures premium margins through structural engineering complexity and mandatory inspection cycles. |
| Reclaimed Asphalt Pavement Integration | Reduces material cost exposure while meeting EU recycled content thresholds for contract qualification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with state transportation department procurement officers, toll operator asset managers, pavement engineering consultants, and hot-mix asphalt plant operators with secondary validation against FHWA funding disbursement records, EU Green Deal implementation guidance, NHAI concession award documentation, and SEC filings from listed infrastructure conglomerates. Bottom-up project pipeline enumeration and top-down macroeconomic factor weighting were triangulated to anchor volume estimates.
Historical reference periods spanning pre-pandemic baseline, stimulus-injection peak, and normalized procurement recovery established the forecast anchoring framework across the projection horizon. Segmentation dimensions modeled include service type specialization, equipment mechanization intensity, client procurement sophistication tier, and regional regulatory cluster. CAGRs were derived from weighted scenario analysis incorporating Infrastructure Investment and Jobs Act funding trajectory assumptions and IRC outsourcing acceleration patterns.
The model assumes a particular technology adoption path; alternative pathways for warm-mix asphalt and drone-based condition assessment would alter the outlook through accelerated or delayed procurement rule revisions. Forecasts reflect assumptions regarding sustained federal funding authorization continuity and skilled technician training pipeline expansion. Practitioners should monitor bitumen price volatility spikes and EU carbon credit market liquidity for early signals of margin compression or expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market