
 Heavy-Duty Automotive Aftermarket Market | 2026-2036
Heavy-Duty Automotive Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Automotive Aftermarket Market Intelligence
Aftermarket service revenue is reconfiguring margin pools away from simple part replacement toward integrated maintenance programs. Bosch leverages its diagnostic technology leadership to capture recurring fleet service contracts. Michelin sustains premium positioning in tire lifecycle management through retreading networks and predictive wear analytics. Continental AG competes on sensor-integrated brake and suspension systems that tie hardware sales to software-enabled monitoring.
The heavy-duty automotive aftermarket encompasses the post-sale ecosystem of parts, services, and systems sustaining commercial vehicles above Class 6 gross vehicle weight ratings, typically operating at 26,000 pounds or higher with diesel or alternative-fuel powertrains. Brake friction materials must withstand thermal loads exceeding 300°C during repeated downhill braking cycles, while exhaust aftertreatment assemblies integrate diesel particulate filters and selective catalytic reduction modules to meet emissions thresholds. Fleet operators now represent the dominant demand channel as centralized procurement shifts volume toward contracted service networks and away from fragmented retail purchasing. Repair and replacement services command the largest value share within service type segmentation, though maintenance subscriptions are gaining traction as telematics enable condition-based scheduling.
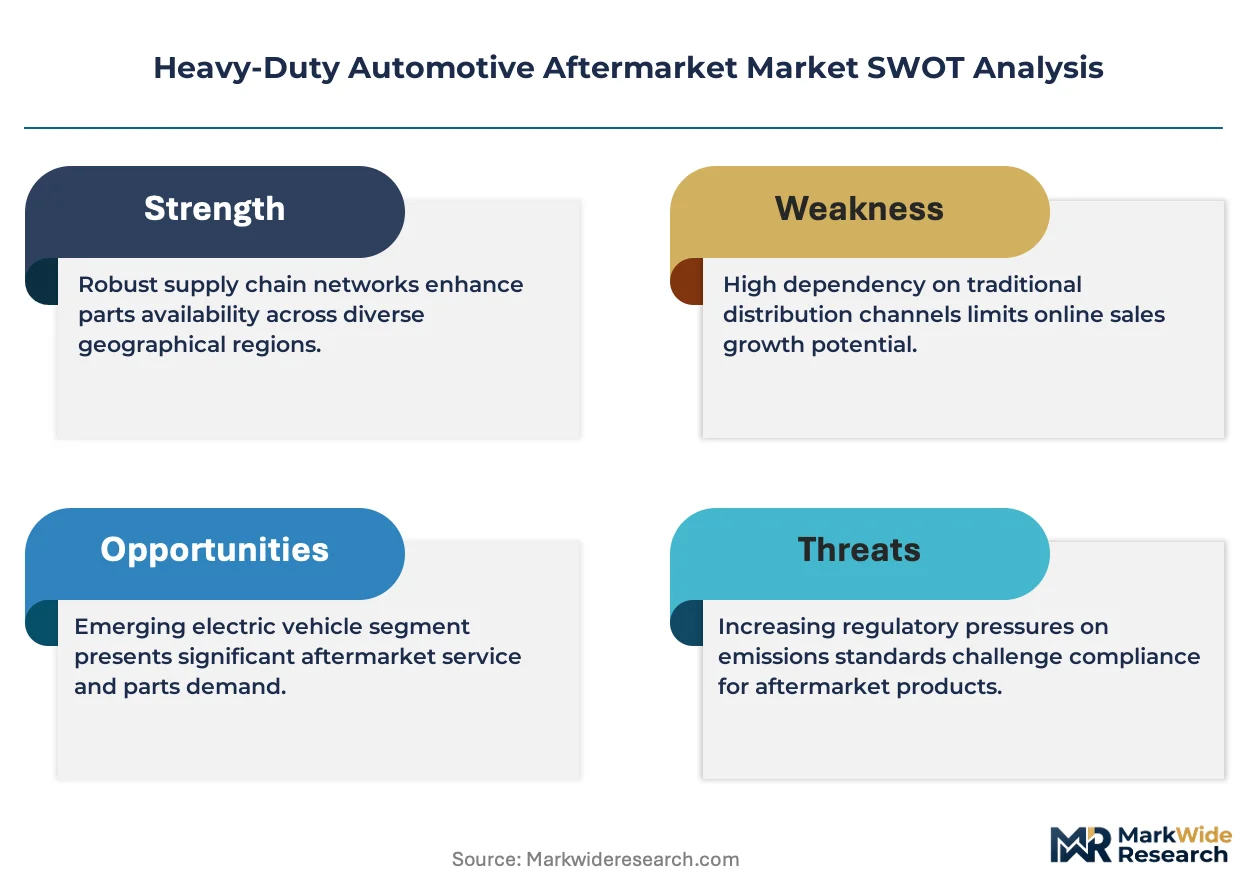
The EPA enforces greenhouse gas Phase 2 standards that mandate component durability and emissions performance verification, while NHTSA governs brake system safety through FMVSS 121 stopping distance requirements. These frameworks elevate compliance costs for non-certified suppliers and redirect fleet procurement toward documented OEM-equivalent parts. Stakeholders must monitor how CARB's Advanced Clean Trucks rule spreads to additional states and whether emerging predictive maintenance platforms reshape distributor economics by disintermediating traditional parts stocking.
Market Dynamics
Fleet telematics platforms are compressing traditional maintenance intervals by enabling condition-based service scheduling, redirecting parts demand from reactive failure replacement toward predictive component swaps before breakdown occurs.
Growth Catalysts
- EPA Phase 2 greenhouse gas standards:Durability mandates for exhaust aftertreatment assemblies accelerate replacement cycles for diesel particulate filters and selective catalytic reduction modules in heavy-duty applications.
- E-commerce logistics expansion:Parcel delivery fleets operating Class 7-8 vehicles sustain elevated brake friction and tire consumption through high-stop urban routing patterns.
- Remanufactured powertrain components:Circular economy incentives and core return programs reduce total cost of ownership for independent repair shops serving owner-operator segments.
Market Restraints
- Raw material volatility in rare earth elements:Neodymium and cerium price swings destabilize pricing for catalytic converter substrates and magnetic sensor assemblies.
- Consolidated OEM parts distribution:Authorized dealer networks in the United States and Germany control access to proprietary diagnostic protocols, limiting independent service provider competitiveness.
- Technical skills deficit in aftertreatment servicing:Specialized training requirements for SCR and DPF troubleshooting constrain workforce scalability across rural service territories.
Strategic Opportunities
- CARB Advanced Clean Trucks rule adoption:California's zero-emission vehicle mandates for Class 4-8 trucks create replacement demand for electric powertrain cooling systems and battery thermal management components.
- Blockchain-enabled parts provenance tracking:Immutable certification records for remanufactured components address fleet procurement concerns about counterfeit brake friction and steering gear.
- Telematics-integrated inventory positioning:Real-time vehicle health data streams enable distributor pre-positioning of high-failure components at regional hubs before diagnostic alerts trigger.
Industry Challenges
- Cross-platform diagnostic compatibility:Proprietary telematics protocols from individual OEMs fragment fleet management system integration, forcing multi-brand operators to maintain redundant service equipment.
- Technician certification timelines:EPA 609 refrigerant handling and NHTSA brake inspector qualifications create onboarding bottlenecks for service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Automotive Aftermarket Market |
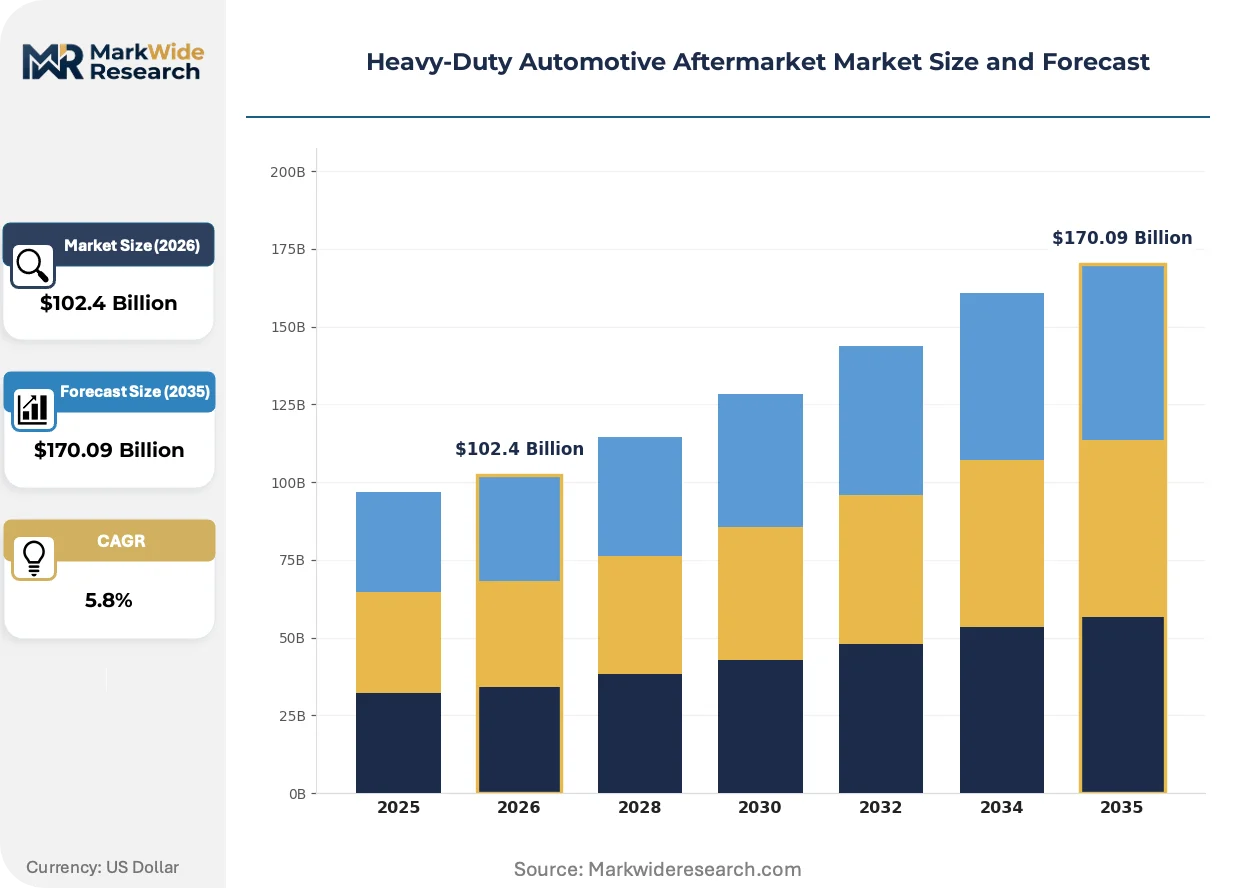
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $170.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brakes, Suspension, Exhaust, Filters End User: Fleet Operators, Repair Shops, Retail Consumers, Distributors Service Type: Repair, Replacement, Maintenance, Customization Distribution Channel: Online Sales, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Denso Corporation, Michelin, 3M Company, Dorman Products, Goodyear, Bosch, Bridgestone, Detroit Diesel Corporation, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Automotive Aftermarket Market Strategic Shifts & Innovations
Digital thread technologies are dissolving boundaries between component manufacturing, distribution, and service execution, compressing information latency across the aftermarket value chain from months to hours.
Sensor-embedded brake friction materials are collapsing the distinction between hardware sales and continuous monitoring services. Fleets operating mountain corridor routes in Colorado and Utah deploy these systems to track thermal degradation during descent cycles. Real-time wear telemetry is collapsing traditional scheduled replacement intervals into dynamic, load-adjusted service events.
EPA enforcement of tamper-proof emissions software is tightening compliance verification for aftermarket engine control module recalibrations. Independent tuners face expanded documentation requirements demonstrating equivalent greenhouse gas performance to certified configurations. Heavy-duty vocational segments in Texas and Pennsylvania are responding by migrating toward EPA-verified remanufacturing programs with embedded compliance tracking.
Centralized fleet procurement desks are consolidating vendor relationships around integrated maintenance contracts that bundle parts, labor, and uptime guarantees. Traditional jobber distributors serving independent garages in the Midwest are losing volume to manufacturer-direct service agreements. This concentration is most visible among national less-than-truckload carriers operating standardized tractor specifications across terminal networks.
Heavy-Duty Automotive Aftermarket Market Segmentation
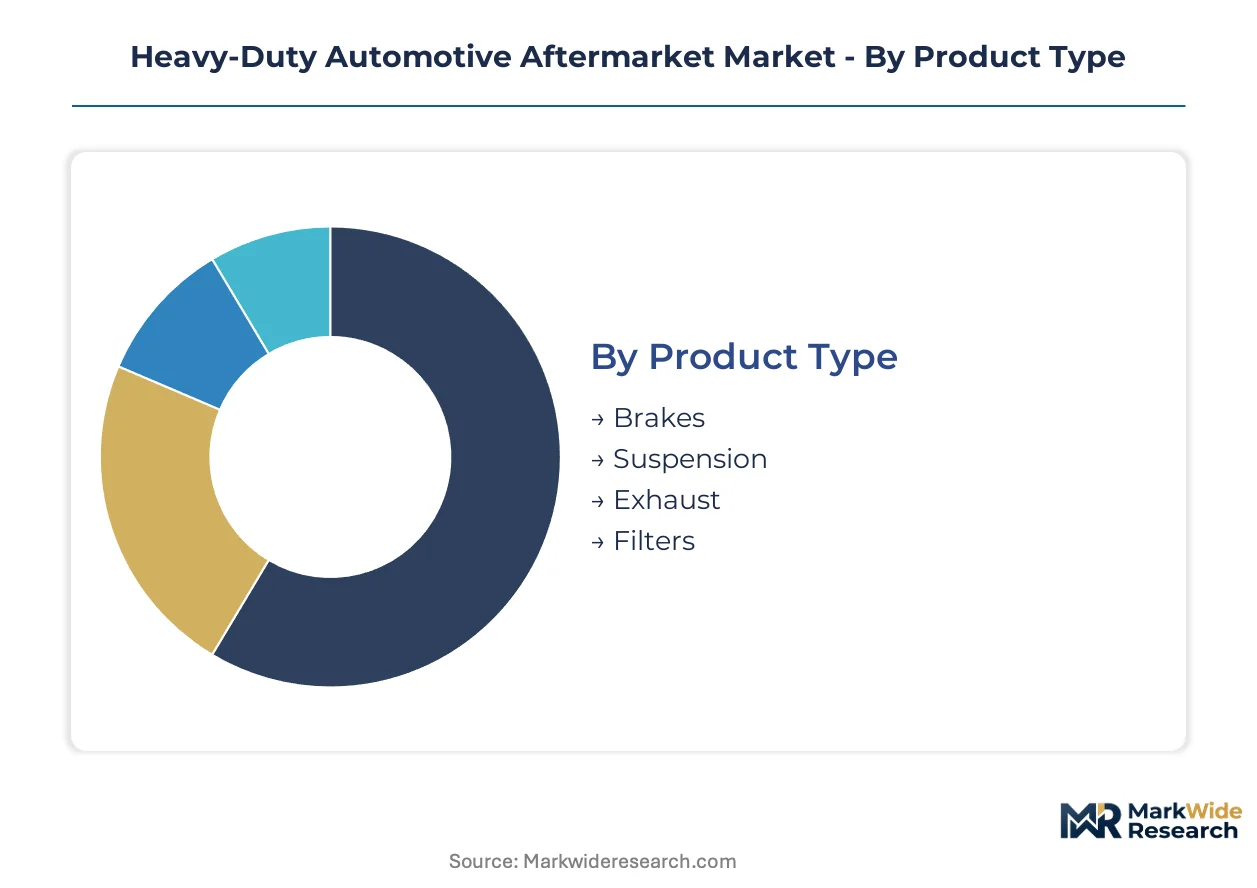
Segmentation in heavy-duty aftermarket parts reveals how service intensity varies dramatically across component lifecycles and customer procurement patterns. Fleet operators demand integrated maintenance programs while independent repair shops prioritize part availability and technical support. Understanding these divergent requirements shapes distributor inventory strategies and manufacturer channel investments.
Product Type:
After-sales service intensity correlates directly with component thermal stress and regulatory compliance burden, creating divergent margin profiles across hardware categories.
- Brakes:Friction materials engineered for thermal loads exceeding 300°C during mountain corridor descents require frequent inspection intervals. Demand concentrates among parcel delivery fleets operating high-stop urban routes in Colorado and Pennsylvania, where brake wear telemetry now enables condition-based replacement scheduling rather than fixed intervals.
- Exhaust:Aftertreatment assemblies integrating diesel particulate filters and selective catalytic reduction modules carry EPA Phase 2 durability mandates that accelerate replacement cycles. Fleet procurement in California and Texas prioritizes documented OEM-equivalent certification to satisfy CARB compliance verification and avoid enforcement penalties.
- Suspension:Air spring and shock absorber replacement tracks closely with axle load profiles and road quality degradation.
- Filters:Engine air and fuel filtration maintenance intervals compress under severe-duty operating conditions in construction and mining applications.
Brakes hold the largest share; momentum sits with exhaust as emissions enforcement tightens replacement velocity.
End User:
Cost tier differentiation separates centralized procurement desks from fragmented retail purchasing, reshaping how parts flow through distribution networks.
- Fleet Operators:National less-than-truckload carriers and dedicated contract fleets operate centralized procurement functions that bundle parts, labor, and uptime guarantees into integrated maintenance contracts. These operators in Illinois and Ohio are migrating manufacturer-direct, bypassing traditional jobber distributors to secure volume pricing and embedded telematics support.
- Repair Shops:Independent service providers serving owner-operators depend on same-day parts availability and technical hotline access. Shops across rural Michigan and Wisconsin face constrained competitiveness as OEM diagnostic protocol restrictions limit their ability to service multi-brand vehicle populations.
- Retail Consumers:Owner-operators purchasing through counter sales prioritize price transparency and core return program simplicity.
- Distributors:Regional warehousing operations balance inventory carrying costs against fill-rate commitments to contracted service networks.
Fleet operators hold the largest share; independent repair shops are gaining share fastest as vocational segment fragmentation sustains decentralized service demand.
Service Type:
Application urgency determines pricing power, with reactive failure events commanding premium labor rates compared to scheduled maintenance windows.
- Repair:Unscheduled failure events in brake and suspension systems generate immediate demand for expedited parts delivery and mobile service deployment. Fleets operating temperature-controlled trailers across Arizona and New Mexico route corridors cannot tolerate refrigeration unit downtime, compressing procurement timelines and elevating willingness to pay for rapid response.
- Replacement:Predictive component swaps triggered by telematics alerts are displacing traditional scheduled intervals. Class 8 tractor fleets in Indiana and Kentucky now pre-position high-failure items at regional terminals before diagnostic codes trigger, reducing roadside breakdown frequency.
- Maintenance:Oil change and inspection services anchor recurring revenue relationships with fleet procurement desks.
- Customization:Upfit modifications for specialized vocational applications command project-based pricing and extended engineering support.
Repair holds the largest share; replacement is expanding most quickly as predictive maintenance platforms compress traditional service intervals.
Distribution Channel:
Volume concentration among national accounts is forcing channel restructuring, with direct manufacturer relationships displacing traditional wholesale intermediaries.
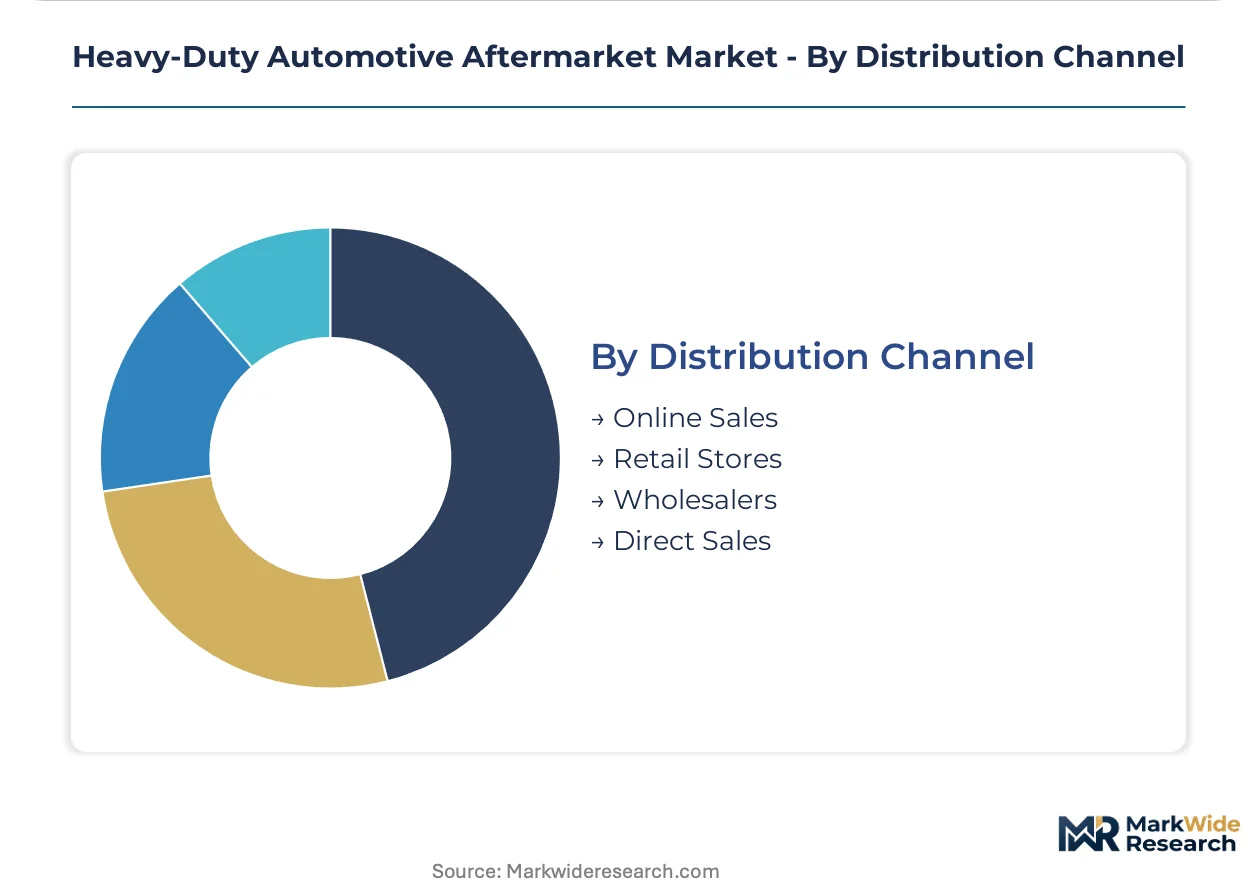
- Online Sales:Digital procurement platforms serving independent repair shops now integrate VIN-specific fitment verification and next-day delivery guarantees. Shop owners in Tennessee and Alabama increasingly bypass counter sales for e-commerce portals that consolidate supplier relationships and reduce transaction friction.
- Retail Stores:Counter-based operations in metropolitan Minneapolis and Denver maintain relevance through immediate availability of high-turn brake friction and filtration SKUs, though their share erodes as fleet procurement centralizes.
- Wholesalers:Traditional jobber distributors serving fragmented garage networks face margin compression from manufacturer-direct programs.
- Direct Sales:Manufacturer service agreements with national fleets bundle parts, labor, and compliance documentation into single-source contracts.
Direct sales hold the largest share; online sales are climbing the fastest as independent shops digitize procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parts manufacturing clusters concentrate in industrial corridors where heavy-duty vehicle production and fleet density overlap. Germany, the United States, Japan, China, and India anchor regional aftermarket ecosystems through distinct regulatory and operational logics.
United States
Class 8 truck fleet aging and e-commerce logistics sustain brake friction and tire consumption across high-stop urban routes. EPA Phase 2 greenhouse gas standards enforce durability mandates for diesel particulate filters and selective catalytic reduction modules. Fleet operators in Illinois and Ohio migrate toward manufacturer-direct procurement, bypassing traditional jobber distributors for integrated maintenance contracts.
Germany
Commercial vehicle engineering excellence supports premium aftermarket component production for exhaust aftertreatment and sensor-integrated brake systems. KBA enforces stringent type-approval requirements for replacement parts entering the EU market. Industrial clusters in Baden-Württemberg and Bavaria house remanufacturing facilities serving Central European logistics corridors.
Japan
Precision manufacturing heritage drives high-performance filtration and thermal management component exports. METI promotes circular economy incentives through certified remanufacturing programs. Nagoya-based suppliers anchor supply chains for Southeast Asian fleet markets.
China
Domestic heavy-duty truck production volume exceeding one million units annually generates massive captive aftermarket demand. MIIT implements GB standards for emissions compliance and component durability verification. Shandong Province manufacturers dominate brake friction and suspension component production for domestic and export markets.
India
Vocational truck fleet expansion in mining and construction sustains severe-duty parts consumption for filtration and drivetrain components. BIS mandates certification for automotive replacement parts under compulsory registration schemes. Tamil Nadu and Maharashtra industrial corridors concentrate remanufacturing and reconditioning operations serving South Asian logistics networks.
Heavy-Duty Automotive Aftermarket Market Key Industry Players
Integrated system suppliers and specialized component fabricators split the market between bundled service contracts and discrete part replacement. The structure tilts toward consolidation as national fleet procurement centralizes vendor relationships around uptime guarantees and telematics integration. Three archetypes dominate: full-line manufacturers with diagnostic technology platforms, tire specialists with retreading and lifecycle management networks, and independent parts distributors with regional fill-rate capabilities. Competitive moves concentrate on strategic partnerships embedding hardware sales within software-enabled monitoring services, plus selective backward integration into friction material and rubber compound production.
Among diversified industrial conglomerates, Bosch and Continental AG occupy positions exemplifying the integrated-system archetype through diagnostic and sensor-embedded hardware portfolios. Michelin anchors the tire-specialist vector with lifecycle management capabilities spanning original equipment and replacement channels. Denso Corporation represents the precision-component tier with thermal and emissions control expertise rooted in Japanese manufacturing heritage.
| Leading Market Players |
|---|
| Denso Corporation |
| Michelin |
| 3M Company |
| Dorman Products |
| Goodyear |
| Bosch |
| Bridgestone |
| Detroit Diesel Corporation |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Shandong Province brake friction manufacturing clusters anchor global supply capacity for heavy-duty applications, with thermal-resistant compound production feeding directly into fleet procurement pricing power across North American logistics corridors. EPA Phase 2 durability mandates for aftertreatment assemblies compress replacement intervals and elevate certified component premiums above non-verified alternatives.
Pricing Analysis
Extended maintenance contracts bundling parts, labor, and uptime guarantees generate the highest lifetime value in after-sales revenue tiers. Three-tier pricing structure across premium OEM-equivalent, standard aftermarket, and economy remanufactured levels separates fleet procurement desks from independent repair shops. Pricing pressure stems from consolidated OEM diagnostic protocol restrictions that limit independent service provider competitiveness. Fleet operators exhibit lowest price sensitivity due to uptime guarantee requirements, while owner-operators purchasing through retail counters demonstrate highest elasticity.
Supply Chain Analysis
Neodymium and cerium feedstock volatility from Chinese and Australian rare earth extraction operations destabilizes catalytic converter substrate costs. Magnetic sensor assemblies and exhaust aftertreatment hardware draw from concentrated upstream mineral processing. Single-source vulnerability in proprietary telematics protocol licensing creates bottlenecks for multi-brand fleet service equipment. Distribution runs through manufacturer-direct service agreements with national carriers, bypassing traditional jobber intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-duty automotive aftermarket demand tracks Class 8 fleet replacement cycles and e-commerce logistics intensity, positioning current expansion as mid-cycle recovery rather than peak.
For Market Incumbents: Insulate service revenue streams by embedding diagnostic technology within hardware sales to capture recurring fleet contracts. Deepen backward integration into friction material compound production to offset rare earth price volatility. Certification investment in EPA-verified remanufacturing programs defends against emerging compliance documentation requirements. For New Entrants and Emerging Players: Rural vocational service territories in Michigan and Wisconsin represent the most penetrable entry point due to technician certification bottlenecks constraining incumbent expansion. Blockchain-enabled parts provenance platforms address fleet procurement counterfeit concerns with minimal capital intensity. Telematics-integrated inventory pre-positioning offers a differentiated go-to-market angle against established distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fleet procurement centralization favors scaled service networks with embedded software capabilities. Target acquisition archetypes include regional distributors with high fill-rate performance and established OEM diagnostic access. Monitor CARB Advanced Clean Trucks rule adoption velocity across additional states as the signal for electric powertrain cooling system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Technology Integration | Bosch and Continental AG embed sensor-embedded brake systems to capture recurring fleet service contracts. |
| Remanufacturing Program Expansion | EPA-verified powertrain component programs reduce total cost of ownership for independent repair shops. |
| Telematics-Inventory Positioning | Real-time vehicle health data enables distributor pre-positioning of high-failure components at regional hubs. |
| Blockchain Provenance Tracking | Immutable certification records address fleet procurement concerns about counterfeit brake friction materials. |
| Certified Technician Network Buildout | SCR and DPF troubleshooting training programs expand workforce scalability across rural service territories. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with fleet procurement directors, aftermarket service managers, OEM platform engineers, and independent repair shop owners; and secondary validation through EPA enforcement records, NHTSA FMVSS documentation, vehicle production databases, and IHS Markit registration data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators established volume and value estimates.
Forecast inputs across vehicle class, propulsion architecture, service type intensity, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from replacement cycle compression rates and fleet telematics adoption curves. Modeled assumptions incorporated EPA Phase 2 durability mandate enforcement timelines and e-commerce logistics fleet expansion trajectories.
Practitioners should monitor rare earth element price volatility, CARB rule adoption geography expansion, and predictive maintenance platform penetration rates for early signals of forecast revision. Cross-checking against vehicle miles traveled data and Class 8 tractor order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market