
 Automotive Body-In-White Market | 2026-2036
Automotive Body-In-White Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Body-In-White Market Analysis
Mexico is rewriting North American BIW supply dynamics as OEMs add stamping and welding capacity to serve EV platform production. Gestamp Automocion SA leverages its European heritage to dominate aluminum-intensive body architecture design. Thyssenkrupp AG anchors high-strength steel supply through integrated rolling and coating operations. Martinrea International Inc. competes on proximity logistics, operating plants within fifty kilometers of major Detroit Three assembly complexes.
Automotive Body-In-White denotes the welded sheet-metal shell of a vehicle before painting, comprising structural members, closures, and crash management systems formed from cold-rolled steel grades up to 1,500 MPa tensile strength, aluminum extrusions, and emerging fiber-reinforced composites. This assembly provides torsional rigidity, occupant protection, and mounting interfaces for powertrain and chassis components across passenger and commercial vehicle programs. Steel retains volume leadership in mass-market segments where cost-per-kilogram and repair network compatibility dominate OEM sourcing criteria, while aluminum claims margin-rich premium electric vehicle platforms where every kilogram of mass reduction extends battery range. Composite and magnesium categories remain nascent, constrained by cycle times, joining technology maturity, and recycling infrastructure gaps that limit scale economics outside motorsport and ultra-luxury applications.
EPA corporate average fuel economy standards and NHTSA crashworthiness protocols jointly dictate material thickness, grade selection, and joining method validation for US-market vehicles. EU REACH chemical restrictions and the EU Green Deal carbon-border adjustment mechanism are forcing European suppliers to document embodied emissions across steel and aluminum supply chains. China's MIIT new-energy vehicle mandates and GB standards for structural integrity shape BIW design priorities for export-oriented capacity. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent lifecycle assessment methodologies threaten to fragment material qualification and lock suppliers into region-specific metallurgical strategies.
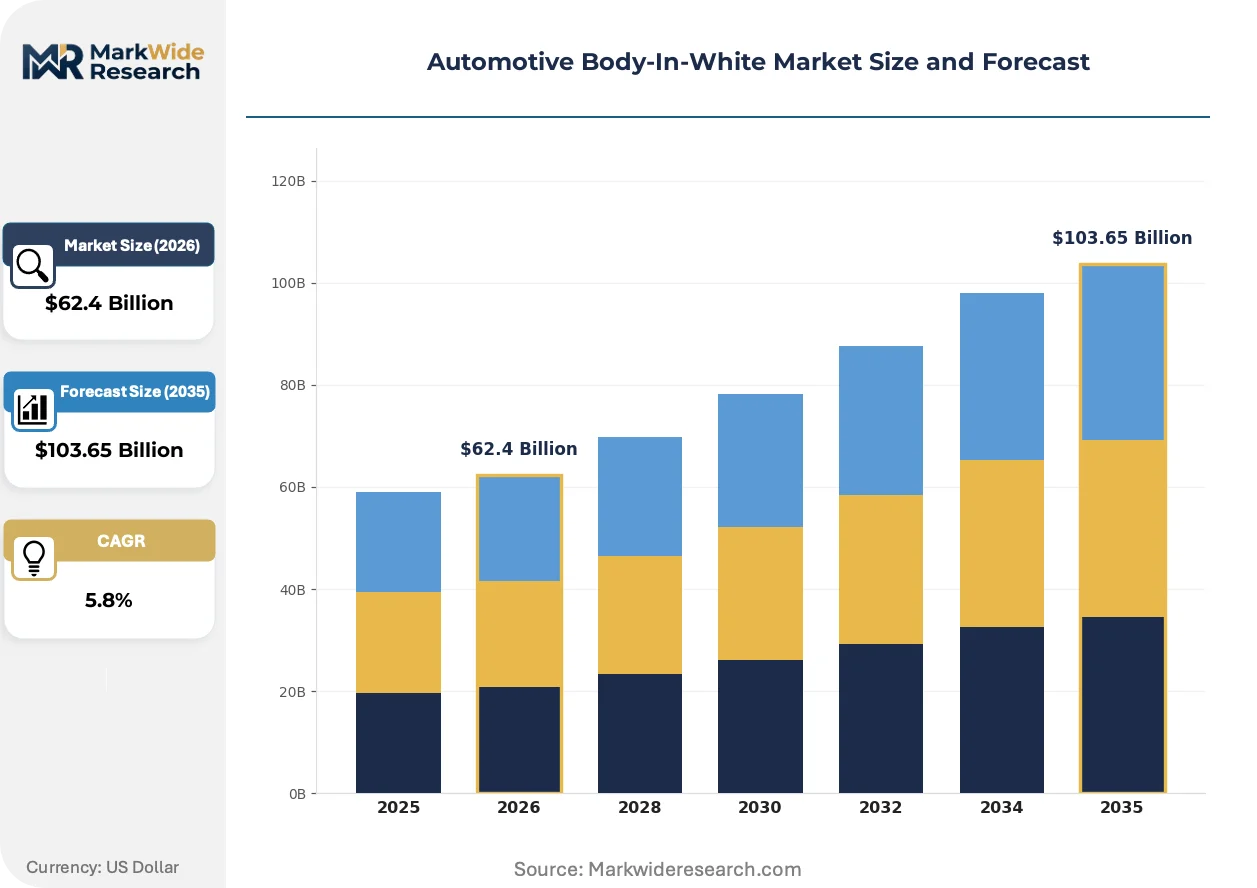
Market Dynamics
EU Green Deal carbon-border adjustment mechanisms and F-Gas Regulation phase-downs are forcing automakers to requalify entire supply chains around embodied emissions documentation, compressing qualification timelines for traditional steel grades while elevating aluminum and composite architectures.
Growth Catalysts
- EU Green Deal carbon-border mechanisms:Automakers must document cradle-to-gate emissions for every ton of steel and aluminum, accelerating supplier switches to electric-arc-furnace producers and hydro-powered aluminum smelters.
- MIIT new-energy vehicle mandates:China's production quotas for battery electric vehicles are pulling aluminum-intensive platform designs into mass-market segments previously dominated by mild steel.
- Tailored blank hot forming:This process allows variable-thickness steel panels in single press cycles, cutting weight fifteen percent without switching material classes or disrupting repair networks.
Market Restraints
- Scrap aluminum price volatility:Secondary aluminum input costs swing with energy prices, eroding the cost stability that OEMs expect from closed-loop recycling claims.
- High-strength steel supply concentration:Integrated rolling and coating capacity clusters in Germany, Japan, and South Korea, exposing North American stamping plants to ocean freight disruption.
- Composite joining limitations:Adhesive cure cycles and mechanical fastening complexity prevent fiber-reinforced polymers from matching steel stamping throughput in high-volume assembly.
Strategic Opportunities
- Thai-Japanese EV platform localization:Battery assembly investments around Bangkok are creating demand for aluminum body shops without established supplier incumbency.
- IRA domestic content bonuses:North American assembly of battery electric vehicles qualifies for tax credits when BIW sourcing meets local content thresholds, reshaping stamping plant geography.
- Digital twin crash simulation:Virtual validation of multi-material joints is compressing prototype cycles from months to weeks, enabling faster aluminum-steel hybrid architecture deployment.
Industry Challenges
- Multi-material welding technician scarcity:Friction stir welding and laser brazing of aluminum to steel demands certifications that vocational programs have not scaled to match OEM hiring timelines.
- Paint shop conversion capex:Aluminum body shells require dedicated pretreatment lines and temperature-controlled electrocoat baths, forcing billion-dollar decisions at plants serving multiple platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Body-In-White Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Magnesium Manufacturing Stage: Stamping, Welding, Painting, Assembly End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Laser Cutting, Hydroforming, 3D Printing, Robotics |
| Companies Covered | Magna International Inc., Gestamp Automocion SA, Benteler International AG, Thyssenkrupp AG, KIRCHHOFF Automotive GmbH, Autokiniton US Holdings, Inc, Martinrea International Inc., CIE Automotive, Voestalpine AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Body-In-White Market Emerging Trajectories
Joining technology advances and lifecycle assessment standardization are collapsing the traditional trade-off between lightweighting ambition and manufacturing pragmatism, enabling material mixes that were uneconomical at prior production scales.
Tailored fiber placement for thermoplastic composites is rendering obsolete the assumption that carbon fiber belongs only in motorsport or luxury vehicle roofs. Battery electric vehicle platforms from premium German and Korean OEMs now specify thermoplastic composite floor pans and structural battery enclosures, cutting mass forty percent versus aluminum equivalents while matching steel stamping cycle times. This convergence is compressing the cost gap between aluminum and composite architectures faster than most supply chain forecasts assumed.
REACH chemical restrictions on hexavalent chromium conversion coatings are forcing European suppliers to adopt zirconium-based and thin-film silane pretreatments for aluminum body panels. The industrial consequence is a complete retooling of surface treatment lines at stamping plants serving export-oriented German and Swedish OEMs. Premium electric vehicle segments are absorbing these conversion costs first, with mass-market platforms following as coating suppliers scale compliant chemistry volumes.
Fleet procurement departments at North American rental and commercial vehicle operators are unbundling body repair certification requirements from initial vehicle purchase contracts, creating direct relationships with aftermarket collision repair networks. This disintermediation of OEM-controlled service channels is most visible in commercial van segments serving last-mile delivery, where aluminum-intensive designs from Ford and Mercedes-Benz face repair network capacity constraints that steel-dominated legacy fleets avoided.
Automotive Body-In-White Market Segmentation
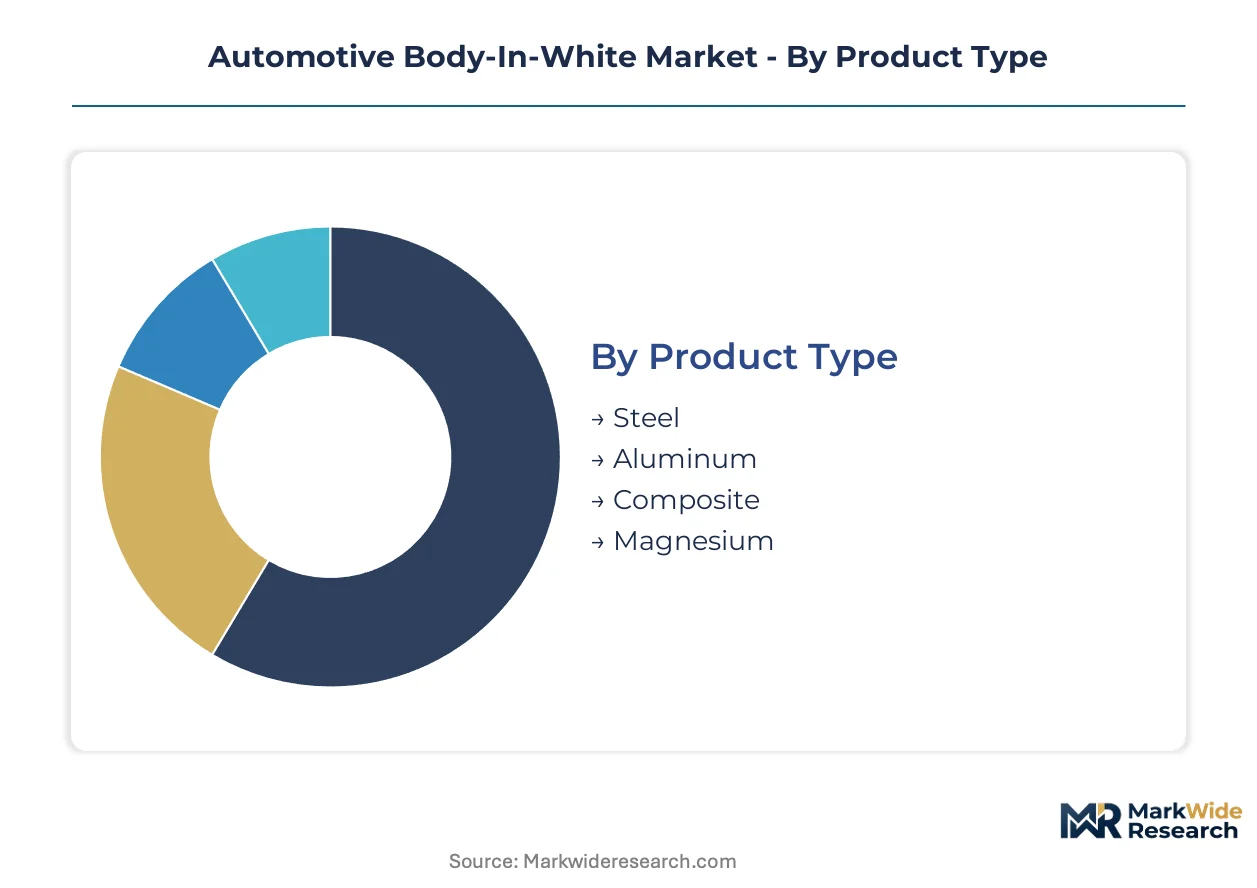
Material selection and manufacturing stage configurations determine capital intensity, cycle times, and regulatory compliance pathways across BIW supply chains. Segment boundaries blur as multi-material architectures force hybrid production setups and cross-trained technician pools.
Product Type:
Steel platforms turn over every 6-8 years on legacy architectures, while aluminum-intensive designs refresh every 3-4 years as EV battery chemistry evolves and range targets tighten.
- Steel:Cold-rolled grades from 340 MPa to 1,500 MPa tensile strength dominate mass-market platforms where repair network compatibility and cost-per-kilogram override lightweighting ambitions. Demand concentrates in Detroit Three truck programs and Chinese domestic-brand sedans where MIIT fuel economy mandates have not yet forced material substitution.
- Aluminum:Extrusions and sheet grades enable 40-50 percent mass reduction versus steel equivalents, justifying premium positioning in German and Korean battery electric platforms where every kilogram extends range. European OEMs localize aluminum body shops near battery assembly plants to minimize logistics complexity.
- Composite:Fiber-reinforced polymers serve structural battery enclosures and floor pans in low-volume premium EVs where thermoplastic cycle times now match metal stamping.
- Magnesium:Cast and thixomolded components address instrument panel beams and steering column brackets where flammability standards permit limited deployment.
Steel anchors the volume base while aluminum gains share at the steepest rate.
Manufacturing Stage:
Cost tier stratification separates billion-dollar paint shop investments from modular welding cells that tier-1 suppliers can relocate across continents.
- Stamping:Progressive and transfer presses form complex draw geometries from coil steel and aluminum sheet, with die changeover times determining line flexibility. German and Japanese press builders dominate high-tonnage equipment supply for 6,000-ton-class aluminum forming.
- Welding:Resistance spot welding retains steel dominance while laser brazing and friction stir welding enable aluminum-to-steel joints. Technician certification scarcity constrains expansion of multi-material welding capacity.
- Painting:Dedicated pretreatment lines and temperature-controlled electrocoat baths add $400-600 million per plant conversion for aluminum body shells.
- Assembly:Final body marriage operations integrate closures, structural battery enclosures, and crash management systems with torque-controlled fastening protocols.
Stamping commands the deepest capital commitment while welding attracts the most technology substitution.
End User:
Volume concentration separates platform-owning OEMs from captive tier-1 suppliers and independent aftermarket channels with diverging technical requirements.
- OEMs:Volkswagen, Toyota, and BYD control proprietary platform architectures and material qualification protocols, sourcing directly from integrated steel and aluminum producers.
- Tier-1 Suppliers:Gestamp, Magna, and CIE Automotive operate dedicated body shop contracts, investing in welding robotics and dimensional validation systems to defend program wins.
- Aftermarket Providers:Collision repair networks face aluminum certification gaps that steel-dominated legacy fleets avoided, creating capacity constraints for Ford and Mercedes-Benz commercial van operators.
- Vehicle Assemblers:Contract manufacturers like Magna Steyr and Valmet Automotive execute complete BIW production for niche and startup OEMs without captive stamping capacity.
OEMs retain architecture control while tier-1 suppliers absorb capital intensity.
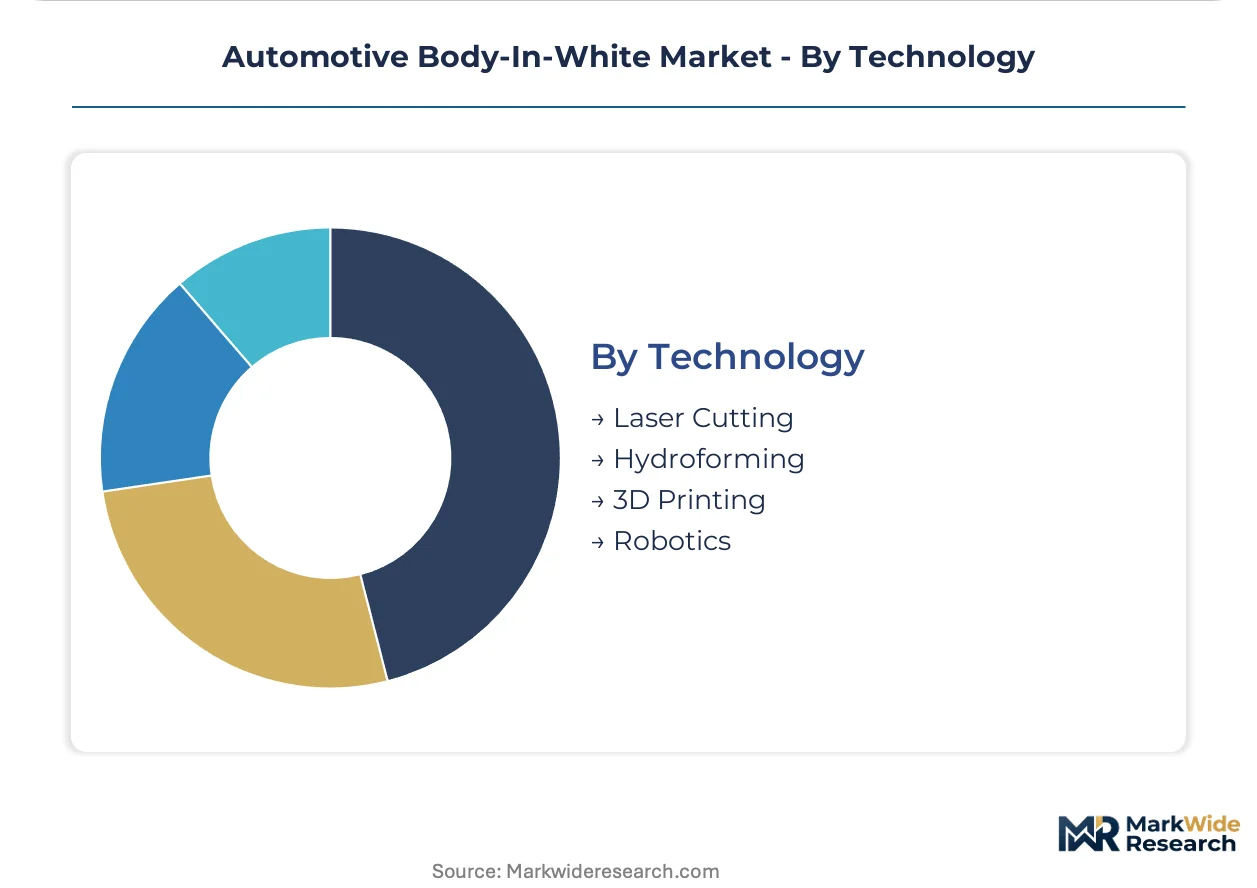
Technology:
Maturity gradients separate proven high-volume processes from emerging technologies constrained by throughput validation.
- Laser Cutting:Fiber laser systems trim tailored blanks and hot-formed components with 0.1 mm precision, enabling variable-thickness panels that cut weight without material class switching.
- Hydroforming:High-pressure fluid forming produces complex aluminum and steel sections with reduced die counts, serving structural rails and A-pillar reinforcements.
- 3D Printing:Directed energy deposition repairs stamping dies and produces low-volume bracketry, not yet qualified for primary structural members.
- Robotics:Seven-axis welding arms with force-controlled end effectors execute aluminum-to-steel joints that human technicians cannot reproduce consistently.
Robotics underpins quality consistency while laser cutting expands application scope fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated rolling mills and aluminum smelters cluster in Germany, China, and Japan, exposing stamping plants elsewhere to freight disruption. OEMs are localizing body-in-white capacity near battery assembly hubs to compress logistics. Regulatory divergence between EPA, EU Green Deal, and MIIT mandates is forcing region-specific metallurgical strategies.
United States
Detroit Three truck programs sustain demand for high-strength steel grades up to 1,500 MPa. EPA corporate average fuel economy standards and NHTSA crashworthiness protocols dictate material thickness and joining validation. Stamping capacity concentrates in Michigan and Ohio, with new aluminum welding cells added near Kentucky and Tennessee battery plants.
Germany
Premium electric vehicle platforms from Volkswagen, BMW, and Mercedes-Benz drive aluminum-intensive body architecture adoption. EU Green Deal carbon-border adjustment mechanisms and REACH chemical restrictions force suppliers to document cradle-to-gate emissions and retool surface treatment lines. Body shops cluster in Lower Saxony and Bavaria adjacent to battery assembly operations.
China
MIIT new-energy vehicle production quotas pull aluminum platform designs into mass-market segments previously dominated by mild steel. GB standards for structural integrity shape BIW export specifications. Capacity concentrates in Yangtze River Delta and Pearl River Delta regions where BYD, NIO, and Tesla operate integrated battery-vehicle complexes.
Mexico
OEMs are adding stamping and welding capacity to serve North American EV platform production from Monterrey and Mexico City Metro hubs. IRA domestic content bonuses reshape sourcing geography for battery electric vehicles assembled in the region. Suppliers leverage proximity to Detroit Three assembly complexes while navigating cross-border steel and aluminum tariff exposure.
Japan
Toyota and Honda proprietary platform architectures sustain demand for advanced high-strength steel and hybrid material qualification. METI carbon neutrality roadmaps and JIS standards guide material substitution timelines. Industrial concentration in Aichi Prefecture around Nagoya anchors tier-1 supplier ecosystems for both domestic and export vehicle programs.
Automotive Body-In-White Market Vendor Landscape
Integrated steel-aluminum producers and modular welding specialists split the market into distinct capability tiers. The vendor base clusters around three strategic archetypes: European heritage aluminum architects, Asian high-strength steel integrators, and North American proximity logistics operators. Consolidation pressure is accelerating through capacity expansion near battery assembly hubs and strategic partnerships for multi-material joining technology licensing.
Among European heritage specialists, Gestamp Automocion SA and Thyssenkrupp AG occupy positions reflecting deep aluminum architecture and integrated rolling expertise respectively. Martinrea International Inc. exemplifies the North American proximity model with operations positioned near major Detroit Three assembly complexes. These three entities represent the dominant competitive archetypes without exhausting the competitive set.
| Leading Market Players |
|---|
| Magna International Inc. |
| Gestamp Automocion SA |
| Benteler International AG |
| Thyssenkrupp AG |
| KIRCHHOFF Automotive GmbH |
| Autokiniton US Holdings, Inc |
| Martinrea International Inc. |
| CIE Automotive |
| Voestalpine AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European electric-arc furnace steel production is compressing spot prices for high-strength grades while simultaneously pressuring integrated aluminum smelters to defend contract premiums through carbon-intensity documentation. This utilization asymmetry between steel and aluminum supply bases is forcing OEM procurement teams to rebalance material qualification timelines against total landed cost targets.
Pricing Analysis
EU Green Deal carbon-border adjustment mechanisms dictate the pricing tier structure across steel and aluminum supply chains. Three-tier pricing structure across premium, standard, and economy levels separates hydro-powered aluminum from coal-intensive primary metal and secondary scrap grades. Price differentiation centers on embodied emissions certification and MIIT compliance documentation for Chinese export eligibility. Pricing pressure stems from scrap aluminum volatility eroding closed-loop recycling economics. Mass-market OEMs exhibit highest price sensitivity, while premium electric vehicle platforms absorb carbon-premium pass-through with minimal volume elasticity.
Supply Chain Analysis
Extended payment terms from German OEMs now stretch to 120 days, forcing tier-1 suppliers to draw from supply-chain finance facilities anchored by aluminum inventory. Geographic concentration clusters integrated rolling capacity in Germany, Japan, and South Korea, while aluminum smelting feeds from hydro-powered Nordic and Canadian operations. Raw material dependencies center on high-grade iron ore, bauxite, and secondary scrap aluminum flows. Single-source vulnerability in friction stir welding equipment exposes multi-material body shops to German and Japanese machinery lead times. Distribution runs through captive tier-1 welding cells positioned within fifty kilometers of battery assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic is displacing component-level procurement as OEMs consolidate body architecture around shared EV skateboards, creating winner-take-most dynamics for suppliers achieving cross-platform welding certification.
For Market Incumbents: Entrench aluminum-intensive architecture expertise through captive supply of structural extrusions and hot-forming capacity in Lower Saxony and Bavaria clusters. Defend program wins by securing friction stir welding technician pipelines ahead of OEM hiring timelines. Multi-material joining certification scarcity represents the primary margin defense lever against emerging composite specialists. For New Entrants and Emerging Players: Thai-Japanese EV platform localization around Bangkok represents the most penetrable entry point, given absent incumbent welding infrastructure and battery assembly investments already committed. Target aluminum body shop contracts for pickup truck derivatives serving Australian and Southeast Asian export markets. Go-to-market angle should emphasize digital twin crash simulation capabilities that compress OEM prototype cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 suppliers with dedicated body shop contracts spanning multiple OEM platforms and multi-year program lifecycles. Long-term viability hinges on exposure to premium electric vehicle architectures rather than legacy steel-intensive truck platforms. Acquisition target archetype: mid-cap welding specialists with friction stir certification and proximity to Kentucky-Tennessee battery corridors. Signal to watch: OEM announcements of shared EV platform licensing to multiple brand houses.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen's unified cell format reduces body architecture variants, concentrating welding contract value with certified tier-1 suppliers. |
| Battery Supply Agreement | CATL and LG Energy Solution cell sourcing commitments anchor aluminum body shop localization decisions near assembly plants. |
| Software-Defined Vehicle Investment | Digital twin integration enables virtual validation of multi-material joints, collapsing prototype development timelines for hybrid architectures. |
| Geographic Manufacturing Footprint | Monterrey and Mexico City Metro stamping investments capture IRA domestic content bonuses for North American EV assembly. |
| Charging Infrastructure Partnership | Fast-charging network density influences EV platform range targets, indirectly driving aluminum-intensive body specifications. |
Methodological Framework
A standing panel of OEM platform engineers, tier-1 supplier procurement directors, aftermarket collision repair network managers, and aluminum smelter commercial leads provided ongoing calibration across primary interview rounds. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and EU ETS carbon price series. Bottom-up segment sizing triangulated against top-down OEM production forecasts across the analysis window.
Scenario bracketing around MIIT mandate acceleration, EU carbon-border enforcement timing, and IRA domestic content threshold revisions bounded the projection range. Segmentation dimensions modeled include vehicle class, propulsion architecture, material content per vehicle, and regional production cluster. CAGRs derived from elasticity-adjusted volume projections incorporating battery chemistry evolution and range target tightening. Industry-specific inputs encompassed die changeover time benchmarks and friction stir welding capacity utilization rates.
Practitioners should monitor EU ETS price spikes, scrap aluminum LME spreads, and NHTSA crashworthiness protocol updates for early signals of material substitution acceleration. Forecasts reflect assumptions regarding battery cost curves and charging infrastructure deployment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market