
 Automotive Collision Repair Market | 2026-2036
Automotive Collision Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Collision Repair Market Analysis
Light commercial fleet operators is broadening their share of collision repair procurement as last-mile delivery vehicle counts rise. Caliber Collision leverages its insurer-direct partnerships to sustain national coverage density. Gerber Collision & Glass anchors its position through integrated glass and body repair capabilities. Boyd Group Services differentiates via cross-border scale across North American markets.
Automotive collision repair encompasses the restoration of vehicle structural integrity, exterior panels, and mechanical systems following impact damage, typically involving steel or aluminum bodywork, advanced joining techniques, and OEM-specification refinishing to return crashworthiness and appearance. The repair type dimension remains the core revenue axis, with body repair occupying the largest volume pool while paintless dent repair captures superior margins on minor damage. Among technology segments, 3D scanning is displacing traditional measuring systems in premium frame restoration, whereas computerized estimating dominates transaction velocity across insurance-channel workflows.
Federal EPA guidelines govern refinishing emissions and hazardous waste disposal, while NHTSA crashworthiness standards dictate repair procedures for structural components on newer vehicle platforms. State-level insurance regulations in California, Texas, and Florida shape appraisal methodologies and direct-repair program eligibility. Stakeholders must monitor OEM certification requirements as vehicle architectures shift toward mixed-material construction.
Market Dynamics
Aluminum-intensive vehicle architectures are forcing collision repair networks to retool capital equipment and technician certification simultaneously. OEM certification requirements now gate access to structural repair procedures on newer platforms.
Growth Catalysts
- EPA Emissions Standards:Refinishing shops in the United States face mandatory volatile organic compound limits that accelerate adoption of waterborne paint systems and high-efficiency spray booth investments.
- Last-Mile Delivery Fleet Expansion:Light commercial vehicle counts operated by parcel and grocery delivery services are broadening maintenance contract scopes to include collision coverage.
- 3D Scanning Technology:Frame measuring accuracy demands on mixed-material vehicles are pulling repair shops toward laser-based dimensional verification systems.
Market Restraints
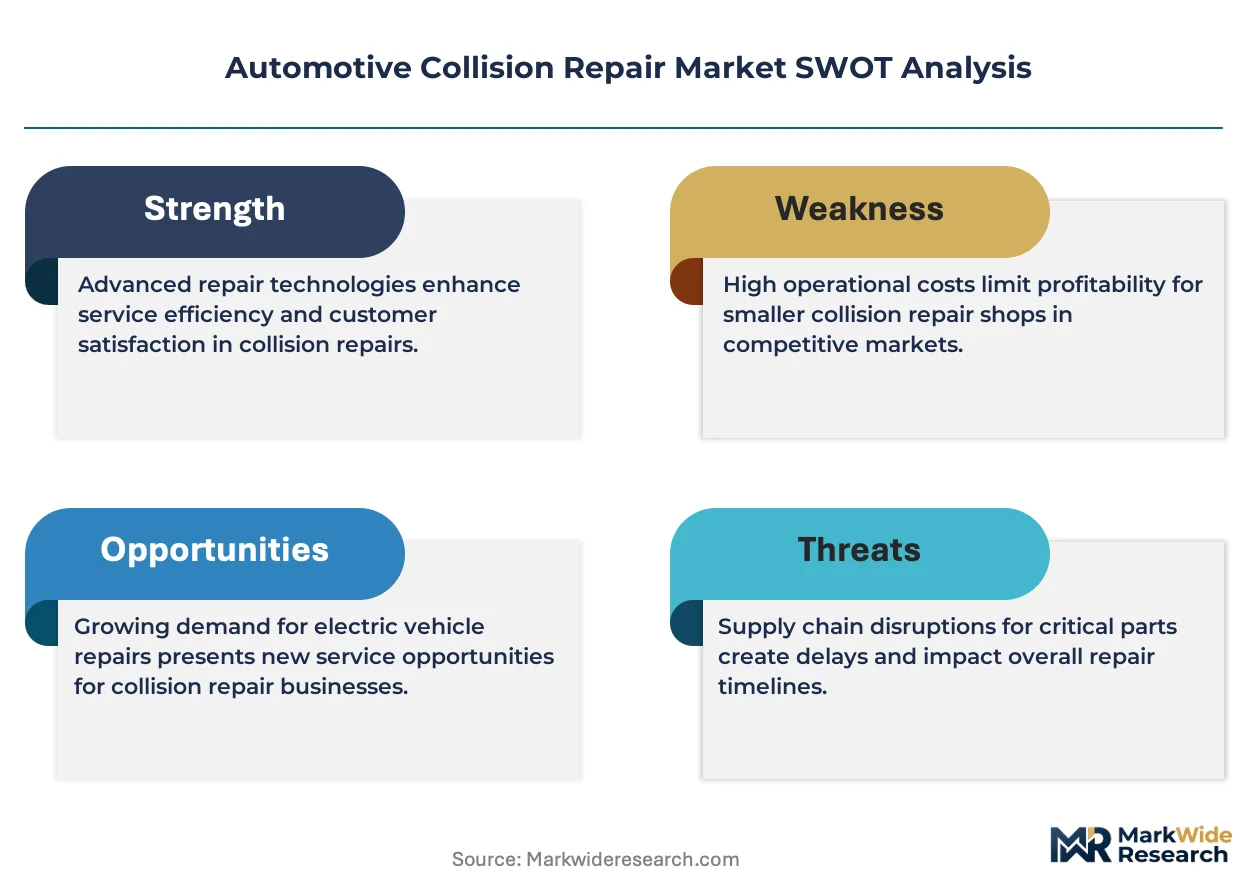
- Aluminum Repair Equipment Costs:Dedicated clean-room environments and specialized welding systems for aluminum bodywork impose capital barriers on independent single-location operators.
- OEM Parts Sourcing Concentration:Structural component availability for newer vehicle platforms depends on constrained certified distribution channels controlled by manufacturer networks.
- Technician Certification Lags:I-CAR and manufacturer-specific aluminum repair credentials require training timelines that outpace shop capacity expansion needs.
Strategic Opportunities
- Insurer-Direct Repair Program Expansion:Preferred shop networks in the United States offer volume commitments that justify equipment investments and technician training amortization.
- Glass-Body Integration:Advanced driver-assistance system calibration requirements following windshield replacement are converging glass and collision repair service lines.
- Used Vehicle Market Residual Value Protection:Certified pre-owned programs are mandating documented OEM-specification repair histories that favor certified shop networks.
Industry Challenges
- Electronics Integration Complexity:Post-repair calibration of adaptive cruise control, lane-keeping, and automatic emergency braking systems requires diagnostic equipment and software subscriptions beyond traditional body shop capabilities.
- Material-Specific Skill Fragmentation:Technicians trained on steel unibody construction face competency gaps in aluminum joining techniques and carbon fiber repair protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Collision Repair Market |
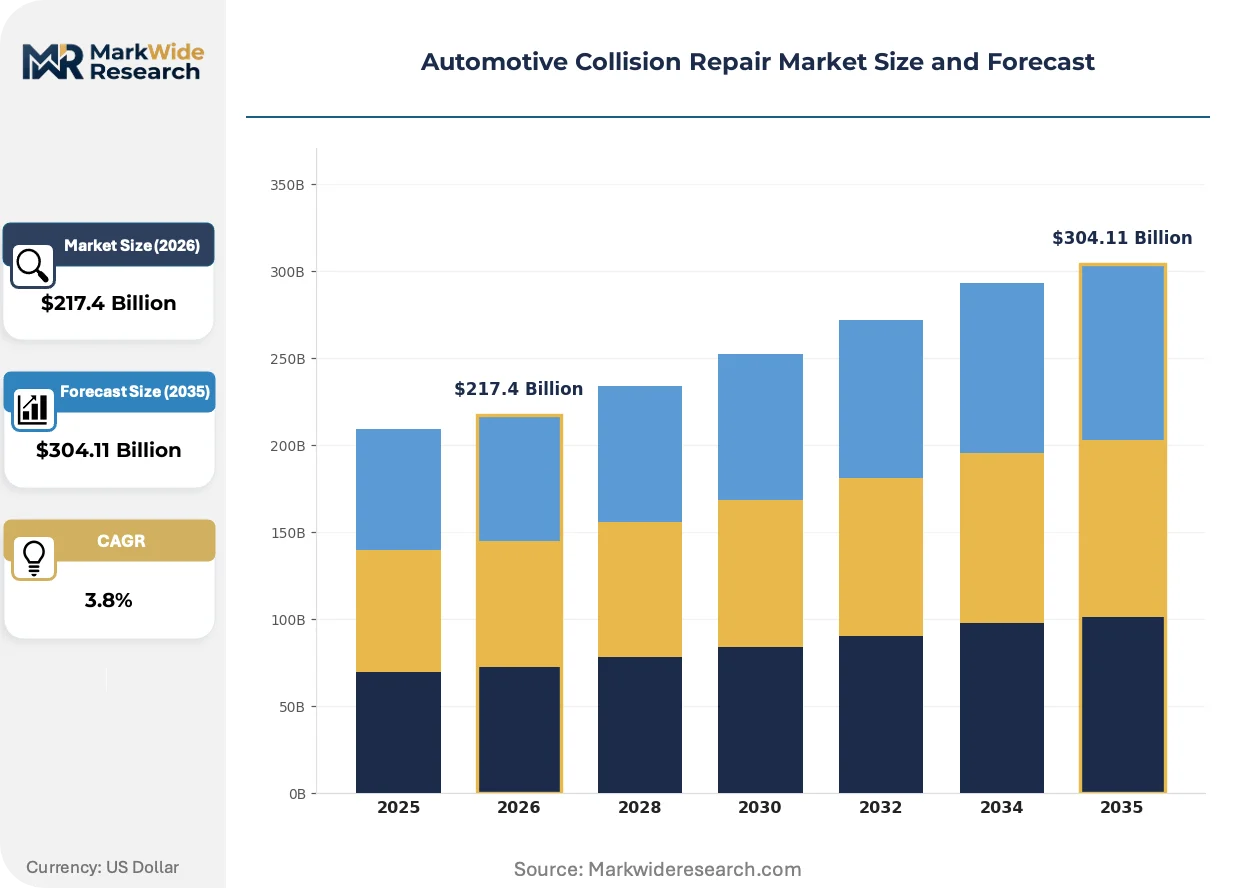
| Market Size in 2026 | $217.4 Billion |
| Market Size in 2035 | $304.11 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Repair Type: Body Repair, Paintless Dent Repair, Frame Repair, Mechanical Repair Technology: Computerized Estimating, Laser Measurement, 3D Scanning, Tire Alignment End User: Vehicle Owners, Insurance Companies, Fleet Operators, Dealerships Service Type: Full-Service Repair, Mobile Repair, Custom Repair, Assisted Repair |
| Companies Covered | Gerber Collision & Glass, Crash Champions, Caliber Collision, Boyd Group Services, AutoNation Collision Centers, Service King Collision, CARSTAR, Fix Network World, ABRA Auto Body Repair of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Collision Repair Market Emerging Trajectories
Digital measurement systems are compressing cycle times while regulatory pressure on refinishing emissions intensifies capital requirements. Repair networks are consolidating to amortize compliance costs across volume bases.
Computerized estimating platforms are unifying insurance adjuster workflows with shop management systems through real-time data exchange. National multi-shop operators deploy these integrations to standardize cycle time reporting and parts procurement across locations. The technology is unifying previously fragmented documentation requirements into single-platform compliance.
REACH regulations in the European Union restrict hazardous substance content in automotive refinishing products, forcing reformulation of primers and clearcoats. Manufacturers serving EU markets must certify compliance through third-party testing laboratories. Collision repair chains with cross-border operations face dual compliance burdens when sourcing materials for US and EU locations.
Fleet procurement departments are centralizing collision repair vendor selection through national maintenance contracts that specify OEM-certified procedures and guaranteed turnaround times. Direct repair programs operated by major insurers are displacing traditional drive-in estimates with photo-based initial assessments. This concentration is most visible in urban United States markets where last-mile delivery vehicle density supports dedicated fleet service lanes.
Automotive Collision Repair Market Segmentation
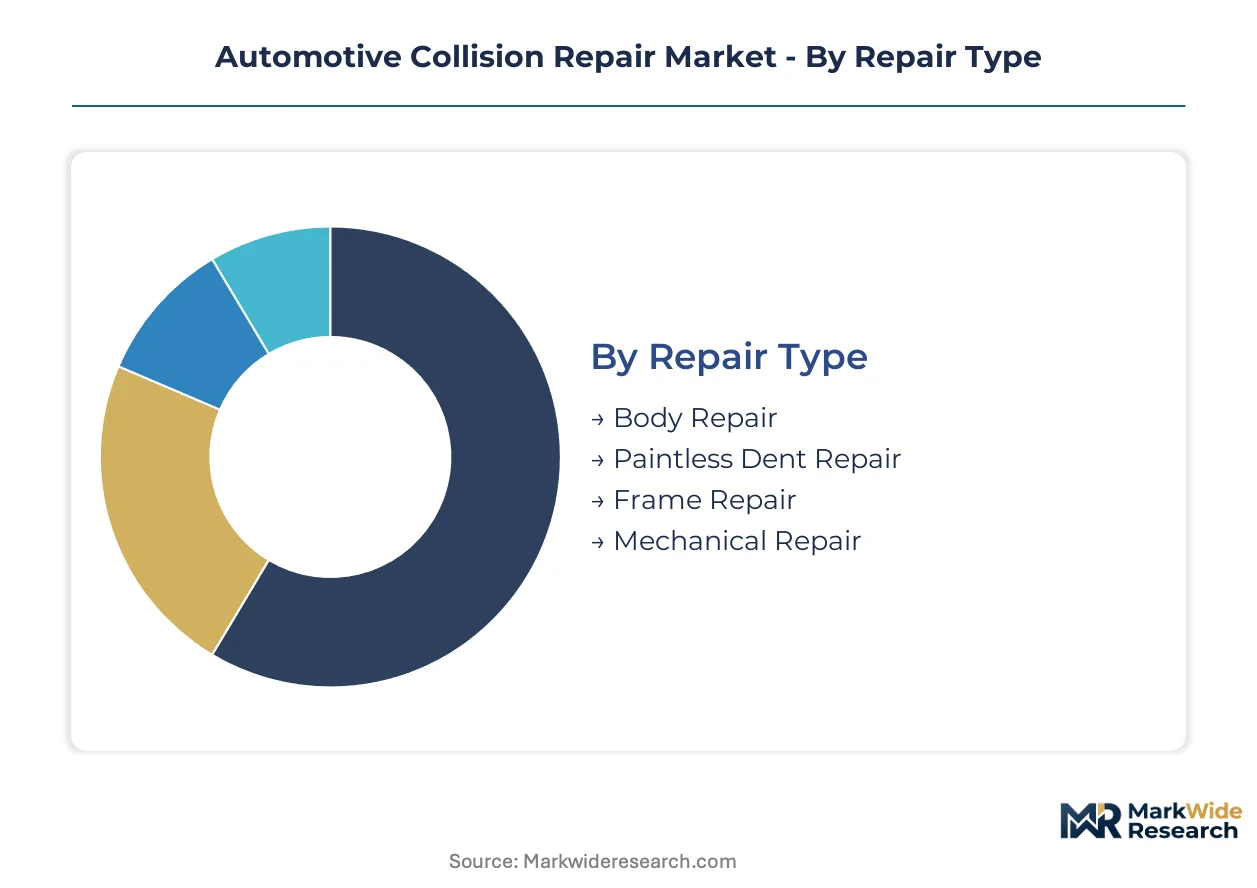
Collision repair segmentation reveals how capital intensity, certification requirements, and insurance channel economics fragment service delivery models. Repair type and technology dimensions drive equipment investment decisions, while end-user concentration shapes pricing power and contract structures.
Repair Type:
Customization intensity ranges from standardized insurance-channel bodywork to specialized aluminum frame restoration requiring OEM certification gating.
- Body Repair:Panel replacement and refinishing operations constitute the volume foundation of collision networks, absorbing the majority of insurance-direct claim dollars. United States multi-shop operators concentrate procurement here to amortize spray booth EPA compliance costs across high throughput.
- Paintless Dent Repair:Non-invasive techniques preserve factory finishes on minor damage, commanding margin premiums through reduced cycle times and material avoidance. Demand concentrates in hail-prone corridors of Texas and Florida where insurer-direct programs route high-volume cosmetic claims to certified technicians.
- Frame Repair:Structural restoration demands laser measurement systems and aluminum-specific welding environments.
- Mechanical Repair:Suspension, steering, and drivetrain restoration following impact damage.
Leading the category by volume: Body Repair. Expanding most quickly: Paintless Dent Repair.
Technology:
Cost tier stratification separates premium diagnostic platforms from entry-level estimating tools accessible to independent operators.
- 3D Scanning:Laser-based dimensional verification systems capture complete vehicle geometry for mixed-material architectures, displacing traditional frame gauges in certified networks. OEM certification requirements for newer aluminum-intensive platforms pull adoption toward dealer-affiliated and large multi-shop operations in California and Texas.
- Computerized Estimating:Digital platforms unify adjuster workflows with shop management systems, compressing documentation cycles and standardizing parts procurement. Insurance-direct repair programs mandate these integrations, concentrating adoption among United States networks serving national carrier contracts.
- Laser Measurement:High-precision frame verification for structural repairs on unibody and space-frame vehicles.
- Tire Alignment:Post-collision suspension geometry correction integrated with ADAS calibration requirements.
Highest equipment investment: 3D Scanning. Broadest transaction velocity: Computerized Estimating.
End User:
Customer type determines contract structure, from retail walk-in pricing to national fleet maintenance agreements with guaranteed turnaround terms.
- Insurance Companies:Direct repair programs and preferred shop networks concentrate volume commitments that justify capital equipment and technician training amortization. Carrier procurement departments in the United States increasingly mandate photo-based initial assessments and guaranteed cycle time penalties.
- Fleet Operators:Last-mile delivery and light commercial vehicle managers are expanding collision coverage within national maintenance contracts, specifying OEM-certified procedures and dedicated service lanes. Parcel and grocery delivery density in urban United States markets supports this procurement centralization.
- Vehicle Owners:Retail customers selecting repair providers through insurer referrals or independent search.
- Dealerships:OEM-affiliated service departments capturing warranty and certified pre-owned preparation work.
Dominating contract value: Insurance Companies. Gaining share fastest: Fleet Operators.
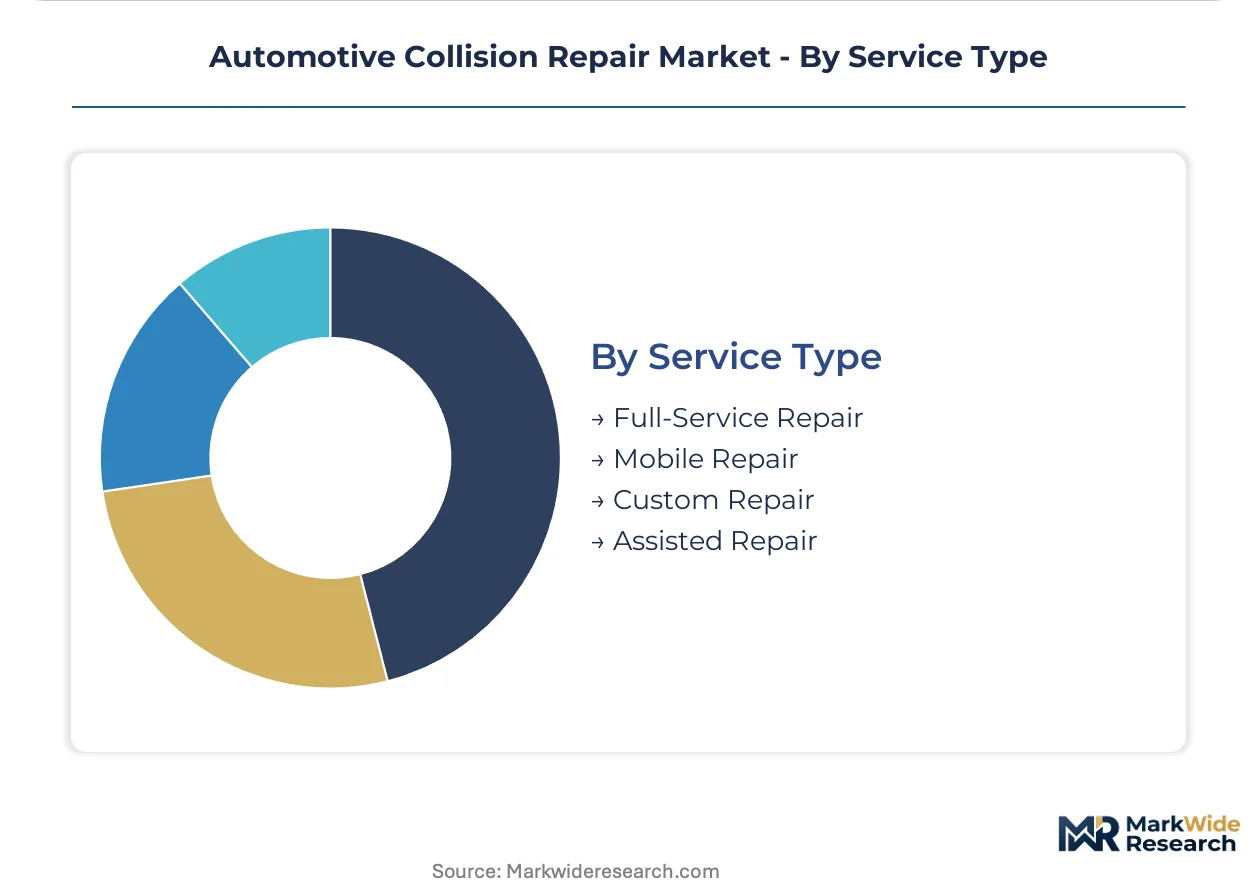
Service Type:
Volume-to-margin tradeoffs separate high-throughput full-service facilities from mobile operators capturing convenience premiums.
- Full-Service Repair:Integrated body, paint, and mechanical restoration under single-roof operations with EPA-compliant refinishing infrastructure. Multi-shop operators in the United States deploy this model to capture insurance-direct volume and amortize compliance investments across location networks.
- Mobile Repair:Paintless dent and minor cosmetic services delivered at fleet depots or customer locations, eliminating vehicle transport friction. Demand concentrates among last-mile delivery operators seeking minimized downtime in dense urban United States corridors.
- Custom Repair:Specialized restoration and modification services outside insurance-channel standardization.
- Assisted Repair:Customer-performed work supported by professional tooling and guidance.
Highest revenue concentration: Full-Service Repair. Steepest expansion trajectory: Mobile Repair.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collision repair capacity concentrates in vehicle-dense economies where insurer-direct programs and fleet procurement centralize demand. Production of aluminum-intensive platforms and ADAS-equipped vehicles pulls specialized service infrastructure toward manufacturer hubs and urban logistics corridors.
United States
Insurer-direct repair programs dominate channel economics, with national multi-shop operators capturing volume commitments from major carriers. EPA emissions standards mandate volatile organic compound limits that accelerate waterborne paint adoption in refinishing shops. Service density clusters in Texas hail corridors and California urban logistics hubs where last-mile fleet operators centralize maintenance contracts.
Germany
Premium vehicle manufacturing anchors demand for aluminum frame restoration and OEM-certified structural repair. REACH regulations restrict hazardous substance content in refinishing products, forcing reformulation of primers and clearcoats. Industrial concentration in Bavaria and Baden-Württemberg supports certified networks serving Audi, BMW, and Mercedes-Benz platforms.
China
Domestic EV production volumes are expanding collision coverage needs for battery-integrated vehicle architectures. MIIT standards govern vehicle repair qualifications and technician certification requirements. Yangtze River Delta manufacturing clusters around Shanghai drive service infrastructure investment for new energy vehicle platforms.
United Kingdom
Insurance market concentration shapes preferred shop network structures with guaranteed cycle time penalties. DVSA vehicle safety standards dictate post-repair inspection protocols for structural components. Greater London logistics density supports dedicated fleet service lanes for parcel and grocery delivery operators.
Japan
Keiressu-affiliated service networks maintain tight OEM control over certified repair procedures for hybrid and hydrogen platforms. METI industrial standards govern automotive service equipment specifications and technician training curricula. Kanto region vehicle density around Tokyo anchors premium bodywork demand for domestic luxury marques.
Automotive Collision Repair Market Vendor Landscape
Top-tier vendors anchor national coverage through insurer-direct partnerships, while regional specialists capture fleet maintenance contracts and certified aluminum repair niches. The market structure favors multi-location operators with capital to amortize EPA-compliant spray booth investments and 3D scanning equipment across volume bases. Three archetypes dominate: scale-driven consolidators with national density, integrated glass-body operators leveraging ADAS calibration convergence, and cross-border platforms spanning North American markets. Competitive moves concentrate on geographic expansion through acquisition and technology licensing for aluminum-specific welding environments.
Within the scale-driven consolidator tier, Caliber Collision and Crash Champions exemplify national coverage strategies built on carrier volume commitments. Boyd Group Services occupies a cross-border position spanning United States and Canadian markets. Gerber Collision & Glass represents the integrated service archetype, combining body repair with glass replacement capabilities to capture ADAS calibration workflows. These three companies collectively illustrate how capital intensity and certification requirements are concentrating market structure around multi-location operators with insurer-direct scale.
| Leading Market Players |
|---|
| Gerber Collision & Glass |
| Crash Champions |
| Caliber Collision |
| Boyd Group Services |
| AutoNation Collision Centers |
| Service King Collision |
| CARSTAR |
| Fix Network World |
| ABRA Auto Body Repair of America |
| Others |
Supply Flow & Price Mechanics
EPA emissions standards for volatile organic compounds gate both qualified supply and premium-tier pricing access, as refinishing shops must invest in waterborne paint systems and high-efficiency spray booths to serve insurer-direct programs. This environmental mandate concentrates procurement power among multi-location operators who amortize compliance costs across volume bases, while independent single-location operators face capital barriers that push them toward economy-tier positioning or exit.
Pricing Analysis
Margin tightening in economy-tier bodywork reflects aluminum repair equipment cost inflation and technician certification lags that compress independent shop viability. Three-tier pricing structure across OEM-certified premium, insurance-direct standard, and non-certified economy levels separates shops by certification grade and capital intensity. Cost-down pressure on standard-tier operations accelerates because national multi-shop operators leverage volume commitments to extract parts procurement discounts. Fleet operators exhibit lowest price sensitivity due to guaranteed turnaround requirements, while retail vehicle owners drive hardest bargaining through insurer referral shopping.
Supply Chain Analysis
Remanufactured and refurbished component flows remain underdeveloped in collision repair, creating reverse-logistics gaps that OEM parts sourcing concentration exploits for margin capture. Structural aluminum panels and ADAS sensor modules draw from Germany, China, and Japan as primary manufacturing hubs. Supply chain risk centers on single-source vulnerability for certified distribution channels controlling newer vehicle platform components. Distribution runs through manufacturer-authorized networks for structural parts, while aftermarket channels serve cosmetic and mechanical replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where EPA compliance costs and OEM certification requirements force weaker independent operators toward acquisition or exit. Capital intensity and regulatory barriers favor scaled networks with amortization capacity across location footprints.
For Market Incumbents: Deepen insurer-direct program density to lock in volume commitments that justify aluminum-specific welding environment investments. Acquire distressed single-location operators in Texas and Florida hail corridors to capture paintless dent repair margin premiums. Threat substitution from mobile repair operators demands integrated glass-body service lines that capture ADAS calibration workflows. For New Entrants and Emerging Players: REACH regulations in Germany open a window for EU-compliant refinishing material import specialists serving cross-border operators. Target last-mile delivery fleet maintenance contracts in California urban logistics hubs where procurement centralization creates vendor consolidation opportunities. Go-to-market angle: guaranteed cycle time penalties backed by mobile repair units for minimized vehicle downtime. For Investors and Strategic Acquirers: I-CAR aluminum certification enrollment spikes are the leading indicator that technician capacity constraints will accelerate shop network consolidation. Five-to-ten year viability favors multi-location operators with backward integration into parts distribution and captive technician training pipelines. Acquisition target archetype: regional three-to-five location operators with EPA-compliant infrastructure and pending OEM certification status.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Certification Investment | Gates access to structural repair procedures on aluminum-intensive vehicle platforms from Audi, BMW, and Mercedes-Benz. |
| Insurer-Direct Program Expansion | Secures volume commitments from national carriers that amortize 3D scanning equipment across location networks. |
| Glass-Body Integration | Captures ADAS calibration workflows following windshield replacement through combined service line capabilities. |
| Mobile Repair Capability Buildout | Serves last-mile delivery fleet operators seeking minimized downtime in dense urban United States corridors. |
| Technician Training Pipeline Development | Addresses I-CAR credential lags that outpace shop capacity expansion needs for aluminum repair. |
Methodological Framework
Document review covered EPA regulatory filings, NHTSA crashworthiness standards, and OEM certification program documentation, complemented by interviews with collision repair network executives, insurance carrier procurement directors, and fleet maintenance managers. Secondary validation drew from I-CAR training enrollment data, state-level insurance commission reports, and vehicle production registration databases. Bottom-up shop-level capacity modeling and top-down carrier spend analysis provided triangulation.
Segmentation outputs reflect repair type, technology adoption tier, end-user contract structure, and service delivery model across the projection horizon. CAGRs were derived from insurance claim volume trajectories, fleet vehicle penetration rates, and equipment investment cycles. Industry-specific inputs included aluminum platform production forecasts and ADAS-equipped vehicle parc growth assumptions.
The model assumes a particular technology adoption path; alternative pathways for 3D scanning displacement of traditional frame measurement would alter the outlook for equipment supplier demand. Forecasts reflect assumptions regarding EPA enforcement intensity and OEM certification program expansion. Practitioners should monitor I-CAR enrollment data and insurer direct-repair program contract awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Cab Services Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
GCC Car Wash Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Europe Car Wash Market
Automotive Services
Motorsports Market
Automotive Services
Car Wash System Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Global Street Sweeper Brushes Market