
 Global Prefilled Safety Device Market | 2026-2036
Global Prefilled Safety Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prefilled Safety Device Market Foresight
Glass-to-cyclic olefin polymer substitution in primary containment is broadening design flexibility for high-viscosity biologics. BD leverages captive resin compounding to control material consistency across its safety syringe lines. Gerresheimer AG anchors European supply through specialized glass-conversion capabilities for auto-injector cartridges. SCHOTT Pharma competes with polymer-ready tubing formats that reduce breakage risk in cold-chain distribution.
Prefilled safety devices integrate needlestick prevention mechanisms, fixed-dose containment, and user-activated shields into single-use parenteral delivery systems, typically manufactured through injection molding of medical-grade polymers and precision glass forming with siliconization for plunger lubricity. Their primary purpose is to eliminate sharps injuries while ensuring dose accuracy in self-administration and clinical settings. Auto-injectors command the deepest margin pools as complexity concentrates in spring-drive mechanisms and human-factors validation. Safety needles face commoditization pressure from multi-source polymer suppliers, while home care end users represent the fastest-growing demand channel as chronic disease management shifts outside hospital walls.
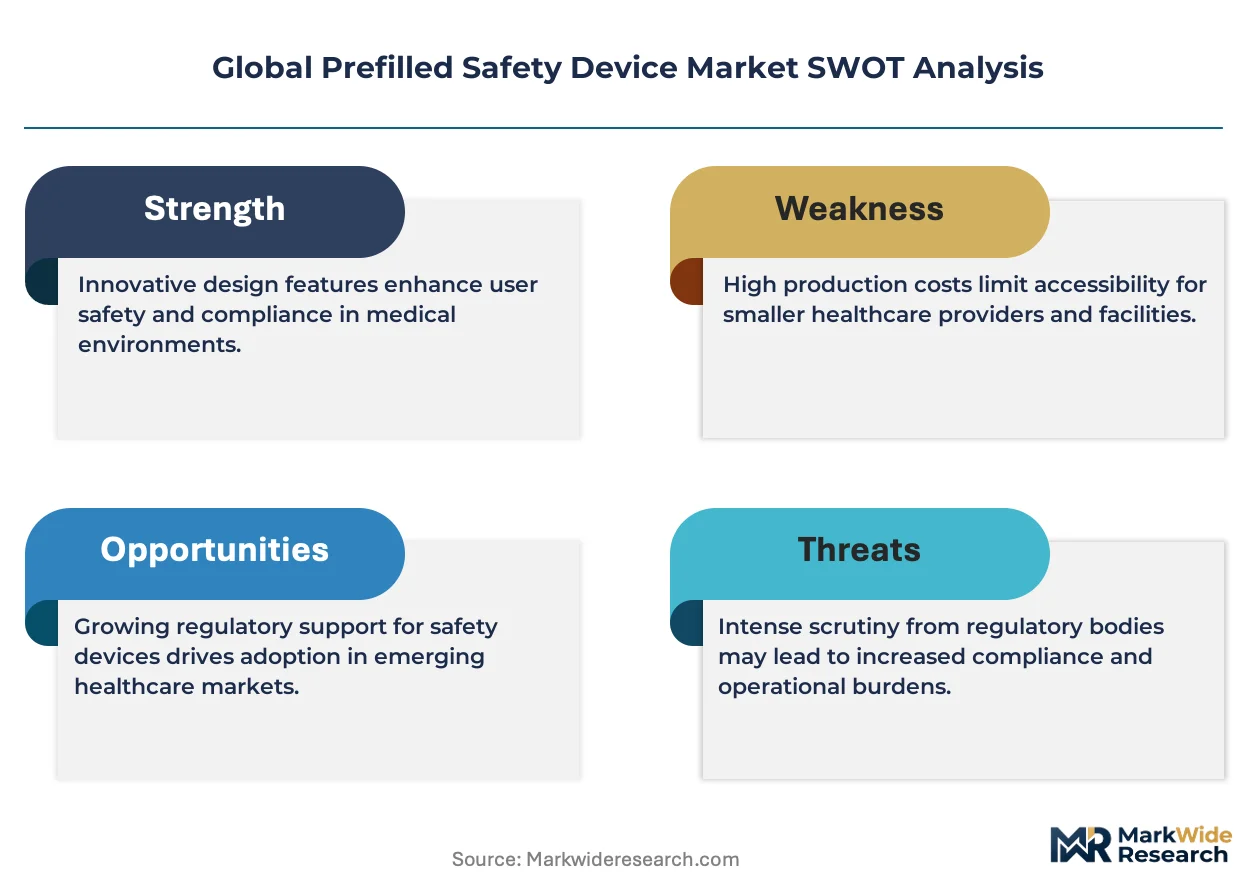
FDA 21 CFR 820 quality system regulations, OSHA Bloodborne Pathogens Standard, and EU MDR Class IIa device classifications collectively mandate retractable or shielded needle architectures for regulated markets. These frameworks create asymmetric compliance burdens that favor manufacturers with established 510(k) and CE mark filing histories. Stakeholders must monitor evolving EPA guidance on pharmaceutical plastic waste streams and WHO prequalification pathways for immunization devices in low-resource settings.
Market Dynamics
Biologics manufacturers are consolidating procurement around needlestick-prevention formats as OSHA Bloodborne Pathogens Standard enforcement intensifies across US hospital systems and EU MDR Class IIa device classifications harden technical barriers for non-compliant suppliers.
Growth Catalysts
- OSHA needlestick mandates:Retractable needle architectures are now compulsory in US clinical settings, forcing device upgrades across parenteral portfolios and eliminating legacy sharp designs from institutional procurement lists.
- Home care migration:Chronic disease management is shifting outside hospital walls, creating pull for user-activated shield mechanisms that protect patients during self-administration of high-viscosity biologics.
- Siliconization advances:Precision glass forming with optimized plunger lubricity is reducing break-force variability, enabling fixed-dose containment for temperature-sensitive monoclonal antibodies.
Market Restraints
- Medical-grade polymer cost volatility:Cyclic olefin resin prices fluctuate with petrochemical feedstock markets, compressing margins for injection-molded safety syringe producers.
- German glass-conversion concentration:European supply chains anchor heavily on specialized tubular glass capabilities, creating geographic vulnerability to energy cost shocks.
- Spring-drive mechanism complexity:Auto-injector assembly requires sub-millimeter tolerance control that few contract manufacturers can reliably achieve at scale.
Strategic Opportunities
- Japan's aging demographic:Self-injection protocols for rheumatoid arthritis and diabetes are expanding the addressable patient population beyond clinical settings.
- WHO prequalification pathways:Immunization device standards for low-resource settings are opening procurement channels for polymer-ready formats that withstand cold-chain distribution failures.
- EPA pharmaceutical waste guidance:Evolving plastic stream regulations are creating first-mover advantage for manufacturers with validated recycling partnerships.
Industry Challenges
- Human-factors validation timelines:FDA 510(k) submissions for combination products require extensive usability testing that extends certification cycles.
- Multi-source polymer qualification:Switching resin suppliers demands re-validation of material consistency across safety syringe lines.
- Legacy sharp disposal integration:Hospital waste management infrastructure was built around conventional needle destruction, creating friction for shielded-device adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prefilled Safety Device Market |
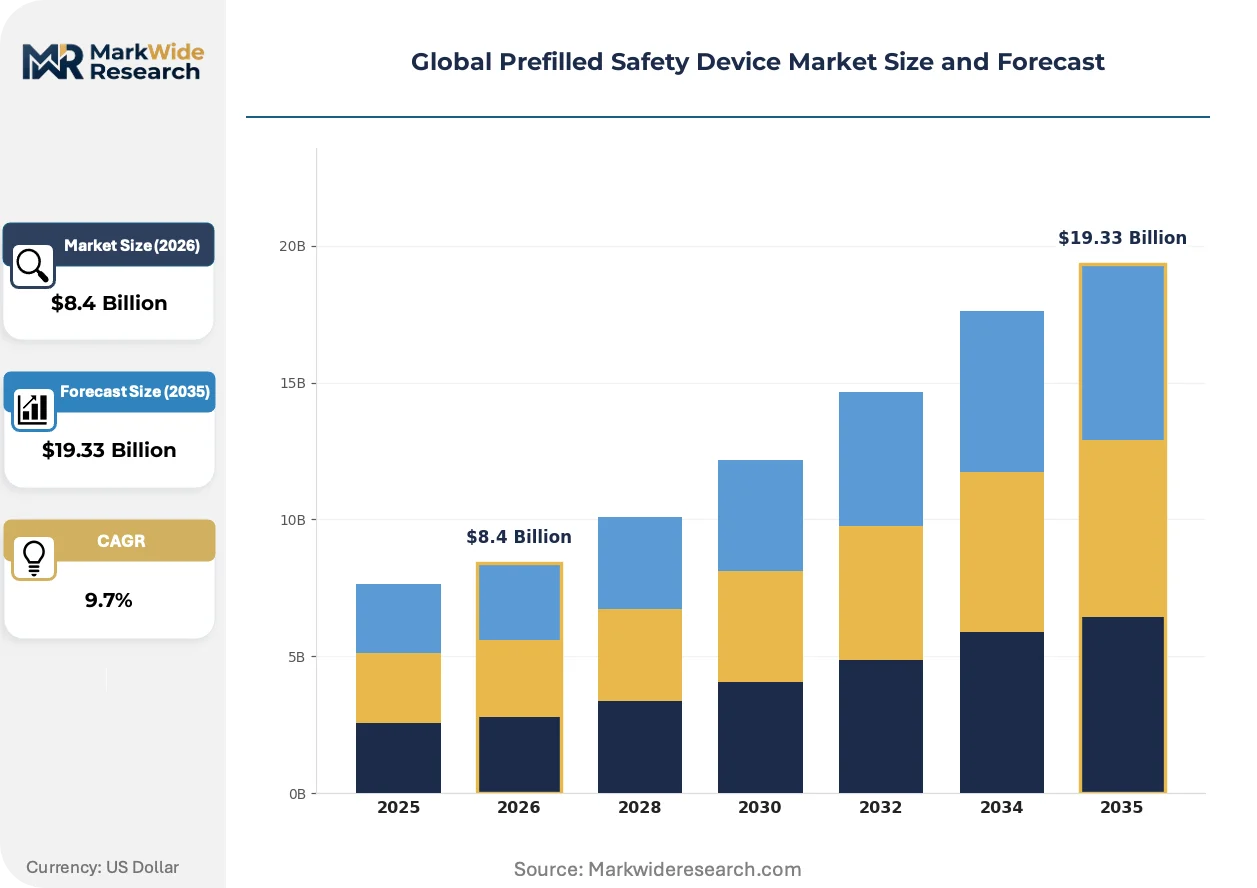
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Auto-Injectors, Safety Needles, Infusion Devices Application: Immunization, Oncology, Diabetes Management, Pain Management End User: Hospitals, Ambulatory Surgical Centers, Home Care, Diagnostic Laboratories Distribution Channel: Pharmacies, Online Retailers, Medical Supply Distributors, Direct Sales |
| Companies Covered | BD, Gerresheimer AG, SCHOTT Pharma, West Pharmaceutical Services, Retractable Technologies, B. Braun, Nipro Corporation, Stevanato Group, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prefilled Safety Device Market Shifts & Advancements
Device architectures are fragmenting into specialized formats as biologics viscosity ranges expand and administration settings diversify from acute care to patient homes.
Modular spring-drive platforms are modularizing auto-injector development by separating the power module from the drug containment cartridge. Large-molecule developers are adopting these configurable systems to accelerate combination product timelines. This modularity is compressing the traditional 18-month human-factors validation cycle into parallel track activities.
EU MDR technical documentation requirements are forcing device manufacturers to rebuild quality management systems around clinical evidence and post-market surveillance. The regulation's Unique Device Identification mandates are driving serialization investments across polymer supply chains. German and French notified bodies are experiencing backlog delays that favor manufacturers with established CE mark filing histories.
Hospital procurement committees are consolidating supplier relationships around full-portfolio safety device vendors rather than sourcing needles, syringes, and sharps containers separately. Group purchasing organizations are unbundling after-sales training from capital equipment contracts. This concentration is most visible in US integrated delivery networks where standardization reduces nursing education burden.
Global Prefilled Safety Device Market Segmentation
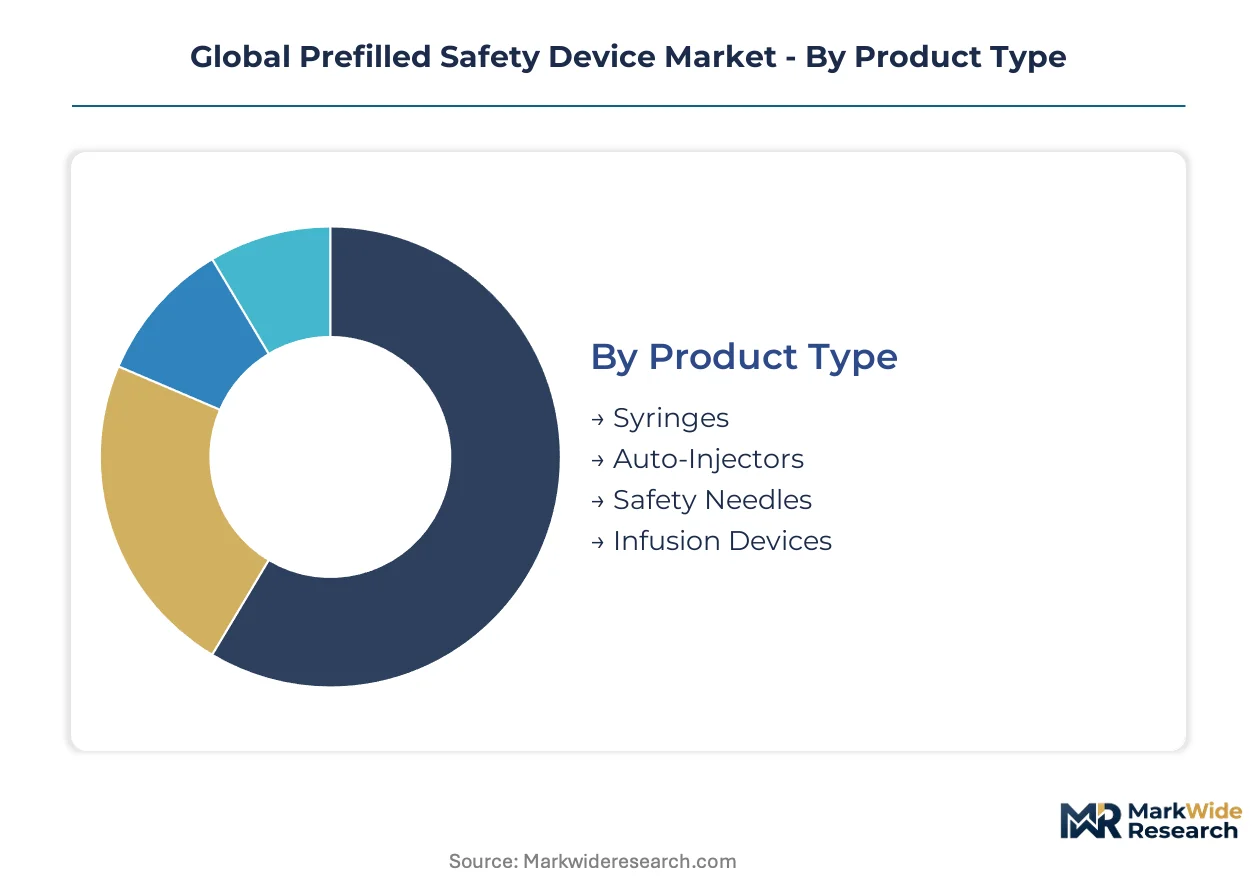
Segmentation in prefilled safety devices reveals how capital deployment, regulatory exposure, and patient setting intersect to determine margin structure. Manufacturers must align product architectures with specific compliance burdens and administration workflows rather than pursuing universal platform strategies.
Product Type:
Auto-injectors demand the heaviest upfront tooling investment due to spring-drive mechanism complexity and sub-millimeter tolerance requirements. Syringes and safety needles require lower capital intensity but face sharper polymer cost volatility.
- Syringes:Glass-barrel and polymer formats with integrated needlestick prevention dominate institutional procurement. US hospital systems under OSHA enforcement mandate retractable or shielded architectures, eliminating legacy sharp designs from group purchasing organization lists.
- Auto-Injectors:Spring-drive platforms with fixed-dose containment command premium positioning through human-factors validation depth. Germany and Japan drive specification intensity as biopharma clusters concentrate combination product development in these markets.
- Safety Needles:Polymer-shielded formats face commoditization pressure from multi-source resin suppliers.
- Infusion Devices:Extended-delivery formats for high-viscosity biologics require specialized flow-control engineering.
Most installed capacity flows through Syringes. Expansion is steepest in Auto-Injectors.
Application:
Diabetes Management and Oncology concentrate the highest per-patient device consumption due to chronic administration protocols. Immunization and Pain Management present diverging volume-margin profiles shaped by public procurement versus specialty pharmacy channels.
- Diabetes Management:Self-injection protocols for insulin and GLP-1 analogs generate recurring device demand. Japan's aging demographic and expanding home care protocols are accelerating patient-controlled administration outside clinical settings.
- Oncology:Temperature-sensitive monoclonal antibodies require siliconized glass containment with break-force consistency. EU MDR Class IIa device classifications harden technical barriers for suppliers serving European infusion centers.
- Immunization:WHO prequalification pathways are opening procurement channels for polymer-ready formats in low-resource distribution environments.
- Pain Management:Post-surgical and chronic pain protocols favor single-use safety formats in ambulatory settings.
Diabetes Management captures the largest installed base. Oncology is climbing the fastest as biologics pipelines deepen.
End User:
Home Care and Hospitals represent opposing poles of the user-sophistication spectrum, driving divergent human-factors requirements. Ambulatory Surgical Centers and Diagnostic Laboratories occupy intermediate positions with distinct throughput priorities.
- Home Care:Patient-activated shield mechanisms protect untrained users during self-administration of high-viscosity biologics. FDA 510(k) submissions for these combination products require extensive usability testing that extends certification cycles.
- Hospitals:Integrated delivery networks consolidate procurement around full-portfolio vendors to reduce nursing education burden. OSHA Bloodborne Pathogens Standard enforcement has made retractable needle architectures compulsory in US acute care.
- Ambulatory Surgical Centers:Same-day discharge protocols favor compact safety formats with minimal disposal friction.
- Diagnostic Laboratories:High-throughput blood collection drives demand for passive safety mechanisms.
Hospitals retain the deepest installed base. Home Care is gaining share fastest as chronic disease management migrates outside institutional walls.
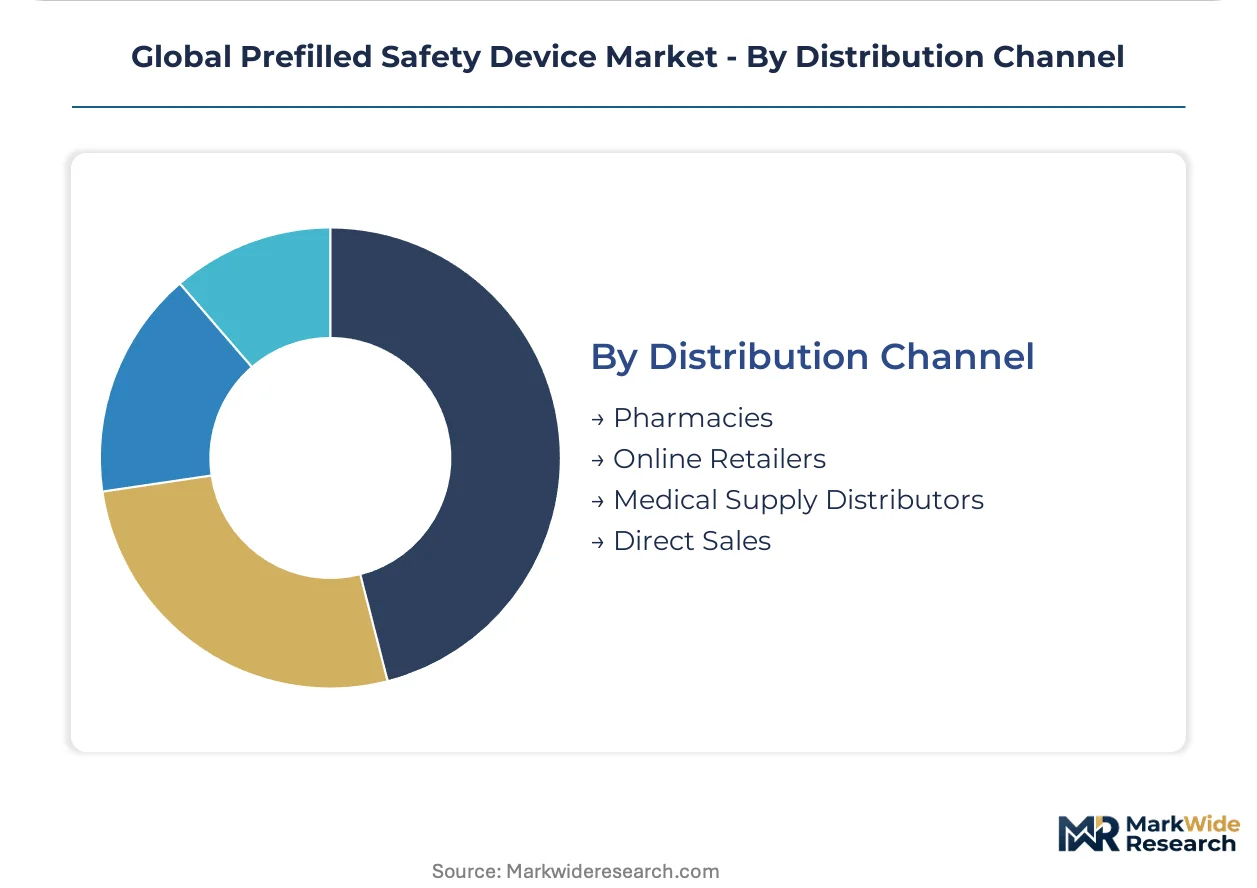
Distribution Channel:
Direct Sales and Medical Supply Distributors concentrate the highest-value transactions, while Online Retailers and Pharmacies serve fragmented patient-pay segments with distinct logistics requirements.
- Direct Sales:Manufacturer-to-biopharma relationships dominate auto-injector and combination product procurement. These partnerships require validated cold-chain documentation and serialized device traceability under EU MDR Unique Device Identification mandates.
- Medical Supply Distributors:Group purchasing organization consolidation favors distributors with comprehensive safety device portfolios. US hospital procurement committees increasingly unbundle after-sales training from capital equipment contracts.
- Pharmacies:Retail dispensing of prefilled safety formats concentrates in diabetes and immunization segments.
- Online Retailers:Direct-to-patient channels are expanding for home care self-injection devices with simplified activation.
Direct Sales channels carry the most established volume. Medical Supply Distributors are expanding most quickly as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharma production clusters in New Jersey, Massachusetts, and the Research Triangle anchor North American device procurement. European glass-conversion capabilities concentrate in southern Germany and eastern France. Japanese precision manufacturing in Kansai and Kanto regions shapes auto-injector specification intensity.
United States
OSHA Bloodborne Pathogens Standard enforcement has made retractable needle architectures compulsory across US hospital systems. FDA 510(k) quality system regulations create asymmetric compliance burdens favoring established filers. The Research Triangle and Greater Boston clusters drive combination product development for temperature-sensitive monoclonal antibodies.
Germany
EU MDR Class IIa device classifications harden technical barriers for non-compliant suppliers serving European infusion centers. ANSM and BfArM oversight concentrates notified body activity in Berlin-Brandenburg and Munich. Gerresheimer AG anchors specialized glass-conversion capabilities for auto-injector cartridges in the Rhine-Main region.
Japan
Self-injection protocols for rheumatoid arthritis and diabetes expand the addressable patient population beyond clinical settings. PMDA combination product regulations demand extensive human-factors validation for home care devices. Osaka-based manufacturing clusters specialize in spring-drive mechanism assembly with sub-millimeter tolerance control.
India
CDSCO medical device rules are harmonizing with EU MDR frameworks for polymer-ready safety formats. WHO prequalification pathways for immunization devices open procurement channels for low-resource distribution. Ahmedabad and Hyderabad clusters specialize in injection-molded safety syringe production for export markets.
China
NMPA medical device registration reforms are accelerating local approval timelines for needlestick-prevention formats. Domestic biologics manufacturers are consolidating procurement around shielded-device vendors. Suzhou and Shanghai biopharma parks drive specification intensity for high-viscosity biologic delivery systems.
Global Prefilled Safety Device Market Competitive Landscape
Global majors compete with regional champions across regulatory filing capabilities and material science specialization. The vendor base separates into three tiers: integrated device-drug combination specialists, captive glass-polymer converters, and regional safety-needle fabricators. Dominant competitive moves include M&A to secure spring-drive engineering talent and capacity expansion in polymer-ready tubing formats.
Within the integrated combination product tier, BD and West Pharmaceutical Services exemplify full-portfolio positioning across safety syringes and auto-injector platforms. SCHOTT Pharma anchors the glass-conversion specialist archetype with polymer-ready tubing investments. These three entities represent divergent strategic postures: captive resin compounding, precision siliconization, and cold-chain distribution risk mitigation.
| Leading Market Players |
|---|
| BD |
| Gerresheimer AG |
| SCHOTT Pharma |
| West Pharmaceutical Services |
| Retractable Technologies |
| B. Braun |
| Nipro Corporation |
| Stevanato Group |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
US hospital procurement consolidation around OSHA-compliant retractable needle formats is forcing polymer resin suppliers to qualify alternative feedstock sources, compressing margins for injection-molded safety syringe producers unable to pass through cyclic olefin cost volatility.
Pricing Analysis
Medical-grade polymer cost pass-through dominates pricing formation as cyclic olefin resin prices fluctuate with petrochemical feedstock markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated combination products from commodity safety needles and basic shielded syringes. Cost compression in the standard tier is intensifying because multi-source resin qualification demands re-validation of material consistency. Group purchasing organizations exhibit the highest price sensitivity, while biopharma direct procurement for auto-injector platforms tolerates premium positioning.
Supply Chain Analysis
Domestic-content mandates in China's NMPA registration pathway and India's CDSCO medical device rules are reshaping sourcing patterns for polymer-ready tubing formats. Manufacturing gravity centers on Germany for specialized glass-conversion, China for injection-molded components, and Japan for spring-drive mechanism assembly. The supply chain draws from cyclic olefin resins, siliconized glass tubing, and precision-engineered springs as core inputs. Single-source vulnerability concentrates in German glass-conversion capabilities for auto-injector cartridges. Distribution runs through direct sales to biopharma manufacturers and medical supply distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA Bloodborne Pathogens Standard enforcement and EU MDR Class IIa device classifications create irreversible demand for needlestick-prevention architectures.
For Market Incumbents: Hedge against polymer cost volatility through captive resin compounding or backward integration into cyclic olefin supply. Expand siliconized glass capacity in the Rhine-Main region to defend against SCHOTT Pharma's polymer-ready tubing investments. Strengthen 510(k) filing histories to exploit FDA human-factors validation backlogs that disadvantage emerging competitors.
For New Entrants and Emerging Players: Capture white-space in WHO prequalification pathways for immunization devices serving low-resource distribution environments. Target India's CDSCO-harmonized polymer-ready safety syringe production for export markets. Differentiate through validated cold-chain distribution partnerships rather than competing on spring-drive mechanism complexity.
For Investors and Strategic Acquirers: Asymmetric upside sits with glass-conversion specialists possessing EU MDR technical documentation capabilities and established CE mark filing histories. Long-term viability hinges on serialization investments under Unique Device Identification mandates. Watch German and French notified body backlog delays as an inflection indicator favoring incumbent manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa device classifications harden technical barriers for non-compliant suppliers. |
| Backward Integration into Resin Compounding | BD's captive supply of cyclic olefin polymers controls material consistency across safety syringe lines. |
| Hospital System Partnership | Integrated delivery networks consolidate procurement around full-portfolio vendors to reduce nursing education burden. |
| Software Companion Development | Modular spring-drive platforms compress human-factors validation cycles through parallel track activities. |
| Reimbursement Strategy | Home care migration for chronic disease management expands patient-pay segments outside institutional procurement. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs directors combine with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and OSHA enforcement records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of installed base expansion and replacement cycles informs the projection framework across the analysis window. Segmentation dimensions include product type, application, end user, and distribution channel, with additional modeling of regional regulatory cluster effects. CAGRs derive from regression analysis of patent filings, capacity announcements, and procurement contract visibility. Forecast inputs incorporate biologics pipeline depth and human-factors validation timeline compression.
Regulatory enforcement intensity shifts, polymer feedstock price dislocations, and notified body capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about compliance timeline adherence and substitution elasticity between glass and polymer containment formats. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Instrumentation Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market