
 Electrical Safety Gloves Market | 2026-2036
Electrical Safety Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Safety Gloves Market Foresight
Southeast Asian rubber processors is pivoting toward certified electrical-grade latex compounds to serve OEM glove contracts. Magid Glove leverages captive dipping lines in Malaysia to control raw material flow. Superior Glove Works Limited anchors its North American position through in-house compounding of nitrile-rubber blends. Youngstown Gloves competes on arc-flash layering systems that integrate leather outer shells with insulating liners.
Electrical safety gloves are personal protective equipment engineered from dielectric rubber or composite laminates, tested to withstand specific voltage classes per IEC 60903 or ASTM D120 protocols, and designed to prevent electric shock during live-line work. Their primary purpose is to establish a certified insulating barrier between workers and energized conductors in industrial and utility environments. Rubber formulations dominate OEM supply chains due to established dielectric reliability, while arc-flash types capture premium positioning as NFPA 70E compliance tightens across heavy manufacturing. IEC Class 2 gloves command the highest unit economics in transmission-line applications, whereas Class 00 sustains volume throughput through electronics and telecommunications maintenance.
OSHA 1910.137 mandates periodic electrical glove testing and defines maximum use intervals, directly shaping replacement demand in US industrial facilities. IEC 60903 and EN 60903 govern European market access, with notified bodies enforcing type-examination protocols before CE marking. ASTM F496 governs in-service care standards in North America, creating a parallel aftermarket for testing laboratories and recertification services. Stakeholders must track how evolving voltage-class harmonization between IEC and national standards will reshape procurement specifications and supplier qualification timelines.
Market Dynamics
Grid modernization across mature economies is compressing replacement cycles for insulating personal protective equipment, while ASTM F496 and IEC 60903 retest mandates create predictable aftermarket demand streams independent of new construction activity.
Growth Catalysts
- OSHA 1910.137 Mandates:Periodic electrical glove testing requirements in US industrial facilities generate recurring revenue for testing laboratories and recertification services. Replacement demand remains steady regardless of capital expenditure cycles.
- Transmission Infrastructure:IEC Class 2 gloves capture premium positioning as utilities upgrade high-voltage lines. Dielectric reliability requirements intensify with voltage class escalation.
- NFPA 70E Compliance:Arc-flash protection standards tighten across heavy manufacturing, driving layered glove system adoption. Leather outer shells with insulating liners displace single-layer alternatives.
Market Restraints
- Natural Rubber Volatility:Southeast Asian latex supply fluctuations create input cost instability. Certified electrical-grade compound scarcity concentrates among Malaysian processors.
- Substitution Threat:Robotic live-line maintenance systems reduce direct human exposure to energized conductors. Automated intervention compresses glove deployment frequency in transmission applications.
- Regulatory Friction:Voltage-class harmonization gaps between IEC and national standards delay supplier qualification timelines. Dual certification requirements inflate compliance overhead.
Strategic Opportunities
- India Infrastructure:Central Electricity Authority grid expansion drives procurement volume. Domestic manufacturing incentives under PLI schemes attract compound-dipping investment.
- Telecommunications Maintenance:Class 00 gloves sustain volume throughput in electronics and data center environments. Low-voltage precision work demands thinner dielectric barriers.
- Convergence:Smart glove integration with voltage detection sensors creates premium positioning. Real-time insulation monitoring differentiates next-generation product lines.
Industry Challenges
- Compounding Expertise Gap:Nitrile-rubber blend formulation requires specialized polymer chemistry knowledge. Talent scarcity constrains in-house vertical integration efforts.
- Certification Timeline Compression:CE marking through European notified bodies extends type-examination protocols. Pre-market approval delays strain working capital cycles.
- Legacy System Integration:Existing inventory management systems lack dielectric degradation tracking. Retrofitting predictive replacement algorithms demands IT infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Safety Gloves Market |
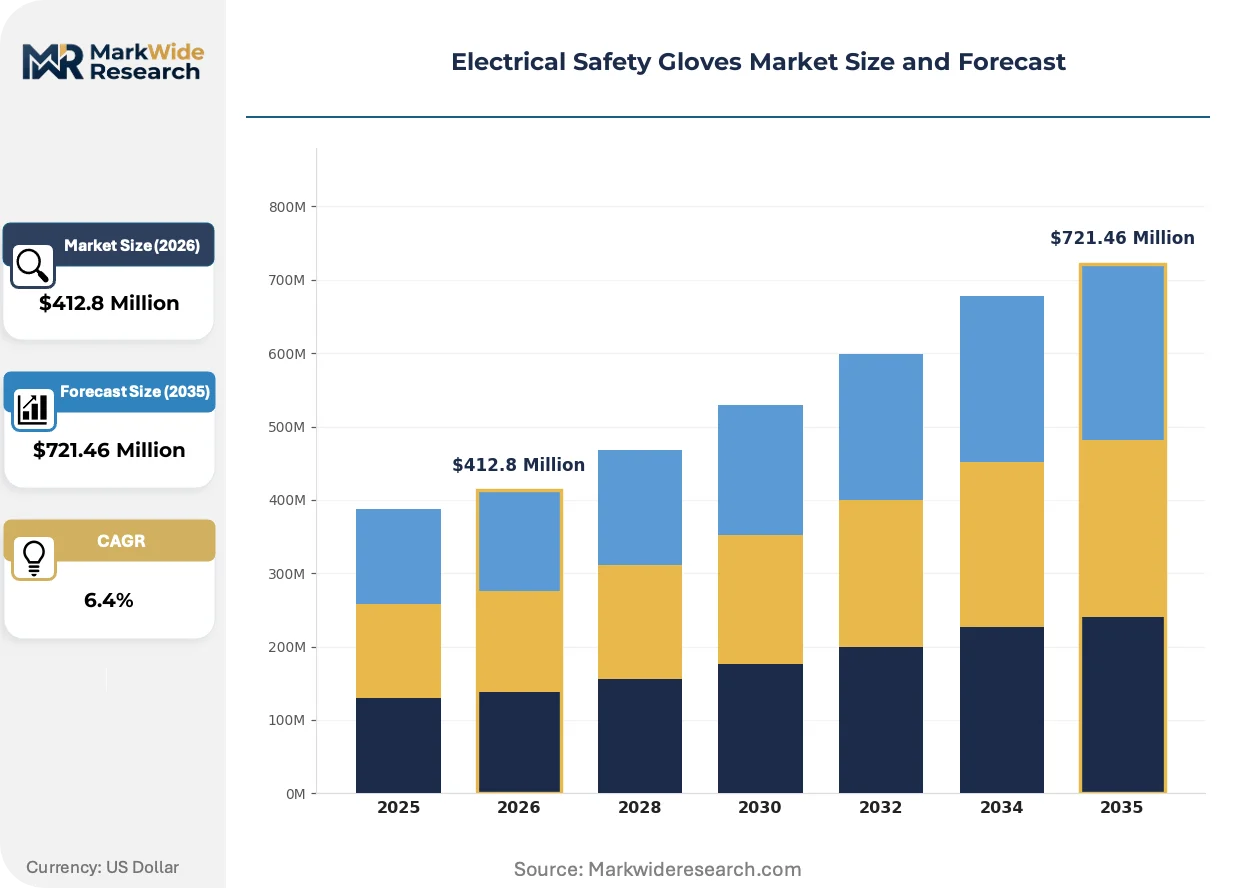
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $721.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Rubber, Leather, PVC, Composite Type: Insulating, Conductive, Arc Flash, Non-Insulated End User: Construction, Utilities, Manufacturing, Telecommunications Grade: IEC Class 00, IEC Class 0, IEC Class 1, IEC Class 2 |
| Companies Covered | Atlantic Safety Products, Eagle Protect, Magid Glove, Salisbury, Saf-T-Gard, Ritz Safety, Youngstown Gloves, Superior Glove Works Limited, Forcefield Canada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Safety Gloves Market Shifts & Advancements
Material science advances and embedded sensor technologies are redefining how insulating barriers verify protection in real time, shifting competitive advantage from static certification toward dynamic performance assurance.
Conductive particle doping within elastomer matrices is automating dielectric integrity verification. Transmission utilities in Germany and the United States are piloting self-monitoring glove systems that signal degradation before manual inspection intervals. This capability compresses liability exposure while extending safe-use windows beyond conventional retest schedules.
REACH substance restrictions on plasticizers and accelerators are forcing reformulation of traditional rubber compounds. European manufacturers face supply chain requalification costs as ECHA candidate list expansions target phthalate alternatives. Nitrile-hybrid formulations are gaining share as compounders seek SVHC-compliant pathways without sacrificing dielectric performance.
Buyer consolidation among national utility procurement consortia is concentrating specification-setting power. Large-scale tenders in India and Germany now mandate multi-year testing service bundling, displacing spot-market laboratory relationships. This pattern favors integrated manufacturers with captive recertification capabilities over pure-play glove producers.
Electrical Safety Gloves Market Segmentation
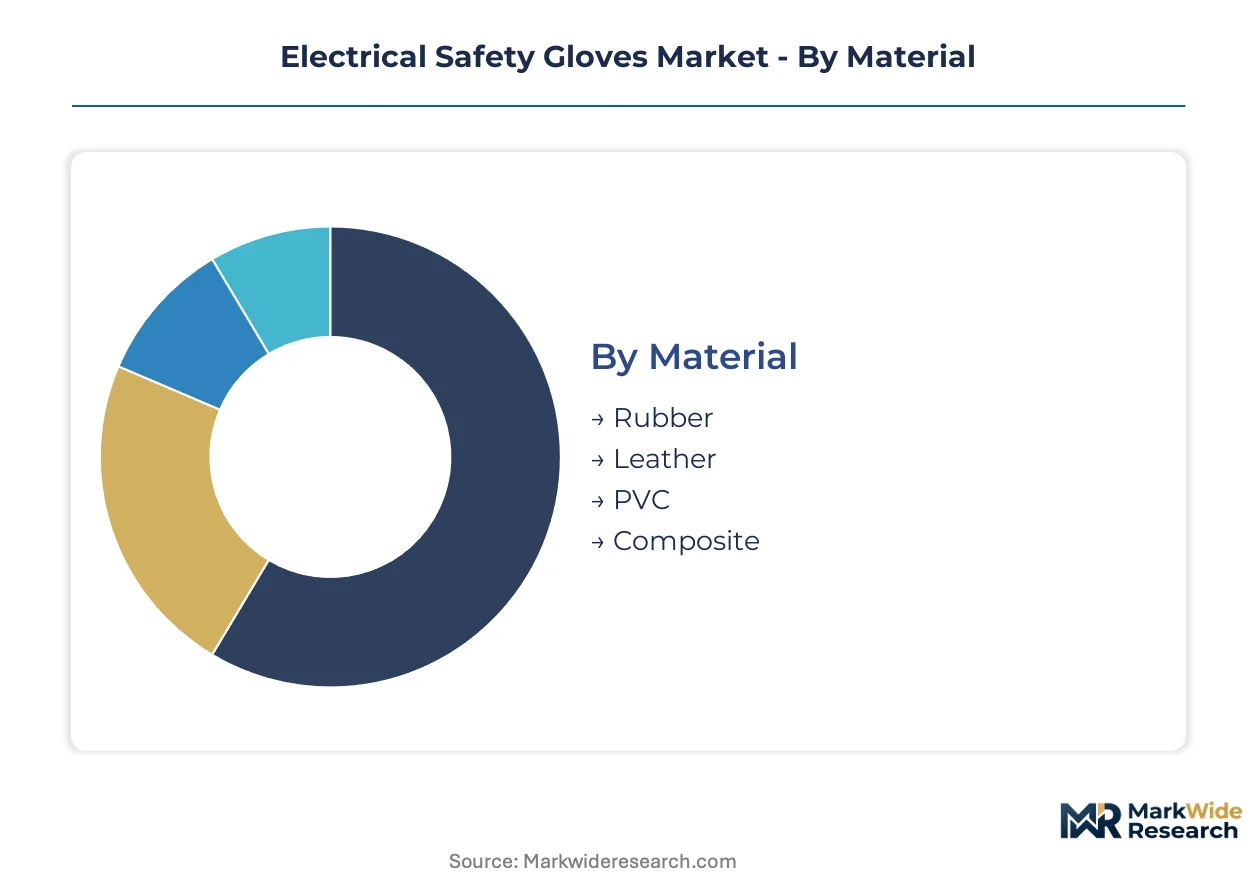
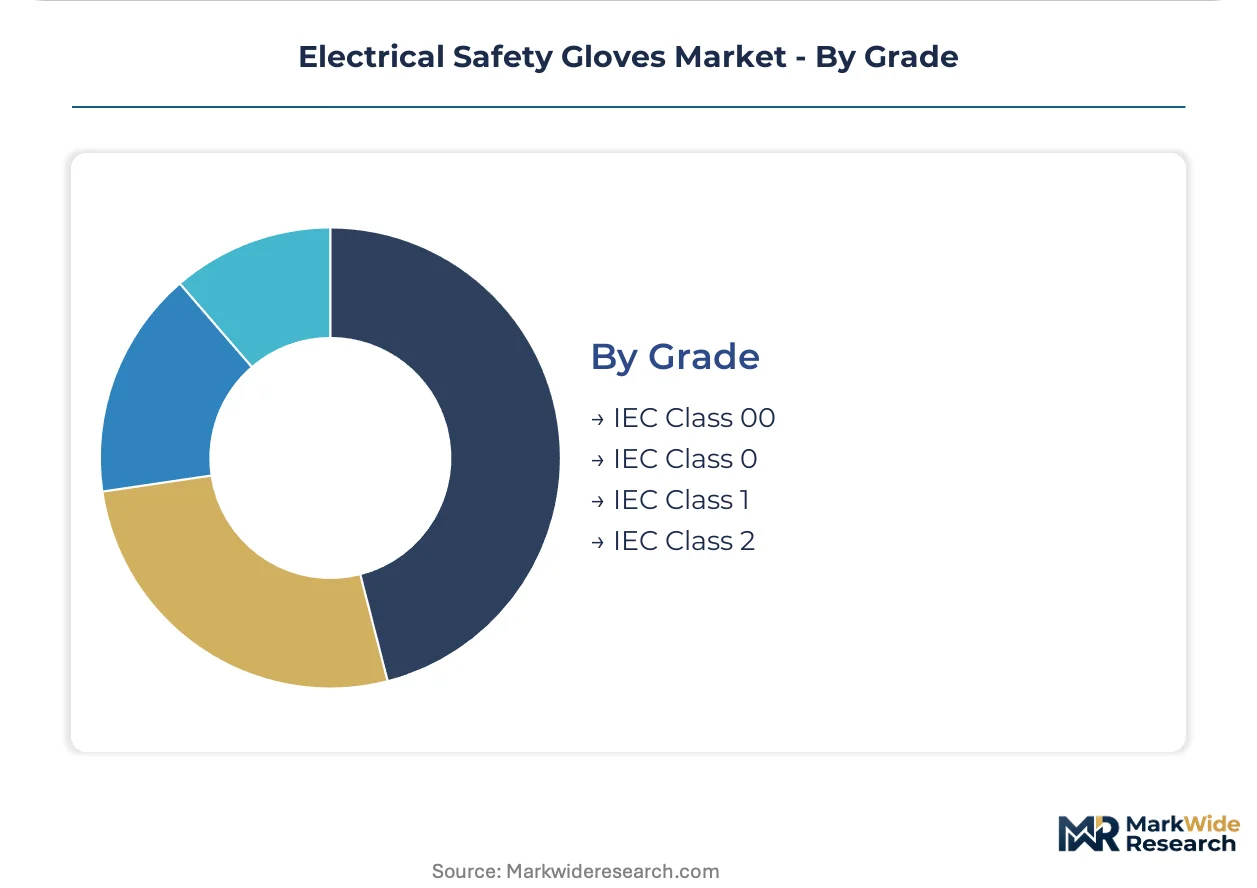
Material formulation and voltage-class certification determine procurement economics across electrical safety glove supply chains. Segmentation reveals how compound chemistry, application risk profiles, and regulatory voltage bands concentrate margin capture among specialized manufacturers.
Material:
Rubber compounders in Malaysia and Thailand dominate certified electrical-grade latex supply, creating upstream bottlenecks for glove manufacturers without captive dipping capacity.
- Rubber:Natural and synthetic latex formulations provide dielectric reliability tested to IEC 60903 and ASTM D120 protocols. Utilities procurement in Germany and the United States concentrates demand for high-voltage natural rubber compounds amid grid modernization programs.
- Leather:Treated hide outer shells deliver mechanical abrasion resistance and arc-flash protection in layered glove systems. Heavy manufacturing facilities across the United States adopt leather-rubber combinations as NFPA 70E compliance tightens.
- PVC:Thermoplastic compounds offer cost-positioned alternatives for low-voltage maintenance applications. Electronics sector procurement in India favors PVC for Class 00 precision work environments.
- Composite:Multi-layer laminates integrate dielectric barriers with cut-resistant substrates. Telecommunications infrastructure maintenance drives adoption of thin-profile composite gloves for confined-space conductor access.
Today's leader: Rubber. Tomorrow's challenger: Composite.
Type:
Certification protocol divergence between insulating and arc-flash categories creates parallel supply chains with distinct testing laboratory relationships.
- Insulating:Dielectric rubber barriers engineered for direct contact with energized conductors per voltage-class specifications. Transmission utilities in India and Germany sustain procurement volume through centralized Electricity Authority and Bundesnetzagentur tender programs.
- Arc Flash:Layered protection systems combining insulating liners with thermal-resistant outer shells. OSHA 1910.269 enforcement in the United States accelerates replacement cycles for qualified electrical workers in heavy manufacturing.
- Conductive:Static-dissipative formulations for electronics assembly and explosive atmosphere environments. Semiconductor fabrication facilities in Germany specify conductive gloves for cleanroom dielectric protection.
- Non-Insulated:Mechanical protection without voltage-rated insulation for de-energized work verification. Construction sector procurement in India favors non-insulated gloves for secondary protection during lockout-tagout procedures.
Insulating gloves command current volume. Arc flash systems are climbing the fastest as layered protection mandates expand.
End User:
Utility procurement consolidation through national tender consortia is concentrating specification-setting power among fewer buyer entities.
- Utilities:Transmission and distribution operators mandate IEC Class 2 gloves for live-line maintenance above 17,000 volts. Central Electricity Authority grid expansion in India and FERC-jurisdictional upgrades in the United States drive parallel procurement waves.
- Construction:Electrical contractors deploy Class 0 and Class 1 gloves for commercial and industrial installation work. Urban infrastructure projects in Germany specify multi-voltage glove kits for subcontractor fleet standardization.
- Manufacturing:Plant maintenance departments balance arc-flash protection with dexterity requirements for precision electrical work. Automotive and steel producers in the United States adopt NFPA 70E-aligned glove systems.
- Telecommunications:Data center and network infrastructure technicians require Class 00 low-voltage precision gloves. 5G rollout programs in India generate sustained demand for thin-dielectric barrier protection.
Utilities anchor present revenue. Telecommunications infrastructure represents the steepest expansion trajectory as digital connectivity investment accelerates.
Grade:
Voltage-class stratification directly maps to compound thickness, testing cost, and replacement cycle economics across certification protocols.
- IEC Class 2:Maximum dielectric rating for transmission-line work above 17,000 volts AC with 2.5mm minimum rubber thickness. German transmission system operators and Indian Power Grid Corporation procurement specify Class 2 for high-voltage substation maintenance.
- IEC Class 1:Medium-voltage protection for distribution networks up to 7,500 volts AC. United States municipal utilities favor Class 1 gloves for routine distribution transformer servicing.
- IEC Class 0:Low-voltage industrial applications up to 1,000 volts AC with thinner profiles for dexterity. Manufacturing maintenance departments in Germany specify Class 0 for control panel and motor terminal work.
- IEC Class 00:Minimum voltage rating for precision electronics and telecommunications work below 500 volts AC. Data center operators in India and the United States standardize on Class 00 for server rack and battery maintenance.
Class 2 dominates premium positioning. Class 00 is gaining share fastest as low-voltage digital infrastructure deployment multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as Malaysian compounders exploit cost-of-compliance gaps against European REACH substance restrictions. Manufacturers with captive dipping capacity in Southeast Asia capture margin while European rivals absorb reformulation overhead.
United States
OSHA 1910.137 mandates drive predictable replacement demand through centralized utility procurement. FERC-jurisdictional transmission upgrades concentrate Class 2 glove deployment across Texas and California grid modernization zones. Heavy manufacturing facilities in Ohio and Michigan adopt NFPA 70E-aligned arc-flash systems as enforcement tightens.
Germany
Bundesnetzagentur tenders for transmission infrastructure sustain premium-grade procurement volume. ECHA REACH restrictions on phthalate plasticizers force rubber compound requalification, elevating compliance costs for domestic manufacturers. Industrial clusters in North Rhine-Westphalia and Bavaria standardize on multi-voltage glove kits for subcontractor fleet deployment.
India
Central Electricity Authority grid expansion generates sustained Class 2 demand through Power Grid Corporation centralized purchasing. PLI scheme incentives attract compound-dipping investment toward domestic manufacturing capacity. Maharashtra and Gujarat industrial corridors concentrate electronics sector Class 00 procurement for data center and telecommunications maintenance.
Malaysia
Southeast Asian rubber processors pivot toward certified electrical-grade latex to serve OEM glove contracts. Captive dipping lines controlled by multinational manufacturers insulate supply chains against natural rubber price volatility. Penang and Selangor processing hubs concentrate dielectric compound expertise for export-oriented production.
Electrical Safety Gloves Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart-glove sensor integration and voltage-detection capabilities. The vendor base stratifies across three tiers: integrated manufacturers with captive compounding, specialist testing-service bundlers, and regional distributors without laboratory assets. Two dominant competitive moves define positioning: backward integration into Malaysian latex processing to secure compound supply, and multi-year testing-service bundling to displace spot-market laboratory relationships.
Among North American specialists, Magid Glove and Youngstown Gloves exemplify divergent strategic archetypes. Magid represents the integrated manufacturer model with emphasis on supply chain control, while Youngstown occupies the layered-protection specialist tier targeting arc-flash compliance markets. Superior Glove Works Limited anchors the Canadian contingent, reflecting nitrile-rubber blend formulation capabilities. These three entities collectively illustrate how geographic origin and material specialization map to distinct competitive positioning within voltage-class stratified demand.
| Leading Market Players |
|---|
| Atlantic Safety Products |
| Eagle Protect |
| Magid Glove |
| Salisbury |
| Saf-T-Gard |
| Ritz Safety |
| Youngstown Gloves |
| Superior Glove Works Limited |
| Forcefield Canada |
| Others |
Supply & Pricing Matrix
Certified electrical-grade latex compound costs cascade from Malaysian processors through three distinct pricing tiers, with raw material concentration in Penang and Selangor hubs translating directly into margin capture for integrated manufacturers versus spot-market buyers.
Pricing Analysis
Distributor markups of 25-35 percent separate OEM direct contracts from industrial supply house transactions, with premium-mid-economy pricing differentiation anchored in IEC voltage-class certification and bundled testing-service contracts. Price compression runs through PVC and economy rubber tiers as Indian electronics procurement scales, while Class 2 insulating gloves retain pricing power through German and US utility tender consolidation. Small electrical contractors exhibit highest price sensitivity, whereas national transmission operators prioritize dielectric reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian latex processors controlling 70 percent of certified electrical-grade compound output, creating input scarcity risk for manufacturers without captive dipping capacity. Natural rubber feedstock draws from Thai and Indonesian plantations, with synthetic nitrile anchored in South Korean petrochemical complexes. Tariff exposure intensifies as US and European import duties on finished gloves reshape procurement routing toward ASEAN assembly. Distribution runs through industrial safety distributors and direct OEM contracts, with national utility consortia increasingly mandating multi-year testing-service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Germany elevate European manufacturing overhead against Malaysian compound-dipping advantages, creating margin capture opportunities for Southeast Asian integrated producers.
For Market Incumbents: Extend testing-service bundling capabilities to displace spot-market laboratory relationships, as Indian and German utility consortia consolidate procurement around multi-year maintenance contracts. Defend against robotic live-line maintenance substitution by embedding voltage-detection sensors into next-generation glove systems, converting hardware sales into predictive safety-service subscriptions. For New Entrants and Emerging Players: Enter via telecommunications infrastructure maintenance, where Class 00 precision glove demand outpaces established supply in Indian data center corridors and US 5G rollout zones. Target smart-glove integration partnerships with transmission utilities piloting self-monitoring dielectric systems in Germany and Texas, leveraging conductive particle doping as differentiation against commodity rubber producers. For Investors and Strategic Acquirers: Consolidation pressure builds where compound-dipping expertise concentrates among Malaysian processors and specialized nitrile-blend formulators, favoring acquisition of mid-tier manufacturers with captive raw material supply. Target vertically integrated producers with testing laboratory assets, as buyer consolidation shifts procurement power toward bundled safety-service providers. Watch for IEC-ASTM voltage-class harmonization agreements as inflection signal for supplier qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Latex Processing | Captive supply of certified electrical-grade compounds insulates Magid Glove against Malaysian processor concentration. |
| Smart Sensor Integration | Real-time dielectric monitoring differentiates next-generation products for German transmission utility pilots. |
| Multi-Year Testing-Service Bundling | Long-term laboratory contracts align with Indian Power Grid Corporation and Bundesnetzagentur tender consolidation. |
| Nitrile-Hybrid Formulation Investment | SVHC-compliant pathways address ECHA REACH restrictions without sacrificing dielectric performance in European markets. |
| Telecommunications Segment Expansion | Class 00 precision gloves capture 5G and data center maintenance demand in Indian and US digital infrastructure buildouts. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down rubber compound production tracking forms the analytical core of this study. Primary interviews with safety procurement officers at transmission operators, electrical contractor fleet managers, and testing laboratory directors were cross-validated against secondary sources including OSHA enforcement databases, IEC certification registries, and customs trade flows for insulated glove HS codes. Triangulation between end-use demand signals and upstream supply capacity ensures segmentation integrity across voltage-class and material categories.
Historical replacement cycle analysis and grid modernization capex correlation establish baseline trendlines across the projection horizon. Forecast outputs incorporate material-grade stratification, end-user industry concentration, and regional regulatory enforcement intensity as primary segmentation dimensions. CAGRs were derived from installed base estimation and mandated retest frequency modeling, with natural rubber price volatility and voltage-class harmonization progress treated as scenario variables.
Inputs from OSHA violation reports and European notified body certification databases were available through the study window; gaps in real-time utility procurement contract disclosure introduce uncertainty bands around public-sector demand timing. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and grid investment commitment patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market