
 Active Hearing Protection Market | 2026-2036
Active Hearing Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Active Hearing Protection Market Insights
The capital-intensity divergence between players is rotating competitive advantage toward integrated electronics manufacturers. 3M Company leverages its materials science portfolio to sustain dominance in industrial ear muff platforms. Honeywell International Inc. anchors its position through channel control across North American and European safety distribution networks. MSA Safety differentiates by specializing in fire service and industrial helmets with embedded communication systems.
Active hearing protection comprises electronic systems that use microphones, digital signal processors, and speakers to attenuate hazardous impulse noise while preserving situational awareness and speech intelligibility, typically achieving noise reduction ratings between 20 and 30 decibels with response times under one millisecond. These devices serve military, industrial, and recreational users who require protection without isolation from critical acoustic cues. Noise-canceling headphones represent the largest product category by volume, though electronic earplugs are capturing margin pools in specialized military and music applications. Communication systems technology commands premium positioning as end users integrate two-way radio and Bluetooth connectivity into standard equipment requirements. The manufacturing application segment remains structurally mature, while entertainment and aviation applications are attracting R&D investment for lightweight, high-fidelity designs.
OSHA's permissible exposure limits and the EU's Physical Agents Directive collectively shape product certification requirements and procurement specifications across major economies. The FDA regulates electronic hearing devices with sound amplification features in the United States, creating dual compliance pathways for manufacturers serving both occupational and consumer segments. NHTSA influence extends to motorsport and tactical vehicle applications where helmet-integrated systems must meet crash safety standards. Stakeholders must monitor evolving military interoperability standards and the convergence of hearing protection with biometric monitoring capabilities.
Market Dynamics
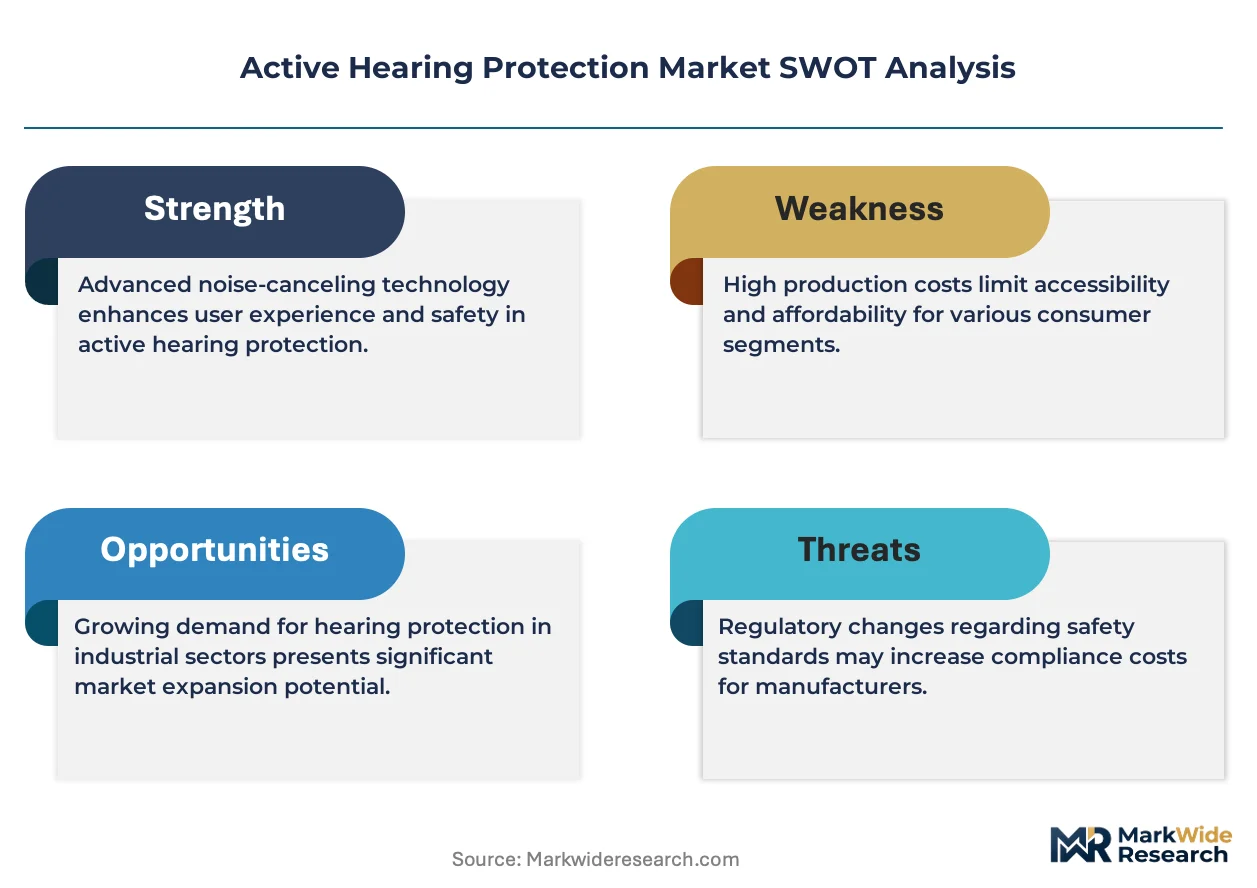
Active hearing protection markets face a structural pivot as military procurement specifications mandate embedded communication and biometric monitoring, forcing electronics integration into previously passive equipment categories.
Growth Catalysts
- EU Physical Agents Directive:Tightened workplace noise exposure limits across Germany, France, and Italy accelerate replacement of legacy passive earmuffs with electronic attenuation systems in heavy manufacturing and construction sites.
- Digital signal processing:Sub-millisecond impulse noise response algorithms now enable military and tactical law enforcement users to maintain situational awareness during firearms training and combat operations.
- Bluetooth integration:Industrial facilities in the United States and Canada specify two-way radio connectivity as standard equipment for plant maintenance crews, expanding addressable demand beyond basic hearing conservation.
Market Restraints
- Lithium-ion battery supply:Concentration of cell production in East Asia creates input cost volatility and extended lead times for manufacturers assembling rechargeable electronic earplugs and helmet systems.
- Passive protection substitution:Low-complexity foam earplugs retain dominant share in price-sensitive construction sub-segments, limiting premium product penetration where compliance budgets remain constrained.
- FDA dual pathway friction:Manufacturers serving both occupational and consumer amplification segments face divergent testing requirements that extend certification timelines and duplicate quality management systems.
Strategic Opportunities
- Aviation maintenance:Ground crew operations at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle generate concentrated demand for lightweight, high-fidelity active systems compatible with airport radio networks.
- Music and entertainment:Professional orchestras and live sound engineers represent an underpenetrated vertical where custom-molded electronic monitors command 4-6x unit economics versus industrial equivalents.
- OSHA enforcement waves:Regional emphasis programs targeting metal fabrication and woodworking create regulatory tailwinds for integrated hearing protection and fit-testing service bundles.
Industry Challenges
- Acoustic engineering talent:Shortage of specialists combining digital signal processing expertise with psychoacoustic validation capabilities constrains R&D throughput for advanced noise-canceling algorithms.
- Military interoperability certification:NATO standardization delays for encrypted communication protocols force manufacturers to maintain multiple hardware variants, fragmenting production scale.
- Legacy system integration:Industrial buyers with existing hearing conservation programs face friction retrofitting electronic platforms into established fit-testing and inventory management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Hearing Protection Market |
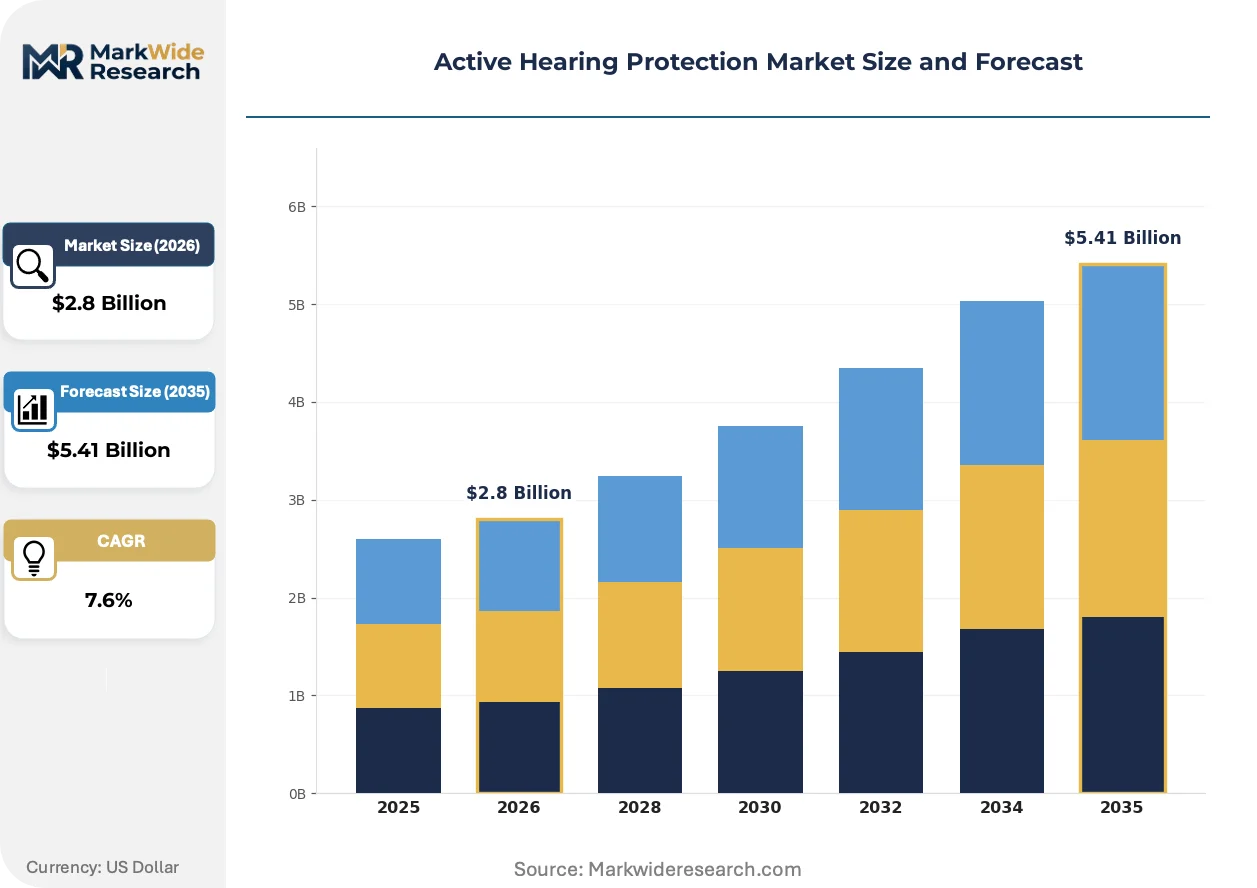
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Earplugs, Noise-Canceling Headphones, Acoustic Helmets, Adjustable Ear Muffs Technology: Active Noise Reduction, Passive Noise Isolation, Sound Enhancement, Communication Systems End User: Construction Workers, Musicians, Military Personnel, Industrial Workers Application: Outdoor Activities, Manufacturing, Aviation, Entertainment |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety, Sensear Pty Ltd., Phonak Communications AG, Dynamic Ear Company, Etymotic Research Inc., Starkey Hearing Technologies, Hellberg Safety AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Hearing Protection Market Trends and Innovations
Electronics miniaturization and algorithmic advancement are compressing form factors while expanding functional scope, blurring historical boundaries between hearing protection, communication equipment, and health monitoring devices.
MEMS microphone arrays and application-specific integrated circuits are miniaturizing active hearing protection into discreet in-ear formats previously occupied by passive foam plugs. Military special operations units and professional musicians drive early adoption of these low-profile systems. The technology is miniaturizing competitive positioning around ear canal geometry customization and real-time acoustic scene analysis.
REACH restrictions on persistent organic pollutants and RoHS substance limitations are forcing reformulation of printed circuit board substrates and solder compositions in European-sold products. Manufacturers must validate alternative material sets without degrading electromagnetic shielding performance in high-RF environments. Industrial distributors in Germany and the Netherlands now require full material disclosure documentation as a procurement gate.
Industrial buyers increasingly unbundle hearing protection from bundled personal protective equipment contracts, creating direct procurement relationships with specialized electronics manufacturers. Safety distributors in North America respond by acquiring technical service capabilities for device programming and firmware updates. This pattern concentrates most visibly in automotive manufacturing clusters around Detroit, Stuttgart, and Toyota City.
Active Hearing Protection Market Segmentation
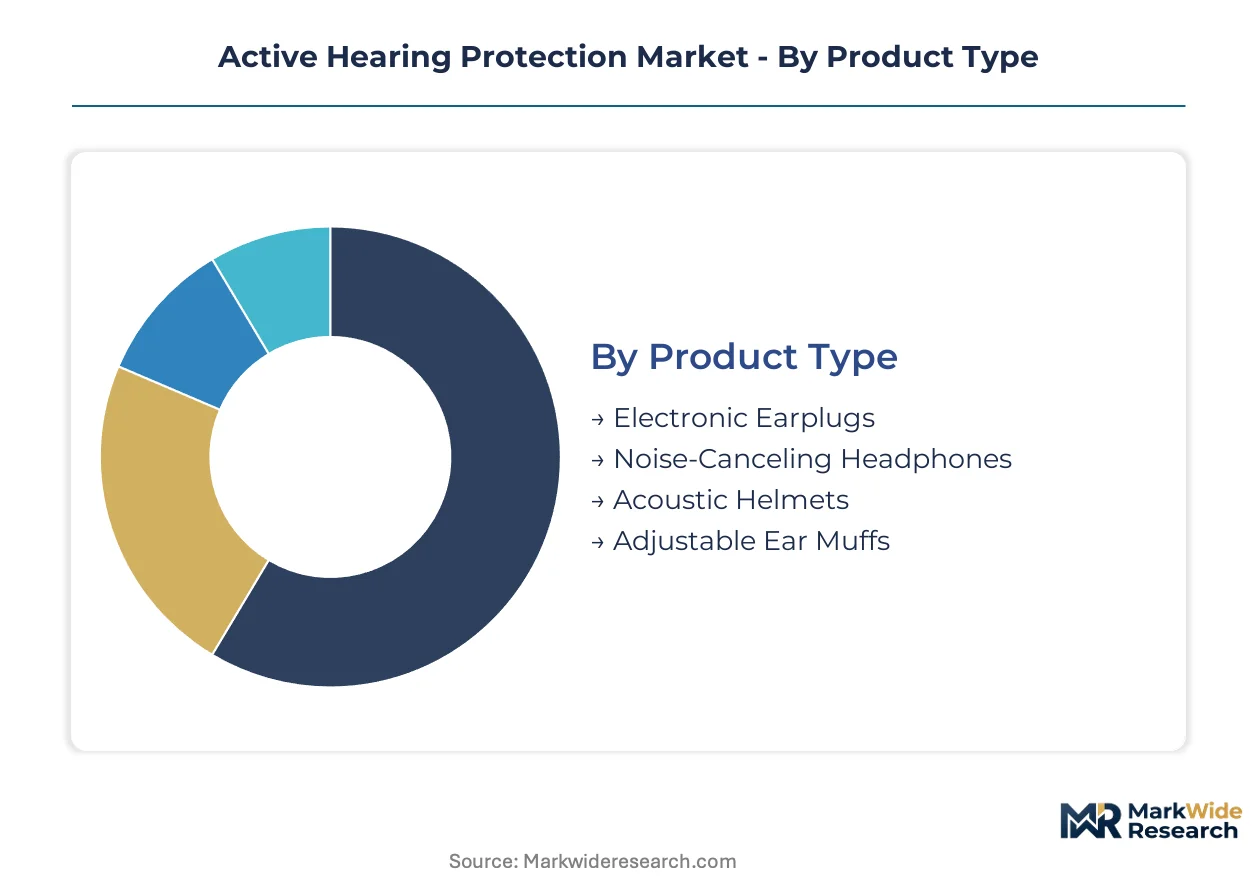
Active hearing protection markets fragment across four distinct dimensions that shape procurement channels, margin structures, and compliance pathways. Electronics integration intensity varies dramatically by segment, creating divergent competitive arenas for component suppliers versus finished device manufacturers.
Product Type:
Channel mix splits sharply: industrial safety distributors dominate ear muff and helmet sales, while consumer electronics retailers and direct-to-military contracts capture earplug and headphone volumes.
- Noise-Canceling Headphones:Circumaural designs with circumferential sealing cushions achieve 25-30 decibel noise reduction ratings through hybrid feedforward-feedback architectures. Manufacturing plants in Germany and the United States specify these as standard issue for grinding and stamping operations under tightened OSHA and EU Physical Agents Directive enforcement.
- Electronic Earplugs:Canal-fitting devices embed MEMS microphones and balanced-armature drivers in silicone or custom-molded housings. Military special operations units in NATO member states drive premium adoption for weapons training scenarios requiring situational awareness preservation.
- Acoustic Helmets:Hard-hat integrated systems combine impact protection with electronic attenuation modules. Fire service and heavy construction applications in France and Italy concentrate replacement demand.
- Adjustable Ear Muffs:Passive-active hybrid designs with electronic augmentation layers serve price-sensitive municipal and educational buyers.
By volume, Noise-Canceling Headphones leads. By growth pace, Electronic Earplugs is climbing the fastest.
Technology:
Cost tier stratification separates military-grade signal processing from commercial noise-canceling implementations, with communication-enabled systems commanding 3-4x unit economics.
- Active Noise Reduction:Digital signal processors execute real-time inverse-phase cancellation with sub-millisecond latency for impulse noise environments. Tactical law enforcement and competitive shooting ranges in the United States represent concentrated demand pockets.
- Communication Systems:Two-way radio and Bluetooth integration transforms hearing protection into networked crew coordination infrastructure. Aviation ground operations at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle generate specification-driven procurement.
- Sound Enhancement:Directional microphone arrays amplify speech and warning signals while attenuating hazardous levels. Industrial maintenance crews in automotive assembly plants adopt these for equipment monitoring applications.
- Passive Noise Isolation:Mechanical blocking without electronics retains dominant share in developing markets and temporary worker populations where battery dependency creates operational friction.
Communication Systems captures the steepest margin expansion, while Active Noise Reduction holds the largest installed base.
End User:
Application context determines feature prioritization: military buyers mandate encrypted interoperability, musicians demand flat-frequency response, and industrial users prioritize all-day wear comfort.
- Military Personnel:Combat and training applications require NIJ-compliant electronics with electromagnetic pulse hardening and multi-band radio compatibility. NATO procurement standardization efforts in Germany, Poland, and the United Kingdom consolidate vendor qualification.
- Industrial Workers:Manufacturing, utilities, and logistics employers specify fit-testing compatibility and inventory standardization across large workforces. Metal fabrication facilities in Ohio and Michigan drive North American volume.
- Construction Workers:Intermittent high-noise exposure and equipment sharing patterns favor robust, low-maintenance designs with visible compliance verification.
- Musicians:Custom-molded in-ear monitors with flat frequency response and ambient blending capabilities serve orchestral and live sound professionals in Vienna, London, and New York.
Industrial Workers represents the deepest volume pool. Musicians show the fastest value-per-unit appreciation.
Application:
Customer maturity varies: manufacturing buyers operate established hearing conservation programs, while entertainment and outdoor segments require education-intensive sales cycles.
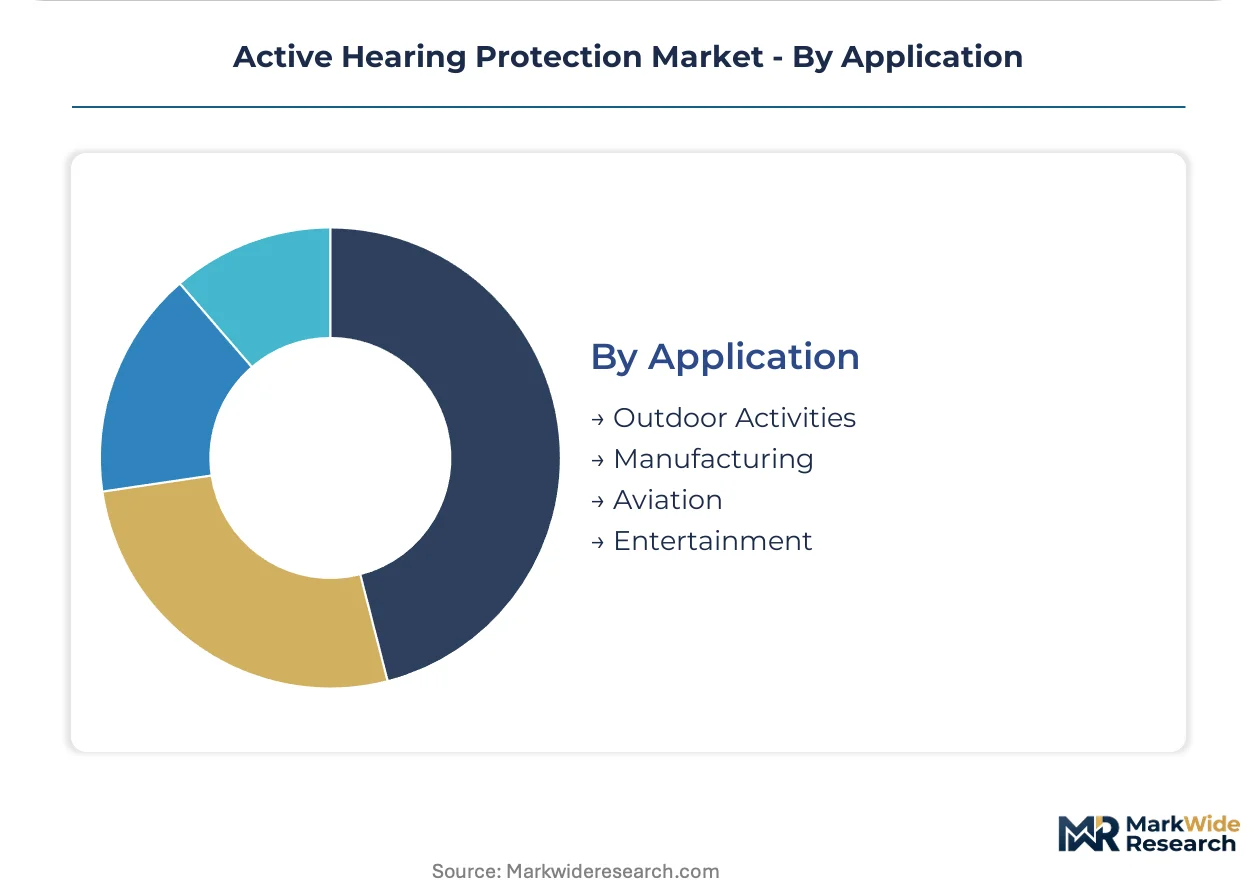
- Manufacturing:Continuous noise environments with documented exposure histories drive regulatory compliance purchases. Automotive and aerospace clusters around Stuttgart, Detroit, and Toyota City concentrate enterprise procurement.
- Aviation:Ground crew and pilot applications demand lightweight designs compatible with airport radio networks and cockpit communication systems. Maintenance operations at major European hubs standardize on dual-earcup configurations.
- Entertainment:Professional orchestras, live sound engineers, and broadcast technicians prioritize sonic accuracy over maximum attenuation. Custom fabrication capabilities differentiate supplier positioning.
- Outdoor Activities:Hunting, motorsport, and recreational shooting applications balance impulse noise protection with environmental awareness requirements.
Manufacturing anchors current revenue. Entertainment is gaining share fastest on premium pricing migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in active hearing protection equipment reveal Germany and the United States as net exporters of electronic attenuation systems, while China and Vietnam remain dependent on imported MEMS microphone arrays and digital signal processors from East Asian semiconductor foundries.
United States
OSHA enforcement waves in metal fabrication and woodworking create regulatory tailwinds for integrated hearing protection systems. The Department of Defense accelerates procurement of communication-enabled tactical headsets through NATO interoperability programs. Industrial safety distributors in Detroit and Houston drive volume for manufacturing plant retrofits.
Germany
The EU Physical Agents Directive tightens workplace noise exposure limits, forcing heavy manufacturing and construction sites to replace legacy passive earmuffs. Defense modernization budgets under the Zeitenwende policy expand military procurement of embedded communication systems. Automotive clusters around Stuttgart and industrial zones in North Rhine-Westphalia concentrate enterprise adoption.
France
ANSM oversight of medical device classifications creates compliance friction for manufacturers serving both occupational and consumer amplification segments. Fire service and heavy construction applications in Île-de-France and Provence-Alpes-Côte d'Azur drive replacement demand for acoustic helmets. Airport ground operations at Paris Charles de Gaulle standardize on dual-earcup configurations with radio connectivity.
United Kingdom
Ministry of Defence procurement standardization efforts consolidate vendor qualification for combat and training applications. The Health and Safety Executive aligns enforcement with EU Physical Agents Directive thresholds post-Brexit. Metal fabrication facilities in the Midlands and aerospace clusters around Bristol generate specification-driven demand.
Japan
METI industrial safety guidelines promote adoption of electronic attenuation in precision manufacturing and automotive assembly. Domestic semiconductor fabricators supply application-specific integrated circuits for MEMS microphone arrays. Manufacturing plants in the Toyota City cluster and industrial zones in Kansai drive fit-testing service bundling.
Active Hearing Protection Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized safety equipment manufacturers. The market exhibits tiered structure with premium positioning held by integrated electronics developers, mid-tier volume occupied by industrial safety distributors, and price-sensitive segments served by passive protection commodity suppliers. Three archetypes dominate: materials science conglomerates leveraging polymer and acoustic engineering portfolios; safety equipment specialists with channel control across North American and European distribution networks; and hearing health technology developers applying audiometric expertise to occupational applications. Competitive moves center on backward integration into MEMS microphone sourcing and geographic expansion through distributor acquisition.
Within the diversified industrial tier, 3M Company and Honeywell International Inc. exemplify scale-driven positioning through materials science and channel infrastructure respectively. MSA Safety occupies a specialist position in fire service and industrial helmets with embedded communication capabilities. These three entities represent the convergence of hearing protection with networked crew coordination infrastructure.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety |
| Sensear Pty Ltd. |
| Phonak Communications AG |
| Dynamic Ear Company |
| Etymotic Research Inc. |
| Starkey Hearing Technologies |
| Hellberg Safety AB |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for MEMS microphone arrays from East Asian foundries concentrate pricing power with integrated electronics manufacturers while forcing passive-protection assemblers into spot-market sourcing. This inventory compression cascades into tiered procurement contracts where buyers with volume commitments secure allocation priority over municipal and educational purchasers.
Pricing Analysis
The customization-premium spread separates standard noise-canceling headphones from configured-to-order electronic earplugs with custom-molded canal housings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation with NIJ-compliant military systems commanding substantial premiums over OSHA-grade industrial units. Cost compression in the standard tier intensifies as Chinese manufacturers expand capacity for basic active noise reduction modules. Municipal buyers in construction and education segments exhibit highest price sensitivity, while NATO procurement offices prioritize interoperability over unit cost.
Supply Chain Analysis
Taiwan Strait transit vulnerability for application-specific integrated circuits from TSMC and UMC foundries concentrates supply risk for digital signal processor cores. Lithium-ion cell production draws from China, South Korea, and Japan, with cathode active material supply anchored in Indonesian nickel processing and Chilean lithium brine operations. Single-source vulnerability for balanced-armature drivers from Knowles and Sonion facilities in Malaysia and Vietnam threatens earplug manufacturer output. Distribution runs through North American and European industrial safety distributors with technical service capabilities, bypassing traditional PPE bundling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive and aerospace OEMs consolidate hearing conservation procurement across multi-plant footprints, fragmenting distributor influence. Industrial facilities in Germany and the United States now demand direct manufacturer relationships with firmware update capabilities and fit-testing service integration.
For Market Incumbents: Shield installed base relationships by deepening backward integration into MEMS microphone sourcing and acquiring regional distributors with technical service capacity. The threat of specialized electronics manufacturers disintermediating traditional safety distributors demands preemptive channel control investments. Certification investment in NATO interoperability standards and FDA dual-pathway compliance creates switching costs that lock out emerging competitors. For New Entrants and Emerging Players: Anchor in music and entertainment verticals where custom-molded electronic monitors remain underpenetrated and 4-6x unit economics attract specialist fabrication capabilities. Aviation ground operations at European hub airports offer specification-driven procurement with less entrenched incumbent relationships than manufacturing segments. Direct-to-orchestra sales partnerships with acoustic engineering consultancies bypass distributor gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates divesting non-core hearing protection divisions amid portfolio restructuring. Long-term viability hinges on electronics integration intensity rather than passive protection commodity exposure. The signal to watch is NATO standardization completion for encrypted communication protocols, which will consolidate vendor qualification lists and eliminate hardware variant fragmentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sourcing | Captive microphone supply insulates margins from Taiwan Strait logistics volatility. |
| Bluetooth Platform Certification | FCC and CE marking for dual-radio compatibility opens aviation and tactical law enforcement procurement. |
| Custom Mold Fabrication Acquisition | In-house ear canal scanning and silicone injection molding captures music vertical premium economics. |
| Fit-Testing Service Bundling | OSHA enforcement emphasis programs in metal fabrication create recurring revenue attachment opportunities. |
| NATO Interoperability Qualification | Standardized encrypted protocol compliance consolidates vendor lists across Germany, Poland, and United Kingdom procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with safety equipment procurement managers, acoustic engineering directors, and military specification officers; and secondary validation through OSHA enforcement records, EU Physical Agents Directive implementation reports, FDA 510(k) filings for sound amplification devices, and NATO standardization documentation. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against national occupational safety expenditure aggregates anchored forecast integrity.
Across the analysis window, the forecasting framework modeled demand trajectories by technology tier, end-user vertical, and application context with specific attention to communication systems integration intensity and battery chemistry transitions. CAGRs were derived from segment-level elasticity analysis against regulatory enforcement timelines and defense procurement cycle phasing. Military interoperability standardization progress and REACH/RoHS substance restriction implementation served as industry-specific demand modifiers.
Material uncertainties — lithium-ion supply chain disruption, NATO protocol standardization delays, and FDA dual-pathway regulatory friction — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding enforcement continuity and procurement budget allocation. Practitioners should keep alternative scenarios live as battery chemistry substitution timelines and encrypted communication certification schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Portable Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market