
 Padlock Seals Market | 2026-2036
Padlock Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Padlock Seals Market Outlook
Chinese metalworking clusters are consolidating output of zinc-alloy and stainless-steel padlock seal bodies. TydenBrooks Security Products Group leverages integrated die-casting and laser-marking operations across Midwestern US facilities. Unisto AG anchors European pharmaceutical and banking logistics with precision-molded security seals certified to customs union standards. Mega Fortris competes on volume in Asian container shipping, sustaining cost leadership through automated assembly lines in Malaysia and Indonesia.
A padlock seal is a single-use mechanical fastening device combining a hasp-like body with a captive locking mechanism, typically manufactured through zinc die-casting or injection-molded ABS polymer and rated for pull strengths from 15 kg to over 100 kg depending on security grade. Its primary function is to provide immediate visual evidence of tampering while securing trailer doors, tote boxes, utility meters, and pharmaceutical totes in transit. Metal seals occupy the premium tier where ISO 17712 compliance is mandatory for international container movements, while plastic seals dominate high-volume warehousing and retail loss-prevention programs due to unit economics below ten cents per piece. Wire seals represent the fastest-growing construction among product types, displacing legacy crimp designs in cash-in-transit and nuclear material custody applications where adjustable length and sequential numbering reduce substitution risk.
FDA Title 21 CFR regulations mandate tamper-evident packaging for over-the-counter pharmaceuticals, directly expanding seal procurement by US drug distributors and contract packagers. EMA's Good Distribution Practice guidelines extend similar requirements across European Union member states, while India's CDSCO enforces track-and-trace serialization rules that incorporate physical seal verification at warehouse handoffs. Stakeholders must monitor evolving customs-to-customs mutual recognition agreements, as harmonized seal certification standards determine which manufacturers qualify for cross-border tender awards without redundant testing.
Market Dynamics
ISO 17712 certification requirements are compressing supplier qualification timelines while Chinese metalworking clusters consolidate zinc-alloy and stainless-steel body production, reshaping competitive access to freight corridors.
Growth Catalysts
- CDSCO track-and-trace mandates:India's pharmaceutical serialization rules incorporate physical seal verification at warehouse handoffs, accelerating replacement cycles for tamper-evident fasteners across domestic drug distribution networks.
- Wire seal construction:Adjustable-length wire seals with sequential numbering are displacing legacy crimp designs in cash-in-transit and nuclear material custody applications where substitution risk demands flexible fastening.
- Port modernization in India:Customs automation programs and container terminal upgrades are standardizing high-security seal procurement across Mumbai, Chennai, and Mundra port authorities.
Market Restraints
- Zinc price volatility:Die-cast zinc-alloy bodies face input cost pressure from London Metal Exchange fluctuations, squeezing margin structures for mid-tier seal fabricators without backward integration into metal sourcing.
- Supplier concentration in Zhejiang:Chinese metalworking clusters control roughly two-thirds of global stainless-steel hasp production, creating geographic single-source risk for buyers requiring rapid scale-up.
- Plastic seal performance ceiling:Injection-molded ABS polymer variants fail ISO 17712 pull-strength thresholds above 50 kg, restricting their deployment to non-container applications despite unit economics below ten cents.
Strategic Opportunities
- EMA Good Distribution Practice expansion:European pharmaceutical cold-chain logistics are extending tamper-evident requirements to last-mile delivery totes, opening new volume tiers for precision-molded security seals.
- Laser-marking convergence with RFID:Hybrid seals combining visible sequential numbering with embedded radio-frequency identification tags enable automated gate verification without manual inspection.
- Utility meter digitization in Southeast Asia:Smart grid deployments across Thailand, Vietnam, and Indonesia are creating demand for serialized padlock seals that bridge physical tamper evidence with digital asset tracking.
Industry Challenges
- ISO 17712 testing backlog:Third-party certification laboratories face eighteen-month queues for high-security seal classification, delaying new product launches and contract eligibility for unqualified suppliers.
- Die-casting tooling amortization:Zinc-alloy body production requires hardened steel molds with six-figure capital outlays, favoring incumbents with installed capacity and deterring specialized entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padlock Seals Market |
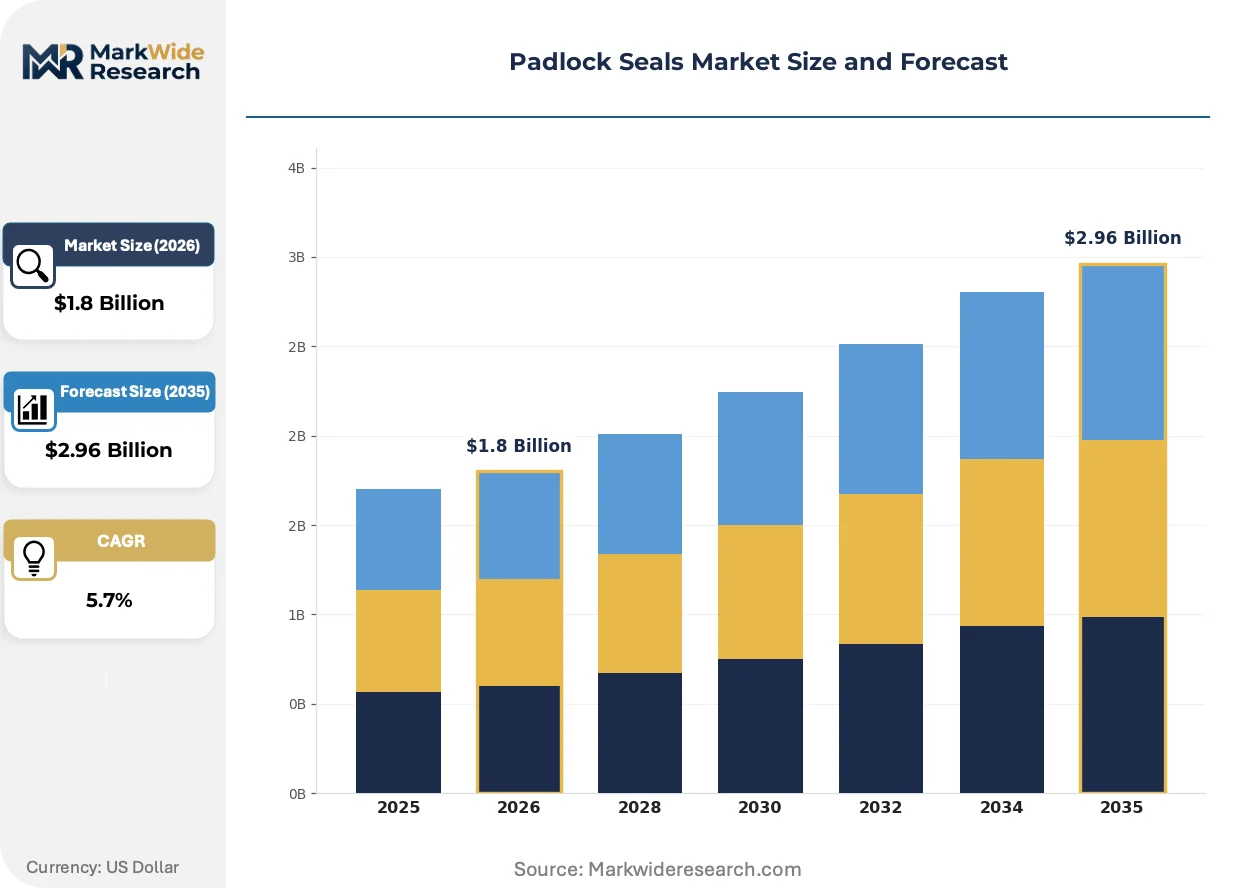
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Seals, Metal Seals, Wire Seals, Cable Seals Application: Logistics, Warehousing, Transportation, Waste Management End User: Retail, Automotive, Pharmaceuticals, Manufacturing Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | TydenBrooks Security Products Group, Unisto AG, American Casting & Manufacturing, Acme Seals, Cambridge Security Seals, Mega Fortris, Shosky Security, PRECINTIA INTERNATIONAL S.A., Haoshi Light Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padlock Seals Market Strategic Shifts
Physical-digital convergence is redefining tamper evidence from passive mechanical fastening to active supply-chain data capture, with three distinct vectors reshaping product architecture and buyer specifications.
Blockchain-anchored seal verification is decentralizing custody documentation across pharmaceutical and precious-metals logistics. Distributed ledger protocols now encode seal serial numbers, break timestamps, and geolocation data into immutable records accessible to customs authorities and insurers without intermediary data aggregators. Swissmedic and Health Canada are piloting interoperable verification standards that would eliminate redundant paper-based chain-of-custody documentation at border crossings.
REACH substance restrictions are forcing reformulation of ABS polymer compounds used in retail loss-prevention seals. ECHA's expanding candidate list of substances of very high concern now covers certain plasticizers and flame retardants common in injection-molded security devices, compelling compounders to validate alternative formulations without sacrificing pull-strength or UV stability. European contract packagers are accelerating supplier audits to preempt compliance gaps ahead of 2026 authorization deadlines.
Buyer consolidation among third-party logistics providers is compressing vendor qualification cycles and favoring multi-product security suppliers. DHL Supply Chain and Kuehne+Nagel are centralizing seal procurement through framework agreements covering twelve to eighteen-month horizons, displacing spot purchasing from regional distributors. This concentration is most visible in German automotive inbound logistics, where OEM-mandated supplier reduction programs have halved approved seal vendors since 2022.
Padlock Seals Market Segmentation
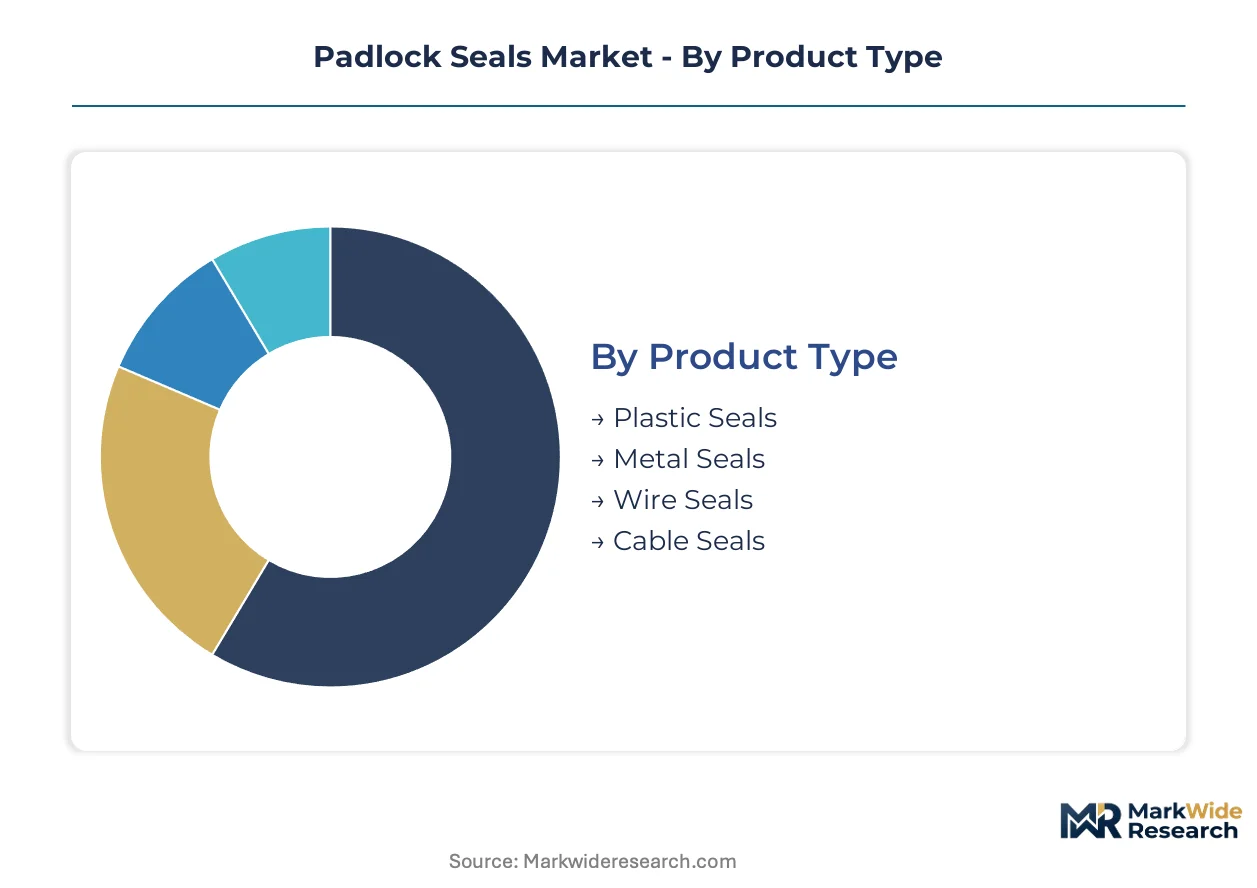
Padlock seal procurement varies sharply by security grade, material specification, and regulatory context. Buyers select construction type based on ISO 17712 compliance requirements, end-use risk profiles, and total cost of ownership across replacement cycles.
Product Type:
Replacement cycles accelerate where regulatory certification mandates metal construction over legacy plastic alternatives.
- Plastic Seals:Injection-molded ABS polymer bodies deliver pull strengths below 50 kg, disqualifying them from international container movements. Warehouse loss-prevention programs and retail tote applications dominate procurement volumes due to unit economics below ten cents per piece.
- Metal Seals:Zinc-alloy die-cast or stainless-steel hasp designs rated for 100+ kg pull strength satisfy ISO 17712 high-security classification. Mumbai, Chennai, and Mundra port authorities are standardizing these seals under customs automation programs.
- Wire Seals:Adjustable-length construction with sequential numbering displaces crimp designs in cash-in-transit and nuclear material custody where substitution risk demands flexible fastening geometry.
- Cable Seals:Braided steel cable variants bridge metal seal strength with wire seal adjustability for utility meter and bulk liquid tanker applications.
Plastic seals sit at the top of the volume ranking, with wire seals climbing the fastest.
Application:
Cost tier differentiation separates premium-certified deployments from high-volume commodity procurement.
- Logistics:Third-party logistics providers centralize procurement through twelve to eighteen-month framework agreements covering multi-modal freight. DHL Supply Chain and Kuehne+Nagel are consolidating approved vendor lists.
- Warehousing:High-velocity distribution centers specify color-coded plastic seals for tote tracking without ISO 17712 overhead. Unit economics drive spot purchasing from regional distributors.
- Transportation:Cross-border trucking and rail movements require tamper-evident sealing at every handoff point. EMA Good Distribution Practice guidelines extend requirements to European pharmaceutical cold-chain lanes.
- Waste Management:Hazardous waste manifesting uses serialized seals to document chain-of-custody from generator to treatment facility.
Logistics commands the largest procurement budget, while transportation exhibits the steepest expansion trajectory.
End User:
Customer type determines whether procurement prioritizes regulatory documentation or operational throughput.
- Retail:Loss-prevention teams specify color-coded plastic seals for high-volume carton sealing at distribution centers. RFID-laser hybrid variants are gaining traction for automated gate verification.
- Automotive:German OEM inbound logistics programs have halved approved seal vendors since 2022 through supplier reduction mandates. Just-in-time sequences demand zero-defect delivery performance.
- Pharmaceuticals:FDA Title 21 CFR mandates tamper-evident packaging for over-the-counter drugs, while India's CDSCO enforces track-and-trace serialization with physical seal verification at warehouse handoffs.
- Manufacturing:Component suppliers to regulated industries adopt ISO 17712 seals preemptively to qualify for automotive and aerospace tender awards.
Pharmaceuticals leads premium-tier procurement, with automotive expanding most quickly.
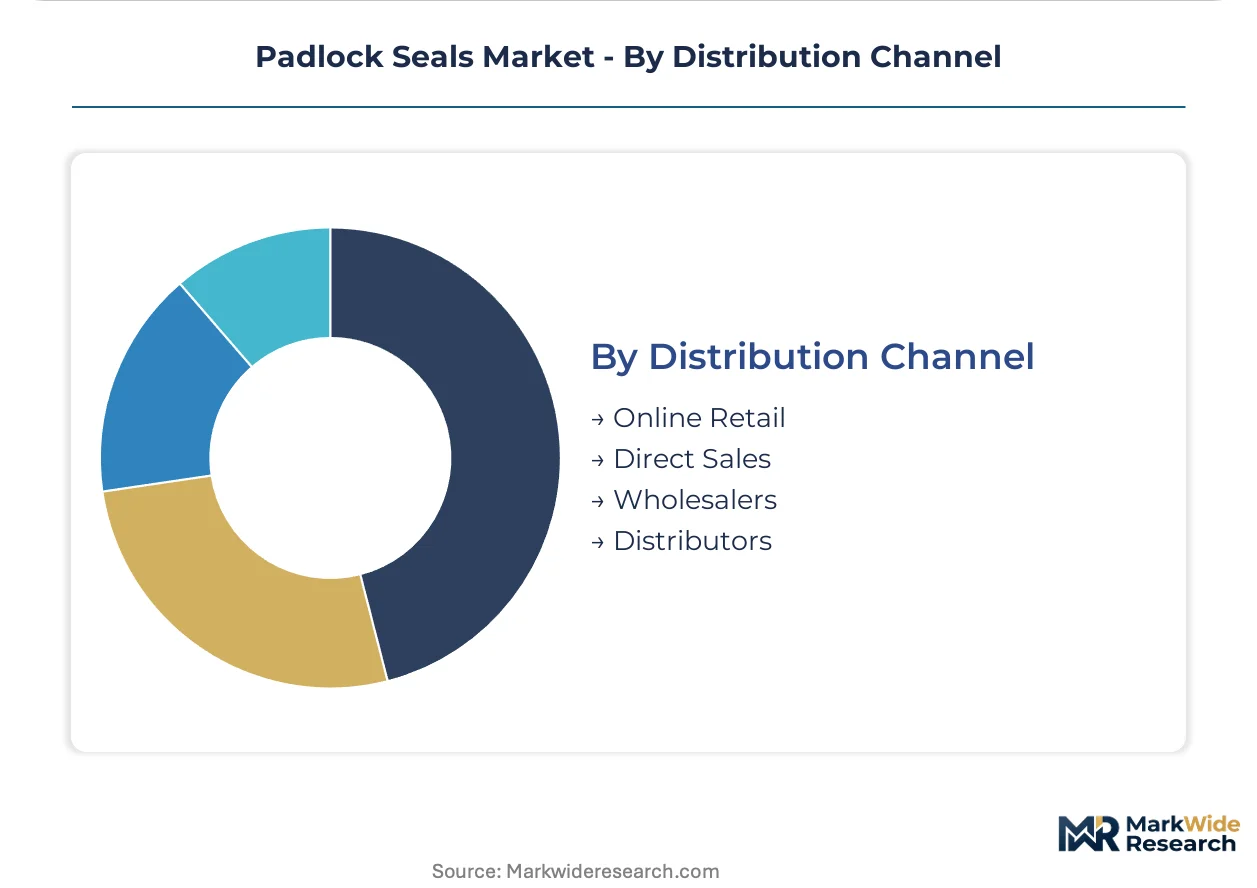
Distribution Channel:
Supply concentration in Chinese metalworking clusters shapes how buyers access certified product.
- Online Retail:E-commerce platforms serve small-volume buyers with standardized plastic seal SKUs lacking customization or certification documentation.
- Direct Sales:Large seal manufacturers operate dedicated account teams for pharmaceutical and automotive OEMs requiring audit trails and batch certificates.
- Wholesalers:Regional inventory positions support rapid replenishment for warehousing and waste management contractors with unpredictable demand timing.
- Distributors:Authorized distributors carry ISO 17712 certified inventory for freight forwarders and customs brokers requiring immediate documentation.
Direct sales captures the highest-margin transactions, with distributors gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as Chinese metalworking clusters absorb compliance-cost advantages from consolidated zinc-alloy supply chains, while Indian port automation and European pharmaceutical serialization tighten demand specifications.
China
Zhejiang and Guangdong provinces dominate stainless-steel hasp fabrication for export markets. SAMR's national standardization push aligns domestic seal testing with ISO 17712 benchmarks, reducing friction for outbound certification. Ningbo metalworking clusters now supply two-thirds of global die-cast zinc-alloy bodies.
India
CDSCO track-and-trace mandates are accelerating seal replacement cycles across domestic pharmaceutical distribution. Mumbai, Chennai, and Mundra port authorities are standardizing high-security procurement under customs automation programs. DGFT's phased rollout of serialized warehouse handoff verification creates captive demand for ISO 17712 certified metal seals.
United States
FDA Title 21 CFR tamper-evident packaging rules expand seal procurement by drug distributors and contract packagers. Midwestern integrated manufacturing facilities combine die-casting with laser-marking operations for domestic pharmaceutical logistics. EPA hazardous waste manifesting requirements sustain demand for serialized seals in treatment-facility chain-of-custody documentation.
Germany
EMA Good Distribution Practice guidelines extend tamper-evident requirements to pharmaceutical cold-chain last-mile delivery. KBA-mandated supplier reduction programs in automotive inbound logistics have halved approved seal vendors since 2022. Bavarian precision-molding specialists anchor European banking and pharmaceutical logistics with customs-union certified product lines.
Switzerland
Swissmedic blockchain-anchored verification pilots are decentralizing custody documentation for pharmaceutical and precious-metals logistics. Geneva and Basel logistics corridors demand hybrid seals bridging physical tamper evidence with digital asset tracking. REACH substance restrictions are forcing reformulation of polymer compounds ahead of 2026 authorization deadlines.
Padlock Seals Market Competitive Environment
Zhejiang producers anchor the volume tier; Midwestern US and Swiss specialists hold premium-certification positions. The vendor base organizes around three strategic archetypes: integrated metalworkers with captive die-casting capacity, precision polymer compounders serving retail loss-prevention, and hybrid physical-digital specialists bridging RFID with laser-marking. Dominant competitive moves include backward integration into zinc-alloy sourcing and strategic partnerships with third-party logistics providers for framework agreement positioning.
Among the named fabricators, TydenBrooks Security Products Group and Unisto AG occupy positions on the premium-certification vector, with Mega Fortris representing scale-driven Asian manufacturing. These three exemplify the geographic and capability segmentation defining competitive access: US and Swiss entities anchor pharmaceutical and automotive compliance markets, while Malaysian and Indonesian automated assembly lines sustain cost leadership in container shipping volumes.
| Leading Market Players |
|---|
| TydenBrooks Security Products Group |
| Unisto AG |
| American Casting & Manufacturing |
| Acme Seals |
| Cambridge Security Seals |
| Mega Fortris |
| Shosky Security |
| PRECINTIA INTERNATIONAL S.A. |
| Haoshi Light Industrial Products |
| Others |
Value Chain & Pricing Dynamics
RFID-laser hybrid manufacturing is compressing cost curves for serialized security seals while concentrating production among integrated Midwestern US and Swiss fabricators capable of precision-molding and embedded chip assembly. This technological shift simultaneously elevates certification barriers and rewards scale, locking out fragmented metal stampers and polymer compounders lacking capital for six-figure die-casting tooling.
Pricing Analysis
Distributor margins absorb the steepest compression in plastic seal tiers where spot purchasing from regional wholesalers yields unit economics below ten cents. Three-tier pricing structure across premium ISO 17712-certified metal, mid-grade cable, and economy ABS polymer separates pharmaceutical logistics budgets from warehousing commodity procurement. Price differentiation hinges on certification grade and volume scale, with zinc price volatility squeezing mid-tier fabricators lacking backward integration. Automotive OEMs exhibit lowest price sensitivity due to zero-defect delivery requirements, while retail loss-prevention teams drive hardest bargain hunting.
Supply Chain Analysis
Regional distribution centers in Ningbo, Mumbai, and Rotterdam anchor hub-and-spoke patterns for certified seal inventory. Manufacturing concentrates in China, Malaysia, and Indonesia where automated assembly lines feed container shipping volumes. Raw material dependencies span London Metal Exchange zinc, ABS polymer compounds, and stainless-steel wire feedstock. Single-source vulnerability runs through Zhejiang metalworking clusters controlling two-thirds of global die-cast body output. Distribution runs through authorized distributors carrying ISO 17712 documentation for freight forwarders requiring immediate customs compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Padlock seal procurement has shifted toward premium-certified specifications as pharmaceutical serialization mandates and customs automation programs displace commodity plastic alternatives. Quality-grade metal seals now command disproportionate margin expansion.
For Market Incumbents: Cement ISO 17712 certification moats by accelerating third-party laboratory queue positions before eighteen-month backlogs harden competitive access. Deepen captive die-casting capacity in Midwestern US facilities to offset zinc price volatility threatening mid-tier margin structures. Defend against emerging Asian volume players by locking twelve-to-eighteen-month framework agreements with consolidating third-party logistics providers. For New Entrants and Emerging Players: Launch via direct sales to Southeast Asian utility meter digitization programs where smart grid deployments create demand for serialized seals bridging physical tamper evidence with digital asset tracking. Target Thai and Vietnamese smart grid deployments as most penetrable geography given nascent supplier relationships and absence of incumbent framework agreements. Pursue white-space in European pharmaceutical cold-chain last-mile delivery totes where EMA Good Distribution Practice extensions outpace certified supplier capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among precision polymer compounders facing REACH substance restriction compliance costs and reformulation deadlines. Long-term viability favors hybrid physical-digital specialists with RFID-laser convergence capabilities across the five-to-ten year technology adoption window. Monitor ISO 17712 testing laboratory queue lengths as inflection signal: contracting timelines indicate certification supply relief, while extension confirms persistent scarcity premium.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc-Alloy Sourcing | Captive metal supply shields margin structures from London Metal Exchange volatility affecting die-cast body production. |
| RFID-Laser Hybrid Product Launch | Embedded radio-frequency identification tags enable automated gate verification without manual inspection for pharmaceutical logistics. |
| ISO 17712 Certification Investment | Third-party laboratory qualification unlocks cross-border tender awards under harmonized customs-to-customs mutual recognition agreements. |
| Framework Agreement with 3PL Providers | DHL Supply Chain and Kuehne+Nagel centralization displaces spot purchasing and locks twelve-to-eighteen-month revenue visibility. |
| REACH Compliance Reformulation | ECHA substance restrictions force ABS polymer compound validation ahead of 2026 authorization deadlines for European market access. |
Study Parameters
Multiple input streams — customs automation program documentation, pharmaceutical distributor procurement records, and metalworking cluster production data — were reconciled across primary interviews with seal manufacturing plant managers, freight forwarder procurement leads, pharmaceutical supply chain directors, and customs broker operations heads. Secondary validation drew from ISO 17712 certification registries, CDSCO track-and-trace mandate filings, EMA Good Distribution Practice guidelines, and SEC disclosures from listed logistics providers. Bottom-up unit economics and top-down corridor demand estimates were triangulated to anchor volume projections.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped analytical framework development over the projection horizon. Security grade tier, material specification, and regulatory context segmentation modeled replacement cycle acceleration where certification mandates displace legacy alternatives. CAGRs were derived from installed base turnover rates and port automation program procurement schedules, with zinc price volatility and testing laboratory queue lengths incorporated as sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended ISO 17712 certification delays or acute zinc supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market