
 Bulletproof Gear Market | 2026-2036
Bulletproof Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Bulletproof Gear Market Insights
Asset-light manufacturing partnerships and government leasing programs is fragmenting competitive dynamics in bulletproof gear. Point Blank Enterprises leverages domestic production capacity to anchor military contracts. DuPont de Nemours sustains its position through captive Kevlar fiber supply. Safariland differentiates via modular vest platforms for law enforcement agencies.
Bulletproof gear encompasses personal protective equipment engineered to defeat ballistic threats through layered fiber composites, ceramic strike faces, or hybrid configurations meeting specific threat-level ratings. The primary purpose centers on reducing projectile penetration and backface deformation trauma for personnel in combat or high-risk security environments. Body armor commands the dominant value pool as militaries replace legacy flak vests with lightweight plate carriers. Ceramic plates and UHMWPE composites represent the fastest-growing material category as end users seek multi-hit protection below five pounds per plate. Law enforcement applications generate concentrated margin pools due to shorter replacement cycles and officer-specific fitting requirements.
NIJ certification protocols in the United States, CE marking under the EU PPE Regulation, and ISO 14876 ballistic test standards collectively define product admissibility and liability exposure across procurement channels. These frameworks force manufacturers to maintain parallel testing facilities and documentation systems, raising fixed costs for new entrants. Stakeholders must monitor evolving threat profiles from armor-piercing ammunition and directed-energy weapons to anticipate next-generation protection requirements.
Market Dynamics
The transition from legacy flak vests to lightweight plate carriers is compressing replacement cycles across NATO military procurement channels. Ceramic composite inserts and UHMWPE materials are displacing traditional aramid fibers as the baseline protection standard.
Growth Catalysts
- NIJ Level IV Certification Mandates:United States federal law enforcement agencies now require ceramic composite plates meeting NIJ 0101.06 standards, forcing fleet-wide upgrades of soft armor systems.
- Armor-Piercing Threat Escalation:Militaries in Poland, Germany, and the United Kingdom are accelerating orders for multi-hit capable plates rated against M2 AP and tungsten-core ammunition.
- Domestic Content Requirements:The Berry Amendment and similar Buy American provisions in defense procurement are channeling production investment toward captive U.S. fiber and ceramic manufacturing capacity.
Market Restraints
- Alumina and Silicon Carbide Supply Concentration:Ceramic strike face production depends on Chinese and Ukrainian raw material processors, creating vulnerability to export controls and conflict disruption.
- Extended NIJ Certification Timelines:Third-party ballistics laboratory capacity constraints in the United States stretch product approval cycles to 18-24 months, freezing new entrants from contract eligibility.
- Polymer Weight-Floor Limitations:UHMWPE plates below 4.5 pounds sacrifice multi-hit integrity against steel-core threats, capping lightweight adoption for frontline infantry applications.
Strategic Opportunities
- Swedish and Finnish NATO Accession:New member states are rebuilding strategic stockpiles and establishing domestic armor integration facilities, opening procurement windows for qualified suppliers.
- Directed-Energy Countermeasures:Integration of conductive mesh layers with traditional ballistic substrates addresses emerging laser and microwave weapon threats in vehicle crew protection.
- State-Level Police Consolidation:Multi-agency purchasing cooperatives in Texas, California, and Florida are streamlining vest procurement through master service agreements, favoring vendors with modular platform architectures.
Industry Challenges
- Ballistics Engineer Scarcity:Specialized expertise in ceramic fracture mechanics and backface signature modeling concentrates at a handful of government laboratories and primes, constraining R&D throughput.
- Legacy System Integration Friction:New plate carrier designs must interface with existing MOLLE webbing, communications routing, and quick-release mechanisms, adding customization cost and test iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulletproof Gear Market |
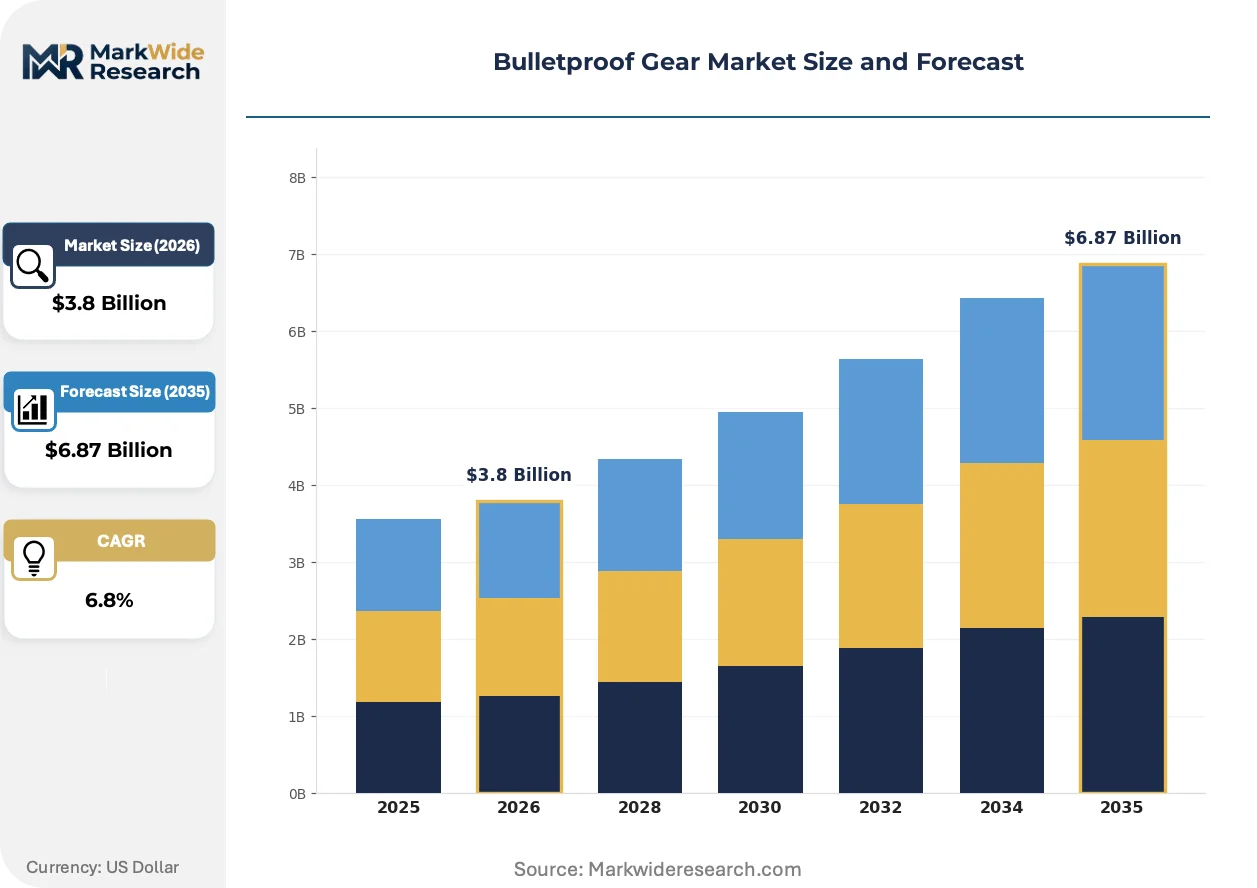
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Ballistic Helmets, Tactical Vests, Bomb Disposal Suits, Protective Shields Material: Kevlar, Dyneema, Spectra, Ceramic Plates, UHMWPE Composite Application: Military Operations, Law Enforcement, Homeland Security, Private Security, Corrections Facilities End User: Armed Forces, Police Departments, Security Firms, Intelligence Agencies, Emergency Responders |
| Companies Covered | Point Blank Enterprises, Inc., Safariland, LLC, DuPont de Nemours, Inc., Honeywell International Inc., Avon Protection plc, BAE Systems plc, Armor Express, MKU Limited, 3M Ceradyne, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulletproof Gear Market Trends and Innovations
Material science breakthroughs and procurement digitization are converging to compress product lifecycles and fragment traditional supplier relationships. Three developments are actively restructuring competitive positioning.
Hybrid ceramic-polyethylene laminates are collapsing the weight-performance tradeoff that has governed infantry armor selection for two decades. U.S. Army PEO Soldier and Marine Corps Systems Command are fielding plates below 4 pounds with Level IV equivalent protection against 7.62mm armor-piercing rounds. This is collapsing the addressable market for pure aramid soft armor in ground combat roles, relegating Kevlar and Twaron to concealable law enforcement vests and fragmentation protection.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-repellent fabric treatments used in plate carrier exteriors. European manufacturers must certify alternative durable water-repellent chemistries by 2026 or face import barriers. German and French defense procurement agencies are accelerating testing of silicone-based and hydrocarbon alternatives, with Bundeswehr technical teams leading validation protocols for multi-climate performance.
Unit-level direct purchasing through Defense Logistics Agency e-commerce portals is fragmenting traditional prime-contractor relationships. Battalion and company commanders in U.S. Army and Marine Corps units now requisition plate carriers and accessory components through FedMall and similar platforms, bypassing multi-year program office acquisition cycles. This pattern concentrates in special operations and security force assistance brigades, where mission-specific configuration requirements outpace centralized specification timelines.
Bulletproof Gear Market Segmentation
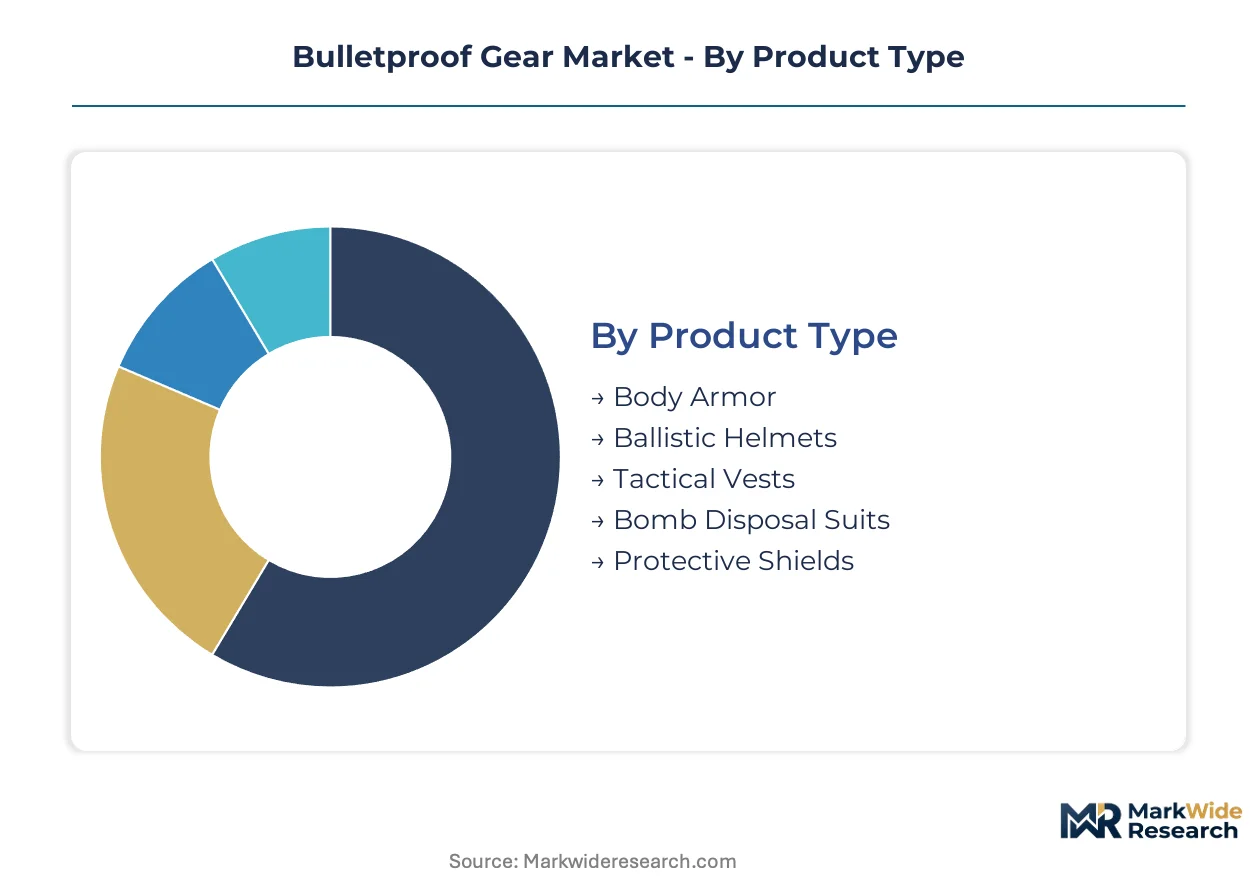
Segmentation in bulletproof gear separates procurement channels with radically different technical specifications, replacement cycles, and certification burdens. Military buyers prioritize multi-hit ceramic plates against armor-piercing threats, while law enforcement agencies demand concealable soft armor with shorter field lifespans. Material selection and end-user identity together determine pricing power and supplier relationships across this fragmented demand base.
Product Type:
Mature vest platforms dominate unit volumes, while emerging integrated systems reshape performance benchmarks across threat environments.
- Body Armor:Ceramic composite and UHMWPE insert plates rated NIJ Level III and IV constitute the core procurement category for NATO ground forces. United States military channels are consolidating orders around lightweight multi-curve designs that integrate with existing plate carrier architectures.
- Ballistic Helmets:High-cut and mid-cut configurations using hybrid aramid-UHMWPE weaves are displacing legacy PASGT designs in special operations and conventional infantry units. German Bundeswehr and British Army procurement offices are accelerating fielding of helmet systems with integrated rail mounts and night vision shrouds.
- Tactical Vests:Modular plate carriers with MOLLE-compatible load-bearing surfaces serve vehicle crews and dismounted patrols requiring rapid reconfiguration.
- Bomb Disposal Suits:Full-encapsulation ensembles with integrated cooling and communications systems address explosive ordnance disposal teams in military and federal law enforcement channels.
- Protective Shields:Handheld and mobile ballistic barriers rated for rifle threats support entry teams and checkpoint operations in urban security environments.
Body Armor handles the majority of throughput; Ballistic Helmets is the fastest mover on share.
Material:
Cost tier separation between commodity aramid fibers and advanced ceramic-polymer hybrids defines supplier margins and end-user access.
- Kevlar:DuPont's para-aramid fiber remains the baseline for concealable soft armor and fragmentation protection in law enforcement vests. United States domestic content requirements under the Berry Amendment sustain captive North American spinning capacity despite weight disadvantages against UHMWPE alternatives.
- Dyneema:DSM's gel-spun polyethylene fiber commands premium positioning in maritime and humid environments where moisture degradation threatens aramid performance. Dutch and Scandinavian defense procurement channels specify Dyneema-based inserts for coastal and amphibious units.
- Spectra:Honeywell's ultra-high molecular weight polyethylene competes with Dyneema in North American military and federal law enforcement specifications.
- Ceramic Plates:Alumina, silicon carbide, and boron carbide strike faces bonded to composite backings deliver Level IV protection against armor-piercing ammunition.
- UHMWPE Composite:Pure polyethylene plates without ceramic strike faces achieve Level III protection at sub-4-pound weights for dismounted infantry load reduction.
Ceramic Plates command the highest unit economics; UHMWPE Composite is expanding most quickly in ground combat procurement.
Application:
Volume concentrates in military channels, while margin structure favors law enforcement and specialized security segments with accelerated replacement requirements.
- Military Operations:Conventional and special operations forces drive demand for plate carriers, ballistic helmets, and scalable armor systems against evolving armor-piercing threats. Polish and Baltic state military procurement agencies are rebuilding strategic stockpiles with NATO-interoperable equipment following regional security realignments.
- Law Enforcement:Municipal, state, and federal police agencies generate recurring revenue through 5-year vest replacement cycles and officer-specific fitting protocols. Texas and California multi-agency purchasing cooperatives are consolidating procurement through master service agreements.
- Homeland Security:Border protection and critical infrastructure security units require modular platforms adaptable to variable threat environments.
- Private Security:Corporate executive protection and high-value asset transport teams source concealable soft armor with civilian-legal specifications.
- Corrections Facilities:Stab-resistant and spike-protected vests address close-quarters threats in prison and detention environments with distinct certification requirements from ballistic standards.
Military Operations handles the majority of throughput; Law Enforcement delivers the steepest margin expansion trajectory.
End User:
Customer type determines specification complexity, with armed forces demanding integrated system-of-systems approaches and emergency responders prioritizing rapid donning and doffing.
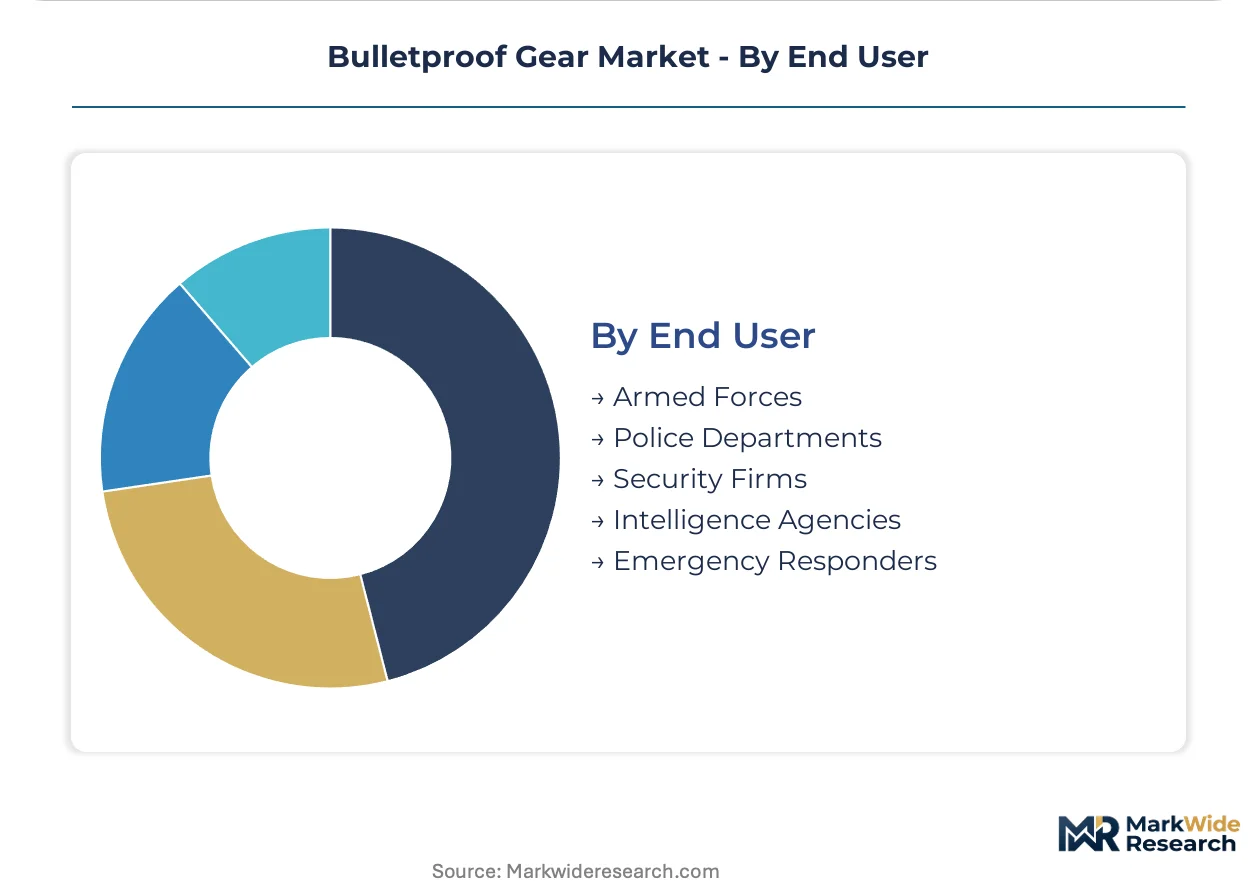
- Armed Forces:Army, Marine Corps, Navy, and Air Force ground personnel constitute the largest addressable demand pool for scalable plate carrier systems. United States Army PEO Soldier and Marine Corps Systems Command are fielding next-generation soldier protection systems with integrated power and data routing.
- Police Departments:Local and state law enforcement agencies balance budget constraints against officer safety mandates through standardized vest programs. Florida Department of Law Enforcement coordinates statewide procurement specifications that influence vendor product roadmaps.
- Security Firms:Private military contractors and corporate security providers operate outside military specification channels, creating demand for commercial-off-the-shelf platforms with rapid availability.
- Intelligence Agencies:Clandestine and protective operations units require low-visibility concealable systems with minimal signature.
- Emergency Responders:Fire-rescue and emergency medical personnel need ballistic protection compatible with turnout gear and medical equipment access.
Armed Forces handles the majority of throughput; Police Departments is gaining share fastest through consolidated purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Berry Amendment and parallel domestic content statutes across NATO member states are redirecting procurement toward captive fiber and ceramic manufacturing capacity. Military modernization programs in Eastern Europe and Indo-Pacific rim countries are accelerating plate carrier fielding timelines.
United States
Army PEO Soldier and Marine Corps Systems Command are consolidating orders around lightweight multi-curve plate designs. The Berry Amendment channels defense procurement toward domestic Kevlar spinning and ceramic pressing facilities. Domestic production clusters concentrate in Florida and Ohio, where Point Blank Enterprises and Safariland anchor military contract fulfillment.
Germany
Bundeswehr technical teams are validating silicone-based water-repellent chemistries to meet REACH Annex XVII restrictions on perfluorinated substances. The EU PPE Regulation CE marking requirements govern product admissibility for federal police and military channels. Industrial activity clusters in Bavaria and North Rhine-Westphalia, where armor integration facilities serve NATO interoperability specifications.
Poland
Regional security realignments are driving strategic stockpile rebuilding with NATO-standard plate carriers and ballistic helmets. Polish military procurement agencies are accelerating multi-hit capable plate orders rated against M2 AP ammunition. Manufacturing concentration centers on Warsaw and Krakow metropolitan areas, where domestic armor assembly capacity is expanding.
United Kingdom
British Army procurement offices are fielding helmet systems with integrated rail mounts and night vision shrouds. The UK follows EU PPE Regulation alignment post-Brexit through retained CE marking requirements. Defense industrial activity concentrates in the Midlands and South East England, where BAE Systems plc maintains protective systems engineering.
Sweden
NATO accession is triggering strategic stockpile establishment and domestic armor integration facility construction. Swedish defense procurement agencies are specifying Dyneema-based inserts for coastal and amphibious units under humid climate protocols. Industrial development centers on Stockholm and Gothenburg regions, where new supplier qualification programs are opening procurement windows.
Bulletproof Gear Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated fiber-ceramic manufacturers, specialized armor fabricators, and modular platform assemblers. DuPont de Nemours and Honeywell International represent captive fiber supply archetypes. Point Blank Enterprises and Safariland exemplify domestic production and modular platform differentiation respectively. Competitive moves center on backward integration into ceramic pressing capacity and strategic partnerships with defense logistics agencies.
Within the integrated materials tier, DuPont de Nemours, Inc. and Honeywell International Inc. anchor North American para-aramid and UHMWPE fiber supply. Point Blank Enterprises, Inc. represents the domestic fabrication archetype with concentrated military contract exposure. Safariland, LLC occupies a position emphasizing modular vest architectures for law enforcement channels. These three entities exemplify distinct competitive positioning vectors: captive raw material control, domestic production scale, and platform modularity specialization.
| Leading Market Players |
|---|
| Point Blank Enterprises, Inc. |
| Safariland, LLC |
| DuPont de Nemours, Inc. |
| Honeywell International Inc. |
| Avon Protection plc |
| BAE Systems plc |
| Armor Express |
| MKU Limited |
| 3M Ceradyne, Inc. |
| Others |
Pricing and Supply Chain Analysis
Chinese alumina and Ukrainian silicon carbide processors anchor raw material supply for ceramic strike faces, concentrating margin capture with integrated manufacturers possessing captive pressing capacity while fragmenting pricing power among pure-play armor fabricators dependent on spot procurement.
Pricing Analysis
Certification level creates the primary spread across product tiers, with NIJ Level IV plates commanding substantial premiums over Level III equivalents due to multi-hit testing requirements and extended laboratory validation timelines. Three-tier pricing structure across premium, standard, and economy levels reflects material composition—boron carbide strike faces for special operations, alumina-silicon carbide hybrids for conventional forces, and pure UHMWPE for training and rear-echelon applications. Cost compression in standard-grade ceramic plates is intensifying because Polish and Baltic military procurement agencies are consolidating orders around NATO-interoperable specifications, pressuring vendors to absorb certification overhead. Law enforcement agencies exhibit highest price sensitivity due to municipal budget cycles, while special operations units demonstrate lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Export controls on high-purity ceramic powders and gel-spun polyethylene fiber technology limit flows from Chinese and Dutch suppliers to non-allied defense contractors, forcing NATO-aligned manufacturers toward domestic spinning and pressing investments. Geographic supply concentration centers on China for alumina precursors, Ukraine for silicon carbide processing, and the Netherlands for Dyneema fiber production. Raw material dependencies encompass boron carbide for lightweight strike faces, para-aramid yarns for soft armor backing, and ultra-high molecular weight polyethylene for maritime-rated inserts. Single-source vulnerability runs through Ukrainian silicon carbide facilities exposed to regional conflict disruption. Distribution runs through Defense Logistics Agency e-commerce portals and multi-agency purchasing cooperatives, bypassing traditional prime-contractor relationships for unit-level requisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NATO expansion and armor-piercing threat escalation signal early-cycle expansion, with Swedish and Finnish accession triggering strategic stockpile establishment that extends procurement windows for qualified suppliers beyond traditional replacement cycles.
For Market Incumbents: Harden supply chain resilience through backward integration into ceramic pressing capacity in Ohio and Florida production clusters, insulating against Ukrainian raw material disruption. Deepen certification investment at NIJ-approved ballistics laboratories to compress 18-24 month approval timelines and freeze contract eligibility for emerging competitors. Anchor military relationships through domestic content compliance under the Berry Amendment while expanding modular platform architectures for law enforcement master service agreements.
For New Entrants and Emerging Players: State-level police purchasing cooperatives in Texas and California represent the most penetrable entry point, bypassing federal procurement barriers through standardized vest programs with shorter specification cycles. Swedish and Finnish NATO accession creates immediate demand for qualified armor integration facilities, opening procurement windows before incumbent supplier relationships solidify. Target go-to-market positioning around rapid customization capabilities for special operations units requiring mission-specific configurations outside centralized program office timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed armor fabricators lacking captive fiber or ceramic supply, presenting consolidation opportunities for integrated materials players seeking downstream channel control. Long-term viability favors manufacturers with in-house Kevlar spinning or UHMWPE gel-spinning capacity, as domestic content requirements harden across NATO procurement channels. Watch directed-energy countermeasure integration as the inflection signal—conductive mesh layer development indicates next-generation protection requirements that would obsolete pure-ballistic substrate specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Pressing Capacity Expansion | Captive alumina and silicon carbide processing insulates against Ukrainian supply disruption for NATO contracts. |
| NIJ Laboratory Certification Investment | Parallel testing facilities compress 18-24 month approval cycles and freeze new entrant contract eligibility. |
| Modular Platform Architecture Development | MOLLE-compatible vest systems align with Texas and California multi-agency purchasing cooperative requirements. |
| Directed-Energy Countermeasure Integration | Conductive mesh layer R&D addresses emerging laser threats in vehicle crew protection specifications. |
| Domestic Fiber Spinning Scale-Up | Berry Amendment compliance secures Army PEO Soldier and Marine Corps Systems Command contract access. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ballistic engineering directors, military procurement officers at Army PEO Soldier and Marine Corps Systems Command, NIJ certification laboratory managers, and state police equipment coordinators; and secondary validation against NIJ 0101.06 compliance databases, Defense Logistics Agency FedMall transaction records, SEC 10-K filings from integrated fiber manufacturers, and REACH Annex XVII regulatory filings. Bottom-up triangulation across product-type segmentation and top-down reconciliation against NATO defense expenditure disclosures anchored volume and value estimates.
Forecast inputs encompassed ceramic plate and UHMWPE composite adoption curves, military modernization program timelines across Polish and Baltic procurement agencies, and law enforcement vest replacement cycle compression. Segmentation dimensions modeled include material composition, threat level certification, end-user procurement channel, and geographic domestic content requirement clusters. CAGRs were derived from regression analysis of historical procurement data against threat escalation indicators and alliance expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations cycles or ceramic raw material export control enforcement would shift the trajectory. Forecasts reflect assumptions regarding NIJ laboratory capacity expansion and REACH alternative chemistry validation timelines. Material shifts in directed-energy weapon fielding or armor-piercing ammunition proliferation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market