
 Diving and Survival Equipment Market | 2026-2036
Diving and Survival Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Diving and Survival Equipment Market Outlook
Multi-source procurement for critical subsystems is realigning how original equipment manufacturers structure their supply bases. Aqua Lung International leverages integrated manufacturing in Europe to sustain quality control across regulator assemblies. Cressi Sub S.p.A. anchors its competitive stance through deep specialization in neoprene wetsuit engineering. Johnson Outdoors controls North American distribution channels for recreational diving equipment while competing on brand recognition in the survival segment.
Diving and survival equipment encompasses life-support systems, thermal protection garments, breathing apparatus, and flotation devices engineered to sustain human operators in submerged or hazardous environments; regulators must deliver breathable gas at depths exceeding 40 meters while maintaining inhalation resistance below specific thresholds. Neoprene dominates material selection for diving suits due to thermal insulation properties and established supply chains, while polyurethane gains traction in buoyancy compensators where abrasion resistance matters. The recreational diving category occupies the largest volume pool, though military operations command premium pricing through hardened specifications and extended service intervals.
ISO 12402 lifejacket standards and EN 250 breathing apparatus requirements shape product development timelines and testing expenditures for manufacturers serving European markets. The US Coast Guard and FAA impose parallel certification burdens on survival equipment destined for maritime and aviation applications, creating compliance complexity for multi-market suppliers. Stakeholders must monitor how evolving decompression algorithms and closed-circuit rebreather technologies reshape training protocols and equipment replacement cycles.
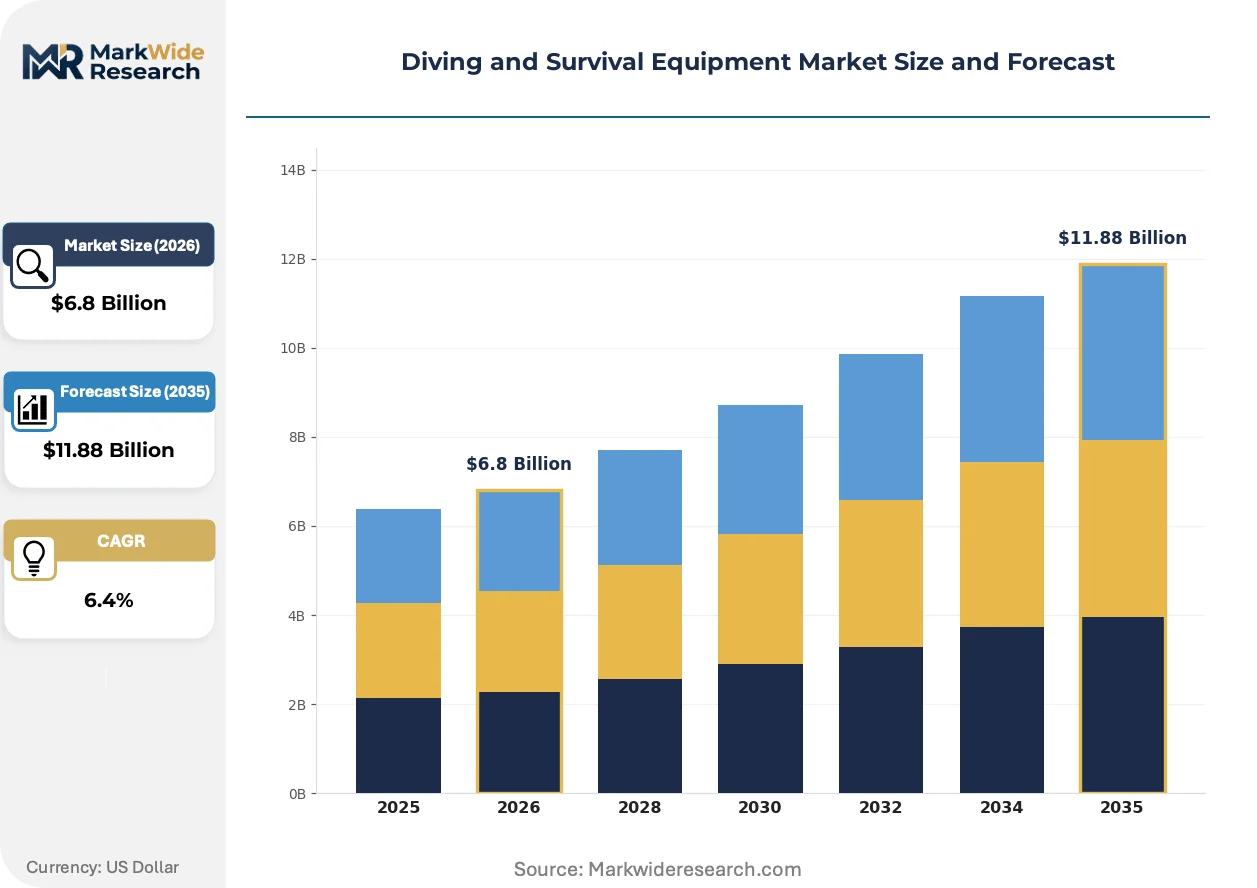
Market Dynamics
Fleet renewal programs among commercial diving contractors are compressing equipment replacement cycles while ISO 12402 and EN 250 certification tightening in Europe forces manufacturers to retest entire product lines. This dual pressure from demand-side capital deployment and regulatory stringency defines current market motion.
Growth Catalysts
- Offshore Energy Expansion:Southeast Asian offshore oil and gas development in Indonesian and Vietnamese waters drives demand for saturation diving systems and atmospheric diving suits.
- EN 250 Certification Mandates:European breathing apparatus standards now require extended cold-water performance testing, forcing product upgrades across regulator portfolios.
- Marine Tourism Convergence:Thailand and Philippines dive resort clusters are professionalizing instructor equipment standards, expanding certified gear procurement volumes.
Market Restraints
- Neoprene Supply Concentration:Japanese and South Korean neoprene sheet manufacturers control over 70% of premium-grade supply for diving suits, creating input vulnerability.
- FAA Certification Burden:Aviation survival equipment faces parallel US Coast Guard and FAA approval requirements, extending time-to-market by 18-24 months for multi-application suppliers.
- Closed-Circuit Rebreather Complexity:Technical training infrastructure limitations restrict adoption of advanced life-support systems outside military and scientific segments.
Strategic Opportunities
- India Coastal Infrastructure:Sagarmala port development and submarine cable laying programs create first-mover positioning for commercial diving contractors.
- EU Green Deal Procurement:Public sector vessel operators must source recyclable flotation materials by 2027, opening substitution windows for bio-based foam developers.
- Direct-to-Professional Channels:E-commerce platforms serving dive instructors and commercial supervisors are bypassing traditional distribution markups in Australia and Brazil.
Industry Challenges
- Hyperbaric Welding Certification:Pipeline inspection contractors face acute shortages of divers qualified to AWS D3.6 underwater welding standards.
- Legacy System Integration:Military operators struggle to interface modern rebreather electronics with existing vessel life-support monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diving and Survival Equipment Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Diving Suits, Buoyancy Compensators, Regulators, Tanks Material: Neoprene, Nylon, Polyurethane, PVC Usage Scenario: Recreational Diving, Commercial Diving, Search and Rescue, Military Operations Certification Standard: ISO 12402, EN 250, CE Marking, ISO 9001 |
| Companies Covered | Aqua Lung International, Johnson Outdoors, Cressi Sub S.p.A., Mares S.p.A., Scubapro, Huish Outdoors, Beuchat International, TUSA, Sherwood Scuba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diving and Survival Equipment Market Strategic Shifts
Material science advances and regulatory digitization are compressing product development timelines while reshaping how buyers evaluate equipment lifecycles. Three developments dominate this transition.
Closed-circuit rebreather technology is rewriting competitive positioning in technical diving segments. These systems recycle exhaled gas through chemical scrubbers, extending dive durations by factors of three to five compared to open-circuit apparatus. Military special operations units and cave exploration teams in Mexico and Florida are driving adoption, forcing traditional regulator manufacturers to acquire or partner for rebreather capability.
REACH chemical registration in Europe is forcing material substitutions across neoprene and polyurethane supply chains. The restriction of certain chloroprene processing aids requires reformulation of diving suit laminates at higher cost. Manufacturers serving German and French markets are accelerating bio-based rubber testing to preempt further substance bans.
Subscription-based equipment refresh programs are displacing outright purchase models among commercial diving contractors. Fleet operators in Norwegian and UK North Sea operations now lease regulators and buoyancy compensators with mandatory 18-month replacement cycles. This shifts capital burden to manufacturers while locking in multi-year revenue streams.
Diving and Survival Equipment Market Segmentation
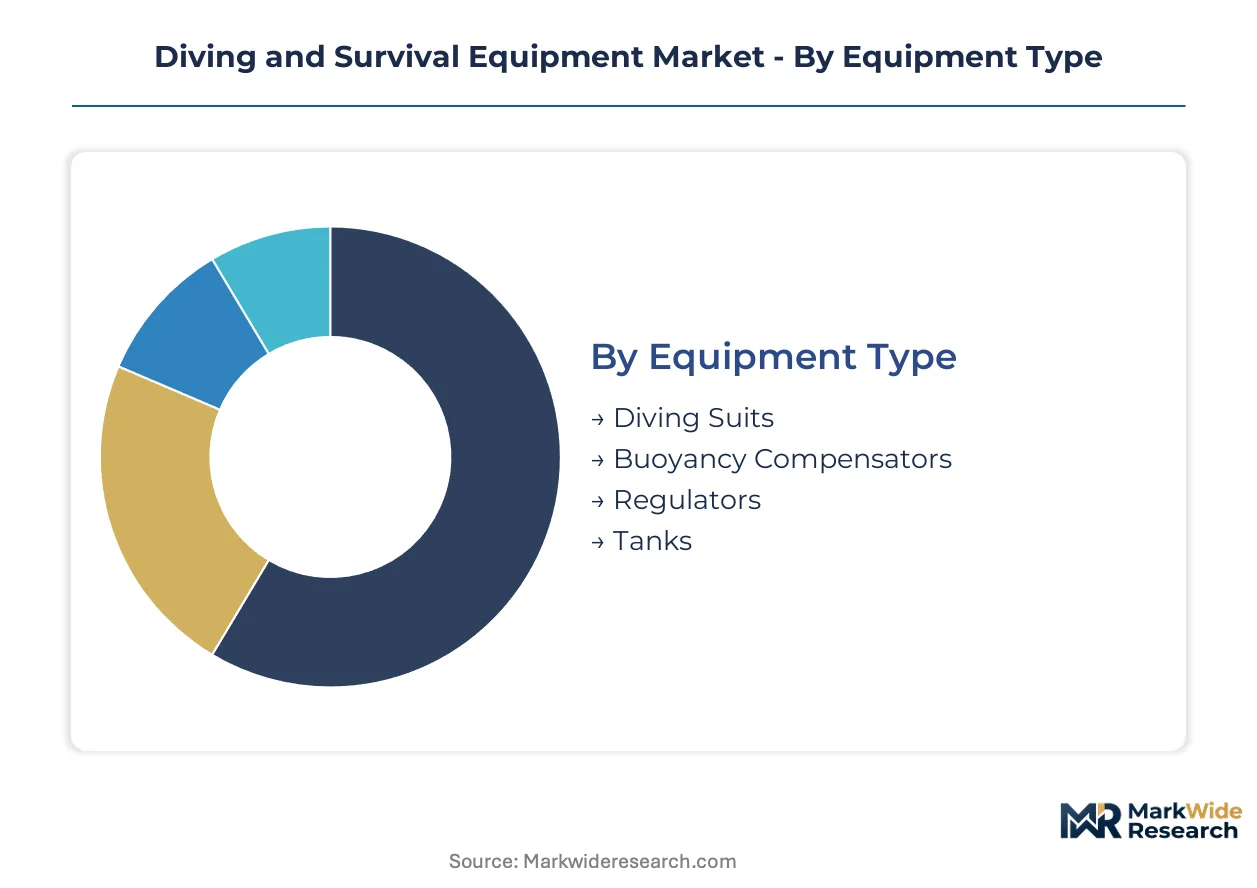
Segmentation in diving and survival equipment reveals how technical specifications, material properties, and certification requirements create distinct procurement patterns across professional and recreational user bases. Equipment buyers prioritize different performance thresholds depending on depth ratings, thermal protection needs, and regulatory compliance burdens.
Equipment Type:
Technical performance specifications and depth ratings differentiate procurement priorities across the four equipment categories.
- Diving Suits:Neoprene or membrane constructions provide thermal insulation across water temperature ranges from tropical to polar conditions. Military saturation diving programs in Norway and commercial shellfish harvesters in British Columbia drive demand for crushed neoprene and trilaminate drysuit configurations.
- Buoyancy Compensators:Bladder-and-harness systems manage ascent control and trim positioning through integrated weight pockets and rapid-dump valves. Technical diving schools in Florida and cave exploration teams in Mexico's Yucatán Peninsula are upgrading to backplate-and-wing configurations with redundant bladder designs.
- Regulators:First and second stage assemblies reduce high-pressure tank contents to ambient pressure for safe inhalation. EN 250 cold-water certification mandates are forcing retooling of entire product lines for European distribution.
- Tanks:Aluminum and steel cylinders store compressed breathing gas at pressures up to 300 bar. Rental fleets at Thailand dive resorts favor aluminum for corrosion resistance in saltwater environments.
Diving suits lead on scale; buoyancy compensators lead on momentum as technical diving professionalizes instructor equipment standards.
Material:
Cost tiers and supply chain concentration shape material selection tradeoffs between performance and procurement risk.
- Neoprene:Closed-cell chloroprene rubber delivers thermal insulation through trapped nitrogen gas bubbles. Japanese and South Korean sheet manufacturers control premium-grade supply, creating input vulnerability for European wetsuit assemblers.
- Nylon:Woven polyamide fabrics reinforce drysuit shells and BCD outer layers against abrasion. REACH chemical registration is forcing reformulation of laminate adhesives at higher cost for German and French markets.
- Polyurethane:Thermoplastic elastomers provide abrasion resistance in BCD bladders and hose sheathing. Bio-based polyurethane testing is accelerating to preempt further substance bans under EU Green Deal procurement timelines.
- PVC:Cost-competitive vinyl compounds serve entry-level snorkel gear and flotation device shells. Environmental scrutiny is restricting PVC applications in public sector vessel tenders.
Neoprene leads on scale; polyurethane leads on momentum as bio-based substitution windows open.
Usage Scenario:
Application-specific duty cycles and safety margins drive divergent equipment specifications across four operational contexts.
- Recreational Diving:Open-circuit scuba systems with conservative depth limits dominate resort-based instruction and leisure travel. Dive resort clusters in Thailand and the Philippines are professionalizing instructor equipment standards, expanding certified gear procurement volumes.
- Commercial Diving:Surface-supplied and saturation systems support offshore construction, inspection, and maintenance at depths exceeding 50 meters. Fleet renewal programs among North Sea contractors are compressing equipment replacement cycles.
- Search and Rescue:Rapid-deployment surface and shallow-water apparatus prioritizes portability and intuitive operation. Coast guard units in Australia and Brazil are standardizing on modular systems with cross-compatible components.
- Military Operations:Hardened specifications and extended service intervals command premium pricing through closed-circuit rebreather and atmospheric diving suit procurement. Special operations units are driving adoption of electronic rebreather controls.
Recreational diving leads on scale; commercial diving leads on momentum as offshore energy expansion accelerates in Southeast Asian waters.
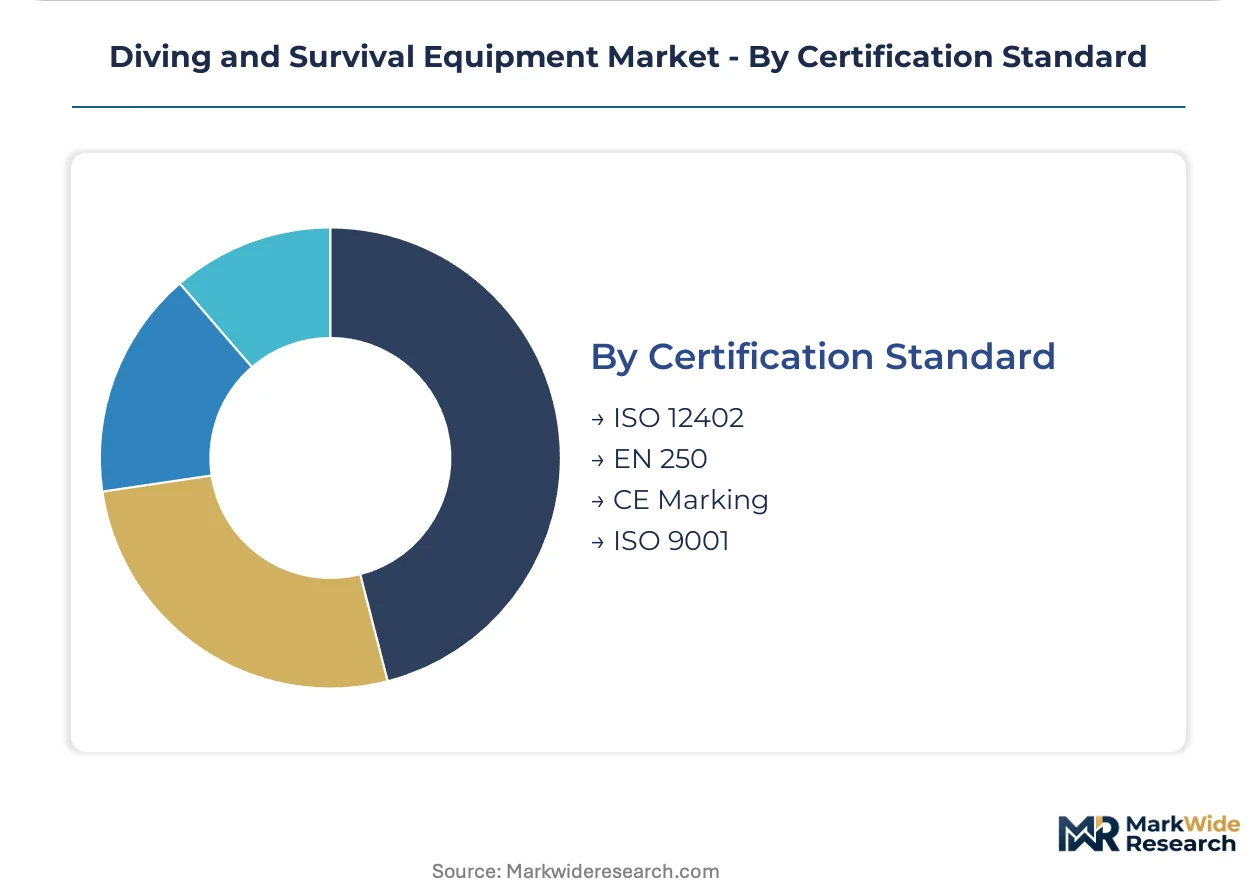
Certification Standard:
Geographic market access depends on alignment with regional testing protocols and quality management requirements.
- ISO 12402:Lifejacket and personal flotation device standards specify buoyancy retention, freeboard, and self-righting performance. Public sector vessel operators in EU member states must source recyclable flotation materials by 2027.
- EN 250:European breathing apparatus requirements now mandate extended cold-water performance testing, forcing product upgrades across regulator portfolios. Certification tightening is retesting entire product lines for manufacturers serving European markets.
- CE Marking:Conformity assessment for EU market access covers mechanical safety, pressure equipment, and electromagnetic compatibility. Parallel US Coast Guard approval requirements extend time-to-market for multi-application suppliers.
- ISO 9001:Quality management system certification supports supplier qualification for military and commercial diving contractor procurement. Subscription-based equipment refresh programs in Norwegian North Sea operations now mandate 9001-certified manufacturing.
CE Marking leads on scale; ISO 12402 leads on momentum as sustainability procurement mandates reshape material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea diving contractor cluster compresses equipment replacement cycles as fleet renewal programs accelerate. Southeast Asian offshore energy development and marine tourism convergence reshape procurement volumes. Regulatory tightening across multiple jurisdictions forces manufacturers to retest product lines for regional market access.
Norway
North Sea saturation diving contractors drive demand for atmospheric diving suits and hyperbaric life-support systems. The Norwegian Maritime Authority enforces strict equipment inspection protocols for offshore petroleum operations. Stavanger and Bergen harbor clusters concentrate commercial diving contractor headquarters and equipment staging facilities.
United Kingdom
Offshore wind farm construction and decommissioning programs expand commercial diving requirements in UK waters. The Health and Safety Executive mandates compliance with Diving at Work Regulations for all professional subsea operations. Aberdeen maintains its position as the primary North Sea diving contractor equipment procurement hub.
Indonesia
Offshore oil and gas development in the Java Sea and Makassar Strait drives saturation diving system demand. The national energy regulator imposes local content requirements on foreign diving contractors operating in Indonesian waters. Balikpapan and Jakarta serve as equipment distribution nodes for Southeast Asian offshore energy projects.
Thailand
Dive resort professionalization and instructor certification upgrades expand recreational equipment procurement volumes. The Tourism Authority of Thailand partners with equipment manufacturers to standardize resort-based diving safety protocols. Phuket and Koh Tao island clusters concentrate dive instructor training centers and certified gear distribution channels.
Germany
REACH chemical registration and EU Green Deal procurement mandates force material substitutions in neoprene and polyurethane supply chains. The Federal Maritime and Hydrographic Agency enforces CE marking conformity for life-support equipment entering German ports. Hamburg and Bremen harbor logistics networks handle European distribution for diving equipment manufacturers.
Diving and Survival Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue rebreather technology partnerships and bio-based material development. The vendor base spans integrated manufacturers with captive European production, specialized neoprene engineering houses, and North American distribution channel controllers. Three archetypes dominate: quality-anchored European fabricators, Asia-Pacific volume suppliers, and multi-segment outdoor recreation conglomerates. Competitive motion centers on subscription-based equipment refresh programs and regulatory-driven product line retesting investments.
Among European integrated manufacturers, Aqua Lung International anchors quality-control positioning across regulator assemblies. Cressi Sub S.p.A. exemplifies deep specialization in neoprene wetsuit engineering archetypes. Johnson Outdoors occupies a position controlling North American recreational distribution channels while competing on brand recognition in adjacent survival segments.
| Leading Market Players |
|---|
| Aqua Lung International |
| Johnson Outdoors |
| Cressi Sub S.p.A. |
| Mares S.p.A. |
| Scubapro |
| Huish Outdoors |
| Beuchat International |
| TUSA |
| Sherwood Scuba |
| Others |
Value Chain & Pricing Dynamics
Commercial diving contractors in the North Sea and Southeast Asian offshore energy corridors concentrate procurement volumes, locking in subscription-based equipment refresh programs that shift capital burden to manufacturers while standardizing 18-month replacement cycles across regulator and buoyancy compensator portfolios.
Pricing Analysis
Input-cost pass-through from Japanese and South Korean neoprene sheet suppliers drives pricing adjustments across European wetsuit assemblers, with REACH chemical registration adding reformulation premiums. Pricing stratifies across military-grade hardened specifications, commercial EN 250-certified tiers, and recreational entry-level equipment. Cost compression in the recreational tier intensifies as dive resort clusters in Thailand and the Philippines consolidate procurement through direct-to-instructor e-commerce channels. Military operators show least price sensitivity due to extended service interval requirements and closed-circuit rebreather integration mandates.
Supply Chain Analysis
Workforce availability constraints in Italian and French neoprene lamination facilities limit output scaling despite demand acceleration from EU Green Deal procurement timelines. Manufacturing gravity centers on Japan and South Korea for premium-grade chloroprene sheet, Italy for wetsuit assembly, and Germany for regulator precision machining. Raw material dependencies span chloroprene rubber, bio-based polyurethane feedstocks, and aerospace-grade aluminum for tank cylinders. Single-source vulnerability concentrates in Japanese neoprene sheet supply controlling over 70% of premium-grade input. Distribution runs through Stavanger and Aberdeen harbor logistics for North Sea commercial contractors, with Phuket and Balikpapan serving Southeast Asian resort and offshore energy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as fleet renewal programs and EN 250 certification tightening compress replacement cycles toward premium-specification equipment with mandatory cold-water performance testing.
For Market Incumbents: Hedge neoprene supply concentration through backward integration into bio-based rubber testing or captive supply agreements with emerging European laminate producers. Defend positioning against rebreather technology entrants by acquiring electronic control system capabilities or partnering with military special operations suppliers. Prioritize certification investment in ISO 9001 quality management systems to qualify for Norwegian and UK North Sea subscription-based refresh programs. For New Entrants and Emerging Players: Closed-circuit rebreather electronic controls offer a technology-first wedge into the military and scientific segments where technical training infrastructure limitations have restricted incumbent penetration. Target India's Sagarmala port development and submarine cable laying programs as the most penetrable geography with first-mover positioning available for commercial diving contractors. Pursue direct-to-professional e-commerce channels in Australia and Brazil to bypass traditional distribution markups and capture dive instructor procurement volumes. For Investors and Strategic Acquirers: Outdoor recreation conglomerates with multi-segment brand portfolios are the most active acquirer in this space, seeking diving equipment assets to complement existing water sports and survival gear holdings. Over the 5-10 year viability window, acquisition targets should display integrated European manufacturing for quality control, established EN 250 and ISO 12402 certification portfolios, or rebreather technology partnerships with military procurement channels. Watch for inflection in closed-circuit rebreather training infrastructure expansion as the signal that technical diving adoption is crossing from military-scientific niches into commercial contractor segments.| Strategic Initiative | Industry Significance |
|---|---|
| EN 250 Certification Investment | Cold-water performance testing mandates force product line retooling for European market access. |
| Backward Integration into Bio-Based Materials | EU Green Deal procurement timelines by 2027 create substitution windows for recyclable flotation foam developers. |
| Subscription-Based Equipment Refresh Programs | Norwegian and UK North Sea fleet operators now lease regulators with mandatory 18-month replacement cycles. |
| Rebreather Technology Partnership | Military special operations units drive adoption of electronic controls, forcing traditional regulator manufacturers to acquire capability. |
| Direct-to-Professional E-Commerce Launch | Platforms serving dive instructors in Australia and Brazil bypass traditional distribution markups. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with commercial diving contractors, equipment procurement officers at offshore energy operators, dive resort operations managers, and regulatory affairs leads at certification bodies with secondary validation from EN 250 testing protocols, ISO 12402 documentation, customs trade data for neoprene sheet imports, and SEC filings from publicly traded outdoor recreation conglomerates. Bottom-up equipment shipment tracking and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon to documented fleet renewal cycles, regulatory implementation timelines, and material substitution windows across the analysis window. Segmentation dimensions modeled include equipment type, material composition, usage scenario, and certification standard with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle compression rates, offshore energy capital deployment patterns, and marine tourism professionalization trends. Industry-specific inputs incorporated decompression algorithm evolution and closed-circuit rebreather training infrastructure expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to neoprene supply disruption, REACH chemical registration expansion, and military procurement budget reallocation. Forecasts reflect documented assumptions around certification tightening implementation and offshore energy project sanctioning rates. Material deviation in neoprene supply concentration or EN 250 testing protocol amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Portable Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market