
 Global Guns Safes Market | 2026-2036
Global Guns Safes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Guns Safes Market Analysis
Modular safe configurations is recalibrating how buyers evaluate storage investments, shifting preference from single large vaults toward stackable, expandable units that adapt to collection size. Liberty Safe leverages its domestic manufacturing footprint to sustain short lead times on custom orders. American Security anchors its position through heavy-gauge steel construction and dealer network density across the American Southwest. Fort Knox Vaults differentiates via lifetime warranty programs and proprietary locking mechanisms.
A gun safe is a reinforced security container engineered from hardened steel plate, typically between 10-gauge and 7-gauge thickness, designed to resist forced entry, unauthorized access, and environmental damage to firearms and ammunition. Fireproof safes incorporate gypsum-based insulation layers rated for sustained high-temperature exposure, protecting contents during residential or commercial structure fires. Biometric safes represent the fastest-expanding product category as fingerprint recognition modules drop in cost and improve reliability. Steel dominates material selection for premium installations, while composite materials gain traction in portable and vehicle-mounted applications where weight reduction matters.
The United States Department of Justice maintains firearm safety device certification standards that manufacturers must satisfy for legal sale in multiple states, directly shaping product design minimums. The EU Firearms Directive imposes storage security requirements on member state gun owners, creating standardized demand for certified safes across Germany, France, and Italy. ISO 9001 quality management certification increasingly serves as a procurement filter for military and law enforcement contracts. Stakeholders must monitor evolving state-level safe storage legislation, as mandatory secure storage laws spread across additional American jurisdictions and European member states tighten enforcement protocols.
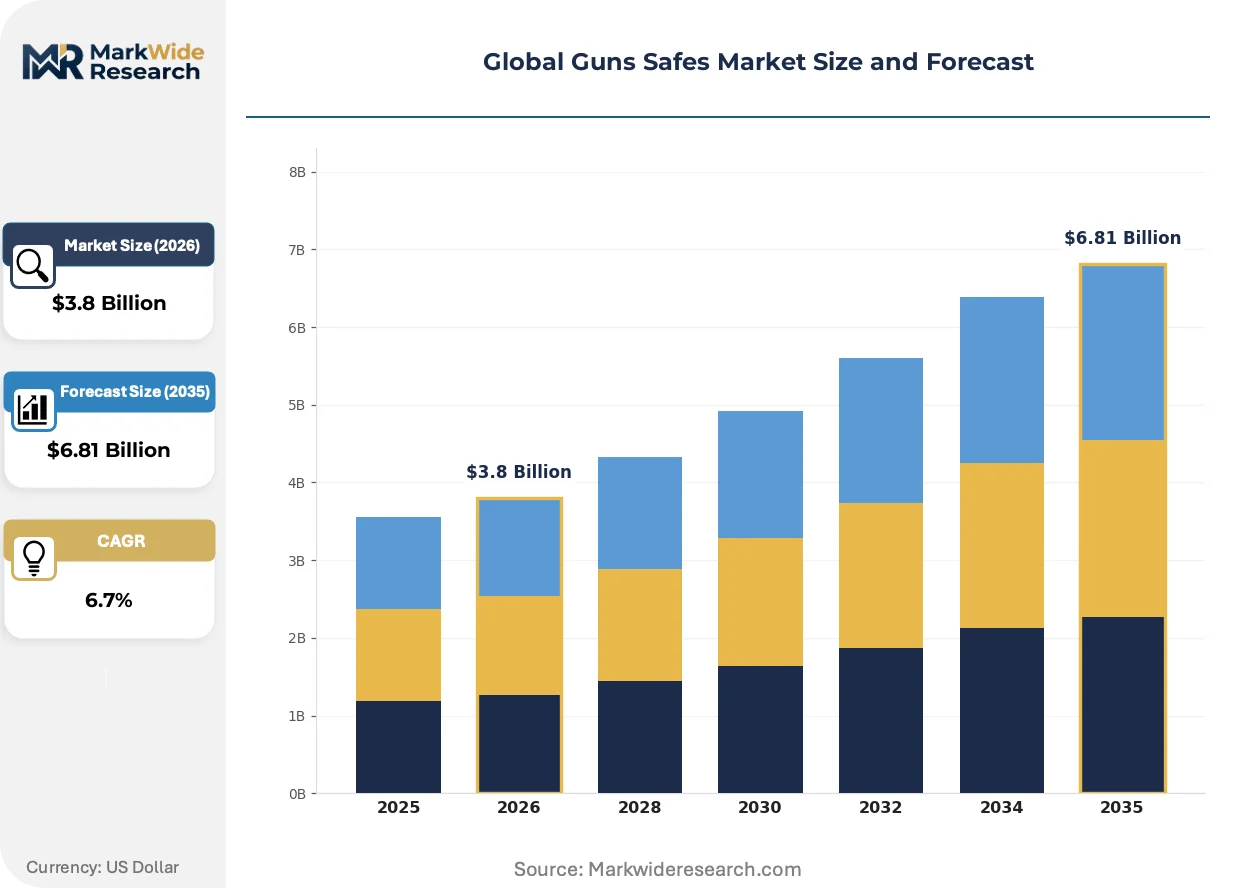
Market Dynamics
Modular safe configurations are absorbing buyer preference away from monolithic vaults, forcing manufacturers to retool production lines for stackable, expandable architectures that accommodate collection growth without full replacement.
Growth Catalysts
- California DOJ certification mandates:Tightening firearm safety device requirements in the most populous US state are pulling certified safe sales upward as retailers stock compliant inventory preemptively.
- NATO military procurement expansion:Secure weapons storage contracts across member defense ministries are creating institutional demand for hardened, tamper-evident container systems with audit trail capabilities.
- Fingerprint recognition cost collapse:Biometric module prices have fallen below threshold levels, enabling mass-market biometric safes that previously served only premium residential buyers.
Market Restraints
- Steel input volatility:Cold-rolled steel prices fluctuate with energy costs and scrap availability, compressing margin predictability for manufacturers committed to heavy-gauge construction.
- China supply concentration:Electronic lock mechanisms and biometric sensors concentrate production in Shenzhen and Dongguan corridors, exposing lead time risk during trade friction or logistics disruption.
- Weight-to-security tradeoff:Portable safe demand for vehicle mounting conflicts with theft-resistance ratings, limiting product performance in the fastest-growing mobility segment.
Strategic Opportunities
- German residential compliance gap:EU Firearms Directive enforcement remains uneven across German Länder, creating first-mover advantage for certified safe distributors as storage inspections intensify.
- Subscription monitoring services:Connected safes with cellular tamper alerts and humidity monitoring represent recurring revenue potential beyond one-time hardware sales.
- Insurance premium linkage:Underwriters in Australia and Canada are beginning to discount homeowner policies for documented safe storage, converting compliance into direct consumer savings.
Industry Challenges
- Cyber-physical integration complexity:Smart safe development requires firmware security expertise foreign to legacy metal fabrication shops, forcing partnership or acquisition strategies.
- Multi-jurisdiction certification backlog:California DOJ, ISO 9001, and EU type-approval processes run on non-aligned timelines, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Guns Safes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Safes, Fireproof Safes, Portable Safes, Wall Safes Material: Steel, Aluminum, Composite, Plastic End User: Private Consumers, Law Enforcement, Military, Retailers Installation Type: Floor Mounted, Wall Mounted, Free Standing, Vault |
| Companies Covered | Liberty Safe, American Security, Fort Knox Vaults, Cannon Safe, Stack-On Products, SentrySafe, Barska, SnapSafe, Winchester Safes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Guns Safes Market Emerging Trajectories
Product architecture is fragmenting into three distinct performance tiers as biometric commoditization meets hardened steel premium positioning, while regulatory pressure forces connected audit capabilities into mid-market offerings.
Biometric fingerprint recognition is absorbing the access-control function previously served by mechanical combination locks and keypad entry systems. First-time gun owners in suburban United States markets are adopting biometric safes at rates exceeding mechanical alternatives by substantial margins. This shift is compressing the addressable market for traditional lock manufacturers while expanding total accessible market for consumer electronics suppliers entering the security hardware space.
REACH substance restrictions on hexavalent chromium plating are forcing European manufacturers toward zinc-nickel or powder-coat finishes for corrosion resistance. The industrial consequence is elevated surface treatment costs and supply chain qualification requirements for coating chemical suppliers. German and Italian safe producers are responding by vertically integrating finishing operations to maintain quality consistency and regulatory documentation.
Residential buyers are consolidating purchase decisions around insurance-adjacent certification tiers rather than independent security research. This behavior shift is displacing independent dealer consultation with direct-to-consumer e-commerce channels featuring side-by-side compliance badge comparison. The pattern is most visible in United States markets where homeowner policy riders explicitly reference Underwriters Laboratories or California DOJ certification levels as premium discount thresholds.
Global Guns Safes Market Segmentation
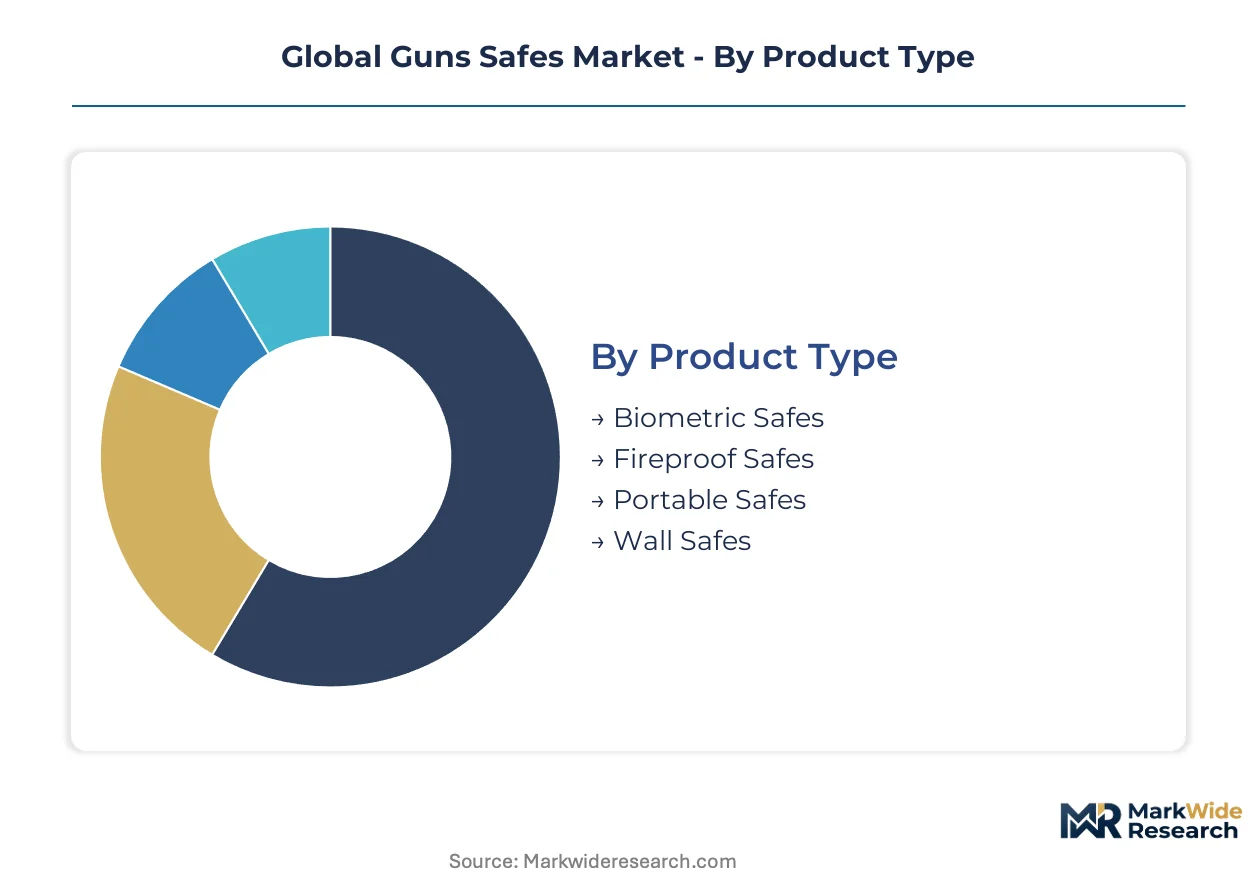
Gun safe purchasing decisions split across access technology, material durability, institutional versus residential use, and physical mounting constraints. Each segmentation axis carries distinct certification requirements and margin profiles that reshape competitive positioning.
Product Type:
Volume concentration favors legacy mechanical and electronic keypad units, while premium capture shifts toward biometric and fire-rated configurations with connected monitoring capabilities.
- Biometric Safes:Fingerprint recognition modules authenticate users through capacitive or optical sensors with sub-second response times. Residential buyers in suburban United States markets are adopting biometric units at rates exceeding mechanical alternatives, driven by California DOJ certification alignment and first-time gun owner preference for rapid access.
- Fireproof Safes:Gypsum-based insulation layers rated for sustained high-temperature exposure protect contents during residential structure fires. Demand concentrates among collectors and competitive shooters storing high-value firearms, with insurance premium discounts in Australia and Canada reinforcing specification priority.
- Portable Safes:Vehicle-mounted units prioritize weight reduction over theft-resistance ratings, creating performance compromises in the mobility segment.
- Wall Safes:Recessed installation between wall studs offers concealment advantages with reduced capacity versus freestanding alternatives.
Mature deployment sits with fireproof and wall-mounted units. Newer deployment is concentrated in biometric configurations with cellular connectivity and tamper alerts.
Material:
Cost tiering separates heavy-gauge steel premium positioning from aluminum and composite economy offerings, with regulatory pressure on surface treatments reshaping European supply chains.
- Steel:Cold-rolled plate between 10-gauge and 7-gauge thickness dominates premium installations for forced-entry resistance. NATO military procurement programs specify hardened steel construction with tamper-evident audit capabilities, anchoring institutional demand.
- Composite:Fiber-reinforced polymer matrices reduce weight for portable and vehicle-mounted applications where mobility outweighs absolute security ratings. REACH substance restrictions on hexavalent chromium plating are forcing German and Italian producers toward zinc-nickel finishes.
- Aluminum:Corrosion-resistant extrusions serve marine and high-humidity environments with moderate security requirements.
- Plastic:Injection-molded housings address lowest-cost segments with minimal theft-resistance certification.
Specification priority clusters in steel for institutional and high-value residential storage. Composite materials are gaining share fastest in mobility-optimized product lines.
End User:
Customer type determines procurement channel, with private consumers driving modular configurations and institutional buyers mandating connected audit capabilities.
- Private Consumers:Residential buyers consolidate decisions around insurance-adjacent certification tiers rather than independent security research, displacing dealer consultation with direct-to-consumer e-commerce channels featuring compliance badge comparison.
- Military:Defense ministries across NATO member states require hardened container systems with tamper-evident logging and chain-of-custody documentation, creating multi-year contract visibility for qualified suppliers.
- Law Enforcement:Agency procurement filters on ISO 9001 quality management certification with evidence-handling protocol alignment.
- Retailers:Commercial inventory storage demands scale configurations with master-key override systems and dual-access controls.
Contract stability sits with military and law enforcement procurement. Volume expansion is concentrating in private consumer channels as mandatory secure storage legislation spreads across American state jurisdictions.
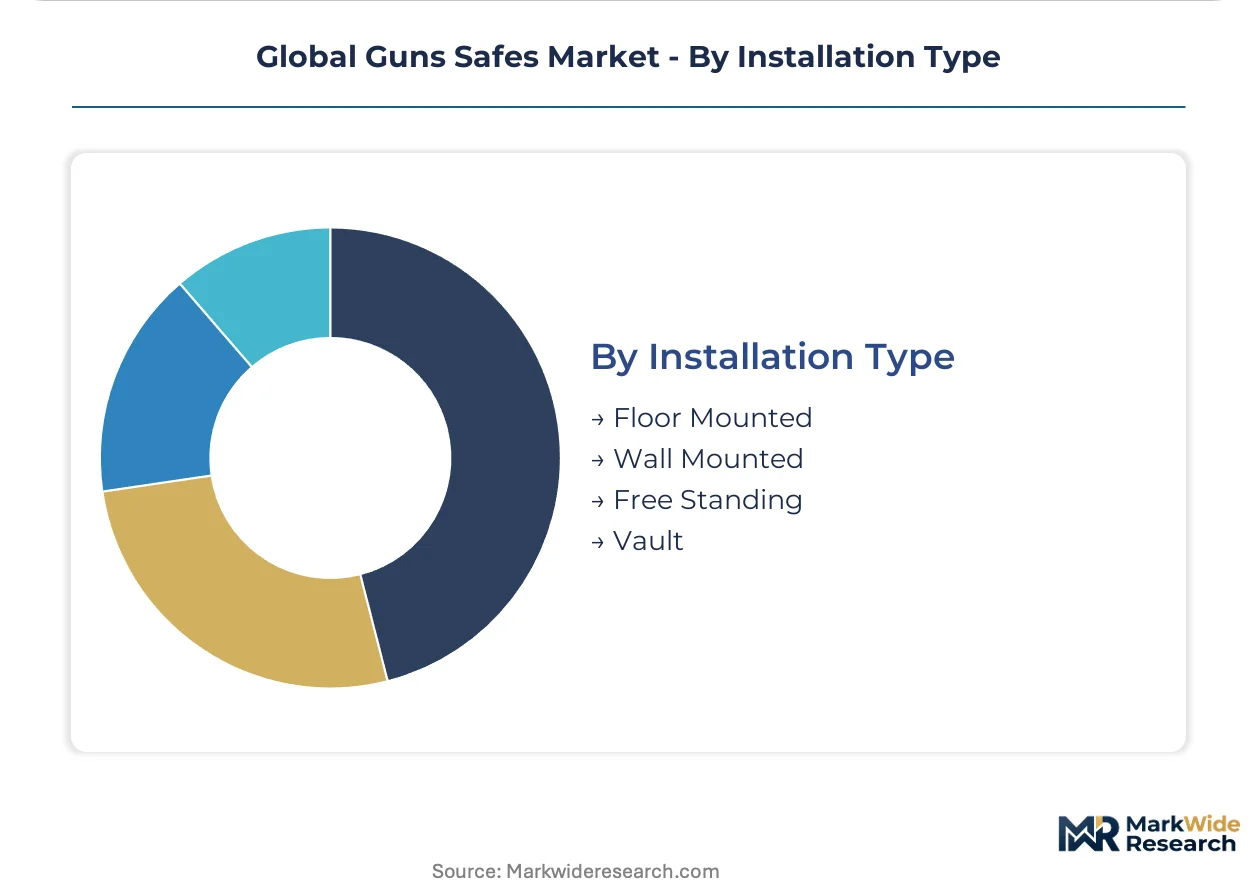
Installation Type:
Physical mounting constraints reshape product architecture, with floor and vault installations anchoring premium positioning while wall configurations address space-constrained residential environments.
- Vault:Dedicated room-scale installations with reinforced concrete envelopes and climate control systems serve high-volume collectors and institutional armories. German residential compliance gaps under EU Firearms Directive enforcement are creating first-mover advantage for certified vault distributors as storage inspections intensify.
- Free Standing:Modular stackable units accommodate collection growth without full replacement, absorbing buyer preference away from monolithic vaults and forcing production line retooling.
- Floor Mounted:Bolt-down configurations resist tipping and removal, satisfying insurance requirements for documented secure storage.
- Wall Mounted:Recessed installation preserves floor space in urban residential environments with limited square footage.
Established infrastructure sits with floor-mounted and vault installations. Configuration innovation is concentrating in freestanding modular architectures with expandable capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the United States and China, while consumption spreads across NATO defense ministries and residential buyers in jurisdictions tightening storage mandates.
United States
California DOJ certification requirements pull compliant inventory through retail channels nationwide, with suburban first-time gun owners adopting biometric configurations at accelerating rates. The Department of Justice maintains firearm safety device standards that shape product design minimums across state lines. Production clusters in the American Southwest leverage dealer network density for rapid custom order fulfillment.
Germany
EU Firearms Directive enforcement remains uneven across Länder, creating first-mover advantage for certified safe distributors as storage inspections intensify. REACH substance restrictions on hexavalent chromium plating force producers toward zinc-nickel finishes with elevated surface treatment costs. Industrial concentration in Baden-Württemberg anchors finishing operations to maintain quality consistency and regulatory documentation.
China
Shenzhen and Dongguan corridors concentrate electronic lock mechanism and biometric sensor production, exposing lead time risk during trade friction or logistics disruption. GB standards and MIIT oversight shape domestic manufacturing protocols for security hardware exports. Yangtze River Delta fabricators supply NATO military procurement programs with hardened container systems requiring tamper-evident audit capabilities.
Australia
Underwriters certification tiers convert compliance into direct consumer savings as insurers discount homeowner policies for documented safe storage. The country's national firearms regulator enforces storage security requirements that standardize demand for certified safes across state jurisdictions. New South Wales and Victoria residential markets consolidate purchase decisions around insurance-adjacent certification rather than independent security research.
Canada
Homeowner policy riders referencing certification levels as premium discount thresholds reshape buyer behavior toward direct-to-consumer e-commerce channels. Health Canada oversight aligns with provincial firearms storage regulations creating multi-jurisdiction compliance frameworks. Ontario and British Columbia concentrate retail distribution for modular stackable units accommodating collection growth without full replacement.
Global Guns Safes Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three performance tiers as biometric commoditization meets hardened steel premium positioning. The vendor base organizes around domestic manufacturing footprint advantages, heavy-gauge construction specialization, and proprietary locking mechanism differentiation. Strategic archetypes include scale-driven mass-market suppliers, premium custom fabricators, and technology-integrated smart safe developers. Competitive moves concentrate on production line retooling for modular architectures and partnership strategies addressing cyber-physical integration complexity.
Within the premium custom fabrication tier, Liberty Safe and Fort Knox Vaults exemplify archetypes built on domestic manufacturing positioning and warranty-backed differentiation. American Security anchors the heavy-gauge construction specialization vector. These three entities represent distinct competitive approaches: short lead time customization, lifetime warranty programs with proprietary mechanisms, and dealer network density across high-demand geographies. Their collective positioning illustrates how certification alignment and regional compliance expertise create defendable market presence.
| Leading Market Players |
|---|
| Liberty Safe |
| American Security |
| Fort Knox Vaults |
| Cannon Safe |
| Stack-On Products |
| SentrySafe |
| Barska |
| SnapSafe |
| Winchester Safes |
| Others |
Supply Flow & Price Mechanics
Backward integration into surface treatment operations anchors both supply security and pricing power for European manufacturers confronting REACH substance restrictions on hexavalent chromium plating. This upstream control over finishing processes insulates margin structures from coating chemical volatility while enabling premium positioning through regulatory documentation.
Pricing Analysis
Margin tightening in mid-market biometric configurations reflects fingerprint module commoditization and Chinese supplier price aggression. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels separates buyers by California DOJ certification status and insurance-recognized Underwriters Laboratories ratings. Cost compression accelerates in electronic lock mechanisms as Shenzhen corridor production scales. Private consumers in United States suburban markets exhibit highest price sensitivity, while NATO military procurement programs demonstrate lowest sensitivity due to multi-year contract visibility and tamper-evident audit requirements.
Supply Chain Analysis
Dual-sourcing requirements from defense ministries and large retail chains mandate qualified secondary suppliers for electronic lock mechanisms and biometric sensors. Manufacturing concentrates in United States domestic fabricators, Chinese Yangtze River Delta electronics clusters, and German Baden-Württemberg finishing operations. Cold-rolled steel plate, gypsum-based fireproofing insulation, and capacitive fingerprint sensors constitute critical input dependencies. Single-source vulnerability concentrates in Shenzhen and Dongguan corridors for biometric modules. Distribution runs through dealer networks in American Southwest, direct-to-consumer e-commerce channels, and institutional procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where California DOJ firearm safety device certification creates a barrier-to-entry moat for players with preemptive regulatory investment.
For Market Incumbents: Deploy certification portfolio expansion to capture emerging state-level mandatory storage legislation before competitors complete testing cycles. Anchor defensive positioning through captive supply of electronic lock mechanisms to reduce Dongguan corridor exposure. Deepen dealer network density across American Southwest and Pacific Northwest where residential demand concentrates. Threat substitution from smart home security ecosystems demands firmware security partnership strategies. For New Entrants and Emerging Players: Biometric-first product architecture offers white-space penetration in German Länder where EU Firearms Directive enforcement intensifies unevenly. Target Australian residential markets where insurer premium discounts convert compliance into direct consumer savings. Vehicle-mounted portable safes present underdeveloped mobility segment opportunity. Go-to-market angle should emphasize subscription monitoring services with cellular tamper alerts for recurring revenue beyond hardware. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified security hardware conglomerates seeking biometric technology integration. Long-term viability favors players with domestic manufacturing footprints and multi-jurisdiction certification alignment. Acquisition target archetype: mid-cap specialists with California DOJ approval and ISO 9001 quality management certification. Signal to watch is mandatory secure storage law passage in additional United States state jurisdictions triggering inventory preloading at retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | California DOJ approval unlocks preemptive retail inventory positioning before state mandates spread. |
| Biometric Module Partnership | Shenzhen supplier alliances reduce lead time exposure during trade friction or logistics disruption. |
| Subscription Monitoring Launch | Cellular tamper alerts and humidity monitoring convert one-time hardware sales into recurring revenue streams. |
| Dealer Network Density Build | American Southwest concentration enables rapid custom order fulfillment and short lead time competitive differentiation. |
| Surface Treatment Vertical Integration | In-house zinc-nickel finishing insulates European manufacturers from REACH compliance cost volatility. |
Methodological Framework
Multi-period observation of California DOJ certification timelines, NATO military procurement award patterns, and biometric module cost curves anchored the trend analysis, supplemented by interviews with safe manufacturing plant managers, firearms retailer procurement leads, defense ministry contracting officers, and insurance underwriters writing homeowner policy riders. Secondary validation drew from United States Department of Justice firearm safety device registry data, EU Firearms Directive implementation reports, customs trade records for cold-rolled steel plate, and SEC filings from diversified security hardware conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across access technology, material durability, and end-user segments.
Segment-weighting approaches applied differential growth assumptions to biometric configurations versus legacy mechanical units, with fire-rated and portable categories receiving distinct trajectory parameters. Modeled dimensions spanned access technology, material gauge thickness, institutional versus residential end use, and physical mounting constraints. CAGRs derived from fitted trend lines applied to historical shipment data and projected regulatory enforcement intensification. Industry-specific forecast inputs included California DOJ certification backlog durations and NATO member state defense budget allocation patterns for secure weapons storage.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Chinese electronic component flows, unforeseen regulatory reciprocity agreements between United States and EU certification regimes, and breakthrough lightweight composite materials displacing steel in premium installations. Forecasts reflect documented assumptions about biometric sensor cost decline rates and state-level legislative diffusion patterns. A model refresh is warranted upon material change in United States state-level mandatory secure storage law passage velocity or NATO defense procurement contract award timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market