
 Cargo Security Seals Market | 2026-2036
Cargo Security Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Security Seals Market Outlook
Premium electronic and RFID-enabled cargo security seals is decoupling from commodity plastic and metal bolt variants on a performance and pricing basis. TydenBrooks leverages embedded tracking technology to command higher margins in pharmaceutical cold chain applications. Mega Fortris anchors its position through backward integration into zinc-alloy casting for high-strength bolt seals. American Casting & Manufacturing Corporation competes on manufacturing scale across standardized container security products.
Cargo security seals are mechanical or electromechanical devices manufactured from ABS plastics, zinc alloys, or galvanized steel cable, designed to provide tamper-evident closure and unique identification for transport containers, trucks, and warehouse facilities. ISO 17712 compliance mandates specific shear strength, bending resistance, and impact tolerance thresholds for international container movements. Metal seals and cable seals dominate container security applications due to superior tensile strength, while plastic seals lead in truck and last-mile logistics where cost sensitivity prevails. RFID-enabled electronic seals represent the fastest-growing segment as shipping companies integrate real-time tracking into fleet management systems.
FDA traceability rules for pharmaceutical shipments, EPA hazardous materials transport requirements, and ISO 17712 customs security standards collectively shape product design and certification pathways for seal manufacturers. The EU Green Deal packaging directives and REACH material restrictions are pressuring suppliers to eliminate heavy metal content and adopt recycled polymer feedstocks. Stakeholders must monitor evolving customs-to-carrier data interoperability standards as regulatory fragmentation between ISO, C-TPAT, and EU AEO programs creates compliance complexity for multinational seal deployments.
Market Dynamics
RFID-integrated seal technologies are compressing replacement cycles for legacy mechanical seals across intermodal networks, forcing manufacturers to reconfigure product portfolios around real-time tracking capabilities.
Growth Catalysts
- ISO 17712 certification mandates:Customs authorities in the United States, Germany, and China now require tamper-evident seals meeting specific shear strength and bending resistance thresholds for international container movements, eliminating non-compliant suppliers from procurement pools.
- Pharmaceutical cold chain expansion:FDA traceability rules for temperature-sensitive drug shipments are driving demand for electronic seals with embedded environmental sensors across North American distribution networks.
- Port security modernization programs:Accelerated infrastructure investments in Rotterdam, Singapore, and Los Angeles are replacing legacy bolt seals with RFID-enabled alternatives capable of automated gate clearance.
Market Restraints
- Zinc alloy input cost volatility:Mega Fortris and other bolt seal manufacturers face margin compression from fluctuating zinc prices, which directly impacts high-strength metal seal production economics.
- REACH material restrictions:EU Green Deal packaging directives are pressuring suppliers to eliminate heavy metal content and adopt recycled polymer feedstocks, complicating existing ABS plastic formulations.
- Commodity seal oversupply:Standardized plastic and metal variants from low-cost Asian manufacturers are saturating truck and last-mile logistics segments where price sensitivity dominates procurement decisions.
Strategic Opportunities
- India port infrastructure buildout:Jawaharlal Nehru Port and Mundra Port expansion projects under the Sagarmala initiative create procurement windows for ISO-compliant seal suppliers entering South Asian markets.
- Blockchain-IoT convergence:Integration of distributed ledger verification with RFID seal data is enabling tamper-proof custody chains for high-value electronics and luxury goods shipments.
- EU AEO program incentives:Authorized Economic Operator certification benefits are motivating European logistics providers to upgrade seal inventories ahead of mandatory compliance deadlines.
Industry Challenges
- RFID systems integration complexity:Shipping companies struggle to synchronize electronic seal data with legacy fleet management platforms, delaying real-time tracking deployments.
- Multi-standard certification timelines:Manufacturers must navigate overlapping ISO 17712, C-TPAT, and EU AEO requirements, extending product validation cycles before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Security Seals Market |
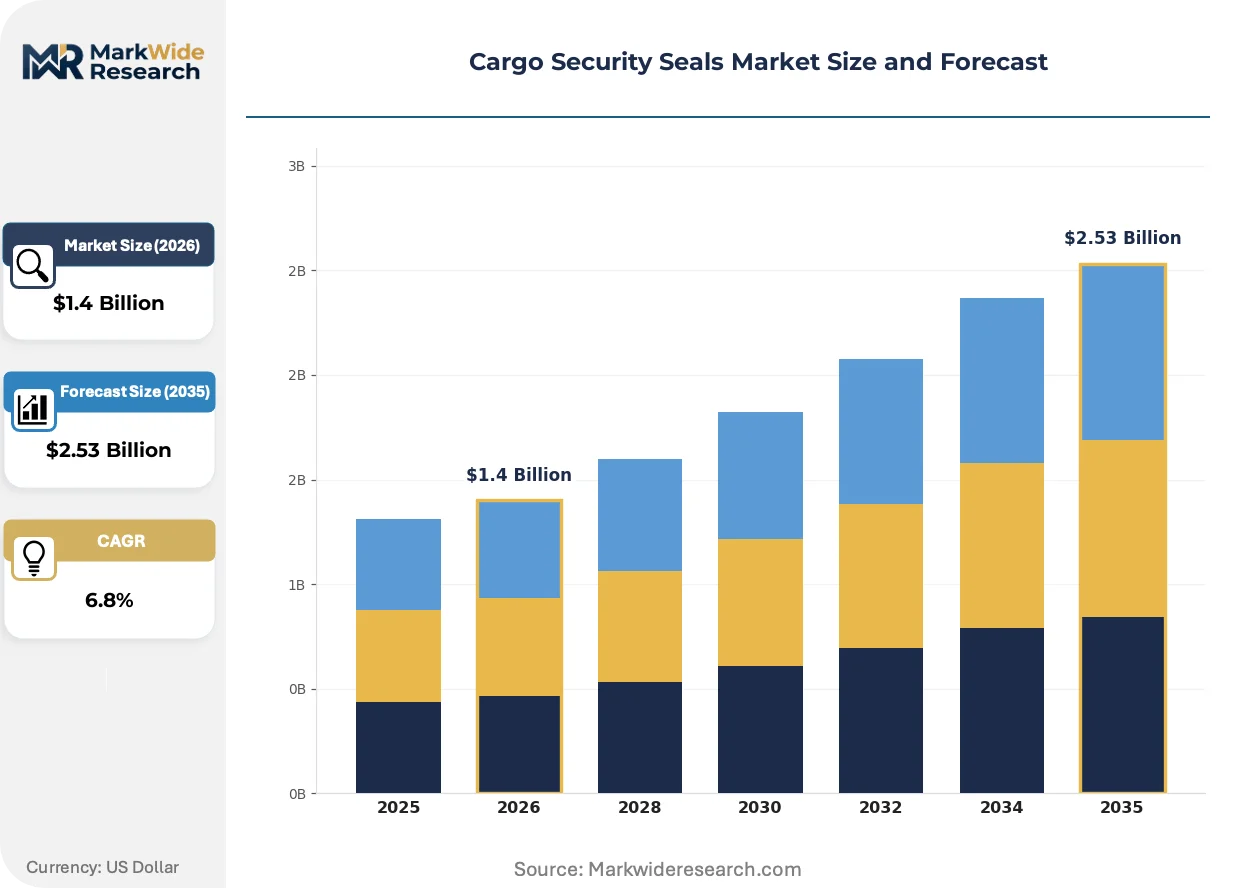
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seal Type: Plastic Seals, Metal Seals, Cable Seals, Bolt Seals End User: Logistics Providers, Retailers, Manufacturers, Shipping Companies Application: Container Security, Truck Security, Warehouse Security, Freight Security Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | American Casting & Manufacturing Corporation, TydenBrooks, Cambridge Security Seals, LeghornGroup, EJ Brooks Company, Mega Fortris, Unisto, Shosky Security, Acme Seals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Security Seals Market Strategic Shifts
Active sensor integration and automated identification protocols are redefining competitive differentiation beyond physical tamper evidence toward data-rich supply chain visibility.
Embedded NFC and UHF RFID chips with environmental monitoring capabilities is rewriting how pharmaceutical and electronics shippers verify chain-of-custody integrity. Cold chain operators in North America and Europe are adopting these seals at accelerating rates to preempt FDA and EMA inspection failures. The technology is compressing differentiation timelines between premium electronic tiers and commodity mechanical alternatives.
REACH material restrictions and EU Green Deal packaging directives are forcing reformulation of ABS plastic and zinc alloy components across European supply chains. Manufacturers must now document recycled content percentages and eliminate cadmium additives to maintain market access. German and Dutch logistics providers are prioritizing suppliers with certified sustainable material pathways in procurement specifications.
Consolidated procurement through fourth-party logistics providers is concentrating seal purchasing decisions among fewer buyers with standardized technical specifications. Maersk, DHL Supply Chain, and Kuehne+Nagel are unbundling seal selection from individual carrier relationships into centralized category management functions. This pattern is most visible in North American and North European container shipping corridors where carrier alliances dominate volume allocation.
Cargo Security Seals Market Segmentation
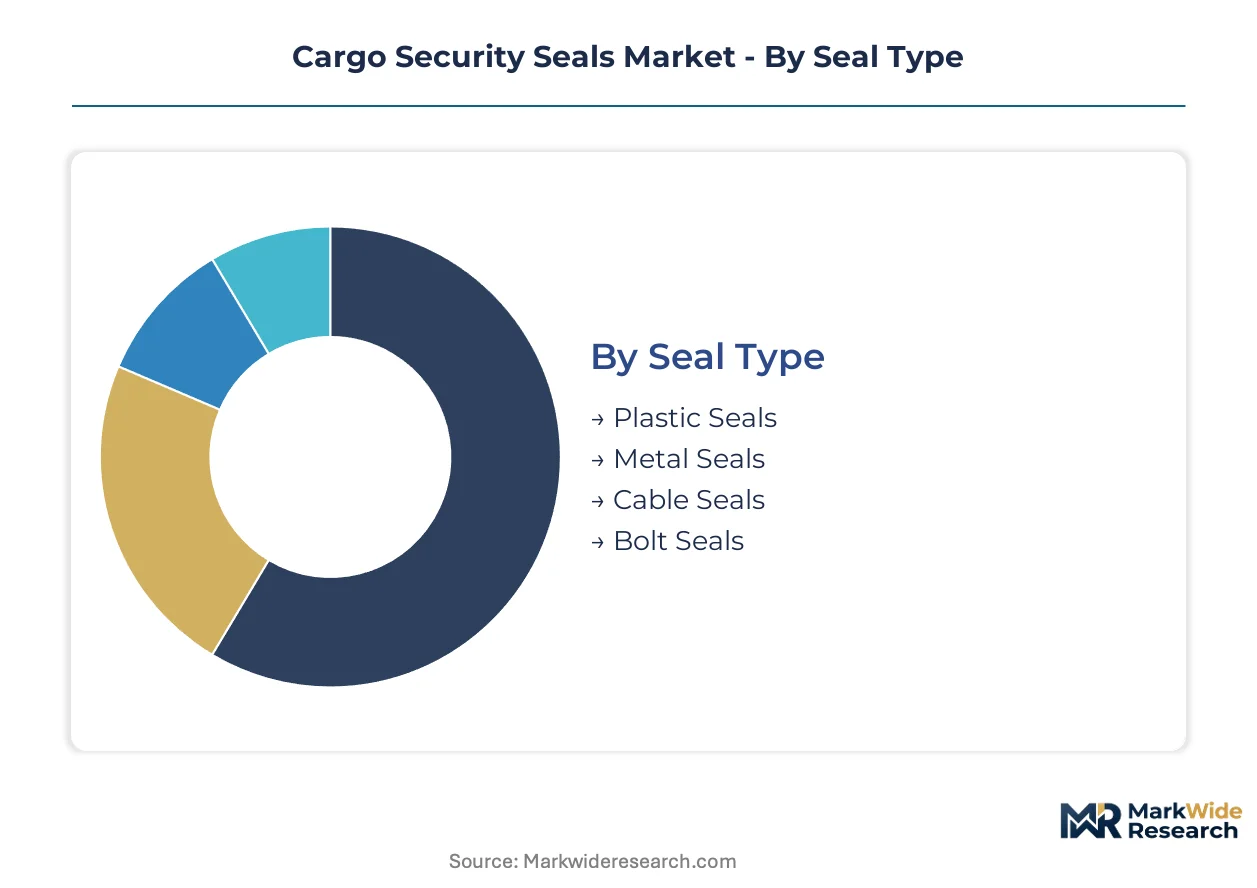
Cargo security seals serve divergent operational requirements across transportation modes, forcing manufacturers to balance tamper-evidence standards against cost thresholds. Segmentation reveals how ISO 17712 certification tiers, environmental exposure conditions, and fleet integration capabilities partition procurement decisions across intermodal networks.
Seal Type:
Customization intensity varies sharply across this category, from standardized commodity plastics to engineered electronic systems requiring embedded sensor calibration.
- Plastic Seals:Molded ABS or polypropylene devices with sequential numbering provide single-use tamper evidence for truck doors and tote boxes. Retailers and last-mile operators in the United States favor these for high-volume, low-unit-cost deployment where shear strength requirements remain minimal.
- Metal Seals:Stamped steel or aluminum bands deliver intermediate tensile resistance for railcar hatches and bulk container latches. German logistics providers specify these for domestic freight corridors where mechanical durability must coexist with manual removal tools.
- Cable Seals:Galvanized steel wire with zinc-alloy locking heads achieves adjustable closure diameters for irregular container fittings.
- Bolt Seals:High-strength zinc-alloy castings with ISO 17712-compliant shear ratings secure international container doors at major ports.
Leading the category by volume: Plastic Seals. Growing fastest: Bolt Seals.
End User:
Procurement sophistication scales with fleet size and regulatory exposure, separating enterprise-grade tracking investments from basic compliance purchasing.
- Logistics Providers:Fourth-party operators consolidate seal procurement across carrier networks, mandating RFID interoperability and centralized data dashboards. DHL Supply Chain and Kuehne+Nagel specifications in Europe and North America are compressing supplier qualification timelines.
- Shipping Companies:Container line operators face the strictest ISO 17712 and C-TPAT compliance thresholds at port of entry. Maersk's fleet-wide RFID seal deployment across Rotterdam, Singapore, and Los Angeles terminals demonstrates how carrier scale drives technology migration.
- Retailers:Omnichannel fulfillment networks prioritize rapid-application plastic seals for trailer pools and cross-dock facilities.
- Manufacturers:Pharmaceutical and electronics producers specify environmental sensor integration for custody documentation.
Dominant procurement scale: Logistics Providers. Expanding most quickly: Shipping Companies.
Application:
Physical threat vectors and access frequency determine material selection, with maritime exposure demanding corrosion resistance absent in land-based deployment.
- Container Security:Bolt seals and cable seals with salt-spray-resistant coatings withstand transoceanic exposure and automated gate scanning. Port modernization programs in China and Germany are accelerating replacement of legacy mechanical variants with RFID-enabled alternatives.
- Truck Security:Plastic pull-tight seals dominate tractor-trailer and last-mile van applications where driver-operated removal occurs multiple times daily. Cost sensitivity here limits penetration of electronic tracking technologies.
- Warehouse Security:Reusable electronic seals with NFC verification secure high-value inventory zones and bonded storage areas.
- Freight Security:Multi-modal shipments require hybrid seal specifications accommodating both container and truck transfer points.
Highest unit volume: Truck Security. Steepest technology upgrade trajectory: Container Security.
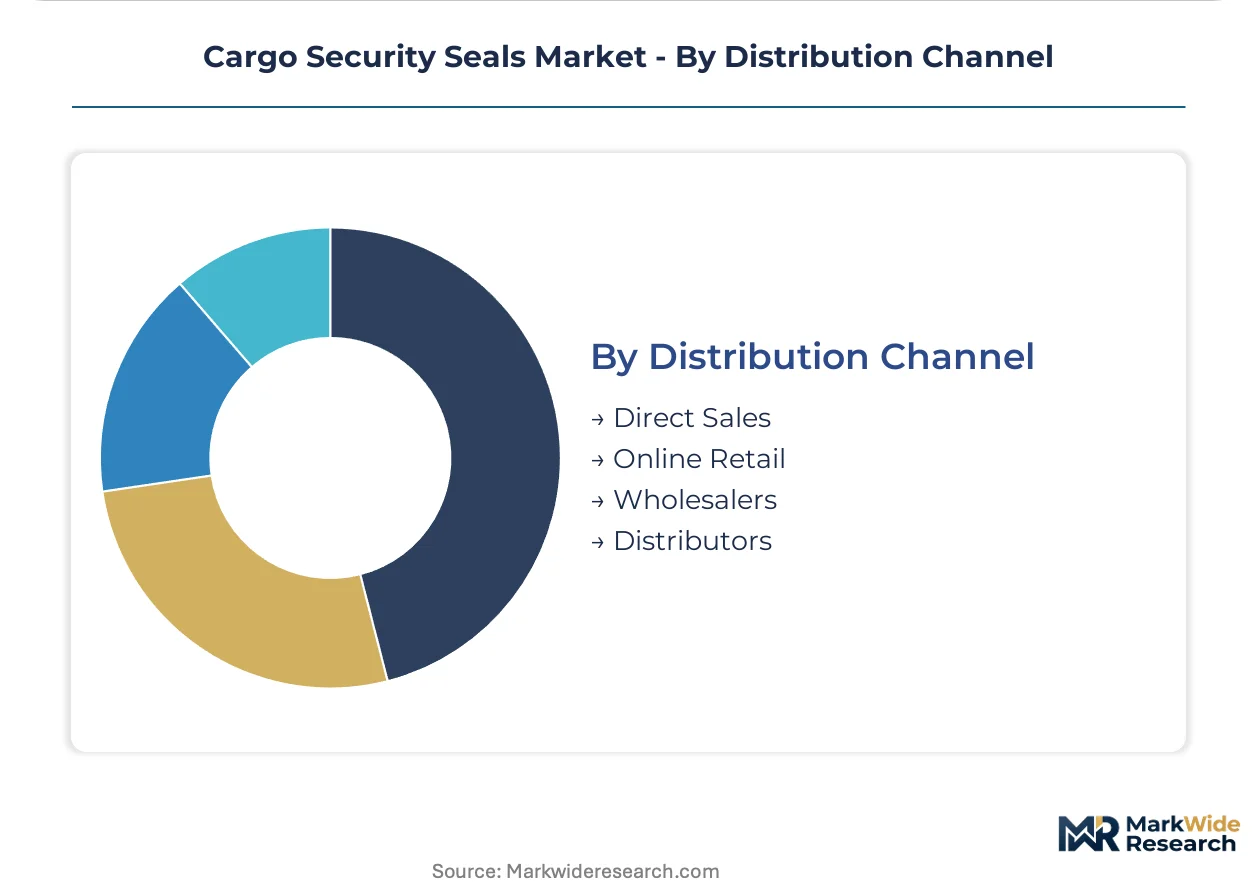
Distribution Channel:
Channel selection reflects order scale, technical specification complexity, and the need for certification documentation in customs-facing procurement.
- Direct Sales:Manufacturers maintain dedicated account teams for container lines and mega-logistics providers requiring ISO 17712 certificate of conformance with every shipment. TydenBrooks and Mega Fortris deploy technical sales engineers to specify embedded RFID configurations.
- Distributors:Industrial supply houses stock standardized plastic and metal seal SKUs for regional freight operators and mid-size retailers. These intermediaries absorb inventory risk for high-volume, low-margin commodity variants.
- Online Retail:E-commerce platforms serve small fleet operators and occasional purchasers with limited technical specification requirements.
- Wholesalers:Bulk packaging for government and institutional procurement channels emphasizes price-per-unit optimization over feature differentiation.
Primary volume pathway: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors cargo security seal procurement intensity through Europe's most automated container terminal complex, where RFID-enabled gate systems process millions of seal-verified movements annually. Port infrastructure investments across three continents are compressing replacement cycles for legacy mechanical variants.
United States
FDA traceability mandates for pharmaceutical cold chains drive sensor-integrated seal adoption across distribution networks. C-TPAT compliance thresholds at Los Angeles and New York-New Jersey ports eliminate non-certified suppliers from carrier procurement pools. The Southeast corridor from Savannah to Charleston concentrates bolt seal demand through expanding intermodal rail connections.
Germany
EU AEO certification incentives motivate logistics providers to upgrade seal inventories ahead of mandatory deadlines. REACH material restrictions and EU Green Deal packaging directives pressure suppliers to eliminate heavy metal content from zinc-alloy formulations. The Hamburg-Bremerhaven port cluster leads RFID deployment through automated gate clearance systems.
China
Port security modernization programs at Shanghai and Shenzhen accelerate replacement of legacy bolt seals with automated scanning alternatives. GB standards alignment with ISO 17712 shear strength requirements tightens compliance for international container movements. The Yangtze River Delta manufacturing belt concentrates domestic seal production capacity.
India
Sagarmala initiative investments at Jawaharlal Nehru Port and Mundra Port create procurement windows for ISO-compliant suppliers entering South Asian markets. DGFT customs modernization programs mandate tamper-evident seals for export container movements. The Gujarat-Maharashtra industrial corridor concentrates pharmaceutical cold chain logistics driving premium electronic seal demand.
Singapore
Port automation programs at Tuas Mega Port replace mechanical seals with RFID-enabled alternatives capable of unmanned gate processing. The Maritime and Port Authority's digitalization mandates synchronize with carrier fleet management platforms across Southeast Asian shipping lanes. The city-state's transshipment dominance concentrates regional seal specification standardization.
Cargo Security Seals Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent technology tiers in cargo security seals. Foundry-integrated manufacturers command margin advantages in high-strength metal variants through captive zinc-alloy casting capacity. Asset-light specialists concentrate electronic seal development through outsourced semiconductor assembly. Market structure separates into three archetypes: backward-integrated metal casters, RFID technology licensors, and commodity plastics molders. Dominant competitive moves include M&A to acquire sensor calibration capabilities and capacity expansion into recycled polymer feedstocks.
Among North American fabricators, American Casting & Manufacturing Corporation exemplifies scale-driven production across standardized container security products. TydenBrooks occupies a position within the premium electronic tier, representing specialists in embedded tracking technology for pharmaceutical applications. Mega Fortris anchors the high-strength bolt seal segment through in-house zinc-alloy casting operations. These three entities collectively illustrate how geographic origin and corporate structure map to divergent competitive positions across mechanical and electromechanical product categories.
| Leading Market Players |
|---|
| American Casting & Manufacturing Corporation |
| TydenBrooks |
| Cambridge Security Seals |
| LeghornGroup |
| EJ Brooks Company |
| Mega Fortris |
| Unisto |
| Shosky Security |
| Acme Seals |
| Others |
Value Chain & Pricing Dynamics
Backward integration into zinc-alloy casting anchors both supply security and margin control for high-strength bolt seal manufacturers serving ISO 17712-certified container security markets. Mega Fortris exemplifies this pattern, where captive foundry capacity insulates production economics from raw material volatility while supporting premium positioning against commodity competitors.
Pricing Analysis
Outcome-based pricing tied to cargo integrity assurance anchors the premium tier, with RFID-enabled electronic seals commanding substantial uplifts over mechanical alternatives based on real-time tracking yield and audit trail defensibility. Pricing stratifies across premium, standard, and economy tiers aligned with certification grade, customization level, volume scale, and after-sales service bundling. Cost compression in commodity plastic and metal bolt segments is intensifying because low-cost Asian manufacturers saturate truck and last-mile logistics procurement pools. Retailers and small fleet operators exhibit the highest price sensitivity, while pharmaceutical cold chain operators and container lines demonstrate the lowest.
Supply Chain Analysis
Returns and refurbishment flows for reusable electronic seals with embedded sensors are creating secondary supply channels that compete with primary manufacturing for warehouse security and bonded storage applications. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta anchoring zinc-alloy casting and ABS plastic molding capacity. Supply chains draw from zinc concentrate, recycled polymer feedstocks, and semiconductor components for RFID integration. Single-source vulnerability in semiconductor assembly for electronic seals poses structural risk. Distribution runs through direct sales teams for container lines, industrial distributors for regional freight operators, and e-commerce platforms for small fleet purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around ISO 17712 certification mandates and RFID interoperability requirements that eliminate subscale mechanical seal producers lacking capital for electronic platform development.
For Market Incumbents: Deploy sensor calibration capabilities as a defensive moat against technology licensors entering pharmaceutical cold chain applications. Mega Fortris and TydenBrooks should extend backward integration into recycled polymer feedstocks to preempt REACH compliance failures in European markets. Certification investment in EU AEO and C-TPAT alignment compresses qualification timelines for fourth-party logistics consolidation. For New Entrants and Emerging Players: Begin with India's Sagarmala port infrastructure buildout, where Jawaharlal Nehru Port and Mundra Port expansion creates procurement windows before incumbent distributor networks solidify. Underpenetrated pharmaceutical cold chain logistics in the Gujarat-Maharashtra corridor offers the most penetrable white space. A go-to-market angle anchored to DGFT customs modernization compliance documentation accelerates carrier qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by foundry-integrated metal casters seeking electronic seal capabilities or RFID technology licensors needing manufacturing scale. Long-term viability favors asset-light specialists with sensor calibration IP over commodity plastics molders facing margin compression. Watch for RFID systems integration complexity resolution as the inflection signal for accelerated carrier fleet-wide deployment.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Technology Licensing | Enables real-time cargo tracking integration with Maersk and DHL fleet management platforms. |
| Backward Integration into Zinc-Alloy Casting | Secures captive supply for ISO 17712 high-shear bolt seals against commodity price volatility. |
| Recycled Polymer Feedstock Transition | Preempts EU Green Deal and REACH material restriction enforcement in German logistics procurement. |
| ISO 17712 Certification Investment | Unlocks C-TPAT and EU AEO procurement pools at Los Angeles and Rotterdam port terminals. |
| Sensor Calibration Capability Acquisition | Accelerates pharmaceutical cold chain positioning against FDA traceability mandate deadlines. |
Study Parameters
Document review covered ISO 17712 certification databases, customs modernization program filings, and RFID technology patent landscapes, complemented by interviews with seal procurement managers at fourth-party logistics providers, technical sales engineers at foundry-integrated manufacturers, regulatory affairs leads at pharmaceutical distributors, and port authority automation officers. Secondary validation drew from customs trade data, SEC filings of logistics providers, and EU AEO certification registries. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to reconcile volume projections.
Segment-level outputs across seal type, end user, application, and distribution channel were generated through the projection horizon, with CAGRs derived from replacement cycle compression analysis and technology migration curves. Modeled inputs included ISO 17712 compliance threshold adoption rates, RFID gate system deployment timelines at automated terminals, and zinc price elasticity effects on bolt seal manufacturing economics.
Regulatory fragmentation between ISO, C-TPAT, and EU AEO programs, commodity zinc price volatility, and RFID semiconductor supply constraints are the dominant revision risks to forecast assumptions. Practitioners should monitor multi-standard certification timeline extensions and carrier fleet management platform integration completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market