
 Armoured Thermocouple Market | 2026-2036
Armoured Thermocouple Market Size, Share, and Industry Trends Forecast 2026-2036
Armoured Thermocouple Market Analytics
Chinese stainless steel sheathing capacity is realigning the competitive map for armoured thermocouple supply. Siccet leverages integrated mineral-insulated cable production to sustain cost leadership across European process industries. Thermosense anchors its position through specialized high-temperature assemblies for aerospace test facilities. Anhui Huaguang Instrument Cable competes on scale, operating one of Asia's largest dedicated thermocouple manufacturing complexes.
An armoured thermocouple consists of thermoelectric conductors encased in a metal sheath with compacted mineral insulation, typically magnesium oxide, enabling operation from minus 200 degrees Celsius to over 1,100 degrees Celsius in corrosive or mechanically stressed environments. Heavy-duty thermocouples dominate margin pools in oil and gas downstream applications where failure costs exceed instrument replacement by orders of magnitude. Miniature thermocouples represent the fastest-growing product category as medical device manufacturers and semiconductor fabricators demand faster thermal response in confined spaces.
EPA emissions standards and EU Green Deal monitoring protocols are mandating redundant temperature verification at combustion sources, directly expanding replacement demand for certified armoured assemblies. China's GB standards and NMPA process safety rules require identical instrumentation redundancy at coal-fired and chemical plants. Stakeholders must monitor evolving IEC 60584 calibration tolerances and regional content requirements that could fragment procurement specifications across major demand centers.
Market Dynamics
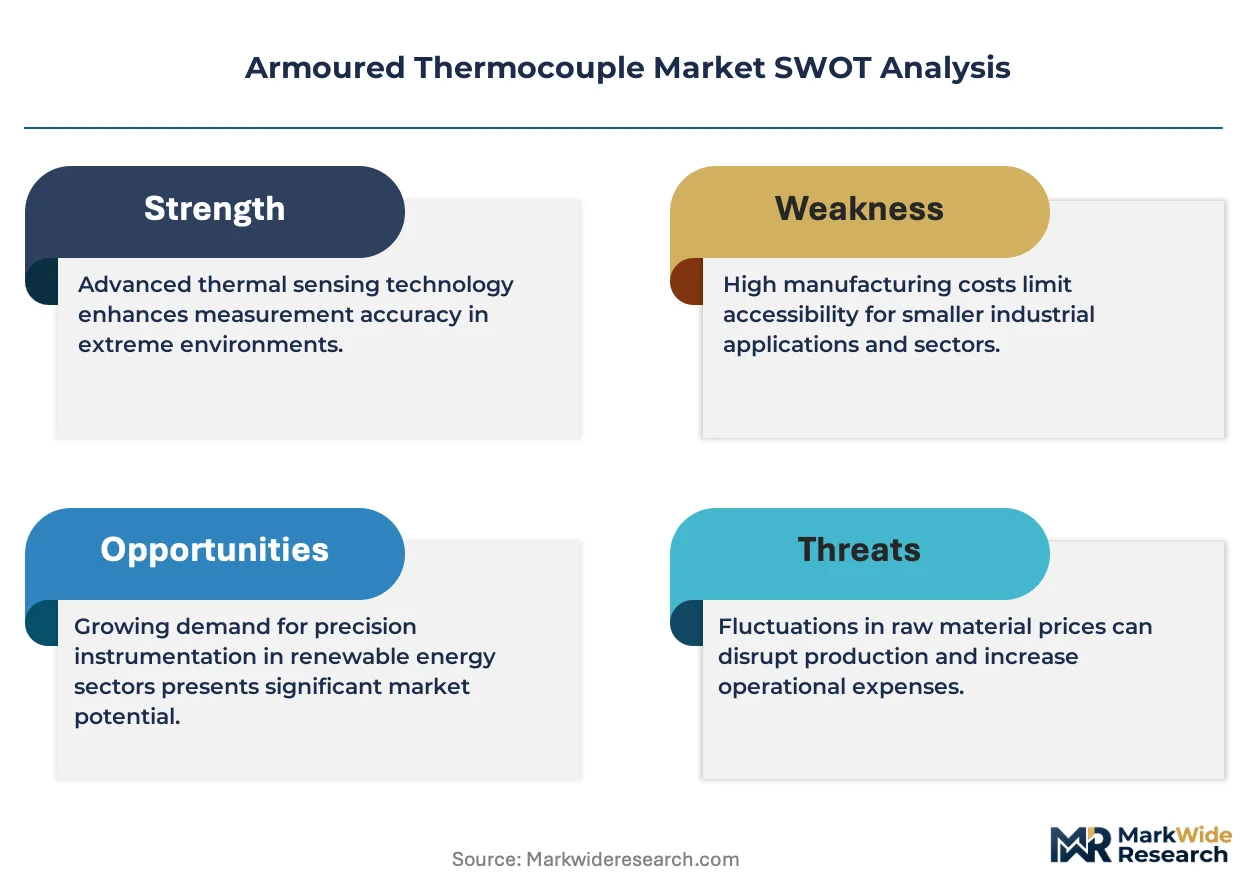
Mineral-insulated cable manufacturing concentration in Chinese stainless steel hubs is compressing cost structures and forcing European producers toward high-temperature specialization to defend margin pools.
Growth Catalysts
- EPA emissions verification mandates:Redundant temperature monitoring at combustion sources now requires certified armoured assemblies, expanding replacement cycles at US power generation facilities.
- Semiconductor thermal response demands:Miniature thermocouples with faster reaction times are penetrating wafer fabrication processes where confined-space instrumentation limits conventional sensor deployment.
- EU Green Deal monitoring protocols:Industrial combustion sites across Germany and Poland must install dual-verification temperature systems, directly lifting certified product demand.
Market Restraints
- Nickel alloy input volatility:Inconel and Hastelloy sheath material costs fluctuate with mining output from Indonesian and Philippine laterite deposits, squeezing margin predictability for mid-tier manufacturers.
- Sheathing capacity concentration:Chinese integrated producers control over 60% of global mineral-insulated cable output, creating supply vulnerability for European and North American fabricators dependent on imported feedstock.
- IEC 60584 calibration tolerance divergence:Evolving international standards against persistent national certification requirements fragment procurement specifications and extend qualification timelines.
Strategic Opportunities
- India process safety expansion:CEA and BIS enforcement at coal-fired and petrochemical complexes creates first-mover advantage for certified armoured assembly suppliers establishing local calibration facilities.
- Aerospace test facility specialization:High-temperature assemblies rated above 1,100 degrees Celsius for hypersonic wind tunnel applications command premium positioning with limited qualified competition.
- Medical device miniaturization:Catheter-based thermal monitoring for minimally invasive procedures opens volume potential in FDA-regulated Class II and Class III device supply chains.
Industry Challenges
- Precision welding skill scarcity:Qualified technicians for magnesium oxide compaction and sheath sealing remain concentrated in legacy industrial regions, constraining capacity expansion.
- Multi-standard certification burden:Simultaneous ATEX, IECEx, and UL compliance for hazardous area deployment extends product development cycles and inflates qualification costs.
- Legacy system integration friction:Digital temperature transmitters require analog-to-protocol conversion hardware when retrofitting decades-old DCS architectures at established process plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armoured Thermocouple Market |
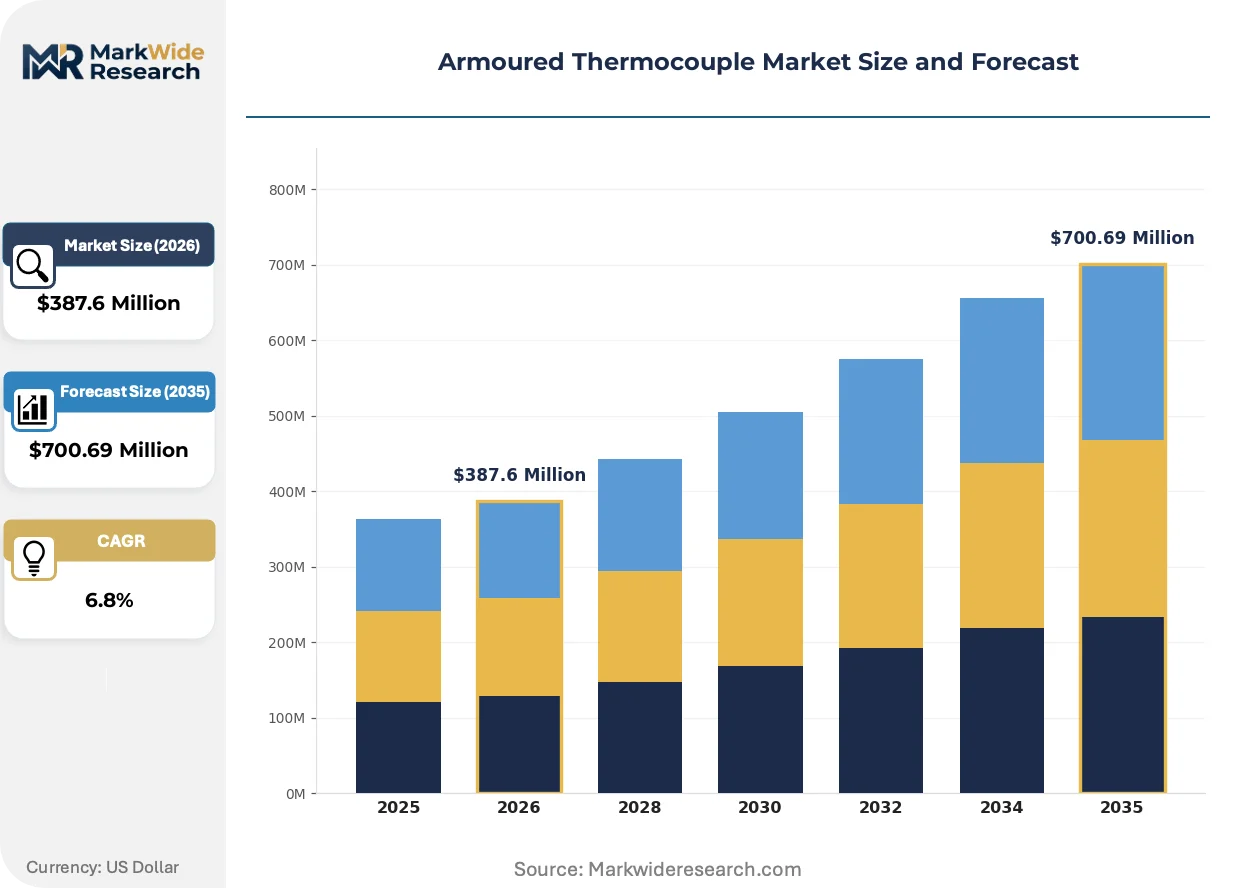
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Thermocouples, Miniature Thermocouples, Heavy-Duty Thermocouples, Surface Thermocouples Material: Inconel, Stainless Steel, Ceramic, Copper End User: Oil & Gas, Power Generation, Food Processing, Aerospace Installation Type: Fixed Installation, Portable Installation, Flanged Installation, Welded Installation |
| Companies Covered | Siccet, Temperature Controls, Thermosense, Permanoid, Cixi Flowmeter, Thermo Electric, Anhui Huaguang Instrument Cable, TC Ltd, Wenzhou Shangtong Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armoured Thermocouple Market Evolving Landscape
Sensor miniaturization, regulatory harmonization pressures, and buyer consolidation are restructuring how armoured thermocouple value is captured and delivered across industrial supply chains.
Thin-film platinum resistance elements deposited directly onto ceramic substrates are overtaking wire-wound thermocouples in semiconductor thermal mapping applications. TSMC and Samsung Foundry have accelerated qualification of these assemblies for EUV lithography chamber monitoring. The technology is overtaking conventional mineral-insulated designs in sub-500 degree Celsius zones where response speed determines process yield.
REACH substance restrictions on hexavalent chromium coatings are forcing sheath manufacturers toward nickel-palladium surface treatments or laser-marked identification. German chemical processors under ECHA enforcement timelines face accelerated replacement of legacy inventory. Aerospace OEMs in France and Italy are now specifying chromium-free alternatives for all new platform thermal instrumentation.
Consolidated procurement through integrated automation vendors is displacing direct sensor purchasing by end-users. Siemens, ABB, and Yokogawa now bundle certified thermocouple assemblies with DCS commissioning packages, compressing standalone distributor margins. This concentration is most visible in German automotive paint lines and Japanese chemical complexes where single-source automation contracts dominate capital expenditure approval workflows.
Armoured Thermocouple Market Segmentation
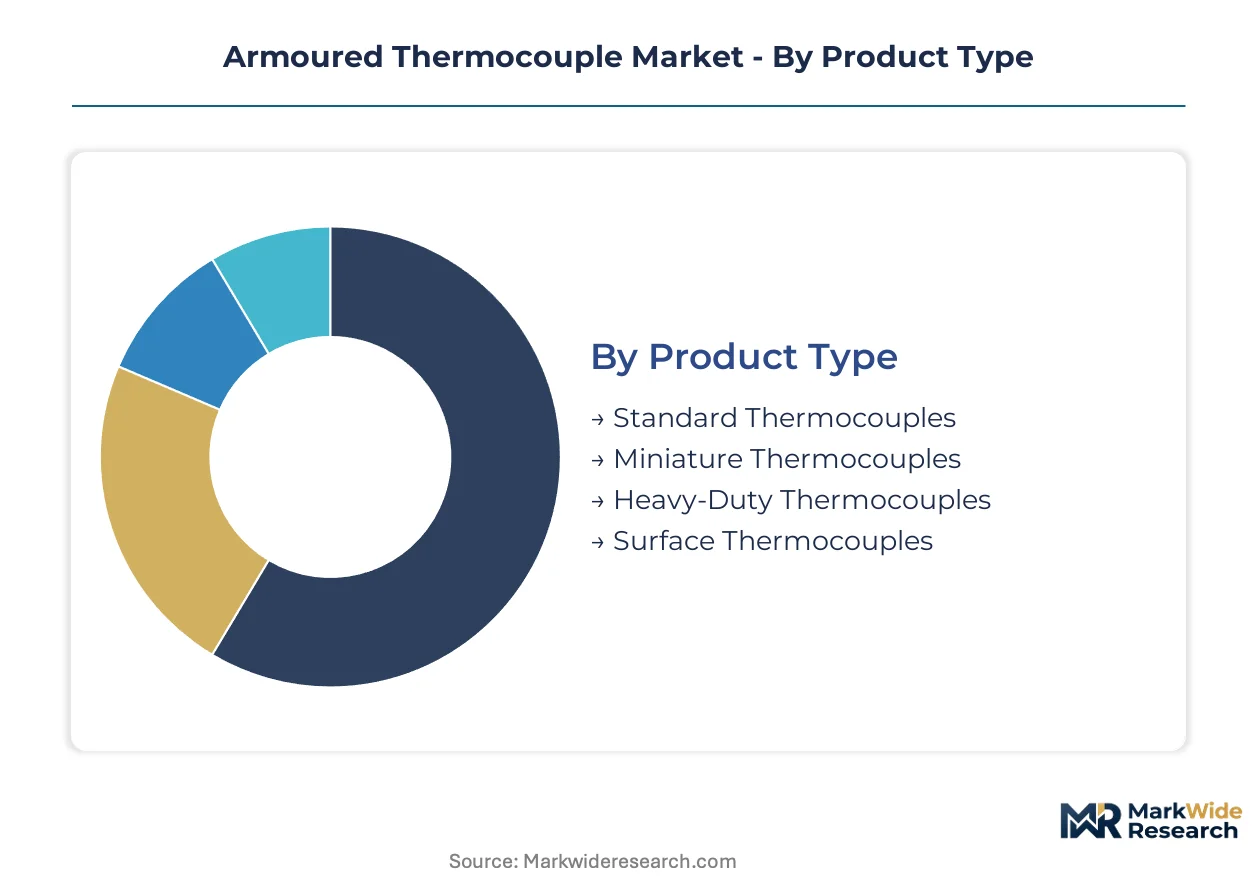
Armoured thermocouple procurement splits across technical specifications, metallurgical requirements, and deployment constraints that reshape vendor selection criteria. Understanding these segment boundaries clarifies why certain suppliers dominate specific application environments while others compete on material cost.
Product Type:
Technical specifications define thermal response speed, mechanical durability, and spatial constraints across industrial deployment scenarios.
- Heavy-Duty Thermocouples:Magnesium oxide-insulated conductors within thick-walled Inconel or stainless steel sheaths withstand vibration, corrosion, and thermal shock in refining catalytic crackers. Oil and gas downstream operators in the US Gulf Coast specify these for failure costs exceeding instrument replacement by orders of magnitude.
- Miniature Thermocouples:Reduced-diameter mineral-insulated cables achieve sub-second thermal response in confined spaces. Semiconductor fabricators in Germany and medical device manufacturers in the US drive specifications for catheter-based thermal monitoring and wafer fabrication chamber instrumentation.
- Standard Thermocouples:General-purpose mineral-insulated assemblies serve power generation boiler monitoring and chemical process control across mid-tier industrial facilities.
- Surface Thermocouples:Flat-profile or clamp-on designs attach to external pipework and vessel walls where immersion is impractical.
Heavy-Duty Thermocouples lead on scale; Miniature Thermocouples lead on momentum.
Material:
Sheath metallurgy determines maximum operating temperature, chemical compatibility, and unit economics in corrosive process streams.
- Inconel:Nickel-chromium-iron alloys maintain structural integrity above 1,100 degrees Celsius in sulfidizing and carburizing atmospheres. Aerospace test facilities in France and Germany specify Inconel sheathing for hypersonic wind tunnel instrumentation where thermal cycling demands oxidation resistance.
- Stainless Steel:Type 304 and 316 sheathing dominates cost-sensitive applications through Chinese integrated production capacity. Power generation facilities in Poland and India source stainless steel assemblies for sub-800 degree Celsius boiler monitoring under EU Green Deal and CEA compliance timelines.
- Ceramic:Alumina or silicon carbide outer protection enables operation above 1,600 degrees Celsius in furnace and kiln applications.
- Copper:Limited to cryogenic and sub-zero applications where thermal conductivity and ductility outweigh corrosion concerns.
Stainless Steel dominates procurement volumes; Inconel commands premium positioning.
End User:
Industry-specific operating conditions drive certification requirements and replacement cycle economics.
- Oil & Gas:Downstream refining and petrochemical complexes demand ATEX and IECEx certified assemblies for hazardous area deployment. Redundant temperature verification at FCCU and delayed coker units sustains replacement demand under EPA emissions monitoring mandates.
- Power Generation:Coal-fired and combined-cycle plants require redundant thermocouple arrays at combustion sources. Germany and Poland face accelerated installation under EU Green Deal protocols requiring dual-verification temperature systems.
- Food Processing:Hygienic design specifications and FDA compliance dominate thermal monitoring for pasteurization and sterilization equipment.
- Aerospace:High-temperature test facility instrumentation and engine development programs specify specialized assemblies with extended calibration traceability.
Oil & Gas concentrates margin pools; Power Generation expands most quickly on regulatory compliance.
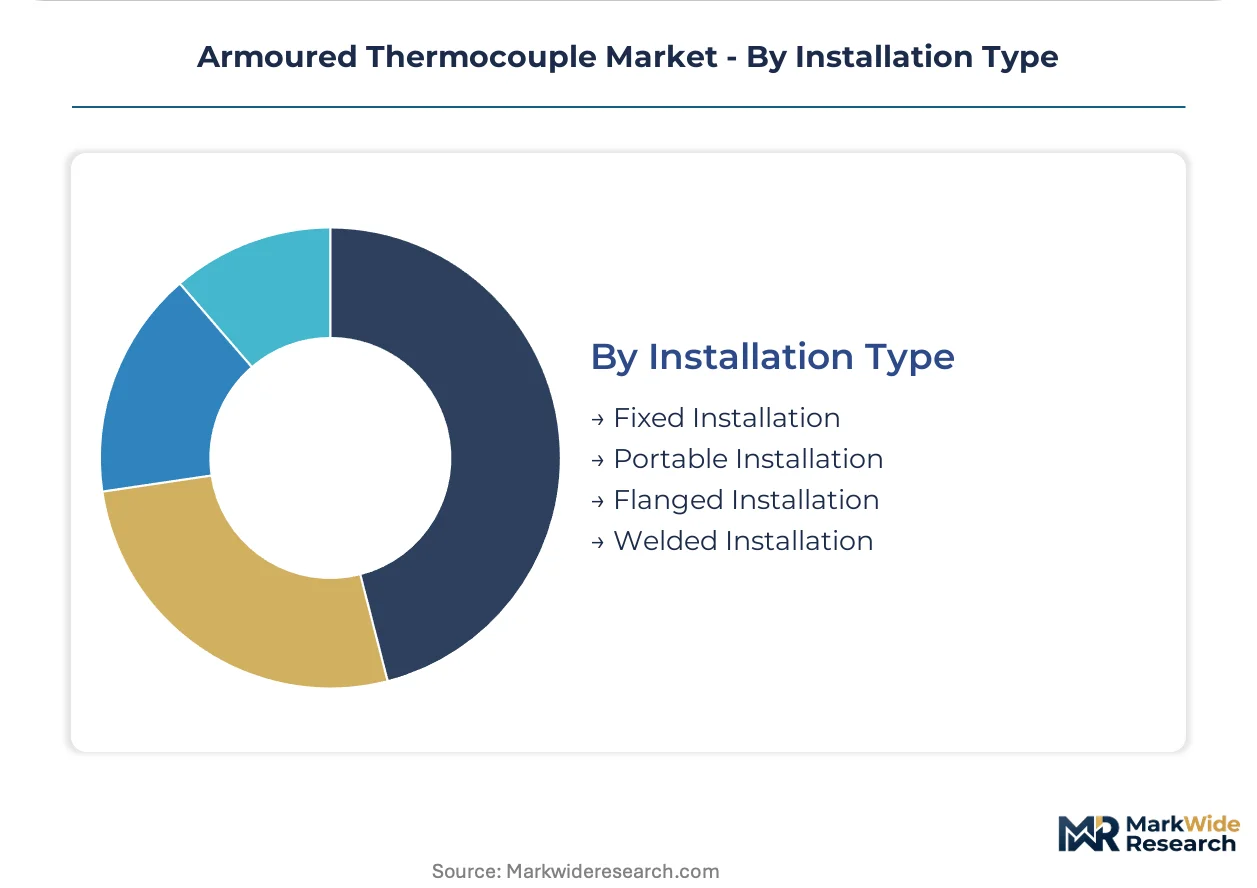
Installation Type:
Mounting configuration determines mechanical reliability, maintenance accessibility, and integration with existing process infrastructure.
- Flanged Installation:ASME or DIN standard flanges enable pressure-tight insertion into high-pressure reactors and steam lines. Chemical processors in Germany specify flanged assemblies for autoclave and polymerization reactor monitoring.
- Welded Installation:Permanent sheath-to-nozzle welding eliminates leak paths in critical containment applications. Nuclear and high-pressure hydrogen service in France and Japan requires welded installations under ASME Section III and METI guidelines.
- Fixed Installation:Threaded or compression fittings suit general industrial applications with moderate pressure and vibration.
- Portable Installation:Quick-disconnect and magnetic-mount designs serve temporary monitoring and calibration verification.
Flanged Installation anchors established process plant specifications; Welded Installation gains share fastest on safety-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are shifting fabrication capacity toward Chinese stainless steel hubs while European and North American producers retreat into high-temperature specialization and certification-heavy segments.
Germany
EU Green Deal enforcement at coal-fired plants and chemical complexes drives redundant temperature monitoring installations. ECHA timelines for hexavalent chromium elimination accelerate sheath replacement cycles. The Ruhr industrial corridor and Bavarian chemical belt concentrate demand for ATEX-certified assemblies.
United States
EPA emissions verification mandates at power generation facilities expand replacement demand for certified armoured thermocouples. Downstream oil and gas operators in the Gulf Coast specify heavy-duty assemblies where failure costs dwarf instrument replacement. Houston and Louisiana petrochemical clusters anchor procurement volumes.
China
GB standards and NMPA process safety rules mandate instrumentation redundancy at coal-fired and chemical plants. Integrated mineral-insulated cable production in Zhejiang and Jiangsu provinces compresses cost structures for global supply. Yangtze River Delta manufacturers dominate stainless steel sheathing capacity.
India
CEA and BIS enforcement at thermal power stations and petrochemical complexes creates demand for certified armoured assemblies. Coal-fired boiler monitoring requirements under national process safety frameworks expand installation volumes. Gujarat and Maharashtra industrial corridors attract calibration facility investments.
France
Aerospace test facility instrumentation for hypersonic wind tunnel applications commands premium positioning with limited qualified competition. REACH substance restrictions drive chromium-free sheath specifications for new platform thermal systems. Toulouse and Paris-Saclay aerospace clusters specify high-temperature assemblies rated above 1,100 degrees Celsius.
Armoured Thermocouple Market Competitive Landscape
Chinese integrated producers anchor the scale-driven tier; European specialists hold the certification-intensive premium segment. The vendor base splits between mineral-insulated cable manufacturers with captive stainless steel capacity and assembly fabricators dependent on imported feedstock. Three archetypes dominate: integrated Chinese producers with backward control over sheathing, European high-temperature specialists, and regional distributors bundling with automation platforms. Competitive moves concentrate on capacity expansion in Chinese stainless steel hubs and strategic partnerships with DCS vendors.
Among European fabricators, Siccet and Thermosense occupy distinct positioning within the premium tier. Anhui Huaguang Instrument Cable exemplifies the scale-driven Chinese archetype with integrated production infrastructure. Temperature Controls and Permanoid represent mid-market assembly specialists navigating multi-standard certification requirements. TC Ltd and Wenzhou Shangtong Instruments sit within the distributor-integrated segment serving regional automation procurement channels.
| Leading Market Players |
|---|
| Siccet |
| Temperature Controls |
| Thermosense |
| Permanoid |
| Cixi Flowmeter |
| Thermo Electric |
| Anhui Huaguang Instrument Cable |
| TC Ltd |
| Wenzhou Shangtong Instruments |
| Others |
Value Network & Pricing Analysis
Nickel alloy ingot costs cascade through three distinct pricing tiers for armoured thermocouple procurement. Chinese integrated producers with captive stainless steel sheathing capacity capture mid-market volume through compressed magnesium oxide cable economics. European fabricators defend premium positioning via Inconel specialization and ATEX certification bundling.
Pricing Analysis
Distributor margins compress most severely in standard-grade mineral-insulated cable sales to power generation contractors. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified assemblies with full calibration traceability from basic stainless steel units and unbranded Chinese imports. Price differentiation hinges on certification grade and volume scale, with procurement officers at German chemical complexes least sensitive to unit cost when failure downtime exceeds replacement expense. Cost compression in the standard tier intensifies because Yangtze River Delta manufacturers have expanded sheathing capacity faster than European demand growth.
Supply Chain Analysis
Inconel and Hastelloy feedstock draws from Indonesian and Philippine laterite mining operations through Japanese and European specialty alloy processors. Magnesium oxide insulation powder sources from Chinese and Turkish magnesite deposits, while stainless steel sheathing concentrates in Zhejiang and Jiangsu province rolling mills. Single-source vulnerability in nickel alloy supply creates exposure to mining export restrictions. Distribution runs through automation vendor bundling with Siemens, ABB, and Yokogawa displacing standalone sensor distributors in German and Japanese capital expenditure workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chinese manufacturing cost advantages against European regulatory compliance burdens create geographic-arbitrage opportunities for armoured thermocouple procurement and fabrication investment.
For Market Incumbents: Acquire calibration laboratory assets in India and Southeast Asia to anchor local certification capabilities before CEA and BIS enforcement tightens. Defend margin pools by deepening backward integration into magnesium oxide compaction and precision welding technician training programs. Threat substitution from thin-film platinum resistance elements in semiconductor thermal mapping demands accelerated R&D in sub-second response mineral-insulated designs. For New Entrants and Emerging Players: Medical device manufacturers seeking catheter-based thermal monitoring for minimally invasive procedures represent the most penetrable buyer archetype. White-space concentration in FDA-regulated Class II and Class III device supply chains offers volume potential without competing against entrenched automation vendor relationships. Go-to-market execution should prioritize direct technical sales to biomedical engineering teams rather than distributor channels. For Investors and Strategic Acquirers: Consolidation pressure builds where Chinese scale players seek European certification expertise and aerospace test facility relationships. Long-term viability favors acquisition targets with captive high-temperature assembly capabilities above 1,100 degrees Celsius and established METI or ASME Section III qualification histories. Watch for IEC 60584 calibration tolerance divergence as signal of procurement specification fragmentation that rewards multi-certified inventory holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral-Insulated Cable Production | Captive magnesium oxide compaction reduces feedstock vulnerability for European fabricators facing Chinese import dependency. |
| Calibration Facility Expansion in India | Local BIS and CEA certification capability captures first-mover advantage at Gujarat and Maharashtra industrial corridors. |
| High-Temperature Specialization Above 1,100°C | Inconel sheathing expertise for hypersonic wind tunnel applications commands premium positioning with limited qualified competition. |
| Medical Device Supply Chain Qualification | FDA Class II and Class III device certification opens catheter-based thermal monitoring volume in minimally invasive procedure markets. |
| Chromium-Free Sheath Surface Treatment Transition | Nickel-palladium coatings or laser-marked identification satisfy ECHA enforcement timelines and aerospace OEM specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct armoured thermocouple market estimates. Primary fieldwork engaged plant engineers at power generation facilities, procurement leads at petrochemical complexes, distribution channel partners serving industrial automation markets, and technical directors at mineral-insulated cable manufacturers. Secondary validation drew from EPA emissions compliance filings, EU Green Deal implementation progress reports, SEC 10-K disclosures by listed automation vendors, and customs data tracking nickel alloy and magnesium oxide trade flows. Bottom-up unit demand modeling and top-down industry revenue reconciliation anchored triangulation across the analysis window.
Comparable historical periods anchored volume and value projections across the modeling period without specific year references. Segmentation dimensions included product type tier, sheath metallurgy grade, end-use industry vertical, installation configuration, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to verified baseline estimates. Industry-specific forecast inputs incorporated EPA and EU Green Deal compliance timeline acceleration, semiconductor fab capacity expansion announcements, and aerospace test facility capital expenditure pipelines.
Inputs from plant engineer interviews and automation vendor procurement disclosures were available through the study window; gaps in real-time nickel alloy spot pricing and magnesium oxide contract terms introduce uncertainty bands around cost structure assumptions. Forecasts reflect documented assumptions about regulatory enforcement pacing and technology substitution thresholds. Nickel alloy supply disruption, IEC 60584 tolerance divergence acceleration, and thin-film sensor penetration in sub-500°C applications warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market