
 Global HIV Diagnosis Market | 2026-2036
Global HIV Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global HIV Diagnosis Market Foresight
Point-of-care nucleic acid amplification is reconfiguring how HIV viral load and early infant diagnosis reach decentralized settings. Abbott Laboratories leverages integrated rapid-test platforms to sustain channel control across African and Asian public health networks. Siemens Healthineers anchors its position through automated chemiluminescence systems that dominate high-throughput hospital laboratories. Roche competes via centralized molecular diagnostics that extend its reach into resistance testing and viral load monitoring workflows.
HIV diagnosis encompasses laboratory and point-of-care methods for detecting viral antibodies, antigens, or nucleic acids in human blood, serum, or oral fluid specimens, with sensitivity thresholds typically below 50 copies per milliliter for RNA-based assays. These technologies serve epidemiological surveillance, treatment initiation, and therapeutic monitoring across clinical and community health settings. Rapid diagnostic tests occupy the largest volume tier due to WHO prequalification and national screening program procurement, while nucleic acid amplification tests capture premium margins in viral load and early infant diagnosis applications. Microfluidics-based platforms represent the fastest-growing technology segment as manufacturers miniaturize molecular workflows for resource-limited clinics.
FDA clearance pathways and WHO prequalification standards shape product development timelines and market access for HIV diagnostics manufacturers seeking procurement contracts. EMA oversight of in vitro diagnostic medical devices under the MDR framework adds compliance layers for European market entry. REACH chemical safety requirements and EU AI Act provisions for algorithm-assisted diagnostic interpretation are forcing recalibration of assay design and software validation protocols. Stakeholders must monitor evolving prequalification criteria and decentralized testing reimbursement policies to align R&D portfolios with shifting procurement authority from centralized laboratories to community-based delivery models.
Market Dynamics
Point-of-care nucleic acid testing is fragmenting procurement authority from centralized reference laboratories toward community health clinics and mobile screening units across sub-Saharan Africa and Southeast Asia.
Growth Catalysts
- WHO prequalification tightening:Stricter quality benchmarks for HIV diagnostics are filtering out marginal suppliers and consolidating contract awards to manufacturers with validated cold-chain stability data.
- Early infant diagnosis protocols:National programs in Kenya and Nigeria are mandating birth testing within six weeks, expanding molecular assay volumes beyond traditional antibody screening.
- Microfluidics miniaturization:Chip-based platforms are reducing instrument footprints to suitcase-size units operable by community health workers without laboratory infrastructure.
Market Restraints
- Reagent cold-chain dependency:Temperature-sensitive nucleic acid amplification chemistries require continuous 2-8°C logistics, constraining deployment to clinics with reliable refrigeration.
- Capital equipment concentration:Automated high-throughput systems for viral load monitoring remain concentrated in South Africa's national laboratory network, limiting vendor diversification.
- Substitute algorithm testing:Serial rapid diagnostic testing protocols using multiple antibody assays are displacing some molecular confirmation testing in resource-constrained settings.
Strategic Opportunities
- Resistance testing expansion:Integrase inhibitor rollouts are generating demand for genotypic resistance assays in treatment-experienced patient populations.
- Self-testing regulatory pathways:FDA and WHO are developing streamlined prequalification routes for over-the-counter oral fluid kits, opening pharmacy and direct-to-consumer channels.
- Multi-disease platform convergence:Manufacturers are repurposing HIV viral load instruments for tuberculosis and hepatitis C co-detection, amortizing capital costs across disease programs.
Industry Challenges
- Bioinformatics skill scarcity:Resistance test interpretation requires trained personnel capable of analyzing sequence mutations against Stanford HIVdb algorithms.
- Dual certification timelines:Simultaneous FDA clearance and WHO prequalification submissions demand parallel clinical validation studies, extending product launch schedules by eighteen to thirty months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HIV Diagnosis Market |
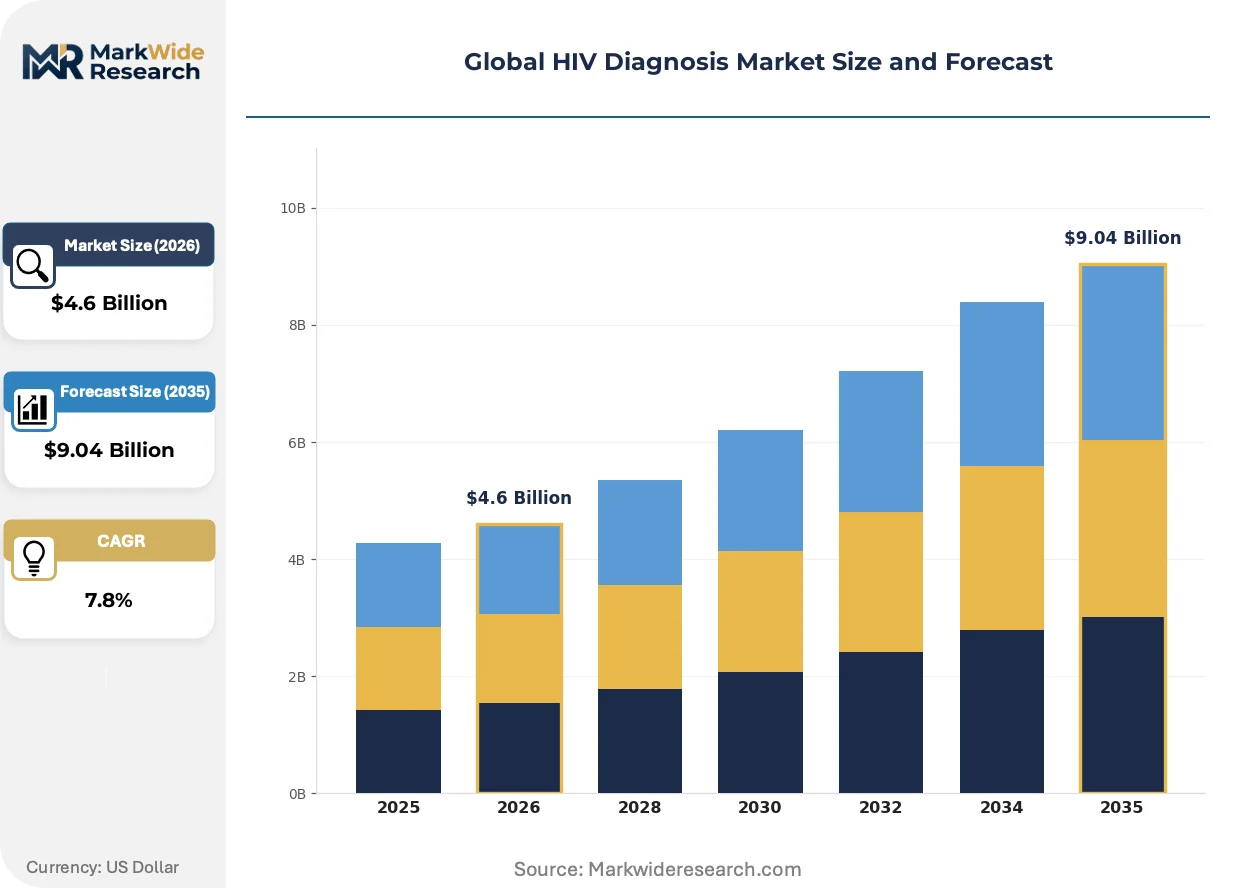
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Diagnostic Tests, Enzyme-Linked Immunosorbent Assay, Western Blot, Nucleic Acid Amplification Tests, Immunofluorescence Assay Technology: Chemiluminescence Immunoassay, Polymerase Chain Reaction, Flow Cytometry, Electrochemiluminescence, Microfluidics Application: Early Detection, Viral Load Monitoring, CD4 Count, Resistance Testing, Mother-to-Child Transmission Screening End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutes, Public Health Organizations |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Danaher Corporation, F. Hoffmann-La Roche Ltd., Becton, Dickinson and Company, bioMérieux, OraSure Technologies, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HIV Diagnosis Market Shifts & Advancements
Molecular workflows are compressing from batch-processed laboratory assays toward cartridge-based systems operable at peripheral health posts, with regulatory frameworks racing to validate quality at decentralized points of care.
Isothermal amplification chemistries such as LAMP and RPA are migrating from research-stage validation toward national procurement lists. Ministries of health in Uganda and Zambia are piloting these platforms for same-day infant diagnosis results. The technology is migrating from reference laboratory exclusivity toward community-based treatment initiation, collapsing the turnaround time between sample collection and antiretroviral therapy start from weeks to hours.
EMA's MDR framework for in vitro diagnostic medical devices is imposing new clinical evidence requirements on HIV assay manufacturers seeking European market access. Class C device classifications now mandate post-market surveillance systems tracking diagnostic accuracy in real-world use. High-complexity molecular platforms face the steepest compliance burden, prompting some manufacturers to deprioritize CE marking in favor of WHO prequalification for African procurement channels.
Service unbundling is separating instrument placement from reagent supply and maintenance contracts in public health tenders. National programs in Mozambique and Malawi are negotiating reagent-only agreements with third-party logistics providers, bypassing traditional bundled leasing structures. This shift is most pronounced in viral load monitoring contracts, where volume guarantees and price-per-test mechanisms are displacing capital-heavy instrument donation models.
Global HIV Diagnosis Market Segmentation
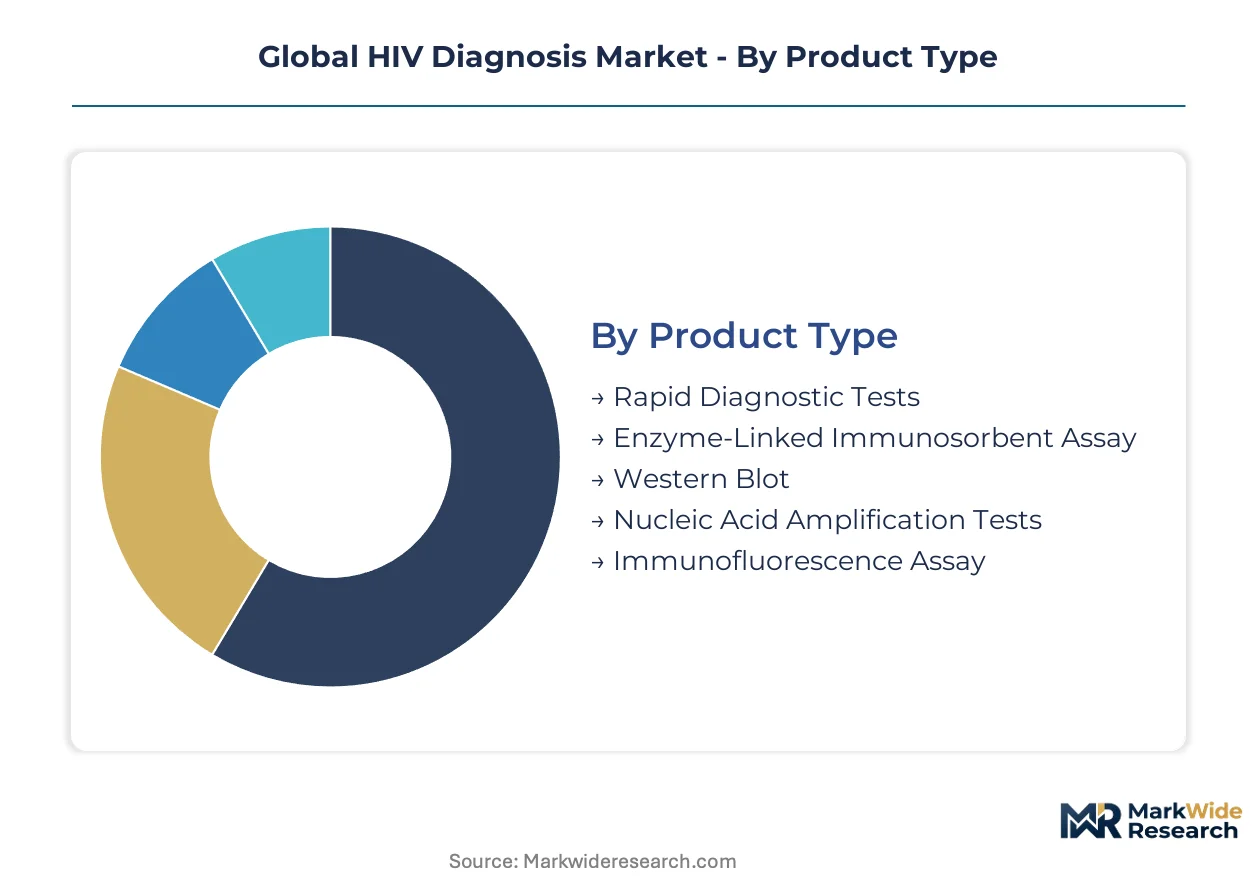
HIV diagnostic procurement splits across five dimensions that determine pricing power, regulatory pathway, and channel strategy. Product type and technology choices dictate whether manufacturers compete on volume contracts or premium margins, while application and end-user segmentation reveals where decentralized testing is displacing centralized laboratory workflows.
Product Type:
Cost tier stratification separates commodity screening tools from high-complexity molecular platforms, with procurement authority fragmenting accordingly.
- Rapid Diagnostic Tests:Lateral flow immunoassays detect HIV antibodies in whole blood, serum, or oral fluid within 15-30 minutes without instrumentation. National programs in South Africa and Nigeria procure these at scale for community screening, with WHO prequalification serving as the gatekeeper to tender participation. Cold-chain independence allows deployment to clinics lacking refrigeration.
- Nucleic Acid Amplification Tests:RNA and DNA amplification platforms achieve sensitivity below 50 copies per milliliter for viral load quantification and early infant diagnosis. Demand concentrates in Kenya's national laboratory network and South Africa's centralized reference facilities, where birth testing protocols within six weeks are expanding molecular assay volumes beyond traditional antibody screening.
- Enzyme-Linked Immunosorbent Assay:Laboratory-based antibody detection with higher throughput than rapid tests but requiring trained technicians and equipment.
- Western Blot:Confirmatory serological testing with high specificity, deployed primarily in reference laboratories for discordant rapid test resolution.
- Immunofluorescence Assay:Fluorescent antibody detection for research and specialized clinical applications with limited routine screening deployment.
Rapid Diagnostic Tests command the established base. The steepest expansion runs through Nucleic Acid Amplification Tests.
Technology:
Application specificity distinguishes batch-processed laboratory methods from miniaturized platforms operable at peripheral health posts.
- Microfluidics:Chip-based systems integrate sample preparation, amplification, and detection into cartridge formats operable by community health workers without laboratory infrastructure. Ministries of health in Uganda and Zambia are piloting these platforms for same-day infant diagnosis results, collapsing turnaround from weeks to hours.
- Polymerase Chain Reaction:Thermal cycling amplification remains the gold standard for viral load quantification and genotypic resistance testing, dominating high-throughput hospital and reference laboratory installations.
- Chemiluminescence Immunoassay:Automated antibody detection with high throughput for blood bank screening and large-scale serosurveillance.
- Flow Cytometry:Cell-based analysis for CD4 T-cell enumeration in treatment monitoring, concentrated in centralized immunology laboratories.
- Electrochemiluminescence:High-sensitivity detection chemistry for quantitative viral antigen and antibody measurement in premium laboratory segments.
Polymerase Chain Reaction anchors current revenue. Microfluidics is climbing the fastest as manufacturers miniaturize molecular workflows for resource-limited settings.
Application:
Clinical utility determines whether assays serve population-wide screening or targeted therapeutic management.
- Early Detection:Serological and nucleic acid screening for acute infection identification, with national programs in Nigeria mandating expanded testing access points.
- Viral Load Monitoring:Quantitative RNA measurement to assess antiretroviral therapy effectiveness, now standard of care in South Africa's treatment cascade.
- CD4 Count:Lymphocyte enumeration for immune status assessment, declining in priority as treat-all policies reduce dependence on threshold-based initiation.
- Resistance Testing:Genotypic and phenotypic assays for antiretroviral failure management, expanding with integrase inhibitor rollouts in treatment-experienced populations.
- Mother-to-Child Transmission Screening:Infant diagnosis protocols requiring nucleic acid testing within six weeks of birth, now policy in Kenya and scaling across sub-Saharan Africa.
Early Detection generates the highest test volumes. Resistance Testing is gaining share fastest as first-line regimen failures accumulate.
End User:
Customer type dictates procurement mechanism, with public health tenders operating on fundamentally different terms than private laboratory purchasing.
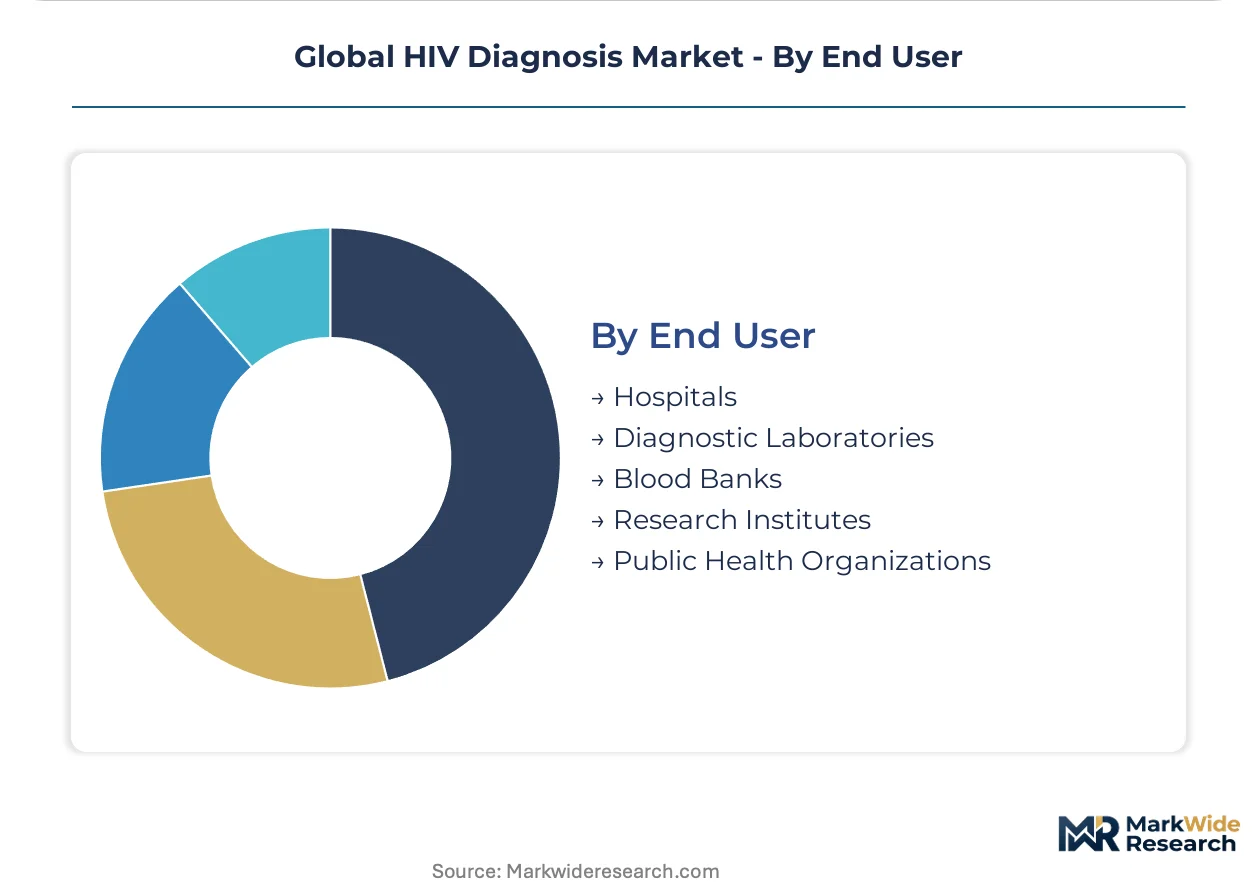
- Public Health Organizations:Ministries of health and national AIDS control programs in Mozambique and Malawi negotiate reagent-only agreements with third-party logistics providers, bypassing traditional bundled instrument leasing. Volume guarantees and price-per-test mechanisms are displacing capital-heavy donation models.
- Diagnostic Laboratories:Independent and hospital-affiliated facilities purchase through distributor networks, with automated high-throughput systems concentrated in South Africa's national laboratory network.
- Hospitals:Acute care facilities requiring rapid turnaround for inpatients and emergency settings, driving point-of-care platform adoption.
- Blood Banks:Serological screening for donated blood units, with chemiluminescence systems dominating high-volume processing.
- Research Institutes:Academic and clinical trial sites utilizing resistance testing and novel assay validation for protocol development.
Public Health Organizations dominate procurement volume. Diagnostic Laboratories represent the most contested competitive arena as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health procurement authorities in sub-Saharan Africa concentrate the largest diagnostic volumes, while North American and European markets anchor premium technology development and regulatory validation pathways for new assay platforms.
South Africa
The National Health Laboratory Service operates the continent's largest centralized viral load monitoring network, processing millions of tests annually through automated high-throughput systems. WHO prequalification standards filter supplier participation in national tenders, consolidating awards to manufacturers with validated cold-chain stability data. Cape Town and Johannesburg host the primary reference laboratory clusters where resistance testing capacity is expanding alongside integrase inhibitor rollouts.
United States
FDA clearance pathways shape global product development timelines, with over-the-counter self-test regulatory routes opening pharmacy and direct-to-consumer channels. The Ryan White HIV/AIDS Program funds diagnostic access for uninsured populations, sustaining demand across safety-net health systems. Boston and San Francisco anchor the academic research clusters where novel microfluidics platforms undergo clinical validation before international deployment.
Kenya
National early infant diagnosis protocols mandate nucleic acid testing within six weeks of birth, expanding molecular assay volumes beyond traditional antibody screening. The country's pharmaceutical regulator enforces import quality standards that align with WHO prequalification benchmarks. Nairobi's national laboratory network serves as the distribution hub for point-of-care platforms piloted in rural Western Province clinics.
Germany
EMA's MDR framework for in vitro diagnostic medical devices imposes clinical evidence requirements that extend product launch schedules for European market entry. Automated chemiluminescence systems dominate hospital laboratory procurement, with blood bank screening driving high-volume serological testing demand. Munich and Heidelberg concentrate the research institutes developing next-generation resistance testing algorithms.
India
CDSCO oversight of imported diagnostics creates parallel regulatory pathways alongside WHO prequalification for African export markets. National AIDS control programs are scaling point-of-care testing in high-prevalence states, with molecular capacity concentrated in tertiary medical centers. Mumbai and Delhi host the primary distributor networks supplying reagent-only agreements to third-party logistics providers across South Asian procurement channels.
Global HIV Diagnosis Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The market structure consolidates around manufacturers with dual FDA and WHO prequalification status, while regional distributors capture margin in reagent logistics. Three archetypes dominate: integrated diagnostics conglomerates with full-platform portfolios, molecular specialists focused on viral load and resistance testing, and rapid-test pure-plays optimized for cold-chain-independent deployment. Competitive moves center on service unbundling to secure reagent-only contracts and microfluidics miniaturization to displace centralized laboratory workflows.
Among North American-based diagnostics conglomerates, Abbott Laboratories and OraSure Technologies occupy distinct positioning archetypes that exemplify the channel-control versus product-specialist divide. Siemens Healthineers, a German GmbH-structured entity, represents the European automated systems tier. These three companies anchor the competitive landscape without exhausting its structural complexity.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Becton, Dickinson and Company |
| bioMérieux |
| OraSure Technologies |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Reagent cold-chain vulnerability determines both pricing tier spreads and supply chain shape across HIV diagnostic procurement networks. Temperature-sensitive nucleic acid amplification chemistries require continuous 2-8°C logistics, forcing manufacturers to absorb premium freight costs or cede margin to third-party cold-chain specialists.
Pricing Analysis
Cost-plus contracts with WHO prequalification indexation dominate public health tenders in sub-Saharan Africa. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with FDA-cleared molecular platforms commanding 40-60% premiums over WHO-prequalified equivalents. Cost compression in rapid diagnostic tests is intensifying as serial testing protocols displace some molecular confirmation demand. Ministries of health in Mozambique and Malawi exhibit highest price sensitivity, while South Africa's National Health Laboratory Service prioritizes throughput reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Jabil, Flex, and specialized IVD contract manufacturers holding cartridge and instrument assembly capacity. Supply draws from precision injection molding clusters in Germany, optical component suppliers in Japan, and printed circuit board fabricators in Taiwan. Single-source vulnerability persists for specialized enzymes and fluorescent probes used in isothermal amplification chemistries. Distribution runs through national laboratory networks in Kenya and South Africa, with third-party logistics providers increasingly managing reagent-only fulfillment to peripheral clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care nucleic acid testing represents an early-cycle expansion story, with microfluidics miniaturization collapsing turnaround times from weeks to hours in resource-limited settings.
For Market Incumbents: Harden cold-chain logistics partnerships to defend reagent supply contracts against emerging cartridge-based competitors. Deepen backward integration into enzyme manufacturing to reduce dependency on single-source biochemical suppliers. Anchor position through instrument placement with long-term service agreements that resist unbundling pressures from national procurement authorities. For New Entrants and Emerging Players: Rural Western Province clinics in Kenya offer underpenetration for suitcase-size molecular platforms operable by community health workers. Target Uganda and Zambia pilot programs seeking same-day infant diagnosis results. Pursue WHO prequalification-first regulatory strategy to bypass FDA timeline disadvantages in African tender participation. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors dual-certification manufacturers with validated cold-chain data. Long-term viability rests on resistance testing expansion and multi-disease platform convergence across tuberculosis and hepatitis C applications. Monitor integrase inhibitor rollout pace as demand inflection signal for genotypic resistance assay volumes.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Fast-Track | Abbott and Roche leverage streamlined pathways to secure African ministry tenders before CE marking completion. |
| Microfluidics Cartridge Development | Chip-based platforms reduce instrument footprints for deployment in clinics lacking laboratory infrastructure. |
| Multi-Disease Platform Repurposing | HIV viral load instruments extend to tuberculosis and hepatitis C detection, amortizing capital costs. |
| Reagent-Only Logistics Partnerships | Third-party providers in Malawi bypass bundled leasing structures with volume-guarantee contracts. |
| Resistance Testing Algorithm Investment | Stanford HIVdb integration requirements drive bioinformatics capability acquisition in treatment-experienced populations. |
Research Methodology
Desk research of WHO prequalification databases, national procurement tender records, and FDA 510(k) filings preceded structured interviews with ministry of health procurement officers, IVD regulatory affairs leads, and biomedical engineers at reference laboratories. Primary fieldwork with GPO contracts managers and cold-chain logistics specialists combined with secondary validation against EMA MDR guidance documents and import quality standards from CDSCO. Bottom-up test volume modeling and top-down market sizing triangulated across public health program expenditure reports.
Assumptions held constant include WHO prequalification criteria evolution timelines and national HIV program funding continuity, while variables included point-of-care adoption rates and resistance testing protocol expansion. The analytical framework segments by product type, technology platform, application purpose, and end-user procurement mechanism across the projection horizon. CAGRs derived from logistic diffusion curves for platform replacement cycles, with viral load monitoring frequency and early infant diagnosis coverage as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese IVD manufacturers with cost-optimized cartridge platforms would shift outcomes through price disruption in rapid diagnostic segments. Quarterly review of WHO prequalification list updates and national tender award announcements is advised to detect inflection in procurement authority fragmentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Diagnostic Reagents Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
Elisa Tests Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Europe Breast Cancer Screening Tests Market