
 Livestock Diagnostics Market | 2026-2036
Livestock Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock Diagnostics Market Intelligence
Software-as-a-Service (SaaS) subscriptions for data analytics and herd health management is restructuring the traditional one-time sale model for diagnostic equipment. IDEXX Laboratories leverages its extensive installed base to promote these recurring revenue services. Zoetis competes by integrating its diagnostic platforms with a broad portfolio of animal health pharmaceuticals. Thermo Fisher Scientific differentiates through its advanced genetic sequencing technologies applied to animal health.
Livestock diagnostics involve assays and instrumentation used to detect pathogens, monitor health, and assess genetic traits in production animals like cattle, swine, and poultry. These systems often rely on molecular techniques like PCR, which can detect specific nucleic acid sequences of viruses or bacteria, crucial for preventing widespread outbreaks. Test kits, particularly those based on ELISA and Lateral Flow technologies, command a significant share due to their use in routine on-farm and laboratory screening. The genetic screening application segment represents the fastest-growing area, driven by the push for improved herd genetics and productivity.
Regulations from bodies like the USDA's Animal and Plant Health Inspection Service (APHIS) in the United States mandate testing for specific transboundary diseases. The European Medicines Agency (EMA) and China's Ministry of Agriculture and Rural Affairs set stringent standards for diagnostic test validation and approval, shaping market access. Navigating these varied and evolving regulatory pathways for new diagnostic technologies remains a critical decision point for market participants.
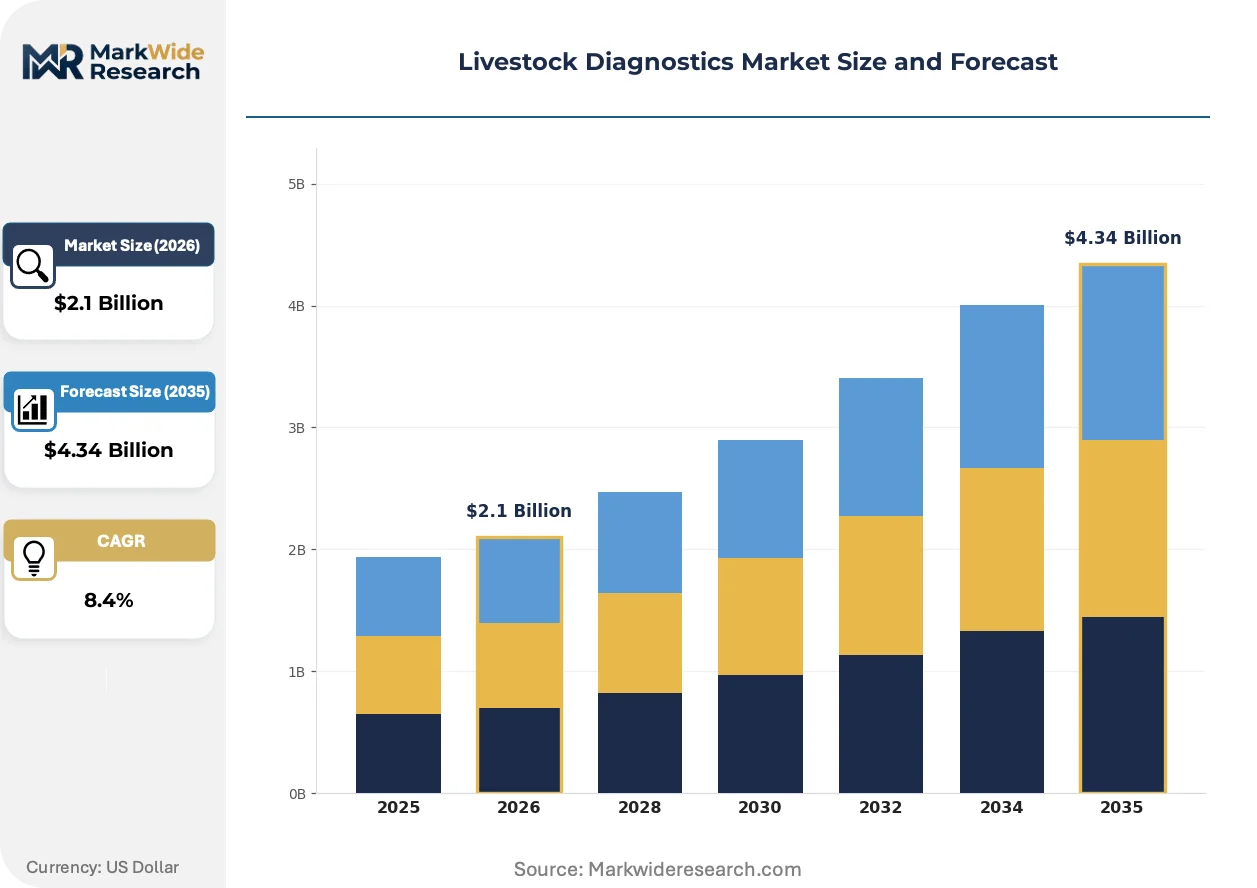
Market Dynamics
The convergence of genomic technologies like Next Generation Sequencing with data analytics platforms is reshaping livestock health management. This shift moves the industry from reactive, single-pathogen testing toward predictive, multi-analyte screening, driven by food safety mandates in key production economies.
Growth Catalysts
- Antimicrobial Stewardship:European Union regulations curbing prophylactic antibiotic use compel producers to adopt diagnostic-led treatment strategies for bacterial infections.
- Food Security Programs:Government initiatives in Brazil and China to secure food supplies are funding large-scale disease surveillance programs using PCR and ELISA tests.
- Genomic Selection Tools:The commercialization of genomic evaluation for cattle and swine drives uptake of genetic screening to improve herd resilience and productivity.
Market Restraints
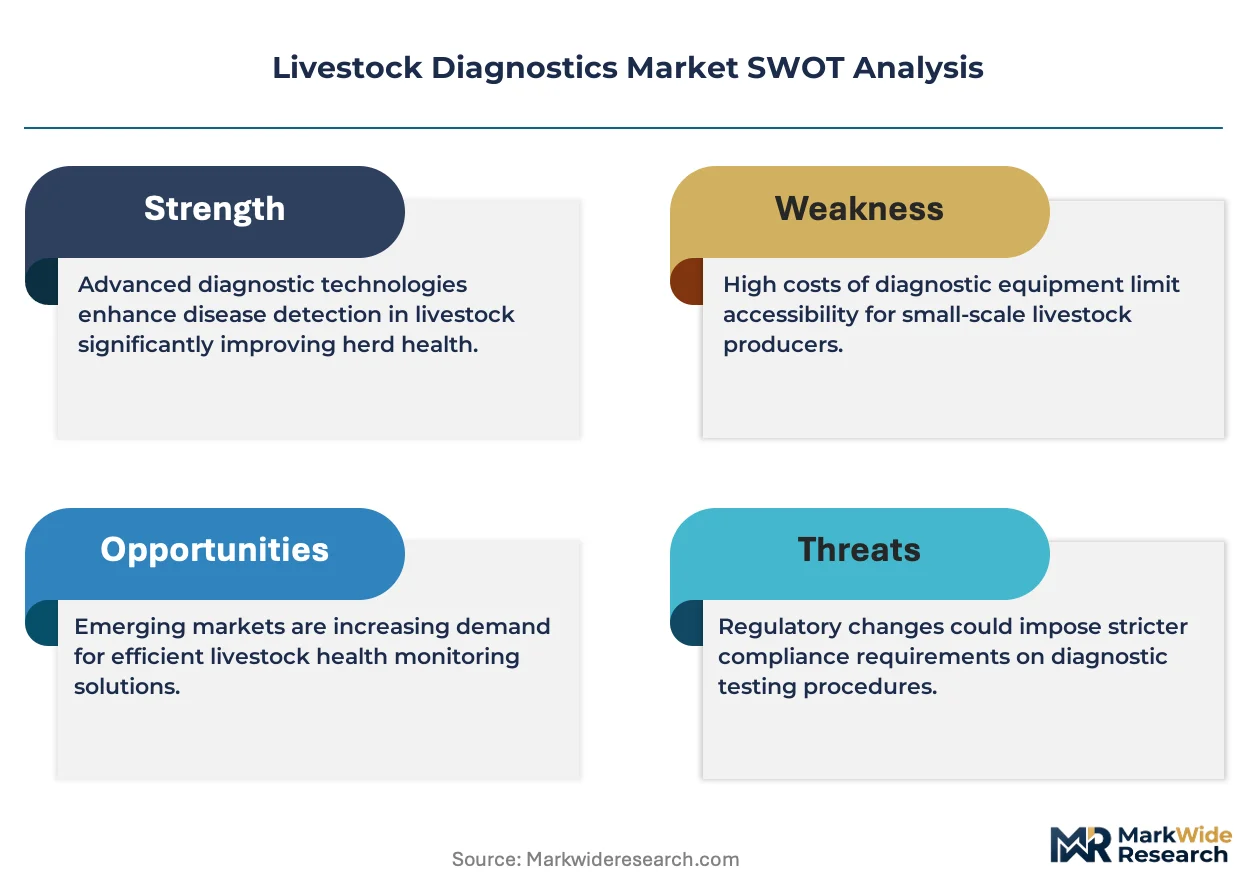
- High Capital Investment:The significant upfront cost for advanced diagnostic systems like PCR and NGS platforms limits adoption by small and medium-sized farms.
- Limited Pen-Side Multiplexing:A scarcity of validated on-farm multiplex tests for simultaneous pathogen detection slows rapid decision-making during outbreaks.
- Fragmented Regulatory Pathways:Disparate and lengthy approval processes from the USDA and EMA for new diagnostic assays delay market entry for innovators.
Strategic Opportunities
- Aquaculture Disease Diagnostics:The fast-growing aquaculture industry in Southeast Asia represents an untapped market for diagnostics targeting pathogens in shrimp and finfish.
- AI-Powered Analytics:Integrating AI with diagnostic data from sources like PCR results enables predictive models for subclinical disease detection in large herds.
- Subscription-Based Data Services:Shifting from equipment sales to SaaS models for herd health analytics provides a recurring revenue stream and deepens customer relationships.
Industry Challenges
- Bioinformatics Skill Gaps:A shortage of veterinarians and technicians skilled in data analytics and genomics limits the effective use of advanced diagnostic information on farms.
- Data Interoperability:The lack of standardized data formats across different diagnostic platforms and farm management systems hinders the creation of comprehensive herd health databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock Diagnostics Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Biosensors, DNA Sequencers, Immunoassays, Rapid Test Devices Technology: Polymerase Chain Reaction, ELISA, Microarray, Lateral Flow, Next Generation Sequencing Application: Disease Detection, Nutritional Monitoring, Reproductive Health, Pathogen Identification, Genetic Screening End User: Livestock Farms, Veterinary Clinics, Animal Health Laboratories, Research Institutes |
| Companies Covered | IDEXX Laboratories, Zoetis, Thermo Fisher Scientific, Bio-Rad Laboratories, bioMérieux, Neogen Corporation, Heska Corporation, QIAGEN, Antech Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock Diagnostics Market Strategic Shifts & Innovations
Technological advancements are transitioning livestock diagnostics from single-event lab tests to continuous, data-driven health monitoring. This evolution is driven by the need for real-time decision-making on large-scale farms, supported by hardware and software innovations.
Next Generation Sequencing (NGS) provides comprehensive pathogen identification and genetic analysis from a single sample. Large commercial producers and veterinary labs are adopting this technology for complex disease investigations and genomic selection. The high-throughput nature of NGS is automating large-scale epidemiological surveillance and pathogen discovery.
Heightened biosecurity regulations, like the USDA's Animal Disease Traceability rule, mandate improved health documentation for interstate livestock movement. These rules create a compliance-driven market for diagnostics integrated with digital animal ID systems. Cattle producers are most affected, requiring certified test results for diseases like brucellosis to facilitate commerce.
Subscription-based service models are gaining traction, separating data analytics from the initial hardware sale. This model disrupts traditional capital expenditure, replacing it with a recurring expense that includes continuous software updates. The shift is most visible among large poultry and swine producers in the US and Brazil for enterprise-wide health management.
Livestock Diagnostics Market Segmentation
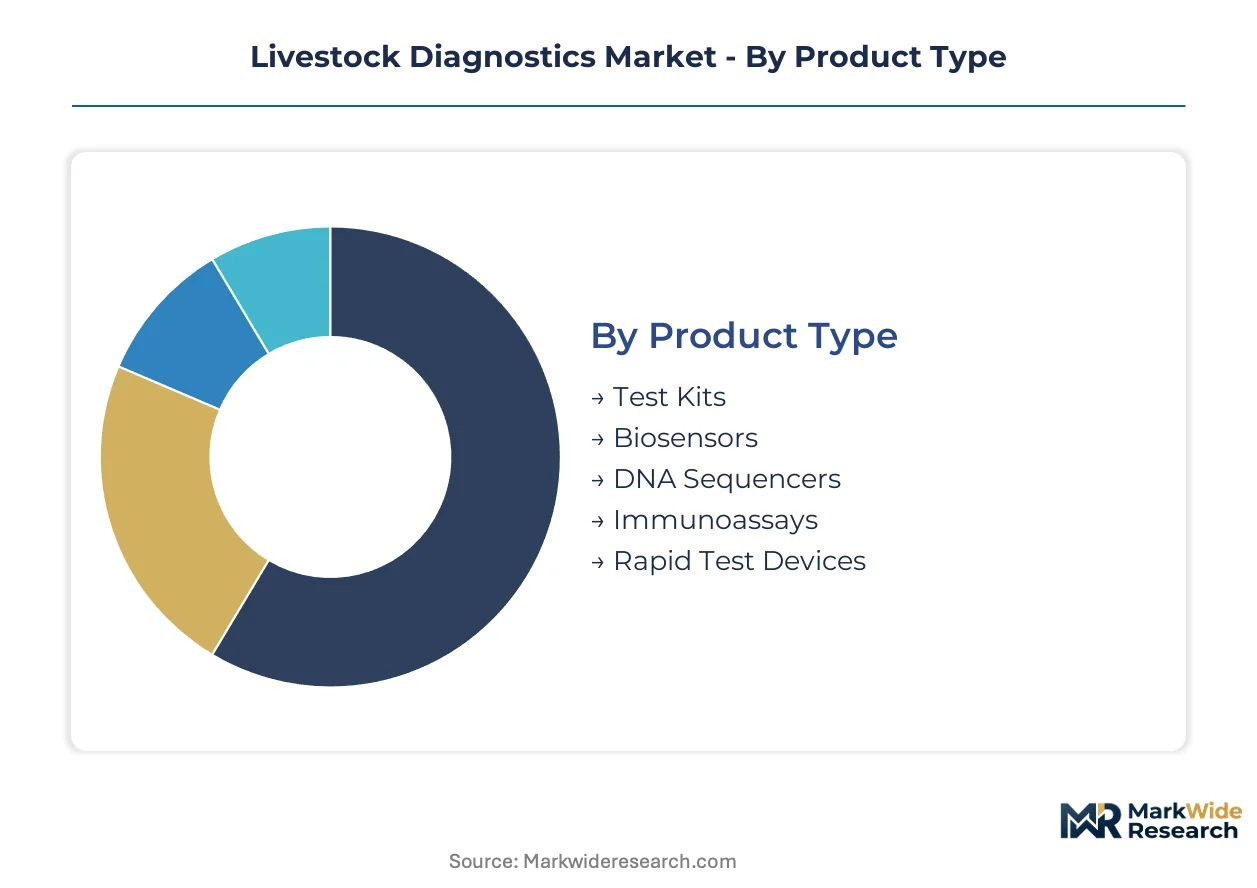
The Livestock Diagnostics Market segmentation provides a detailed understanding of how diverse demands and technological advancements shape product development and market penetration. Analyzing these segments reveals key adoption patterns and strategic opportunities for industry participants.
Product Type:
Buyers prioritize diagnostic product types based on accuracy, speed, and ease of use in diverse farm settings.
- Test Kits:These integrated assays provide all necessary reagents for specific pathogen detection or health monitoring. Demand concentrates in large-scale livestock farms in the United States, driven by routine screening requirements.
- Rapid Test Devices:These portable, often lateral flow-based devices offer quick, on-site results for immediate decision-making. Adoption is accelerating among poultry and swine producers in Brazil for outbreak management.
- Biosensors:Biosensors offer real-time, continuous monitoring capabilities for physiological parameters or pathogen presence.
- DNA Sequencers:DNA sequencers enable detailed genetic analysis and comprehensive pathogen identification for advanced applications.
- Immunoassays:Immunoassays detect specific antibodies or antigens, crucial for disease surveillance and vaccine efficacy assessment.
Volume sits with Test Kits; growth tilts toward DNA Sequencers.
Technology:
The choice of diagnostic technology depends on the required sensitivity, specificity, and throughput for various animal health applications.
- Next Generation Sequencing:NGS platforms provide high-throughput genetic and pathogen analysis, offering comprehensive insights from a single sample. Large commercial producers and veterinary labs in China adopt NGS for complex disease investigations.
- Polymerase Chain Reaction:PCR amplifies specific DNA/RNA sequences, enabling highly sensitive and specific detection of viral and bacterial pathogens. Demand is significant in European Union nations for mandated disease surveillance.
- ELISA:ELISA tests detect antibodies or antigens, widely used for serological surveillance and disease confirmation.
- Lateral Flow:Lateral flow assays provide rapid, portable, and cost-effective on-site diagnostic results.
- Microarray:Microarray technology allows simultaneous detection of multiple genetic markers or pathogens from a single sample.
The market is anchored by Polymerase Chain Reaction, with Next Generation Sequencing showing the steepest expansion trajectory.
Application:
Regulatory mandates and food safety concerns significantly influence the adoption patterns across different livestock diagnostic applications.
- Genetic Screening:This application involves analyzing an animal's genetic makeup for traits like disease resistance, productivity, and breeding potential. It represents the fastest-growing area, driven by genomic selection programs for cattle and swine.
- Disease Detection:This broad application focuses on identifying the presence of specific pathogens or health conditions in livestock populations. It underpins large-scale surveillance programs mandated by bodies like the USDA's Animal and Plant Health Inspection Service (APHIS).
- Pathogen Identification:Pathogen identification precisely pinpoints the causative agents of disease, crucial for targeted treatment and outbreak control.
- Reproductive Health:Diagnostics in reproductive health monitor fertility, detect pregnancy, and identify reproductive disorders in breeding animals.
- Nutritional Monitoring:Nutritional monitoring applications assess an animal's dietary status and nutrient deficiencies to optimize feed efficiency.
While Disease Detection commands substantial volume, Genetic Screening is gaining share fastest.
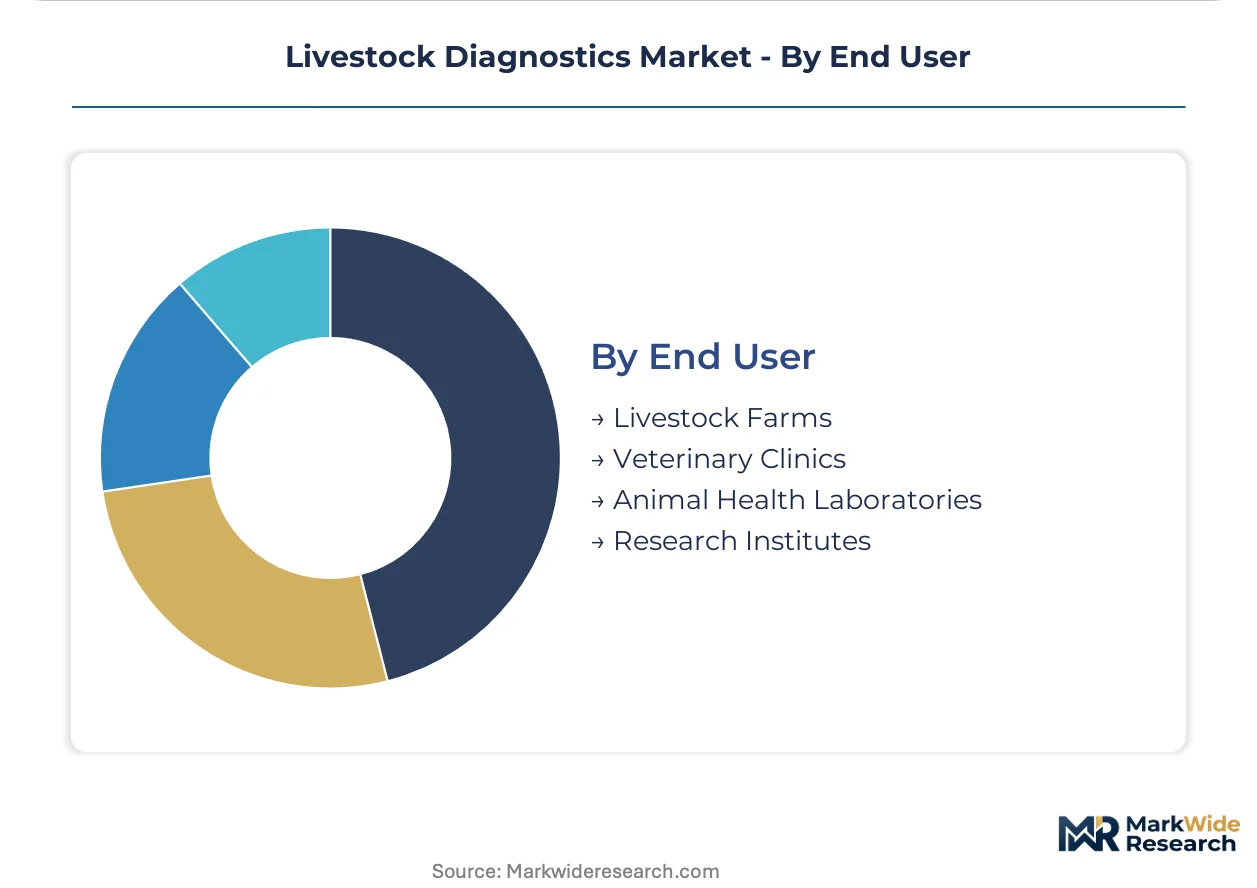
End User:
The scale of livestock operations and available infrastructure dictate the type and complexity of diagnostic solutions adopted by various end-user segments.
- Livestock Farms:This segment comprises commercial farms, from large industrial operations to smaller family-run enterprises, utilizing diagnostics for herd health management. Large-scale farms in the United States and Brazil are adopting advanced systems for early disease detection.
- Animal Health Laboratories:These centralized facilities perform complex diagnostic tests, pathogen identification, and genetic analysis for veterinary practitioners and large producers. They serve as critical hubs for disease surveillance and confirmatory testing.
- Veterinary Clinics:Veterinary clinics utilize diagnostics for individual animal health assessments, disease diagnosis, and treatment monitoring.
- Research Institutes:Research institutes employ advanced diagnostic tools for studying animal diseases, developing new therapies, and improving breeding programs.
The largest share resides with Livestock Farms, with Animal Health Laboratories exhibiting rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global livestock diagnostics market exhibits a clear divide between major production economies and consumption hubs. Large-scale livestock farms in nations like the United States and Brazil drive significant demand for advanced diagnostic solutions. Food security mandates and disease surveillance programs further shape adoption patterns across diverse geographies.
United States
Demand for livestock diagnostics in the United States stems from routine screening requirements and early disease detection for herd health management. The USDA's Animal and Plant Health Inspection Service (APHIS) mandates testing for specific transboundary diseases, ensuring compliance. Large commercial farms in the Midwest utilize sophisticated diagnostic systems for continuous monitoring and rapid response.
China
China's livestock diagnostics market is propelled by government food security programs, complex disease investigations, and comprehensive pathogen analysis. The Ministry of Agriculture and Rural Affairs sets stringent standards for diagnostic test validation and approval. Veterinary labs in major agricultural provinces adopt Next Generation Sequencing for epidemiological surveillance and pathogen discovery.
Brazil
Brazil's market experiences strong demand for outbreak management, large-scale disease surveillance, and enterprise-wide health management. Government initiatives to secure food supplies fund extensive diagnostic programs across the country. Poultry and swine producers in the Southern states accelerate adoption of rapid test devices for immediate decision-making during health events.
Germany
Germany's livestock diagnostics adoption is driven by mandated disease surveillance, antimicrobial stewardship, and genetic trait assessment programs. European Union regulations curbing prophylactic antibiotic use compel producers to adopt diagnostic-led treatment strategies for bacterial infections. Animal health laboratories in Bavaria serve as critical hubs for PCR-based testing and confirmatory diagnostics.
India
India's demand for livestock diagnostics focuses on improving herd genetics, increasing productivity, and pathogen identification for disease control. The country's national animal health authority implements programs to enhance livestock disease management and biosecurity. Research institutes and large dairy farms in states like Punjab and Uttar Pradesh utilize advanced diagnostic tools for breeding and health monitoring.
Livestock Diagnostics Market Key Industry Players
Top-tier vendors anchor comprehensive diagnostic solutions, while specialized firms focus on niche technologies or specific livestock segments, creating a tiered market structure. A few large players offer integrated platforms, driving consolidation within the industry. Strategic archetypes include diversified animal health giants, specialized diagnostic providers, and technology-focused innovators. Competitive moves revolve around strategic partnerships for data integration, continuous portfolio diversification into advanced genomic tools, and geographic expansion into key livestock-producing nations.
Within the diversified animal health archetype, IDEXX Laboratories and Zoetis exemplify companies leveraging extensive installed bases and broad portfolios to promote recurring revenue services for herd health management. Thermo Fisher Scientific, a globally recognized life science solutions provider, occupies a position focused on advanced genetic sequencing technologies applied to animal health. These entities anchor strategic shifts towards integrated diagnostic platforms and data-driven herd management solutions, driving the adoption of sophisticated tools across various livestock operations. Their presence highlights the industry's move towards comprehensive, rather than single-point, diagnostic offerings.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| bioMérieux |
| Neogen Corporation |
| Heska Corporation |
| QIAGEN |
| Antech Diagnostics |
| Others |
Cost & Logistics Intelligence
European Union regulations curbing prophylactic antibiotic use gate both qualified diagnostic supply and premium-tier pricing access for solutions supporting antibiotic-free livestock production. This regulatory push elevates the value of precise, early disease detection technologies. Providers offering validated diagnostic tools that enable targeted treatment strategies gain a competitive advantage in markets with stringent antimicrobial stewardship mandates.
Pricing Analysis
Cost-down pressure on routine test kits accelerates as large-scale farms seek economies of scale for frequent screening. Pricing stratifies across premium, standard, and economy tiers based on assay sensitivity and specificity. Price differentiation stems from diagnostic accuracy and the level of integrated data analytics provided. Small and medium-sized farms exhibit higher price sensitivity for upfront equipment purchases, whereas large commercial operations prioritize value from recurring SaaS subscriptions.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of critical reagents for molecular diagnostics. Geographic supply concentration for these advanced components centers in China, the United States, and Germany. Key raw material dependencies include enzymes for PCR amplification and specific antibodies for ELISA kits. Regulatory restrictions and lengthy approval processes in different regions pose a structural risk to new product introduction. Distribution runs through direct sales channels to large farms and laboratories, alongside veterinary distributors serving smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mandated disease surveillance by bodies like the USDA's Animal and Plant Health Inspection Service (APHIS) frames this market as a cost-of-compliance story. These regulations create a significant barrier-to-entry moat for compliant players offering validated diagnostic solutions.
For Market Incumbents: To counter fragmentation from specialized technology firms, incumbents should acquire companies developing advanced multiplexing capabilities. Deepen existing SaaS offerings by integrating AI-powered predictive analytics for subclinical disease detection. Leverage extensive installed bases to cross-sell genetic screening tools, reinforcing customer lock-in and recurring revenue streams.
For New Entrants and Emerging Players: Begin with niche applications in underserved markets, such as aquaculture disease diagnostics in Southeast Asia. Develop rapid, pen-side multiplex tests that address the scarcity of validated on-farm solutions for simultaneous pathogen detection. Focus go-to-market strategies on subscription-based data services to mitigate high capital investment for smaller producers.
For Investors and Strategic Acquirers: Widespread adoption of genomic evaluation for cattle and swine by mid-sized farms is the leading indicator that the market is entering a new growth phase. Long-term viability is strong, driven by food security concerns and antimicrobial stewardship mandates. Target acquisition profiles include firms specializing in Next Generation Sequencing technologies or AI-driven diagnostic platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch NGS-based multiplex panels | This expands pathogen identification capabilities for complex disease investigations in large commercial farms. |
| Form strategic partnerships with data analytics firms | Integrating AI with diagnostic data enables predictive models for subclinical disease detection in large herds. |
| Acquire specialist firms in aquaculture diagnostics | This taps into the fast-growing aquaculture industry in Southeast Asia, representing an untapped market. |
| Expand geographic presence into Brazil and China | These nations fund large-scale disease surveillance programs and have significant livestock production. |
| Invest in regulatory approval pathways for novel rapid tests | Navigating fragmented regulatory pathways accelerates market entry for innovators with new diagnostic assays. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. The study combined insights from primary interviews with veterinary practitioners, farm managers, diagnostic lab directors, and regulatory officials. This approach ensured a comprehensive understanding of market dynamics and stakeholder perspectives. Bottom-up and top-down triangulation validated market sizing and growth projections.
The analytical framework reconciled multiple data streams across the projection horizon. Segmentation dimensions modeled included product type, technology, application, end user, and regional market dynamics. Compound annual growth rates were derived from historical trends, projected market drivers, and specific forecast inputs such as livestock population growth and disease outbreak frequency.
New disease outbreaks, evolving regulatory shifts, and unforeseen technological breakthroughs are the dominant revision risks. Forecasts reflect assumptions documented through extensive research and expert consultations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Animal Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Anatomic Pathology Market
Diagnostics
US Influenza Diagnostics Market