
 Elisa Tests Market | 2026-2036
Elisa Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Elisa Tests Market Analysis
Aftermarket service revenue is rewriting profit expectations across the ELISA value chain. Thermo Fisher Scientific leverages its installed base of automated processors to sustain recurring consumable pull-through. Bio-Rad Laboratories anchors its position through reagent rental programs that bind diagnostic laboratories to long-term supply contracts. Danaher Corporation competes via integrated workflow platforms that reduce manual intervention in high-throughput settings.
ELISA tests detect and quantify soluble substances such as peptides, proteins, antibodies, and hormones through antigen-antibody binding reactions measured by enzymatic color change, typically using horseradish peroxidase or alkaline phosphatase conjugates with optical density readouts at 450 nm. The primary commercial purpose spans clinical diagnostics, pharmaceutical quality control, and academic biomarker research. Sandwich ELISA configurations command premium positioning in cancer diagnostics due to their superior specificity for large protein analytes. Chemiluminescent detection technology is displacing colorimetric methods in reference laboratories seeking broader dynamic range and lower limits of detection.
The FDA's Quality System Regulation and Clinical Laboratory Improvement Amendments shape instrument validation and operator certification requirements in the United States. In Europe, the In Vitro Diagnostic Regulation and CE marking framework are extending compliance timelines while raising clinical evidence standards for new assay approvals. Stakeholders must monitor how evolving premarket submission pathways in both jurisdictions affect product launch cadence and competitive positioning.
Market Dynamics
Automated liquid handling platforms and chemiluminescent detection systems are compressing turnaround times in diagnostic laboratories while elevating capital barriers for mid-tier facilities. This technological inflection is redistributing testing volume toward consolidated reference networks.
Growth Catalysts
- IVDR Compliance Deadlines:The European Union's extended In Vitro Diagnostic Regulation transition timeline is accelerating assay revalidation investments, pulling forward replacement demand for certified ELISA kits in German and French hospital networks.
- Biopharma QC Expansion:Cell therapy manufacturing scale-up is creating demand for host cell protein quantification assays, with GMP-grade ELISA protocols becoming mandatory release tests for CAR-T batch certification.
- Automated Processor Deployment:Walkaway automation in US reference laboratories is expanding throughput per operator, enabling same-day result delivery for infectious disease panels and reducing manual pipetting error rates.
Market Restraints
- Monoclonal Antibody Supply Concentration:Capture and detection antibody production clusters among Chinese and US contract manufacturers, exposing assay producers to lead time volatility and quality variation risks.
- Instrument Capex Thresholds:Fully automated ELISA workstations require capital commitments exceeding $250,000 per unit, excluding independent clinical laboratories and small research institutions from workflow integration.
- Molecular Assay Substitution:PCR and next-generation sequencing platforms are capturing share in infectious disease diagnostics where pathogen nucleic acid detection offers superior sensitivity for low-titer samples.
Strategic Opportunities
- Point-of-Care Decentralization:Miniaturized microfluidic ELISA cartridges are enabling near-patient testing in Indian and Brazilian primary care settings where laboratory infrastructure remains underdeveloped.
- Veterinary Diagnostics White Space:Companion animal oncology panels and livestock infectious disease surveillance represent untapped application areas with lower regulatory barriers than human clinical assays.
- ISO 15189 Laboratory Accreditation:The international quality standard is mandating traceable calibration and proficiency testing protocols, creating pull-through demand for certified reference materials and external quality control programs.
Industry Challenges
- Assay Validation Talent Scarcity:Clinical laboratories face recruitment gaps for immunochemists capable of executing analytical specificity studies and cross-reactivity matrices under CLIA and CAP guidelines.
- Reagent Cold Chain Integrity:Temperature excursions during conjugate enzyme shipment compromise assay performance, requiring validated packaging and real-time monitoring investments that inflate logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elisa Tests Market |
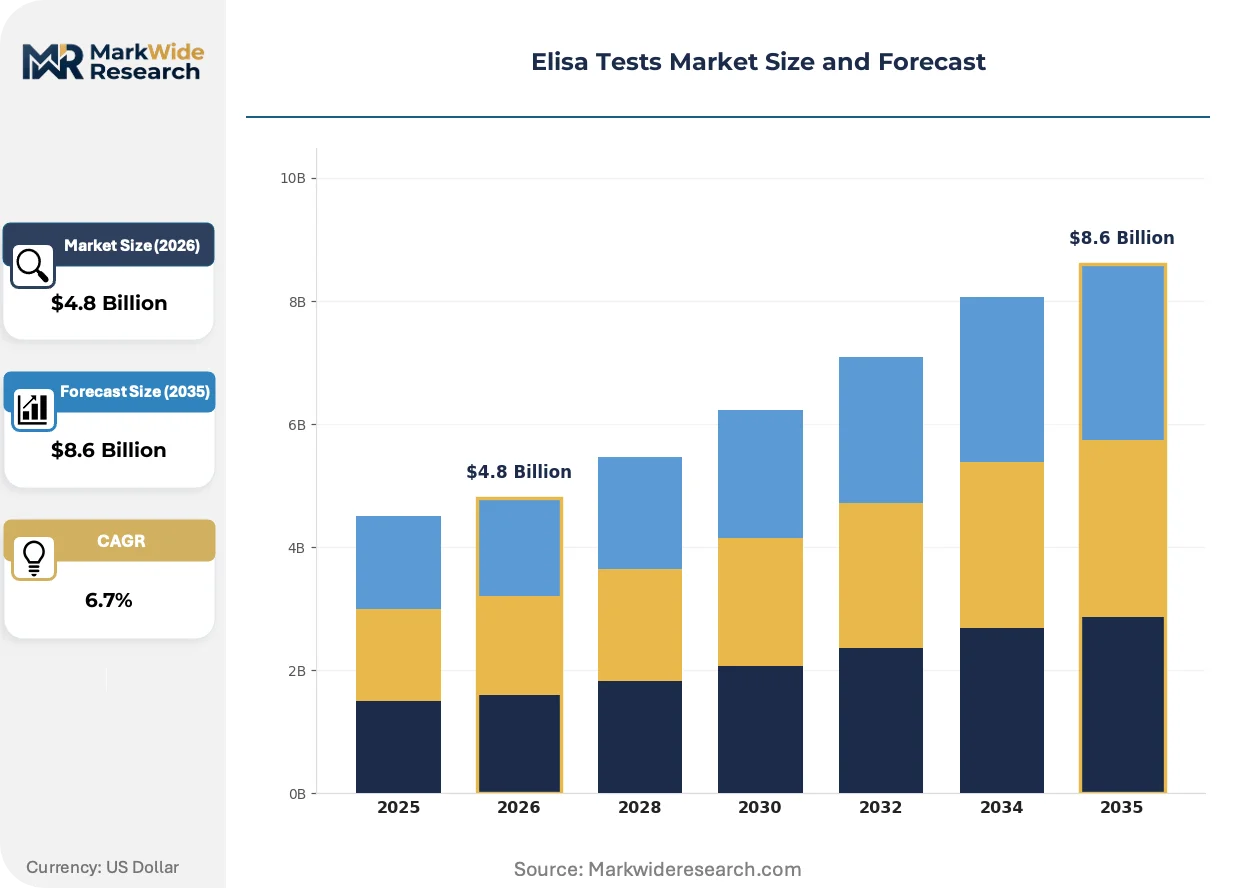
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
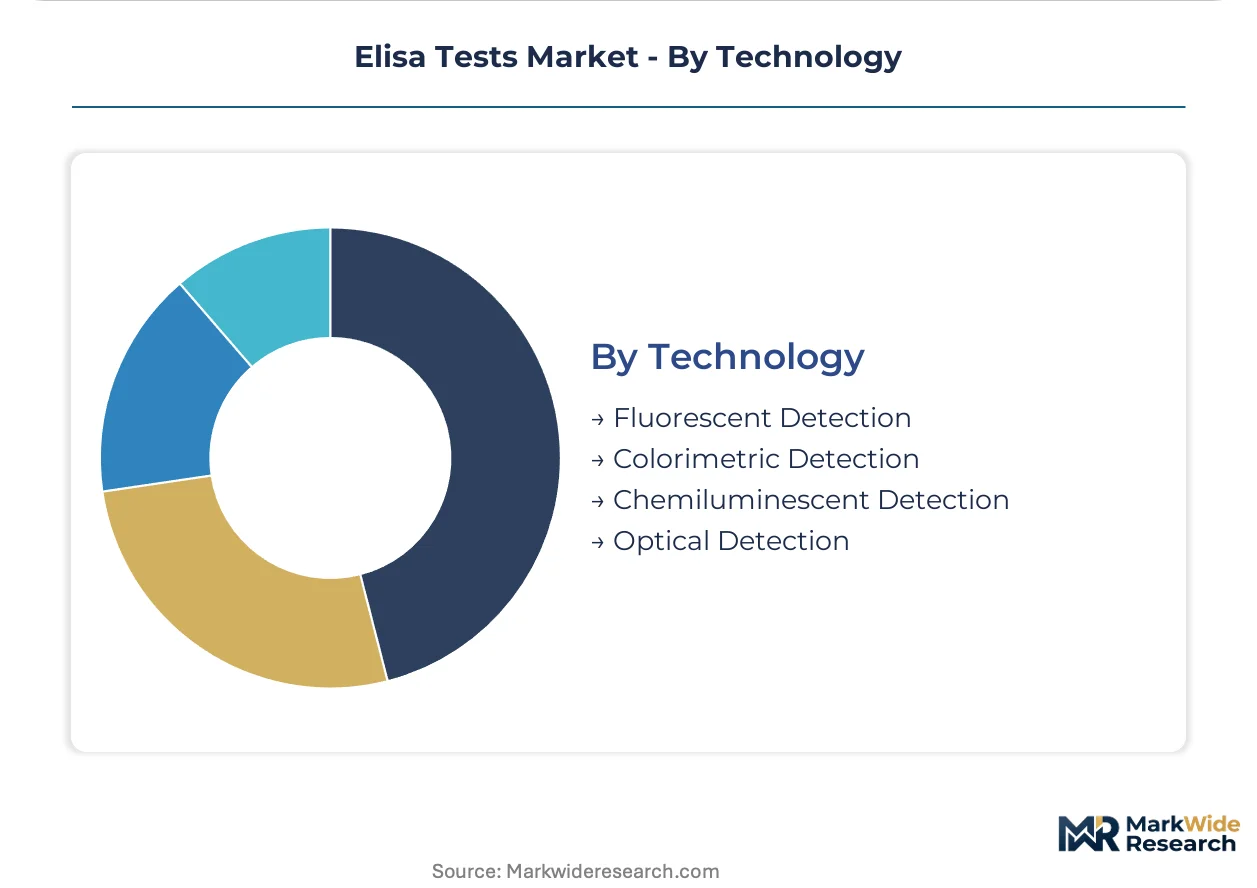
| Segmentation | Product Type: Indirect ELISA, Sandwich ELISA, Competitive ELISA, Quantitative ELISA Application: Infectious Diseases, Autoimmune Disorders, Hormonal Testing, Cancer Diagnostics End User: Diagnostic Laboratories, Research Institutions, Pharmaceutical Companies, Hospitals Technology: Fluorescent Detection, Colorimetric Detection, Chemiluminescent Detection, Optical Detection |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Bio-Techne Corporation, Abcam, Danaher Corporation, F. Hoffmann-La Roche, Merck KGaA, PerkinElmer, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elisa Tests Market Emerging Trajectories
Digital integration and detection chemistry advances are redefining performance benchmarks across the ELISA value chain. These developments are compressing manual intervention requirements while expanding assay multiplexing capabilities.
Multiplex bead-based immunoassays are digitizing protein biomarker quantification by enabling simultaneous measurement of up to 100 analytes per sample well. Reference laboratories in the United States are adopting Luminex and Meso Scale Discovery platforms to consolidate cytokine panels and autoimmune screening into single-run protocols. This convergence is digitizing laboratory information management systems through automated data capture and cloud-based result interpretation.
The FDA's updated guidance on clinical trial assay validation is tightening bridging study requirements for companion diagnostic development. Biopharma sponsors must now demonstrate analytical concordance between investigational use assays and commercial ELISA kits intended for regulatory submission. Oncology biomarker programs are responding by embedding quality control checkpoints earlier in assay development cycles.
Reagent rental contracting is displacing capital purchase models in European diagnostic networks. German hospital procurement consortia are bundling instrument placement with minimum annual consumable commitments, transferring ownership risk to manufacturers while securing predictable revenue streams. This arrangement is most pronounced in Rhineland and Bavaria regions where laboratory consolidation has concentrated purchasing power among three major hospital alliances.
Elisa Tests Market Segmentation
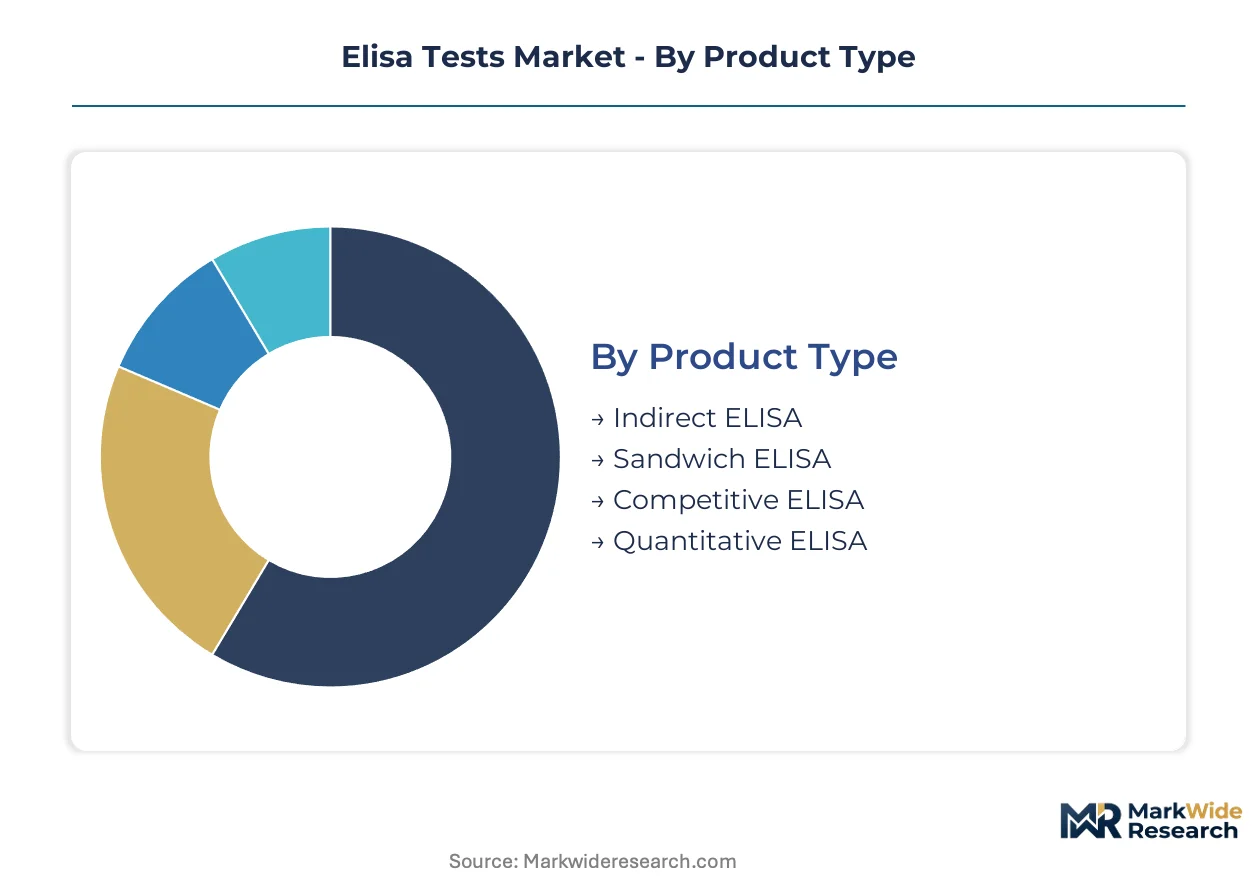
ELISA test segmentation reveals distinct technology-performance tradeoffs that shape procurement decisions across diagnostic settings. Each dimension captures different sources of value capture and competitive differentiation.
Product Type:
Cost tier determines reagent complexity and per-test economics across laboratory workflows.
- Sandwich ELISA:Dual-antibody capture architecture delivers superior specificity for large protein analytes. Demand concentrates in US cancer reference laboratories where biomarker quantification accuracy drives clinical decision-making.
- Indirect ELISA:Secondary antibody amplification enables sensitive detection of host antibodies against pathogens. German hospital networks deploy this format for infectious disease serology panels requiring high throughput at moderate reagent cost.
- Competitive ELISA:Small molecule and hapten quantification using labeled analyte competition. Applied in toxicology and therapeutic drug monitoring.
- Quantitative ELISA:Standard curve-based concentration determination with optical density interpolation. Deployed where absolute analyte levels guide treatment protocols.
Sandwich ELISA commands the established base. The steepest expansion runs through quantitative ELISA as precision medicine protocols proliferate.
Application:
Clinical utility varies by disease area complexity and reimbursement density.
- Cancer Diagnostics:Tumor marker quantification for screening, staging, and therapeutic monitoring. French and Italian oncology networks prioritize this segment for companion diagnostic integration.
- Infectious Diseases:Pathogen-specific antibody and antigen detection. HIV, hepatitis, and COVID-19 serology sustain volume in US public health laboratories.
- Autoimmune Disorders:Anti-nuclear antibody and rheumatoid factor testing. Rheumatology clinics in Japan drive adoption of multiplexed autoimmune panels.
- Hormonal Testing:Reproductive endocrinology and thyroid function assays. Fertility clinics and reference laboratories maintain steady demand.
Infectious disease testing commands the established base. The steepest expansion runs through cancer diagnostics as biomarker-guided therapy protocols multiply.
End User:
Customer type dictates capital intensity and service model requirements.
- Diagnostic Laboratories:High-throughput centralized testing with automated platforms. US reference networks like LabCorp and Quest drive consolidation toward walkaway systems.
- Pharmaceutical Companies:GMP-grade assays for bioprocess monitoring and release testing. Cell therapy manufacturers in Switzerland and Massachusetts require host cell protein quantification.
- Hospitals:Acute care testing with STAT turnaround requirements. German hospital alliances bundle procurement for centralized laboratory services.
- Research Institutions:Investigational use assays with flexible protocol adaptation. Academic medical centers prioritize open-platform configurations.
Diagnostic laboratories command the established base. The steepest expansion runs through pharmaceutical companies as biologics manufacturing scales.
Technology:
Detection chemistry determines sensitivity thresholds and instrument capital requirements.
- Chemiluminescent Detection:Enzyme-triggered light emission with photomultiplier quantification. US and Japanese reference laboratories adopt this for broad dynamic range and femtomolar sensitivity.
- Colorimetric Detection:Horseradish peroxidase or alkaline phosphatase chromogenic substrates read at 450 nm. Budget-constrained facilities in India and Brazil retain this format for infectious disease screening.
- Fluorescent Detection:Fluorophore-conjugated reporters with excitation-emission discrimination. Multiplex bead-based platforms enable simultaneous analyte measurement.
- Optical Detection:Direct absorbance or turbidimetric readouts without enzymatic amplification. Simplified protocols suit point-of-care deployment.
Colorimetric detection commands the established base. The steepest expansion runs through chemiluminescent detection as reference laboratories upgrade sensitivity specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories in India and Brazil exhibit acute price sensitivity toward colorimetric ELISA formats, while reference networks in the United States and Germany absorb premium chemiluminescent systems without volume elasticity constraints. This demand bifurcation shapes procurement patterns across high-throughput and budget-constrained settings.
United States
FDA's updated in vitro diagnostic guidance is compressing assay validation timelines for manufacturers seeking 510(k) clearance. Reference laboratories in North Carolina and Massachusetts are deploying walkaway automation platforms to expand infectious disease panel throughput. The CAP proficiency testing mandate is elevating demand for certified reference materials.
Germany
IVDR compliance deadlines are accelerating kit revalidation investments across Rhineland hospital alliances. The national pharmaceutical regulator is extending transition timelines for legacy CE-marked assays. Bavarian laboratory consortia are bundling instrument procurement with minimum annual consumable commitments.
China
NMPA's streamlined review pathway for innovative diagnostics is shortening approval cycles for domestic assay developers. Biopharma manufacturers in Shanghai and Suzhou are scaling GMP-grade host cell protein quantification capacity. The country's dual carbon goals are pressuring cold chain logistics providers to reduce reagent shipment emissions.
India
CDSCO's phased implementation of medical device rules is elevating quality standards for imported ELISA kits. Primary care clinics in Maharashtra and Karnataka are adopting miniaturized microfluidic cartridges for near-patient infectious disease screening. The PLI scheme is incentivizing domestic production of diagnostic consumables.
Japan
PMDA's harmonization with IVD-R standards is simplifying market entry for multinational assay suppliers. Academic medical centers in Tokyo and Osaka are integrating multiplex bead-based platforms for cytokine panel consolidation. METI's quality infrastructure program is subsidizing ISO 15189 accreditation for mid-tier laboratories.
Elisa Tests Market Vendor Landscape
Capability concentration sits with diversified life science conglomerates; scale advantage sits with specialized diagnostic reagent suppliers. The market exhibits tiered consolidation where automated platform vendors capture recurring consumable revenue through installed base expansion. Three archetypes dominate: integrated workflow providers, reagent rental specialists, and open-platform component suppliers. Competitive intensity centers on strategic partnerships for assay-menu expansion and geographic licensing agreements for regulatory pathway acceleration.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify integrated workflow strategies that bind laboratories to comprehensive automation ecosystems. Bio-Rad Laboratories occupies a distinct position within the reagent rental tier, anchoring long-term supply relationships through instrument placement models. These three entities represent contrasting approaches to value capture across the ELISA value chain.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Bio-Techne Corporation |
| Abcam |
| Danaher Corporation |
| F. Hoffmann-La Roche |
| Merck KGaA |
| PerkinElmer |
| Abbott |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's refrigerated container rates directly compress margins on enzyme-conjugate shipments while amplifying price spreads between GMP-certified and research-grade ELISA kits. German hospital procurement consortia exploit this logistics cost wedge to negotiate steeper discounts on bulk reagent contracts, whereas Indian primary care clinics absorb higher per-test costs for temperature-validated cold chain delivery.
Pricing Analysis
Long-term offtake agreements dominate the reagent rental tier, with German and US hospital alliances locking in minimum annual consumable commitments to secure instrument placement at nominal capital cost. Price differentiation rests on IVDR certification status and detection chemistry tier—chemiluminescent assays command substantial premiums over colorimetric formats. Cost compression in the research-use-only segment intensifies as Chinese domestic manufacturers expand capacity. Academic laboratories in India and Brazil exhibit acute price sensitivity, while Japanese reference networks absorb premium positioning without volume elasticity constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for capture and detection antibody sourcing. Monoclonal antibody production concentrates in Chinese contract manufacturers and US bioproduction facilities, with horseradish peroxidase conjugates and microplate substrates drawing from specialized chemical suppliers in Germany and Japan. Single-source vulnerability persists for GMP-grade host cell protein assay components. Distribution runs through authorized distributor networks in regulated markets and direct procurement channels in research settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ELISA market constitutes a high-growth disruption as chemiluminescent detection platforms displace legacy colorimetric workflows across reference laboratory networks. IVDR compliance deadlines in Europe are compressing assay revalidation timelines and consolidating procurement power among hospital alliances.
For Market Incumbents: Insulate installed base positions through backward integration into antibody production capacity in Switzerland and Massachusetts, reducing exposure to Chinese contract manufacturer lead time volatility. Deepen reagent rental contracting with German hospital consortia to lock in predictable consumable pull-through. Prioritize CLIA-compliant assay validation talent acquisition to defend against molecular assay substitution in infectious disease panels. For New Entrants and Emerging Players: Build out veterinary diagnostics white space in companion animal oncology and livestock surveillance, where regulatory barriers fall below human clinical assay thresholds. Target Brazilian and Indian primary care settings with miniaturized microfluidic cartridges for near-patient infectious disease screening. Pursue ISO 15189 accreditation partnerships as the go-to-market angle to secure reference laboratory entry. For Investors and Strategic Acquirers: IVDR transition timelines reshape the acquisition landscape toward assay revalidation specialists with established European notified body relationships. Frame long-term viability around biopharma QC expansion as cell therapy manufacturing scales. Target vertically integrated platform vendors with captive antibody supply and automated processor installed bases. Monitor FDA 510(k) clearance cadence for companion diagnostic developers as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Revalidation Partnership | Accelerates market access for certified ELISA kits in German hospital networks. |
| Chemiluminescent Platform Upgrade | Captures reference laboratory demand for femtomolar sensitivity specifications. |
| Reagent Rental Program Expansion | Transfers instrument ownership risk while securing multi-year consumable commitments. |
| Veterinary Assay Menu Diversification | Opens lower-regulation revenue streams in companion animal diagnostics. |
| Antibody Production Backward Integration | Reduces lead time volatility from Chinese contract manufacturer concentration. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, IVDR notified body guidance documents, and hospital procurement database extracts. Interviews with diagnostic laboratory directors, biopharma QC executives, immunochemistry R&D leads, and GPO contracts managers informed demand-side assumptions. Secondary validation drew from CAP proficiency testing records, CMS laboratory reimbursement schedules, and SEC filings of diversified life science conglomerates. Bottom-up test volume modeling and top-down market sizing triangulated value estimates.
Forecast inputs span product type, application, end user, and detection technology dimensions across the projection horizon. Chemiluminescent versus colorimetric technology migration curves, IVDR compliance investment cycles, and biopharma manufacturing capacity expansion trajectories shaped segment-level growth rates. CAGRs derive from regression analysis of historical instrument placement data against reagent consumption patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic assay developers or accelerated molecular assay substitution would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Sperm Count Test Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Microdialysis Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Livestock Diagnostics Market