
 North America Thyroid Cancer Diagnostics Market | 2026-2036
North America Thyroid Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thyroid Cancer Diagnostics Market Analytics
Outpatient clinic networks across the United States is recalibrating how thyroid nodules are triaged, shifting volume away from traditional hospital settings toward specialized ambulatory centers. Abbott leverages its point-of-care platform to capture community-based screening workflows. Thermo Fisher Scientific Inc. sustains dominance in next-generation sequencing panels for mutational profiling. GE HealthCare anchors the imaging segment through its ultrasound elastography installed base across major health systems.
Thyroid cancer diagnostics encompasses the detection, characterization, and monitoring of malignant thyroid neoplasms through histopathological examination, serum biomarker quantification, molecular genetic analysis, and cross-sectional imaging modalities, with fine-needle aspiration biopsy serving as the gold-standard initial tissue acquisition technique. The primary purpose is stratifying indeterminate nodules into benign versus malignant categories to guide surgical versus surveillance decisions. Imaging technologies, particularly ultrasound and PET scan modalities, command the largest share of procedure volume due to their role in initial detection and post-treatment surveillance. Genetic testing represents the fastest-expanding segment as BRAF, RAS, and RET/PTC mutational analysis becomes standard for indeterminate cytology cases. Blood test applications for thyroglobulin monitoring maintain stable demand in the prognosis and monitoring categories.
FDA oversight of in vitro diagnostics and companion diagnostic approvals shapes product development timelines and commercialization pathways in the United States, while Health Canada and PMRA regulations govern market access for diagnostic manufacturers in Canada. CLIA laboratory certification requirements and HIPAA data privacy standards further constrain operational models for molecular testing providers. Stakeholders must monitor evolving FDA guidance on artificial-enabled diagnostic algorithms and reimbursement determinations from CMS and provincial health authorities.
Market Dynamics
The FDA's compressed companion diagnostic clearance pathway is compressing commercialization timelines from 18 months to under 12 months, forcing manufacturers to front-load clinical validation work and reshaping how molecular testing platforms reach hospital networks.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for molecular thyroid nodule assays now extend to community-based pathology laboratories, broadening access beyond academic medical centers.
- Metropolitan hospital cluster concentration:Dense networks in the U.S. Northeast and California generate sufficient procedure volume to justify dedicated molecular pathology infrastructure and specialized cytopathology staffing.
- Next-generation sequencing panel standardization:BRAF, RAS, and RET/PTC mutational analysis has become the clinical default for Bethesda III-IV cytology, creating pull-through demand for comprehensive genomic profiling.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction master mixes and library preparation kits depend heavily on a limited supplier base concentrated in Massachusetts and California, exposing testing labs to allocation risk.
- CLIA laboratory certification friction:High-complexity molecular testing requirements demand specialized personnel credentials that create bottlenecks for laboratory expansion in secondary markets.
- Fine-needle aspiration sensitivity ceiling:Diagnostic yield for indeterminate nodules plateaus at 70-75% even with on-site cytology evaluation, limiting the addressable expansion of molecular reflex testing.
Strategic Opportunities
- Canadian provincial health authority integration:Health Canada and PMRA harmonization with FDA clearance pathways creates a streamlined dual-market entry strategy for U.S.-validated assays.
- Artificial-enabled diagnostic algorithms:Machine learning classification of ultrasound elastography patterns converges with molecular risk stratification to reduce unnecessary diagnostic surgery rates.
- Ambulatory surgical center channel development:Outpatient clinic networks in Texas and Florida are building captive pathology partnerships that bypass traditional hospital laboratory relationships.
Industry Challenges
- Molecular cytopathologist scarcity:Fellowship-trained specialists capable of integrating genomic data with cytomorphology remain concentrated in 12 major U.S. academic medical centers, constraining platform rollout.
- HIPAA-compliant data infrastructure:Cloud-based variant interpretation pipelines require substantial capital investment in encrypted architecture and business associate agreements with molecular software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thyroid Cancer Diagnostics Market |
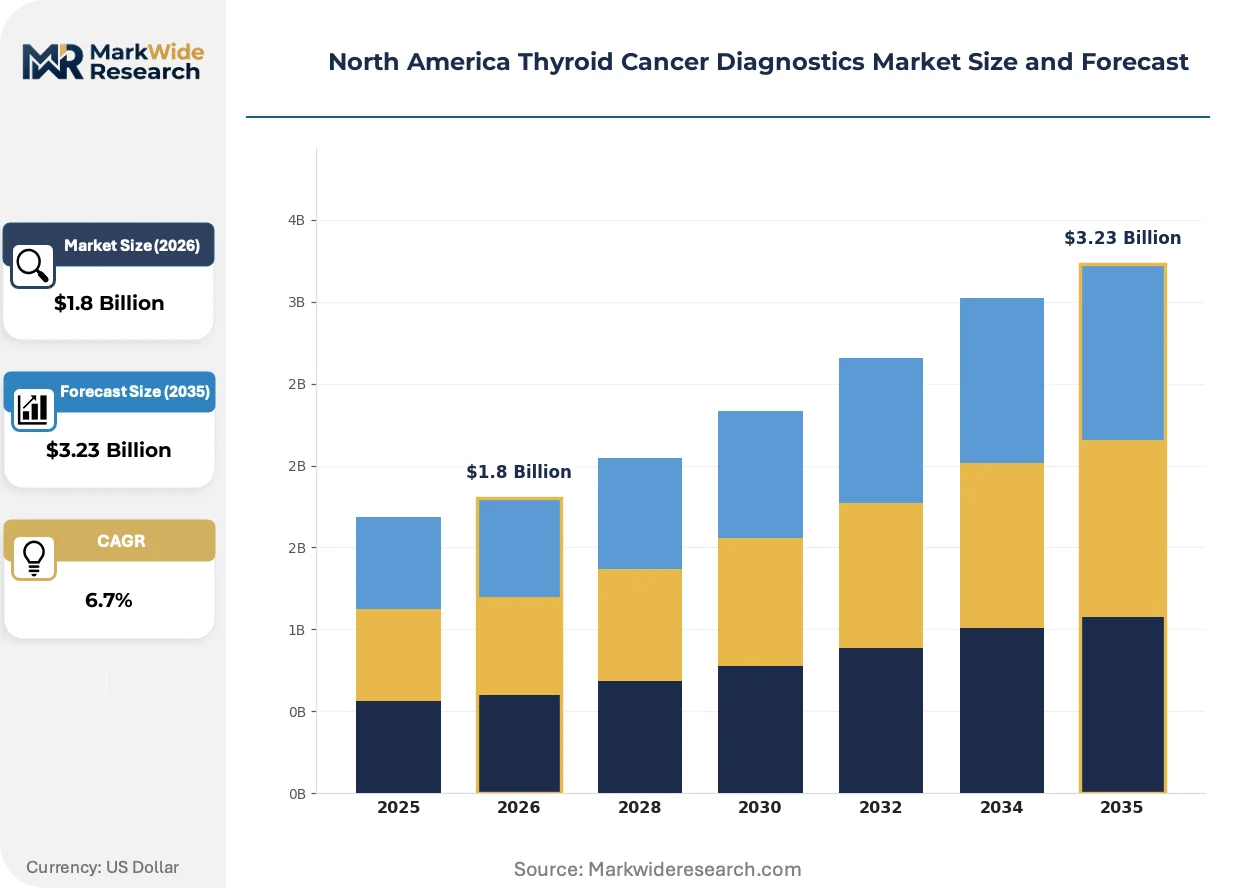
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Blood Test, Genetic Test Application: Diagnosis, Screening, Prognosis, Monitoring Technology: Ultrasound, CT Scan, MRI, PET Scan End User: Hospitals, Diagnostic Labs, Research Institutions, Outpatient Clinics |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Siemens Healthineers GmbH, Quest Diagnostics Incorporated, GE HealthCare, Koninklijke Philips N.V., Illumina, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thyroid Cancer Diagnostics Market Evolving Landscape
Diagnostic workflows for thyroid nodules are fragmenting across multiple care settings, with technology vendors racing to embed artificial intelligence and point-of-care capabilities into established clinical pathways.
Ultrasound elastography combined with artificial intelligence pattern recognition is overtaking conventional B-mode imaging for initial nodule risk stratification in high-volume U.S. health systems. Radiologists at tertiary centers in California and New York now deploy real-time shear wave analysis during the same patient encounter that previously required separate endocrinology referral. This compression of the diagnostic cascade is reducing time-to-biopsy intervals from weeks to days.
Health Canada and PMRA have aligned their in vitro diagnostic review timelines with FDA breakthrough device designation pathways, enabling synchronized U.S.-Canada product launches for molecular thyroid assays. Canadian provincial formularies in Ontario and British Columbia now reference FDA labeling directly, eliminating redundant clinical evidence generation. Manufacturers are responding by structuring pivotal trials to satisfy both regulatory regimes simultaneously.
Hospital procurement committees now bundle molecular testing contracts with imaging equipment leases, displacing the historical separation of radiology and pathology vendor relationships. Integrated delivery networks in the U.S. Midwest negotiate multi-year agreements that tie ultrasound system upgrades to exclusive molecular panel commitments. This consolidation of supplier relationships is most pronounced in Minnesota and Wisconsin health systems seeking to reduce vendor management overhead.
North America Thyroid Cancer Diagnostics Market Segmentation
Thyroid cancer diagnostics fragment across four distinct category axes, each capturing different buyer priorities from upfront capital deployment to recurring test consumption. Understanding how procurement committees evaluate trade-offs across these dimensions clarifies where molecular testing platforms displace legacy workflows.
Product Type:
Cost tier separates buyers seeking capital-intensive imaging infrastructure from those prioritizing per-test reagent spend.
- Biopsy:Fine-needle aspiration cytology remains the tissue acquisition standard, with on-site adequacy assessment reducing non-diagnostic rates. Demand clusters in metropolitan hospital networks across the U.S. Northeast where cytopathologist density supports rapid specimen evaluation.
- Imaging:Ultrasound elastography and cross-sectional modalities command the largest installed base, with GE HealthCare and Siemens Healthineers dominating health system procurement cycles through bundled service contracts.
- Blood Test:Serum thyroglobulin assays serve post-treatment surveillance protocols, maintaining stable reimbursement through Medicare coverage determinations.
- Genetic Test:Next-generation sequencing panels for BRAF, RAS, and RET/PTC mutations.
Imaging leads volumes today; genetic testing is gaining share fastest.
Application:
Clinical utility varies sharply by whether the objective is initial detection versus longitudinal management.
- Diagnosis:Definitive malignant versus benign classification drives surgical decision-making, with molecular reflex testing now standard for Bethesda III-IV cytology indeterminates. Academic medical centers in California and New York generate the highest per-facility test volumes.
- Screening:Asymptomatic nodule detection in incidentally discovered thyroid lesions.
- Prognosis:Risk stratification for recurrence and survival outcomes.
- Monitoring:Post-treatment surveillance via serial thyroglobulin and imaging.
Diagnosis commands the largest revenue pool; screening presents the steepest expansion trajectory as incidental detection rises.
Technology:
Resolution requirements and radiation exposure trade-offs differentiate modality selection across patient populations.
- Ultrasound:First-line modality for nodule characterization, with shear wave elastography reducing unnecessary biopsies. Texas and Florida outpatient networks are deploying portable systems to bypass hospital radiology queues.
- CT Scan:Anatomical mapping for extrathyroidal extension and nodal staging.
- MRI:Soft tissue delineation without ionizing radiation, preferred in pediatric and pregnancy protocols.
- PET Scan:Iodine-refractory disease detection and metastatic survey, concentrated in tertiary referral centers with cyclotron infrastructure.
Ultrasound anchors procedure volume; PET scan utilization climbs fastest in recurrence monitoring protocols.
End User:
Site-of-care economics and CLIA certification requirements shape where molecular testing concentrates.
- Hospitals:Integrated delivery networks in Minnesota and Wisconsin bundle imaging and pathology contracts to reduce vendor management overhead, with molecular cytopathologists concentrated in 12 major academic centers.
- Diagnostic Labs:Commercial reference laboratories processing FNA samples from distributed collection sites.
- Research Institutions:Translational studies and clinical trial biomarker validation.
- Outpatient Clinics:Ambulatory surgical centers in Texas and Florida building captive pathology partnerships that bypass traditional hospital laboratory relationships.
Hospitals retain the dominant share; outpatient clinics are expanding most quickly as nodule triage shifts away from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics between FDA and Health Canada clearance pathways are compressing commercialization timelines for molecular assays, while CLIA certification requirements create friction for laboratory expansion in secondary U.S. markets. Manufacturers front-load clinical validation to satisfy both regimes simultaneously.
United States
Metropolitan hospital clusters in the U.S. Northeast and California generate sufficient procedure volume to justify dedicated molecular pathology infrastructure and specialized cytopathology staffing. FDA oversight of in vitro diagnostics and companion diagnostic approvals shapes product development timelines and commercialization pathways. Texas and Florida outpatient networks are deploying portable ultrasound systems to bypass hospital radiology queues.
Canada
Health Canada and PMRA regulations govern market access for diagnostic manufacturers, with provincial formularies in Ontario and British Columbia now referencing FDA labeling directly. Harmonization with FDA breakthrough device designation pathways enables synchronized U.S.-Canada product launches for molecular thyroid assays. Canadian provincial health authority integration creates streamlined dual-market entry strategies for U.S.-validated assays.
Mexico
Diagnostic demand concentrates in Mexico City Metro and Monterrey metropolitan areas where tertiary referral centers manage complex thyroid malignancy cases. The country's national pharmaceutical regulator oversees in vitro diagnostic registration, though many high-complexity molecular tests are referred to U.S. reference laboratories. Cross-border patient flows for specialized cytopathology interpretation sustain demand for binational laboratory partnerships.
North America Thyroid Cancer Diagnostics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated delivery networks in the U.S. Midwest negotiating multi-year agreements that tie ultrasound system upgrades to exclusive molecular panel commitments. The vendor base concentrates around three strategic archetypes: diversified conglomerates with point-of-care platforms, pure-play genomic profiling specialists, and imaging equipment incumbents with bundled service contracts. Dominant competitive moves include strategic partnerships between molecular testing providers and hospital procurement committees, plus portfolio diversification into artificial-enabled diagnostic algorithms.
Among diversified health technology conglomerates, Abbott and GE HealthCare exemplify the integrated platform archetype, while Thermo Fisher Scientific Inc. occupies a position within the genomic profiling specialist tier. Abbott leverages its point-of-care platform to capture community-based screening workflows, and Thermo Fisher Scientific Inc. sustains dominance in next-generation sequencing panels for mutational profiling. GE HealthCare anchors the imaging segment through its ultrasound elastography installed base across major health systems.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers GmbH |
| Quest Diagnostics Incorporated |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Illumina |
| Canon Inc. |
| Others |
Value Network & Pricing Analysis
PCR master mix reagent costs cascade from Massachusetts and California manufacturing clusters through three distinct pricing tiers, with academic medical centers capturing volume discounts unavailable to community pathology laboratories facing CLIA certification barriers.
Pricing Analysis
Distributor margins for molecular testing platforms compress as integrated delivery networks negotiate direct procurement relationships with manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive NGS panels from targeted mutation assays and basic immunohistochemistry. Pricing pressure stems from Medicare reimbursement compression for molecular thyroid nodule testing. Community-based outpatient clinics exhibit highest price sensitivity, while metropolitan hospital clusters in the U.S. Northeast maintain lowest sensitivity due to bundled imaging-equipment contracts.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive reagents concentrate supply vulnerability in the Boston-Cambridge corridor and San Diego biotech clusters. Manufacturing draws from China for oligonucleotide synthesis, Germany for precision optics in imaging systems, and Japan for specialized histology stains. Single-source vulnerability pervades library preparation kit supply, with one Massachusetts-based vendor controlling critical enzyme formulations. Distribution runs through regional laboratory distributors serving hospital networks, with direct manufacturer relationships expanding among high-volume academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA-Health Canada regulatory harmonization creates geographic-arbitrage value for manufacturers front-loading clinical validation to satisfy both regimes simultaneously, compressing dual-market entry costs versus sequential approval strategies.
For Market Incumbents: Anchor market position through exclusive molecular panel commitments tied to ultrasound system upgrade cycles in Midwest integrated delivery networks. Defend against ambulatory surgical center channel displacement by building captive pathology partnerships in Texas and Florida. Prioritize CLIA laboratory certification support services to reduce customer expansion friction in secondary markets. For New Entrants and Emerging Players: Telepathology platform partnerships offer lowest-friction entry into cytopathologist-scarce secondary markets underserved by the twelve major academic centers. Target Canadian provincial formulary integration leveraging FDA labeling reference pathways in Ontario and British Columbia. Pursue artificial-enabled diagnostic algorithm development as differentiated positioning against established imaging incumbents. For Investors and Strategic Acquirers: Roll-up economics work for molecular cytopathology specialist practices because fellowship-trained expertise concentrates in twelve academic medical centers with limited geographic distribution. Five-to-ten year viability hinges on artificial intelligence diagnostic workflow integration rather than pure genomic testing commoditization. Monitor Health Canada PMRA breakthrough device designation velocity as inflection indicator for synchronized North American commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Partnership | Reduces expansion barriers for molecular testing providers entering secondary U.S. markets. |
| Health Canada Synchronized Submission | Enables dual-market FDA-PMRA approval leveraging Ontario provincial formulary referencing. |
| Ambulatory Surgical Center Channel Development | Captures nodule triage volume shifting from hospital settings in Texas and Florida. |
| AI-Enabled Ultrasound Elastography Integration | Compresses time-to-biopsy intervals through real-time shear wave pattern recognition. |
| Integrated Imaging-Pathology Contract Bundling | Locks in multi-year vendor relationships through Minnesota and Wisconsin health system procurement. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market combining structured interviews with molecular cytopathologists, hospital procurement committee members, CLIA laboratory directors, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, Health Canada MDALL registrations, CMS Medicare coverage determinations, and hospital procurement database extracts. Bottom-up test volume modeling triangulates against top-down market sizing across product type, application, technology, and end-user segmentation dimensions.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include biopsy-imaging-blood-genetic product categories, diagnosis-screening-prognosis-monitoring applications, ultrasound-CT-MRI-PET technology modalities, and hospital-diagnostic lab-research-outpatient end-user sites. CAGRs derive from procedure volume elasticity to incidence trends and reimbursement trajectory assumptions. Forecast inputs incorporate FDA companion diagnostic clearance pathway velocity and provincial formulary adoption timelines.
The model assumes a particular technology adoption path; alternative pathways for artificial-enabled diagnostic algorithms would alter the outlook if machine learning classification achieves standalone reimbursement codes ahead of current CMS timelines. Forecasts reflect assumptions about regulatory harmonization sustaining between FDA and Health Canada. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Urinary Protein Reagents Market