
 North America Bloodstream Infection Testing Market | 2026-2036
North America Bloodstream Infection Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bloodstream Infection Testing Market Insights
Market Context with Strategic Players
The bloodstream infection testing landscape is rebalancing between premium molecular platforms and commodity culture-based workflows. bioMérieux SA leverages its FilmArray system to dominate syndromic panel deployment in tertiary care centers. BD sustains competitive positioning through integrated blood culture instrument and media portfolios that anchor laboratory standardization contracts. Cepheid competes via cartridge-based molecular diagnostics that reduce technician hands-on time in mid-volume hospital settings.
Technical Definition and Structural Segments
Bloodstream infection testing encompasses laboratory methodologies that detect viable pathogens, microbial nucleic acids, or host biomarkers directly from blood specimens, typically requiring sensitivity thresholds of one to ten colony-forming units per milliliter given low bacterial loads in circulating blood. The primary purpose is to enable targeted antimicrobial therapy initiation and reduce sepsis-related mortality through accelerated pathogen identification and resistance profiling. Molecular diagnostics platforms command the fastest expansion trajectory as hospitals prioritize same-day species and resistance gene detection, while culture-based methods retain volume dominance in smaller laboratories constrained by capital budgets. Consumables generate recurring revenue streams that outpace instrument sales cycles, and sepsis diagnosis applications concentrate the largest addressable patient population across emergency and intensive care workflows.
Regulatory Framework and Outlook
FDA 510(k) premarket notification requirements govern in vitro diagnostic platform commercialization, while Clinical Laboratory Improvement Amendments shape analytical validation standards for laboratory-developed tests in hospital settings. Health Canada Medical Device Licensing and provincial laboratory accreditation bodies in Ontario and Quebec impose parallel conformity demands that shape product registration strategies for cross-border suppliers. Stakeholders must monitor evolving antimicrobial stewardship mandates from CMS and private payers that increasingly tie reimbursement to rapid diagnostic utilization metrics.
Market Dynamics
Multiplex PCR panel adoption is compressing diagnostic turnaround times from days to hours, forcing hospital laboratories to reconfigure workflow architectures around molecular platforms while CMS antimicrobial stewardship mandates accelerate capital redeployment toward rapid testing infrastructure.
Growth Catalysts
- CMS SEP-1 Bundling:Medicare reimbursement incentives now tie hospital payments to rapid pathogen identification protocols, driving integrated health networks toward same-day molecular diagnostics.
- Sepsis Mortality Pressure:Tertiary care centers face escalating liability exposure from delayed antibiotic administration, creating institutional urgency for accelerated species identification workflows.
- Cartridge-Based Automation:Random-access molecular platforms reduce technician hands-on time requirements, enabling mid-volume laboratories to deploy advanced diagnostics without specialized microbiology staffing.
Market Restraints
- Capital Intensity:FilmArray and Panther Fusion instrument platforms require $50,000-$150,000 upfront investment, excluding the recurring consumable costs that dominate total cost of ownership calculations.
- Reimbursement Compression:Private payers in Texas and California impose prior authorization requirements for molecular sepsis panels, creating administrative friction that delays test utilization.
- Culture Methodology Entrenchment:Blood culture remains the gold standard for antimicrobial susceptibility testing, limiting molecular platform displacement in resistance profiling workflows.
Strategic Opportunities
- Ontario Provincial Expansion:Health Canada's Medical Device Licensing harmonization with FDA 510(k) pathways reduces regulatory duplication costs for cross-border platform suppliers.
- Host Response Biomarker Integration:Procalcitonin and C-reactive protein multiplexing with pathogen detection creates differentiated panel offerings for emergency department triage protocols.
- Antibiotic Stewardship Mandates:Joint Commission accreditation standards now require documented diagnostic stewardship programs, institutionalizing rapid testing into hospital operational frameworks.
Industry Challenges
- Molecular Diagnostics Specialist Shortage:CLIA-certified technologists with nucleic acid amplification expertise command premium compensation in California and Texas labor markets, constraining laboratory expansion timelines.
- Legacy LIS Integration Complexity:Hospital information systems require custom middleware development to interface with proprietary molecular platform data formats, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bloodstream Infection Testing Market |
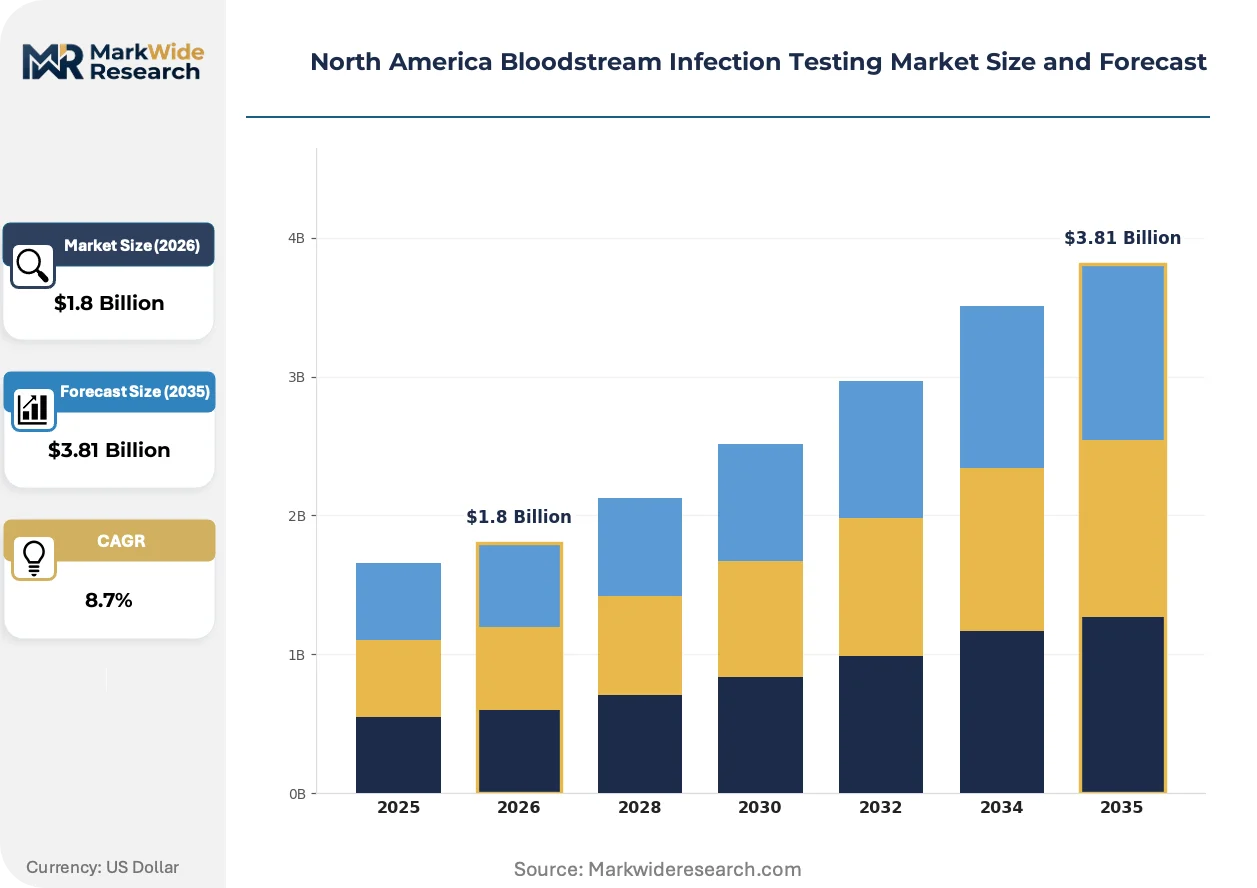
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
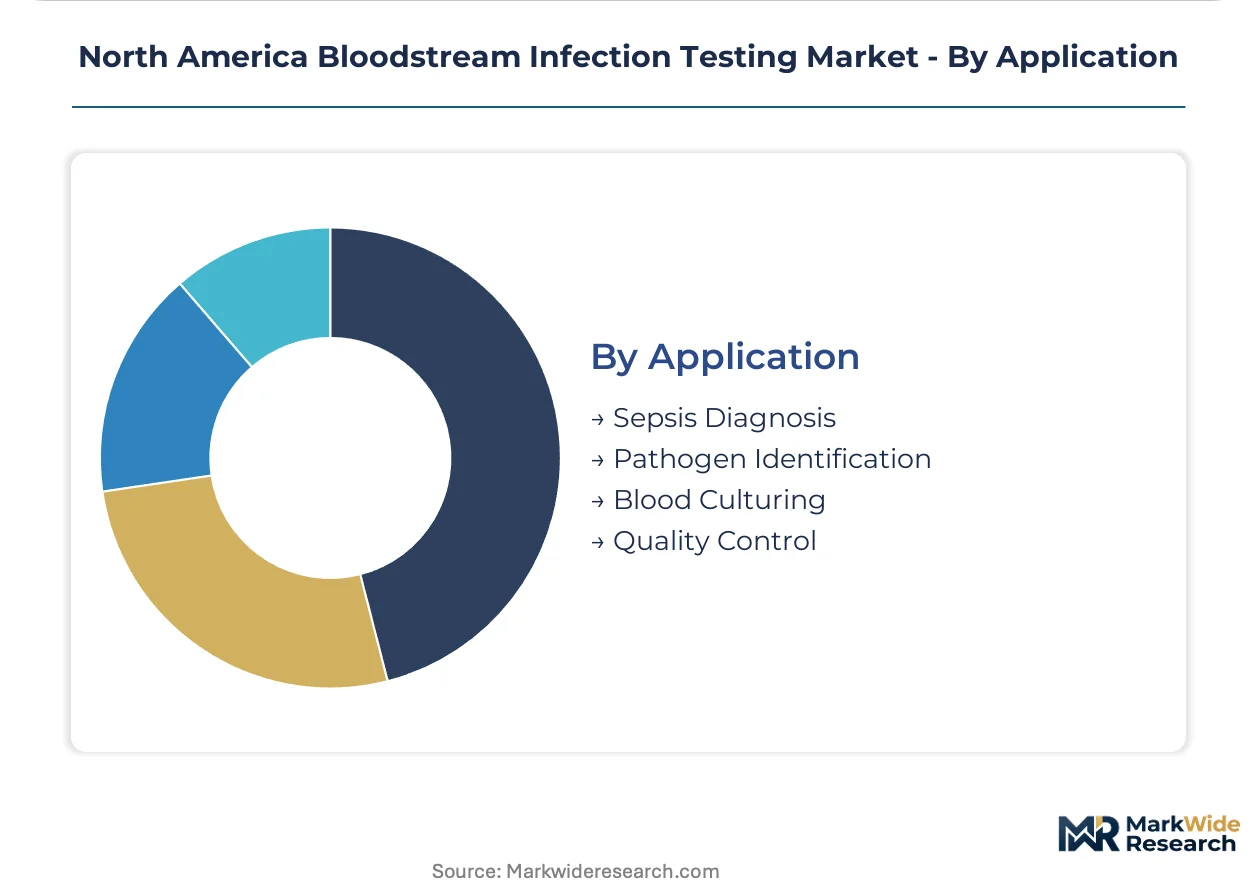
| Segmentation | Product Type: Consumables, Instruments, Software, Assays End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Technology: Culture-Based, Molecular Diagnostics, Immunoassays, Mass Spectrometry Application: Sepsis Diagnosis, Pathogen Identification, Blood Culturing, Quality Control |
| Companies Covered | bioMérieux SA, BD, Cepheid, Abbott, F. Hoffmann-La Roche Ltd, Bruker, Luminex Corporation, Seegene Inc., Accelerate Diagnostics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bloodstream Infection Testing Market Trends and Innovations
Digital PCR and metagenomic sequencing platforms are migrating from research environments into clinical validation pipelines, promising species-agnostic pathogen detection that bypasses culture-dependent workflows entirely.
T2 Magnetic Resonance technology is electrifying bloodstream infection diagnostics by enabling direct-from-blood pathogen detection without nucleic acid extraction. Large integrated delivery networks in Texas and California are piloting T2Dx instruments for candidemia and bacterial sepsis protocols. This platform is electrifying competitive positioning by eliminating the 24-48 hour culture incubation period that currently defines diagnostic delays.
FDA 510(k) clearance pathways for multiplex syndromic panels have compressed premarket review timelines for bloodstream infection applications. The agency's breakthrough device designation for rapid antimicrobial resistance detection is channeling venture funding toward novel diagnostic modalities. Mid-tier hospital laboratories in Ontario and Quebec are accelerating technology assessments to capture early-mover advantages from streamlined regulatory access.
Hospital procurement committees are consolidating vendor relationships around integrated blood culture and molecular platform portfolios. Group purchasing organizations spanning California and Texas health systems are negotiating enterprise-wide contracts that bundle instrument placement with multi-year consumable commitments. This concentration is most visible in tertiary care centers where standardization across affiliated community hospitals drives sole-source agreements with dominant suppliers.
North America Bloodstream Infection Testing Market Segmentation
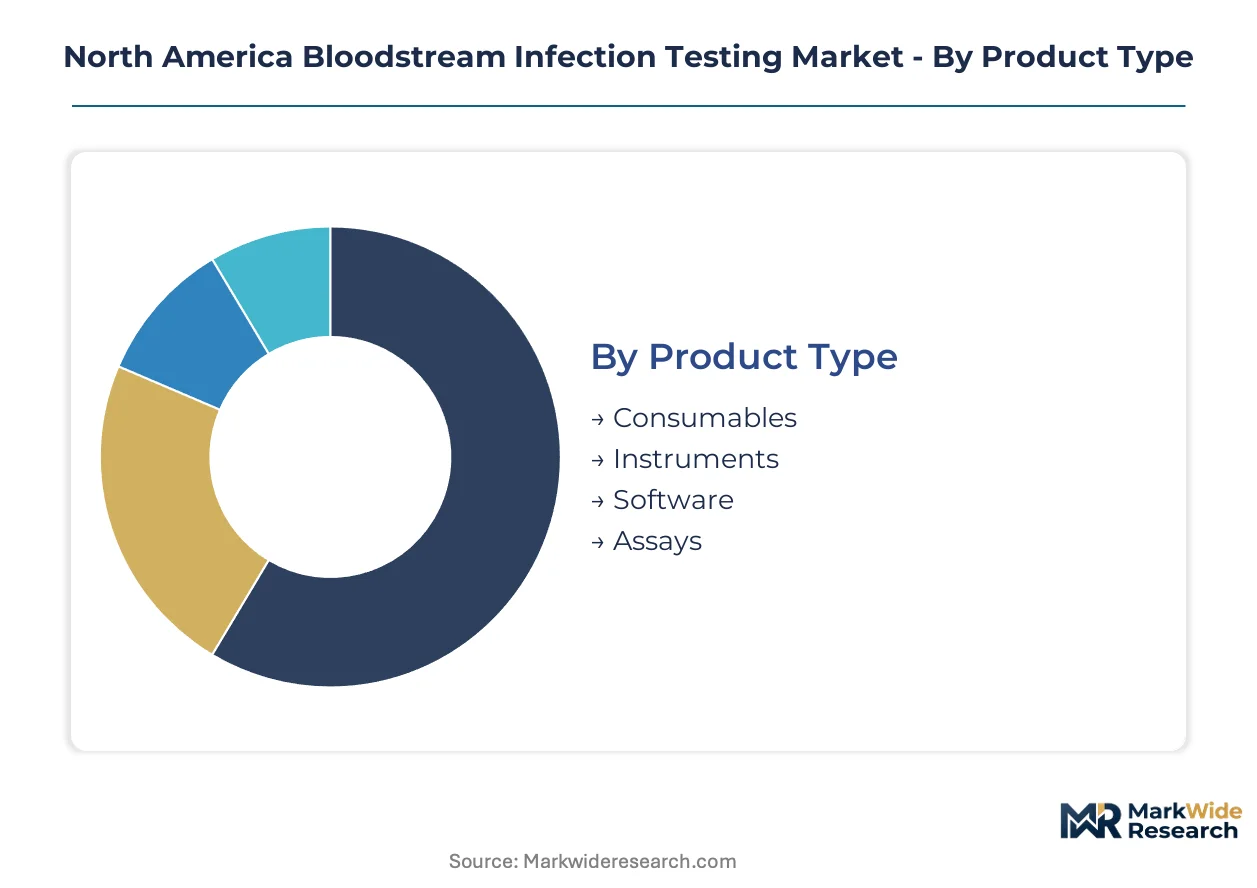
Bloodstream infection testing segments diverge sharply between high-throughput hospital laboratories and distributed point-of-care settings. Procurement patterns in Texas and California health systems favor bundled instrument-consumable contracts that reshape competitive dynamics across each segment tier.
Product Type:
Standalone instrument purchases dominate capital budgeting cycles in large tertiary centers, while embedded consumable programs sustain recurring revenue in mid-volume settings.
- Consumables:Blood culture media, molecular cartridges, and reagent kits constitute the recurring revenue backbone of vendor economics. Texas Medical Center affiliates and Ontario hospital networks negotiate multi-year consumable commitments that lock in supplier relationships.
- Instruments:Automated blood culture systems and multiplex PCR platforms require $50,000-$150,000 capital outlays. California integrated delivery networks prioritize random-access molecular instruments that minimize technician hands-on time.
- Software:Laboratory information system middleware enables data integration between molecular platforms and hospital EMR architectures.
- Assays:FDA 510(k)-cleared pathogen detection panels deliver species identification and resistance gene profiling in single workflows.
Consumables lead volumes today; software is gaining share fastest as LIS integration becomes mandatory for antimicrobial stewardship compliance.
End User:
Customer concentration varies dramatically by testing volume and regulatory complexity, with tier-one hospitals capturing the majority of molecular platform placements.
- Hospitals:Emergency departments and intensive care units drive urgent demand for same-day pathogen identification. CMS SEP-1 bundling mandates in the United States accelerate capital deployment toward rapid diagnostics in tertiary and community hospital settings.
- Diagnostic Laboratories:Reference laboratories process high-throughput panels for regional health networks. California and Texas commercial labs compete on turnaround time guarantees that pressure in-hospital microbiology consolidation.
- Clinics:Outpatient settings rely on send-out protocols for bloodstream infection confirmation.
- Research Institutions:Academic medical centers validate novel biomarker signatures and metagenomic sequencing workflows.
Hospitals anchor absolute demand; diagnostic laboratories are expanding capacity most aggressively.
Technology:
Technology selection hinges on sensitivity requirements versus capital constraints, creating a bifurcated landscape between gold-standard culture and emerging molecular modalities.
- Culture-Based:Blood culture remains mandatory for antimicrobial susceptibility testing and resistance profiling. Smaller laboratories in Ontario and Quebec retain volume dominance due to limited capital budgets for molecular migration.
- Molecular Diagnostics:Multiplex PCR and digital PCR platforms compress diagnostic turnaround from days to hours. FDA 510(k) clearance pathways for syndromic panels are accelerating hospital adoption in California and Texas.
- Immunoassays:Procalcitonin and C-reactive protein testing supports sepsis triage protocols.
- Mass Spectrometry:MALDI-TOF platforms enable rapid species identification from culture isolates.
Culture-based methods retain volume leadership; molecular diagnostics is climbing the fastest as stewardship mandates harden.
Application:
Application prioritization reflects clinical urgency hierarchies, with sepsis protocols commanding premium resource allocation.
- Sepsis Diagnosis:Rapid pathogen detection directly impacts mortality outcomes and antibiotic stewardship metrics. Emergency departments across United States and Canadian health systems prioritize same-day molecular panel deployment.
- Pathogen Identification:Species-level detection enables targeted antimicrobial therapy selection.
- Blood Culturing:Automated incubation and detection systems anchor laboratory infrastructure.
- Quality Control:Contamination monitoring and assay validation sustain regulatory compliance.
Sepsis diagnosis concentrates the largest addressable population; pathogen identification is expanding most quickly as resistance profiling demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CLIA-certified molecular diagnostics technologists concentrate in California and Texas metropolitan corridors, anchoring regional laboratory expansion capacity across the North American bloodstream infection testing landscape.
United States
CMS SEP-1 bundling mandates and antimicrobial stewardship reimbursement incentives drive hospital procurement of rapid molecular platforms. FDA 510(k) clearance pathways for multiplex PCR panels compress regulatory timelines for new entrants. The Texas Medical Center in Houston anchors high-throughput microbiology consolidation across affiliated community hospitals.
Canada
Health Canada Medical Device Licensing harmonization with FDA pathways reduces cross-border regulatory duplication for platform suppliers. Provincial laboratory accreditation bodies in Ontario and Quebec impose conformity standards that shape product registration strategies. Toronto's University Health Network pilots T2 Magnetic Resonance instruments for direct-from-blood pathogen detection protocols.
California
Integrated delivery networks prioritize random-access molecular instruments that minimize technician hands-on time in mid-volume settings. Private payer prior authorization requirements for molecular sepsis panels create administrative friction that delays test utilization. The San Francisco Bay Area hosts reference laboratories competing on turnaround time guarantees for regional health networks.
Texas
Large health systems negotiate enterprise-wide contracts bundling instrument placement with multi-year consumable commitments. Molecular diagnostics specialists command premium compensation in tight labor markets, constraining laboratory expansion timelines. Dallas-Fort Worth hospital procurement committees consolidate vendor relationships around integrated blood culture and molecular platform portfolios.
Ontario
Provincial health networks accelerate technology assessments to capture early-mover advantages from streamlined regulatory access. Hospital laboratories reconfigure workflow architectures around molecular platforms as stewardship mandates harden. Ottawa's academic medical centers validate novel biomarker signatures and metagenomic sequencing workflows for future clinical deployment.
North America Bloodstream Infection Testing Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light assay developers for positioning in hospital procurement cycles. The vendor base concentrates around three tiers: multinational diagnostics conglomerates with integrated portfolios, mid-cap molecular specialists with syndromic panel expertise, and emerging platform developers targeting specific resistance detection niches. Dominant competitive moves include strategic partnerships for LIS middleware integration and geographic expansion through group purchasing organization contract capture.
Among the multinational tier, bioMérieux SA, BD, and Cepheid exemplify contrasting archetypes of competitive positioning. The French-listed bioMérieux represents integrated system suppliers leveraging FilmArray placement to anchor long-term consumable revenue streams. BD occupies a position as the legacy blood culture incumbent defending standardization contracts through instrument-media bundling. Cepheid sits within the random-access automation segment, exemplifying cartridge-based platforms that reduce specialized staffing requirements for mid-volume laboratories.
| Leading Market Players |
|---|
| bioMérieux SA |
| BD |
| Cepheid |
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Bruker |
| Luminex Corporation |
| Seegene Inc. |
| Accelerate Diagnostics, Inc. |
| Others |
Pricing and Supply Chain Analysis
Polymer resin price indices cascade through bloodstream infection testing supply chains into three distinct pricing tiers that separate integrated platform bundles from standalone consumable programs. Input cost volatility in diagnostic-grade plastics and specialized reagent chemicals feeds directly into vendor margin structures, compressing economics for mid-tier assay developers while premium instrument manufacturers absorb fluctuations through long-term hospital contracts.
Pricing Analysis
Bundled instrument-consumable contracts dominate enterprise procurement, while unbundled reagent-only purchases sustain smaller laboratories with limited capital budgets. Three-tier pricing structure across premium, standard, and economy levels separates FilmArray-tier integrated systems from cartridge-based mid-market platforms and legacy culture media programs. Price differentiation hinges on FDA 510(k) clearance tier and health system GPO membership scale. Cost compression in mid-tier molecular panels is intensifying because Texas and California private payers impose prior authorization requirements that delay test utilization. Community hospital laboratories exhibit highest price sensitivity; tertiary care centers with stewardship mandates demonstrate lowest.
Supply Chain Analysis
Freight cost escalation for temperature-controlled reagent shipments is reshaping regional inventory positioning across North American distribution networks. Manufacturing concentrates in the United States, France, and South Korea for precision instrumentation; reagent production clusters in the United States and Germany. Supply chains draw from diagnostic-grade polymers, nucleic acid amplification enzymes, and magnetic bead separation media. Single-source vulnerability in specialized PCR enzyme supply creates bottleneck exposure for mid-tier assay developers. Distribution runs through hospital GPOs, regional reference laboratory networks, and direct-to-laboratory vendor logistics programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in consumable pull-through economics as hospitals consolidate around integrated platform vendors, with cartridge-based automation reducing per-test labor costs as the premium-tier shift driver.
For Market Incumbents: Anchor long-term positioning through exclusive GPO contract capture in Texas and California health systems, locking out emerging molecular specialists. Deepen consumable revenue moats by embedding software middleware that raises switching costs for hospital LIS integration. Defend against T2 Magnetic Resonance displacement by accelerating syndromic panel FDA submissions for resistance gene detection. For New Entrants and Emerging Players: Capture white-space opportunity in mid-volume Ontario hospital laboratories where Health Canada regulatory harmonization reduces entry barriers against entrenched US suppliers. Target host response biomarker multiplexing as the most penetrable application segment, where procalcitonin-CRP integration remains underdeveloped. Pursue reference laboratory partnerships as the fastest go-to-market channel, bypassing capital-intensive direct hospital sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with cartridge-based automation specialists possessing CLIA-waived assay menus and random-access instrument architectures. Long-term viability favors platforms with recurring consumable economics over instrument-only vendors exposed to capital budget cyclicality. Monitor FDA breakthrough device designations for rapid antimicrobial resistance detection as the signal indicating platform technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Texas Medical Center affiliation contracts lock in multi-year consumable commitments across 50-plus facilities. |
| FDA 510(k) Submission | Clearance for multiplex sepsis panels compresses regulatory timelines and accelerates Medicare reimbursement eligibility. |
| Software Companion Development | LIS middleware integration raises hospital switching costs and anchors platform standardization decisions. |
| Reimbursement Strategy | CMS SEP-1 compliance documentation ties hospital payments to rapid diagnostic utilization metrics. |
| CE Marking Pathway | Health Canada harmonization enables Ontario and Quebec provincial laboratory procurement access. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and CMS reimbursement filings — were reconciled against primary interviews with laboratory directors, biomedical engineers, and health system supply chain executives. Secondary validation drew from FDA 510(k) clearance records, Health Canada Medical Device Licensing data, and hospital antimicrobial stewardship program disclosures. Bottom-up instrument placement counts and top-down health system expenditure estimates were triangulated to cross-verify market sizing.
Historical instrument shipment patterns were cross-referenced against panel-based forecast assumptions across the analysis window. Segmentation modeling incorporated technology platform type, end-user laboratory tier, application urgency hierarchy, and regional regulatory cluster. CAGRs were derived from instrument replacement cycles and consumable pull-through coefficients calibrated to hospital test volume growth. Forecast inputs included CLIA-certified technologist labor market tightness and CMS stewardship mandate enforcement trajectories.
Underlying measurement precision varies by segment; molecular diagnostics placements carry tighter precision than culture-based volume estimates due to instrument-level tracking visibility. Forecasts reflect assumptions about regulatory pathway timelines and reimbursement policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Sterilization Tunnel Market
Infection Control
Hand Hygiene Products Market
Infection Control
Infection Control Supplies Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Hygiene Stations Market
Infection Control
Global Disinfection Robots Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Antimicrobial Wipes Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Dental Infection Treatment Market