
 Portable Dialysis Machines Market | 2026-2036
Portable Dialysis Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Dialysis Machines Market Analytics
ISO 13485 certification is unwinding competitive access for new entrants in portable renal device manufacturing. Fresenius Medical Care AG & Co. KGaA leverages captive supply chains for dialyzer membranes across European and North American production nodes. Baxter International Inc. anchors its position through backward integration into peritoneal dialysis fluid chemistry. Outset Medical, Inc. differentiates via simplified user interfaces that reduce training burdens for home care staff.
Portable dialysis machines are self-contained renal replacement systems designed to perform solute clearance and ultrafiltration outside traditional clinical settings, typically operating with blood flow rates of 200–400 mL/min and integrated water purification modules. These devices serve patients requiring intermittent or continuous renal support in homes, ambulatory clinics, and remote care environments. Hemodialysis configurations occupy the largest installed base due to established clinical protocols and broader reimbursement coverage, while peritoneal dialysis segments attract investment for their lower infrastructure requirements and suitability for patient self-management. Home care providers represent the fastest-growing end-user channel as payors redirect spending from in-center treatment toward distributed care models that reduce facility overhead.
FDA premarket notification requirements and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that shape regional product launch sequencing and clinical trial investment. The EPA regulates water purification component effluents in US-manufactured systems, adding environmental compliance layers to device design. Stakeholders must monitor how Medicare's expanding home dialysis bundled payment models interact with state-level scope-of-practice rules for remote patient monitoring to determine viable deployment architectures.
Market Dynamics
Medicare's expanding bundled payment models for home-based dialysis are redirecting capital flows from inpatient facilities toward distributed renal infrastructure, forcing manufacturers to redesign devices for unsupervised patient operation and remote clinical oversight.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for wearable hemodialysis systems compress development timelines and reduce regulatory uncertainty for novel form factors targeting home deployment.
- Peritoneal dialysis chemistry advances:Improved biocompatibility of glucose-sparing solutions reduces peritonitis rates and extends catheter survival, expanding the addressable patient pool for self-managed modalities.
- Remote patient monitoring infrastructure:Cloud-connected vital sign integration enables real-time ultrafiltration adjustment and reduces emergency interventions, lowering payor risk for decentralized care models.
Market Restraints
- Polymer membrane supply concentration:High-flux dialyzer production depends on specialized polysulfone and polyethersulfone resin suppliers concentrated in Germany and Japan, creating input vulnerability.
- Water purification system capex:Reverse osmosis and deionization modules for home installation require plumbing modifications and electrical upgrades that strain patient household budgets.
- EU MDR clinical evidence requirements:Stricter post-market surveillance and periodic safety update reporting extend certification timelines and inflate regulatory compliance costs for European market entry.
Strategic Opportunities
- Rural Medicare Advantage penetration:Underserved counties in Texas, Mississippi, and Alaska present concentrated demand for portable systems that eliminate thrice-weekly travel to dialysis centers.
- Acute kidney injury ambulatory protocols:Emergency departments and observation units seek intermittent renal support devices for sub-acute patients who stabilize outside ICU settings.
- Telehealth reimbursement permanence:CMS rulemaking that codifies remote nephrologist oversight payments creates sustainable economics for device-plus-service bundled offerings.
Industry Challenges
- Biomedical technician training pipelines:Home dialysis programs require field service capacity for device maintenance and water system validation that outstrips current vocational program output.
- Interoperability with EHR systems:Treatment data transmission into Epic, Cerner, and Meditech platforms demands HL7 FHIR compliance that fragments across health system IT architectures.
- Patient self-cannulation competency:Vascular access preparation for hemodialysis requires motor skills and antiseptic discipline that exclude substantial portions of the elderly and visually impaired population.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Dialysis Machines Market |
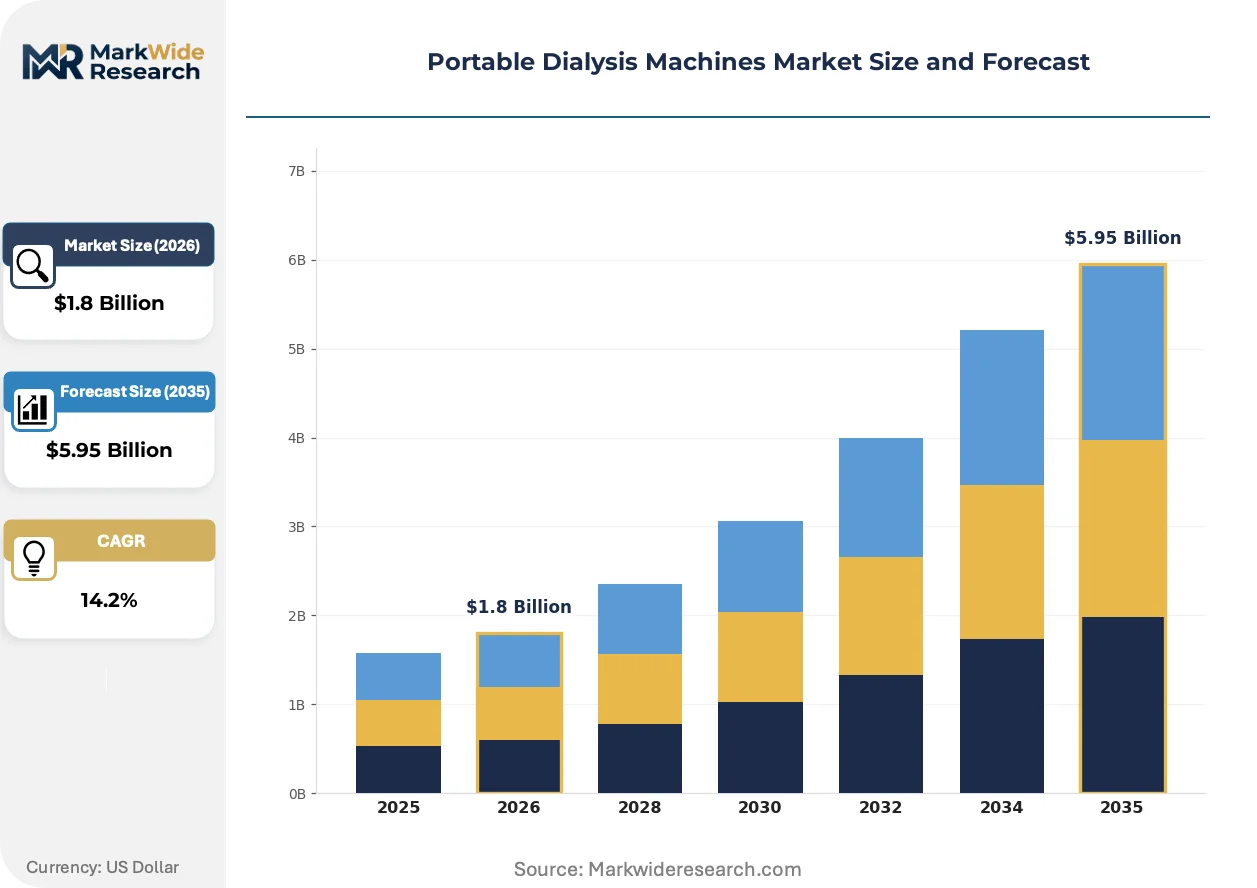
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis, Peritoneal Dialysis, Portable Systems, Home Dialysis Machines End User: Hospitals, Home Care Providers, Healthcare Facilities, Dialysis Clinics Technology: Mobile Dialysis Units, Automated Devices, Continuous Dialysis Systems, Manual Machines Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Distributors |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., B. Braun SE, Outset Medical, Inc., Quanta Dialysis Technologies Ltd., Nikkiso Co., Ltd., Asahi Kasei Medical Co., Ltd., NxStage Systems, Diality, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Dialysis Machines Market Evolving Landscape
Miniaturization of sorbent-based dialysate regeneration is collapsing the infrastructure footprint required for renal replacement, while regulatory harmonization efforts and shifting site-of-care economics simultaneously reshape competitive entry points.
Sorbent cartridge technology is decomposing the traditional dependency on continuous water supply and drain connections for hemodialysis. Home care providers in the United States are piloting systems that regenerate dialysate from 6 liters of tap water rather than 120 liters per session. This compression of fluid logistics is enabling apartment dwellers and rural patients to adopt home modalities previously restricted to homeowners with utility modifications.
The EU Medical Device Regulation's tightened clinical evaluation requirements are forcing manufacturers to generate real-world evidence from post-market surveillance. European notified bodies now demand extended follow-up data for wearable devices that operate outside supervised clinical environments. This regulatory elevation favors established players with existing PMS infrastructure while extending time-to-revenue for novel entrants targeting CE marking.
Hospital purchasing cooperatives are consolidating renal device procurement under single-source agreements that bundle capital equipment, disposables, and technical service. This channel compression disadvantages standalone device vendors without captive fluid or membrane supply. The Veterans Health Administration and several state Medicaid plans have moved toward sole-source contracting, concentrating volume with integrated suppliers capable of absorbing total cost-of-ownership risk.
Portable Dialysis Machines Market Segmentation
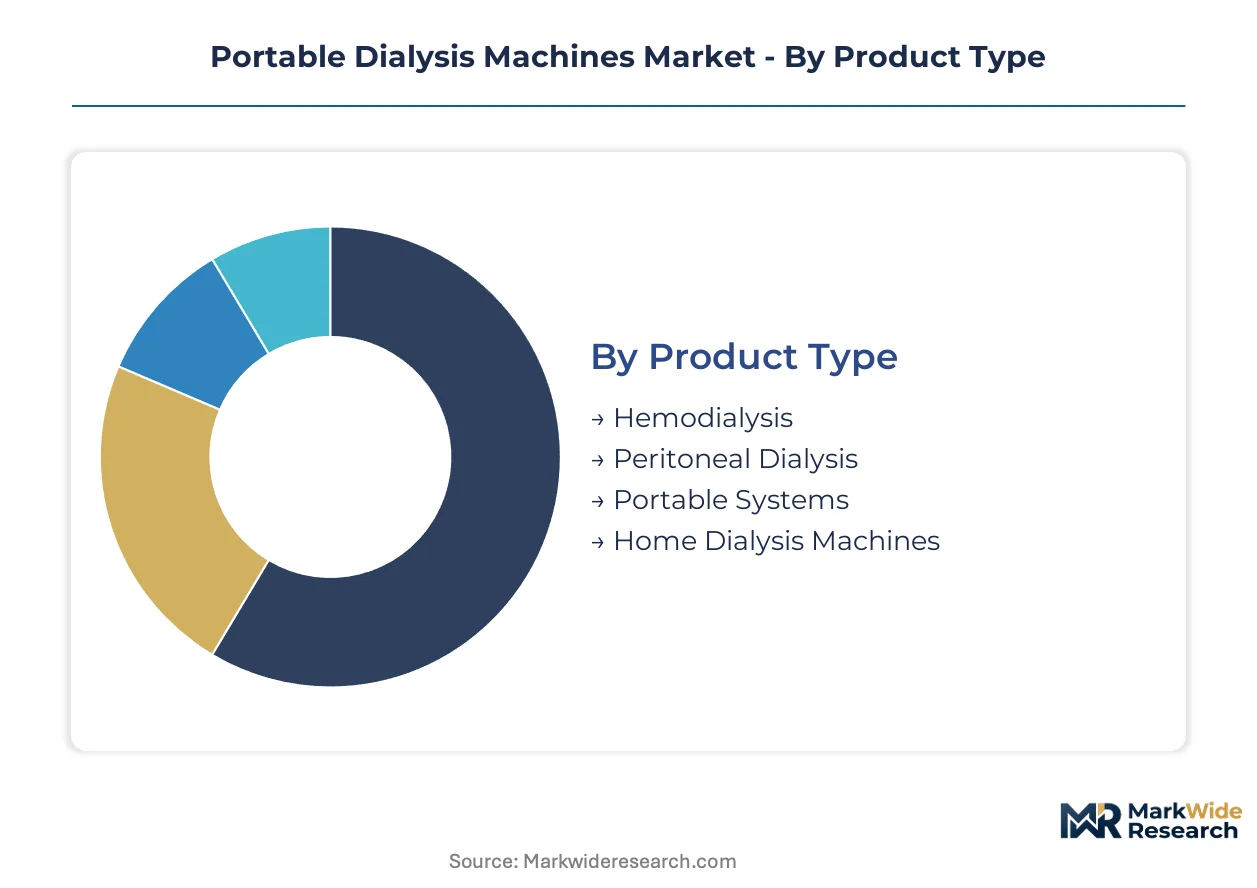
Portable dialysis machines serve heterogeneous clinical and logistical environments, from Medicare-reimbursed home installations to emergency department rapid deployment. Segmentation reveals where technical specifications diverge from reimbursement pathways and where supply chain investments concentrate.
Product Type:
Hemodialysis configurations command the widest margin pools due to established reimbursement codes and consumable attachment rates, while peritoneal dialysis segments attract capital for their infrastructure-light deployment model.
- Hemodialysis:Blood-cleansing systems operate at 200–400 mL/min flow rates with integrated water purification modules. Demand concentrates in United States home care settings where Medicare bundled payments favor thrice-weekly treatment schedules and vascular access infrastructure.
- Peritoneal Dialysis:Fluid-exchange modalities utilize the patient's peritoneal membrane for solute clearance without extracorporeal blood circuits. Adoption accelerates among rural Medicare Advantage beneficiaries in Texas and Alaska where travel distances to in-center facilities exceed 50 miles.
- Portable Systems:Wearable and briefcase-sized devices target ambulatory emergency protocols and travel-dependent patients.
- Home Dialysis Machines:Stationary units designed for dedicated residential utility connections and caregiver-assisted operation.
The dominant share belongs to Hemodialysis, while Peritoneal Dialysis is closing the gap fastest.
End User:
Volume concentration tracks site-of-care reimbursement shifts, with capital flows redirecting from inpatient facilities toward distributed renal infrastructure.
- Home Care Providers:Medicare-certified agencies and visiting nurse associations deploy devices for unsupervised patient operation with remote nephrologist oversight. United States demand concentrates in counties with high ESRD prevalence and limited dialysis center density.
- Hospitals:Acute care facilities utilize portable systems for ICU step-down units and observation holds requiring intermittent renal support.
- Healthcare Facilities:Skilled nursing and long-term acute care settings integrate dialysis for non-ambulatory residents.
- Dialysis Clinics:Outpatient centers deploy portable backup units and patient transition systems for home therapy initiation.
Home Care Providers capture the steepest expansion trajectory as CMS rulemaking codifies remote monitoring payments, while Hospitals retain the largest installed base.
Technology:
Automation intensity determines service revenue attachment and training burden differentiation among competing platforms.
- Automated Devices:Sensor-integrated systems self-adjust ultrafiltration rates and dialysate composition based on real-time hematocrit and pressure readings. United States pilot programs demonstrate reduced emergency intervention rates for elderly self-cannulation patients.
- Continuous Dialysis Systems:Sustained low-efficiency modalities operate 24-hour cycles for hemodynamically unstable patients. Demand emerges in emergency department observation protocols requiring sub-acute stabilization outside ICU settings.
- Mobile Dialysis Units:Vehicle-mounted or transportable systems serve disaster response and temporary clinic supplementation.
- Manual Machines:Operator-dependent devices with minimal electronic control for cost-constrained deployments and backup scenarios.
Automated Devices hold the dominant share, though Continuous Dialysis Systems are gaining share fastest in acute care substitution applications.
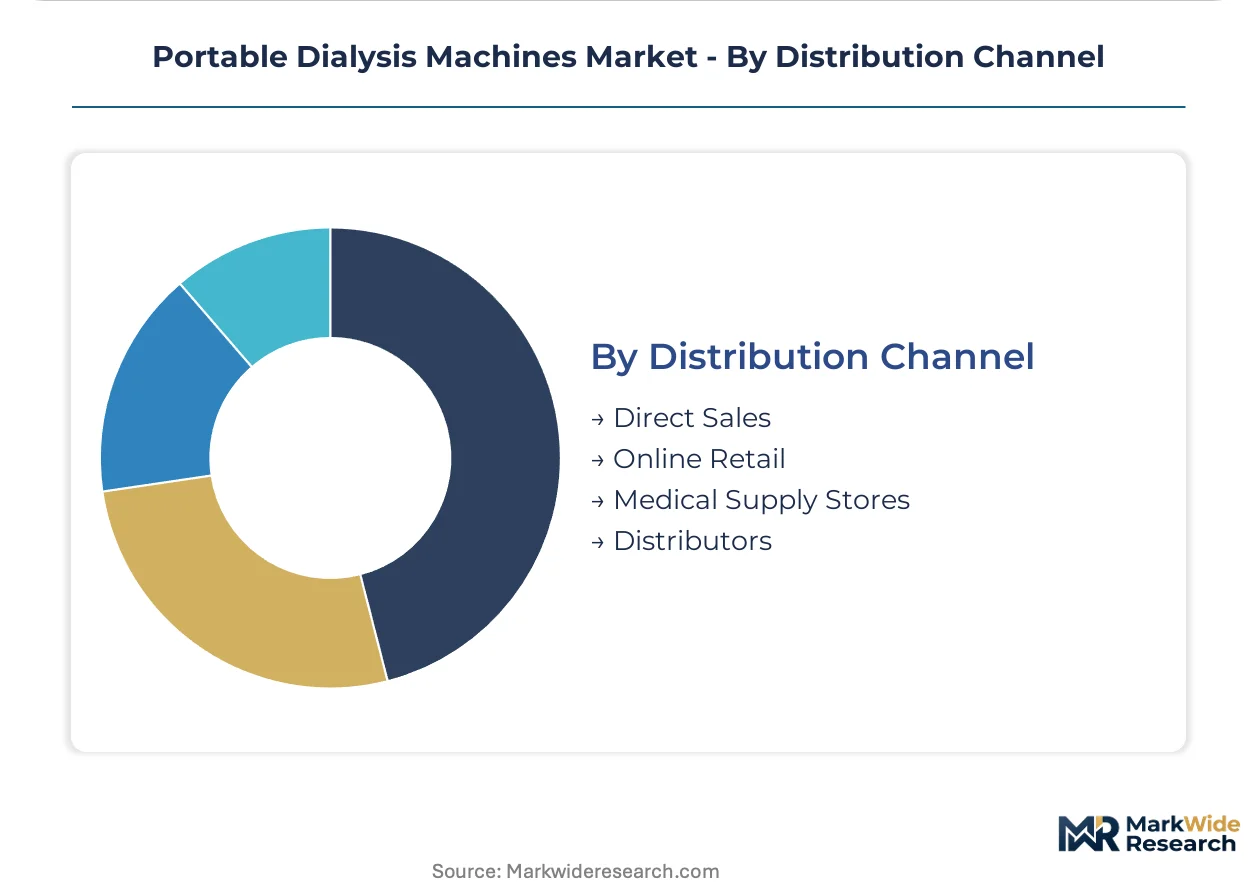
Distribution Channel:
Channel economics reflect capital equipment financing requirements versus consumable replenishment velocity.
- Direct Sales:Manufacturer field organizations negotiate sole-source agreements with Veterans Health Administration and state Medicaid plans. These contracts bundle capital equipment, disposables, and technical service under total cost-of-ownership risk absorption.
- Distributors:Regional medical device wholesalers maintain inventory for same-day replacement and emergency deployment.
- Online Retail:E-commerce platforms serve accessory and consumable replenishment for established home patients.
- Medical Supply Stores:Brick-and-mortar outlets provide local access to replacement tubing, dialyzers, and water treatment supplies.
Direct Sales commands the dominant share, while Distributors are expanding most quickly in rural Medicare Advantage penetration zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare bundled payment expansion for home-based dialysis is redirecting capital toward distributed renal infrastructure across high-prevalence markets. Germany and Japan anchor membrane supply chains for dialyzer production. China's NMPA is accelerating wearable device approvals to reduce facility-based treatment burdens.
United States
CMS rulemaking codifies remote nephrologist oversight payments, creating sustainable economics for device-plus-service models. The FDA Breakthrough Device Designation compresses review timelines for wearable hemodialysis systems. Texas and Alaska rural counties concentrate demand where travel distances to in-center facilities exceed 50 miles.
Germany
Specialized polysulfone and polyethersulfone resin suppliers anchor high-flux dialyzer production for European export markets. The EU MDR mandates extended post-market surveillance for wearable devices operating outside supervised clinical environments. Baden-Württemberg industrial clusters host membrane manufacturing nodes serving Fresenius Medical Care AG & Co. KGaA captive supply chains.
Japan
PMDA regulatory pathways favor miniaturized systems targeting aging demographics with limited caregiver support. METI funding programs accelerate sorbent-based dialysate regeneration R&D to collapse infrastructure footprints. Tokyo and Osaka metropolitan areas concentrate dialysis device engineering talent and precision manufacturing capacity.
China
NMPA streamlined approval processes for portable renal devices address rising ESRD prevalence in tier-2 and tier-3 cities. The country's dual carbon goals pressure manufacturers to reduce water purification energy consumption in home systems. Yangtze River Delta medical device clusters integrate domestic membrane production to reduce import dependency.
United Kingdom
NHS England long-term plan targets 20 percent home dialysis penetration by 2025, expanding procurement for portable systems. MHRA post-Brexit regulatory autonomy enables faster adoption of EU-cleared wearable devices. London and Southeast England health systems pilot cloud-connected vital sign integration for real-time ultrafiltration adjustment.
Portable Dialysis Machines Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance and supply chain integration dimensions. The market structure consolidates around integrated suppliers with captive membrane or fluid chemistry production, while standalone device vendors face channel compression under hospital purchasing cooperative agreements. Two strategic archetypes dominate: vertically integrated multinationals absorbing total cost-of-ownership risk, and technology-focused innovators differentiating through user interface simplification. Competitive moves concentrate on backward integration into consumables and sole-source contracting with government payors.
Within the integrated multinational tier, Fresenius Medical Care AG & Co. KGaA and Baxter International Inc. exemplify archetypes combining device manufacturing with captive supply of dialyzer membranes or peritoneal dialysis fluids. Outset Medical, Inc. occupies a position representing interface-focused innovation targeting home care staff training burden reduction. These three entities anchor the competitive spectrum from supply-chain-integrated incumbents to user-experience-specialized challengers.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International Inc. |
| B. Braun SE |
| Outset Medical, Inc. |
| Quanta Dialysis Technologies Ltd. |
| Nikkiso Co., Ltd. |
| Asahi Kasei Medical Co., Ltd. |
| NxStage Systems |
| Diality, Inc. |
| Others |
Value Network & Pricing Analysis
Sorbent cartridge substitution for conventional reverse osmosis water purification is simultaneously shifting manufacturing geography toward Japan and Germany while compressing total cost-of-ownership economics for home dialysis programs. This input transition collapses plumbing infrastructure requirements but concentrates pricing power among membrane chemistry specialists.
Pricing Analysis
Certification level (ISO 13485/FDA Breakthrough/CE-MDR tier) creates the primary spread between premium integrated systems and economy standalone devices. Pricing stratifies across premium, standard, and economy tiers based on automation intensity and consumable bundling depth. Cost compression in the economy tier is intensifying because hospital purchasing cooperatives consolidate procurement under sole-source agreements. Home care providers exhibit highest price sensitivity due to Medicare reimbursement caps, while Veterans Health Administration contracts demonstrate lowest sensitivity through total cost-of-ownership risk absorption.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Yokohama ports constrain just-in-time delivery of polysulfone resins to North American assembly nodes. Manufacturing concentration centers on Germany, Japan, and the United States for high-flux dialyzer membranes, precision pumps, and sorbent chemistry. Raw material dependencies rest on specialized polyethersulfone resins, medical-grade silicones, and ion-exchange sorbents. Single-source vulnerability runs through Baden-Württemberg membrane suppliers serving Fresenius captive production. Distribution runs through direct sales organizations for government payor contracts and regional distributors for rural Medicare Advantage penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital purchasing cooperative consolidation and sole-source government contracting, fragmenting standalone device vendors while favoring integrated suppliers with captive consumable production.
For Market Incumbents: Fortify backward integration into peritoneal dialysis fluid chemistry and dialyzer membrane production to absorb total cost-of-ownership risk demanded by Veterans Health Administration and state Medicaid plans. Expand ISO 13485-certified capacity in Baden-Württemberg and Texas to defend against emerging sorbent-technology challengers. Prioritize HL7 FHIR interoperability investment to lock in Epic and Cerner health system integration. For New Entrants and Emerging Players: FDA Breakthrough Device Designation fast-tracks regulatory entry for wearable hemodialysis systems targeting rural Medicare Advantage counties in Texas, Mississippi, and Alaska. White-space concentration sits with apartment-dwelling elderly patients excluded by home plumbing modification requirements. Pursue cloud-connected vital sign integration as the primary go-to-market wedge against incumbent training-burden disadvantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed device manufacturers lacking captive membrane or fluid supply. Long-term viability favors platforms with sustainable reimbursement economics under expanding CMS bundled payment models. Target acquisition archetype: automated home dialysis specialists with FDA clearance and established biomedical technician training pipelines. Watch Medicare telehealth reimbursement permanence rulemaking as the critical inflection signal for device-plus-service model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses timelines for wearable hemodialysis systems targeting home deployment. |
| Backward Integration into Sorbent Chemistry | In-house dialysate regeneration production reduces dependency on German and Japanese resin suppliers. |
| HL7 FHIR Interoperability Development | Direct Epic and Cerner EHR integration enables real-time ultrafiltration adjustment and remote oversight. |
| Rural Medicare Advantage Partnership | County-level contracts in Texas and Alaska eliminate thrice-weekly travel burdens for dispersed ESRD patients. |
| Biomedical Technician Training Pipeline | Vocational program expansion addresses field service capacity constraints for home water system validation. |
Research Methodology
A standing panel of nephrologists, biomedical engineers, hospital purchasing committee members, and home care agency administrators provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare claims data, and GPO contract databases. Primary interviews with dialysis clinic operators and renal device procurement managers cross-referenced with EU MDR notified body guidance documents and EPA water purification effluent standards. Bottom-up unit economics triangulated against top-down reimbursement flow analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated product type (hemodialysis, peritoneal dialysis, portable systems, home machines), end user (home care providers, hospitals, dialysis clinics), technology automation level, and distribution channel. CAGRs derived from Medicare reimbursement trajectory analysis, FDA approval pipeline assessment, and rural ESRD prevalence demographic modeling. Industry-specific inputs included bundled payment expansion rates and sorbent cartridge adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained CMS home dialysis reimbursement expansion and stable polymer resin supply from Germany and Japan would require recalibration. Forecasts reflect assumptions regarding regulatory clearance timelines, telehealth reimbursement permanence, and patient self-cannulation competency rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Global Gynecology Devices Market