
 Craniomaxillofacial Plate and Installation Tools Market | 2026-2036
Craniomaxillofacial Plate and Installation Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Craniomaxillofacial Plate and Installation Tools Market Analytics
The divergence between premium patient-specific plating and commodity off-the-shelf systems is realigning procurement patterns across hospital systems. Stryker Corporation leverages its broad trauma portfolio to anchor high-volume contracts with integrated delivery networks. Medtronic competes through advanced navigation-integrated installation platforms that command premium positioning in academic medical centers.
Craniomaxillofacial plates and installation tools comprise titanium and stainless steel fixation systems paired with calibrated screwdrivers, drills, and templates designed to stabilize cranial, mandibular, and midface fractures with submillimeter precision. Titanium alloys dominate implant-grade applications due to their strength-to-weight ratio and MRI compatibility, while polymer resorbable alternatives address pediatric craniosynostosis cases requiring gradual osseous integration without secondary removal. Trauma surgery generates the highest procedural volume among application segments, though reconstructive surgery commands superior margin pools due to complexity and customization requirements. Titanium material systems sustain pricing power against stainless steel alternatives as surgeons prioritize biocompatibility and long-term corrosion resistance in load-bearing facial applications.
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose substantial clinical evidence burdens that filter market access for smaller manufacturers. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification across institutional procurement frameworks. Stakeholders must monitor evolving reimbursement pathways for patient-specific implants as health technology assessment bodies recalibrate value thresholds for personalized surgical interventions.
Market Dynamics
The CMF plating market is restructuring around patient-specific implant workflows, where 3D-printed titanium constructs and pre-surgical planning software are compressing operative time while elevating precision requirements for installation tool calibration.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated clearance pathways for titanium implant systems are accelerating product introductions and reducing time-to-market for novel plate geometries.
- Tertiary Hospital Expansion:Trauma surgery departments at major medical centers are expanding CMF plating inventories to capture complex maxillofacial reconstruction referrals.
- Resorbable Polymer Innovation:Biodegradable polymer alternatives address pediatric craniosynostosis cases requiring gradual osseous integration without secondary removal surgery.
Market Restraints
- EU MDR Compliance Burden:The EU Medical Device Regulation imposes substantial clinical evidence requirements that filter market access for smaller manufacturers lacking dedicated regulatory affairs infrastructure.
- Titanium Feedstock Concentration:Medical-grade titanium sponge supply concentrates among a limited set of specialty metallurgical processors, creating input cost volatility exposure.
- Stainless Steel Substitution Ceiling:Surgeons prioritize biocompatibility and corrosion resistance in load-bearing facial applications, limiting pricing pressure from lower-cost stainless steel alternatives.
Strategic Opportunities
- Japan's Aging Trauma Burden:Japan's elevated geriatric population and specialized maxillofacial surgical volumes create sustained demand for premium navigation-integrated installation platforms.
- Navigation-Robotic Convergence:Integration of optical tracking systems with robotic arm guidance is enabling submillimeter screw placement in complex midface reconstructions.
- Direct-to-Hospital Digital Distribution:Cloud-based surgical planning portals are bypassing traditional distributor networks for patient-specific implant orders.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system certification functions as a baseline procurement threshold, requiring 12-18 month implementation cycles for new market entrants.
- Maxillofacial Surgeon Training Bottleneck:Specialized fellowship programs produce limited annual graduates capable of executing complex CMF plating procedures with navigation assistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craniomaxillofacial Plate and Installation Tools Market |
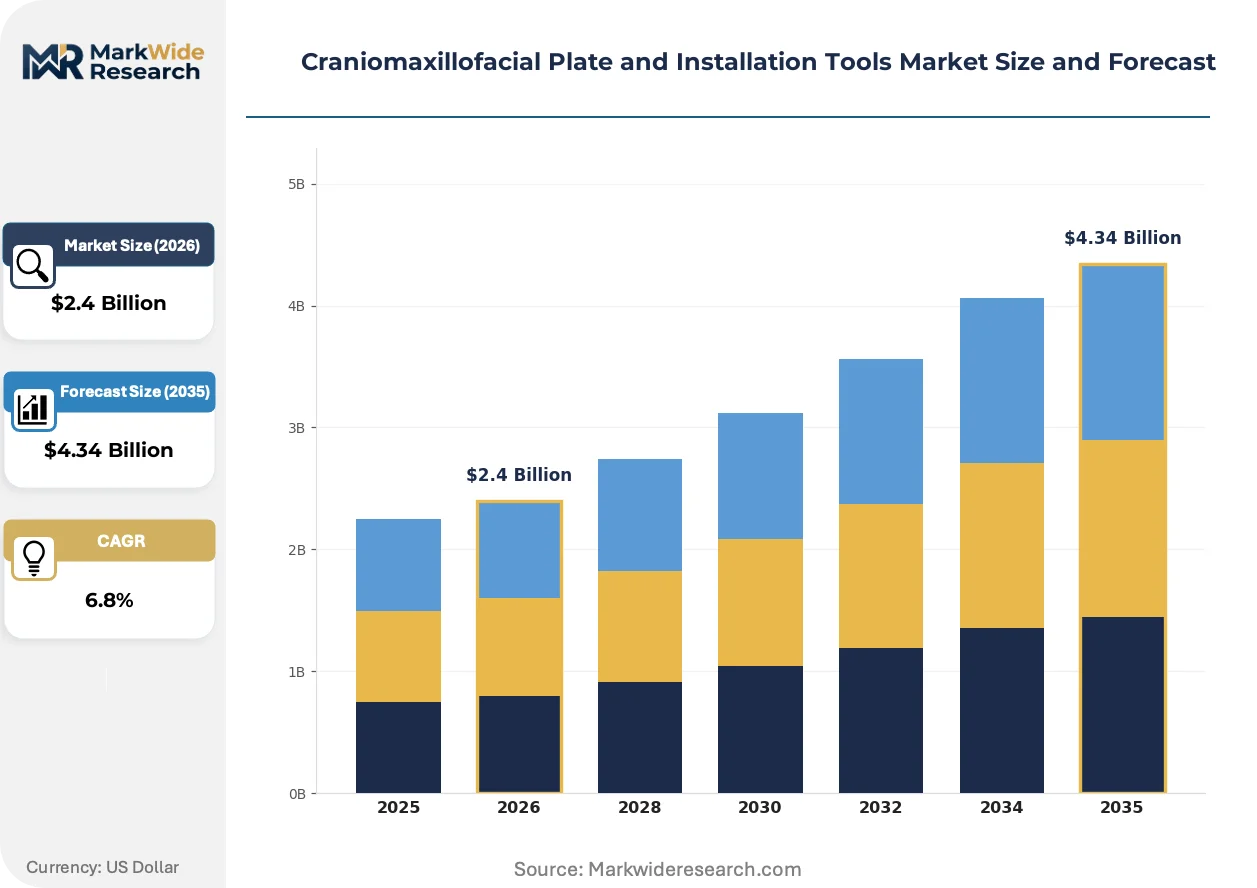
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Instruments, Grafts Application: Orthognathic Surgery, Trauma Surgery, Reconstructive Surgery, Craniosynostosis End User: Hospitals, Ambulatory Surgical Centers, Dental Clinics, Research Institutions Material: Stainless Steel, Titanium, Polymers, Composite Materials |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Medtronic, Johnson & Johnson, B. Braun Aesculap, KLS Martin Group, Integra LifeSciences, Medartis AG, OsteoMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craniomaxillofacial Plate and Installation Tools Market Evolving Landscape
Digital surgical planning and additive manufacturing are converging to displace conventional templating methods, while regulatory frameworks recalibrate evidence requirements for personalized implant workflows.
Patient-specific titanium plates fabricated through selective laser melting are integrating with pre-operative virtual surgical planning software to eliminate intraoperative bending and reduce operative time. Academic medical centers in Germany and the United States are adopting these workflows for complex mandibular reconstruction cases. The technology is integrating surgical simulation with just-in-time manufacturing, compressing supply chain lead times from weeks to days while elevating precision requirements for installation tool calibration.
The EU Medical Device Regulation's enhanced clinical evidence requirements are extending approval timelines for novel plate geometries and resorbable material systems. Manufacturers must now submit prospective clinical data for patient-specific implants previously cleared through predicate equivalence. Small and mid-sized device firms are responding by consolidating regulatory affairs functions and prioritizing CE-marked products with the broadest indication scopes.
Integrated delivery networks are consolidating CMF plating procurement under centralized orthopedic implant contracts, displacing standalone maxillofacial purchasing committees. Hospital systems in the United States are unbundling installation tool sets from plate-screw kits to optimize capital equipment utilization across service lines. Germany's university hospitals retain specialized procurement autonomy, preserving premium positioning for navigation-integrated platforms in academic settings.
Craniomaxillofacial Plate and Installation Tools Market Segmentation
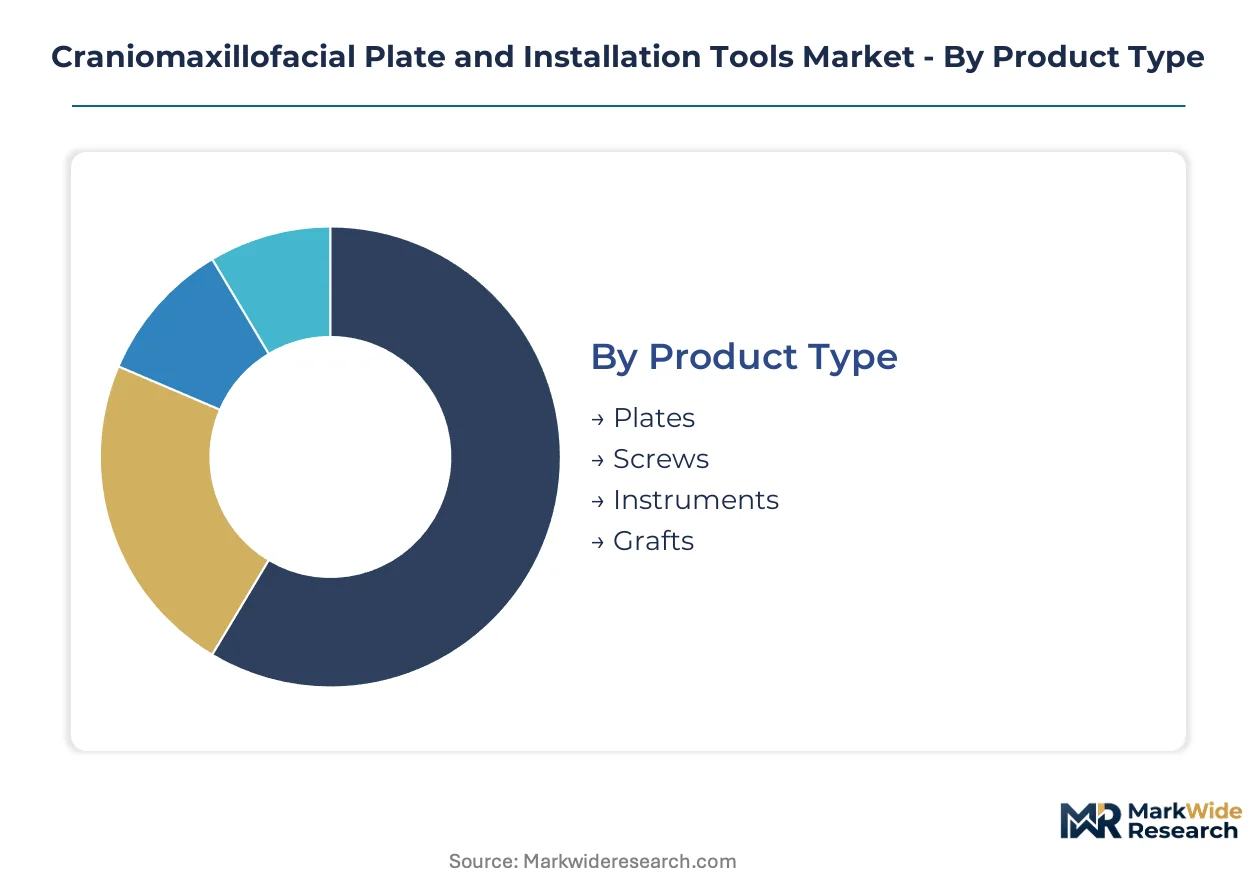
CMF plating procurement splits sharply between high-volume trauma hardware and premium patient-specific reconstructive systems. Segmentation discipline reveals where titanium alloys command pricing power against stainless steel substitutes and which installation tool categories absorb capital investment priority.
Product Type:
Volume concentrates in screw and plate hardware, while margin pools concentrate in precision instruments and patient-matched graft systems.
- Plates:Titanium alloy constructs dominate load-bearing mandibular and midface applications where MRI compatibility and corrosion resistance outweigh cost considerations. Demand clusters at tertiary trauma centers in the United States and Germany executing complex maxillofacial reconstructions with navigation assistance.
- Screws:Self-tapping titanium screws in 1.0mm to 2.4mm diameters constitute the highest-volume hardware category, with standardized SKUs anchoring hospital procurement contracts. Trauma surgery departments in Japan drive premium screw demand for geriatric fracture fixation where bone quality degradation demands enhanced purchase.
- Instruments:Calibrated drills, screwdrivers, and torque-limiting drivers designed for submillimeter precision in dense cortical bone.
- Grafts:Patient-specific titanium mesh and resorbable polymer constructs for cranial defect reconstruction.
Today's leader: Plates. Tomorrow's challenger: Grafts.
Application:
Trauma generates procedural volume; reconstructive surgery captures margin premium through complexity and customization.
- Trauma Surgery:Mandibular, zygomatic, and orbital fracture fixation constitutes the dominant procedural category, with standardized plating systems deployed in emergency settings. United States Level I trauma centers and Japan's specialized maxillofacial units sustain elevated hardware consumption.
- Reconstructive Surgery:Post-oncologic mandibular reconstruction and congenital deformity correction demand patient-specific titanium plates fabricated through selective laser melting. German university hospitals pioneer virtual surgical planning integration with just-in-time manufacturing workflows.
- Orthognathic Surgery:Corrective jaw procedures requiring rigid fixation of repositioned maxillary and mandibular segments.
- Craniosynostosis:Pediatric cranial vault remodeling with resorbable polymer alternatives eliminating secondary removal surgery.
Trauma commands volume. Reconstructive surgery climbs fastest on precision premiums.
End User:
Procurement authority is consolidating under integrated delivery network orthopedic contracts, though academic medical centers retain specialized purchasing autonomy.
- Hospitals:Tertiary medical centers with dedicated CMF trauma services anchor titanium plating demand, particularly in the United States and Germany where maxillofacial fellowship-trained surgeons concentrate. FDA 510(k) cleared systems dominate formulary inclusion.
- Ambulatory Surgical Centers:Outpatient orthognathic and limited trauma procedures drive demand for streamlined instrument sets and disposable drill systems.
- Dental Clinics:Oral and maxillofacial surgery practices performing implant-related bone grafting and alveolar reconstruction.
- Research Institutions:Academic centers validating novel resorbable polymers and navigation-robotic installation platforms.
Hospitals control spend scale. Ambulatory centers gain share on cost efficiency.
Material:
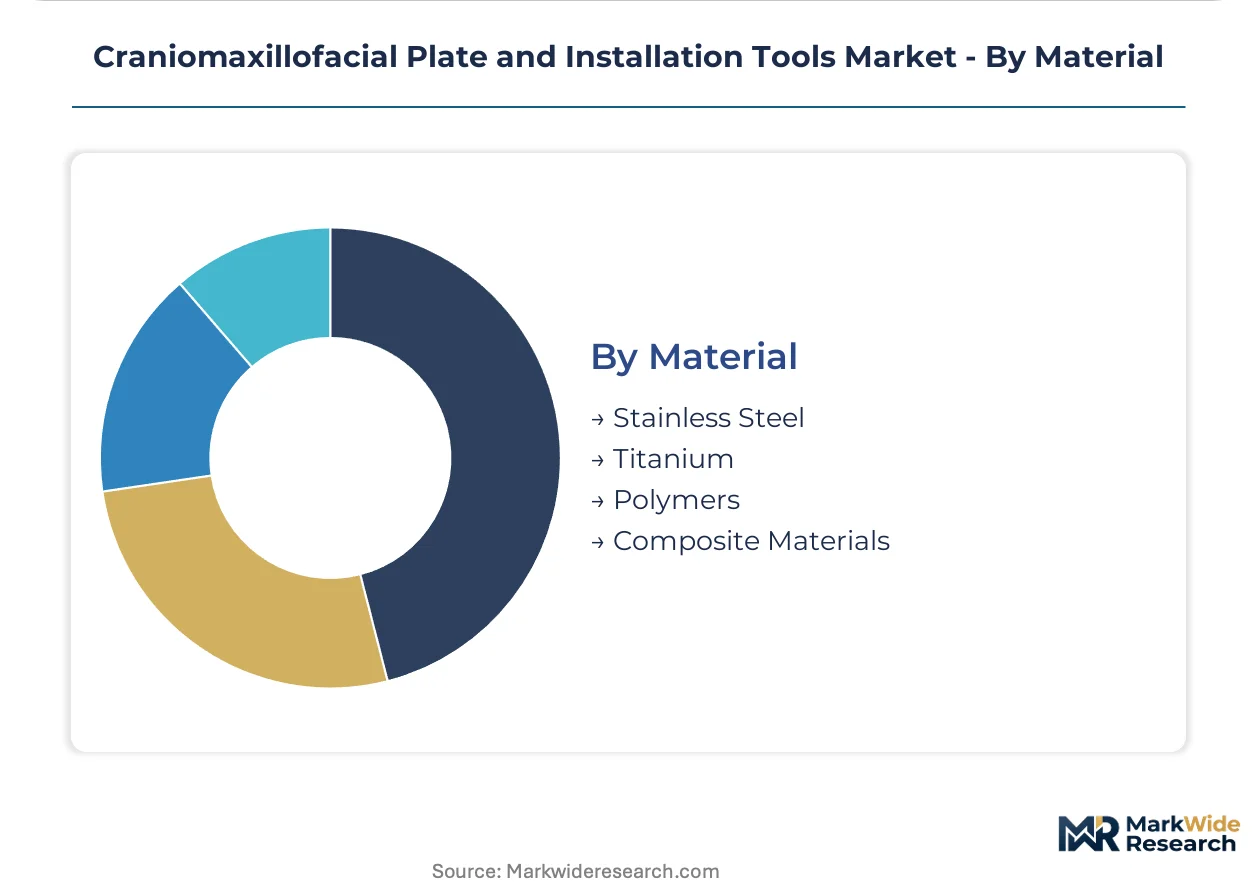
Titanium sustains pricing power through biocompatibility and MRI compatibility; stainless steel faces substitution ceiling in load-bearing facial applications.
- Titanium:Ti-6Al-4V ELI alloy dominates implant-grade applications with strength-to-weight ratios enabling thin-profile plate designs. Japanese and German surgeons prioritize titanium for long-term corrosion resistance in permanent facial fixation.
- Polymers:Polylactic acid and polyglycolic acid resorbable systems address pediatric craniosynostosis where gradual osseous integration eliminates secondary hardware removal. EU MDR clinical evidence requirements extend approval timelines for novel polymer formulations.
- Stainless Steel:316L grade alternatives retain niche positioning in cost-sensitive trauma applications and temporary fixation scenarios.
- Composite Materials:Carbon fiber-reinforced polymers and bioactive glass composites under evaluation for load-sharing applications.
Titanium owns premium positioning. Polymers expand fastest on pediatric and resorption advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maxillofacial fellowship-trained surgeons concentrate in tertiary medical centers across the United States, Germany, and Japan, anchoring procedural volumes and premium hardware procurement. Trauma surgery departments at these institutions drive titanium plating demand through complex cranial and mandibular reconstruction referrals. Regulatory pathways in each geography shape market access timelines and product introduction cadences.
United States
Level I trauma centers in Baltimore, Boston, and Houston sustain elevated CMF hardware consumption through specialized maxillofacial units. FDA 510(k) clearance pathways for titanium implant systems accelerate product introductions compared to European timelines. The Mayo Clinic and Massachusetts General Hospital anchor adoption of navigation-integrated installation platforms for complex midface reconstructions.
Germany
University hospitals in Munich, Heidelberg, and Berlin pioneer virtual surgical planning integration with just-in-time manufacturing of patient-specific titanium plates. EU MDR clinical evidence requirements extend approval timelines for novel plate geometries and resorbable polymers. Baden-Württemberg's medical technology cluster concentrates precision instrument manufacturing for submillimeter surgical applications.
Japan
Geriatric fracture fixation demand concentrates at specialized maxillofacial units in Tokyo, Osaka, and Nagoya where bone quality degradation drives premium screw procurement. PMDA regulatory frameworks prioritize long-term biocompatibility data for permanent facial fixation applications. Kanto region hospitals lead adoption of torque-limiting driver systems for dense cortical bone applications.
Switzerland
Swissmedic certification requirements for implant-grade titanium alloys sustain quality thresholds that filter supplier qualification. Zurich and Geneva university hospitals retain specialized procurement autonomy for navigation-integrated platforms. The Basel medical technology corridor concentrates additive manufacturing capabilities for patient-specific mesh constructs.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex CMF reconstructions at designated tertiary centers in London, Birmingham, and Manchester. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel submission requirements. The Cambridge-Oxford-London triangle anchors academic validation of resorbable polymer alternatives for pediatric craniosynostosis.
Craniomaxillofacial Plate and Installation Tools Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the CMF plating value chain, with integrated medical device conglomerates holding trauma portfolio advantages against specialized maxillofacial boutiques. The market structure tiers around three archetypes: diversified orthopedic giants anchoring high-volume hospital contracts, precision instrument specialists commanding premium positioning in academic settings, and emerging additive manufacturing boutiques disrupting patient-specific workflows. Consolidation pressures favor acquisition of regulatory affairs capabilities and navigation software assets over standalone hardware plays.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet represent capital-scale anchors whose broad trauma portfolios secure integrated delivery network contracts. Medtronic occupies a position exemplifying the navigation-integrated archetype, with its emphasis on optical tracking and robotic guidance systems commanding premium placement in university hospitals. KLS Martin Group and Medartis AG sit within the specialized maxillofacial tier, where focused product ranges and regional regulatory depth sustain niche positioning against broader competitors.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Medtronic |
| Johnson & Johnson |
| B. Braun Aesculap |
| KLS Martin Group |
| Integra LifeSciences |
| Medartis AG |
| OsteoMed |
| Others |
Value Network & Pricing Analysis
Selective laser melting of patient-specific titanium plates compresses manufacturing lead times from weeks to days while concentrating production capability among additive manufacturing boutiques and university hospital partnerships in Germany and Switzerland. This production-method transition simultaneously elevates precision requirements for installation tool calibration and fragments pricing power away from traditional forging-based suppliers toward digital workflow integrators.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from navigation-integrated platform subscriptions. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and surgeon training certification. Pricing pressure stems from integrated delivery networks unbundling installation tool sets from plate-screw kits to optimize capital utilization. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with specialized procurement autonomy absorb premium positioning for patient-matched constructs.
Supply Chain Analysis
Warehouse-distribution layer configurations favor regional hub-and-spoke patterns anchored by tertiary trauma centers in the United States, Germany, and Japan. Medical-grade titanium sponge supply concentrates among specialty metallurgical processors in the United States, Russia, and Japan. Raw material dependencies rest on ELI-grade titanium alloys, resorbable polymer feedstocks, and precision-machined instrument components. Single-source vulnerability in titanium sponge creates tariff exposure risk. Distribution runs through GPO-negotiated contracts and direct-to-hospital digital portals for patient-specific orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Craniomaxillofacial Plate and Installation Tools Market functions as a stable compounder, with trauma surgery departments at tertiary hospitals generating recurring hardware demand through complex maxillofacial reconstruction referrals.
For Market Incumbents: Lock in high-volume trauma contracts with integrated delivery networks before additive manufacturing boutiques capture patient-specific reconstructive workflows. Deepen backward integration into medical-grade titanium sponge supply to offset feedstock concentration risk. Prioritize ISO 13485 certification maintenance as procurement threshold enforcement intensifies. For New Entrants and Emerging Players: Capture white-space opportunity in resorbable polymer craniosynostosis applications where EU MDR clinical evidence requirements filter established competitors. Target Japan's geriatric fracture fixation segment with torque-limiting driver systems optimized for dense cortical bone. Deploy cloud-based surgical planning portals to bypass traditional distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regulatory affairs boutiques with CE-marked product portfolios and narrow indication scopes. Five-to-ten year viability hinges on navigation-software asset accumulation over standalone hardware positions. Watch FDA 510(k) clearance velocity for patient-specific implants as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for novel titanium plate geometries against EU MDR timelines. |
| CE Marking Pathway | Enables European commercialization through consolidated regulatory affairs infrastructure. |
| Hospital System Partnership | Secures formulary inclusion at Level I trauma centers with dedicated CMF services. |
| Software Companion Development | Integrates pre-surgical planning with just-in-time manufacturing workflows. |
| Reimbursement Strategy | Aligns patient-specific implant pricing with health technology assessment value thresholds. |
Research Methodology
Direct dialogue with maxillofacial surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation reconciled procedural volume estimates with titanium alloy consumption patterns.
Bottom-up modeling aggregated individual product category trajectories across plates, screws, instruments, and grafts by material type and application. Segmentation dimensions included trauma versus reconstructive surgery indication, titanium versus resorbable polymer composition, and tertiary hospital versus ambulatory surgical center end-use. CAGRs were derived from surgical volume projections and hardware intensity per procedure assumptions. Navigation-integrated platform adoption curves and additive manufacturing penetration rates informed technology transition inputs.
Underlying measurement precision varies by segment; trauma surgery hardware carries tighter precision than emerging resorbable polymer categories. Forecasts reflect documented assumptions regarding regulatory clearance timelines, surgeon training pipeline capacity, and titanium feedstock price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Orthodontic Headgear Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Infertility Devices Market
Medical Devices
South Korea ECG Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Carotid Stents Market
Medical Devices
Ventilation Devices Market
Medical Devices
Vitrectomy Devices Market